
 Japan Organic Cosmetics Market | 2026-2036
Japan Organic Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Organic Cosmetics Market Intelligence
Japan is fragmenting its organic cosmetics production base as domestic brands expand laboratory capacity in prefectures like Shizuoka and Tochigi. Shiseido leverages its century-old research infrastructure to sustain botanical extraction programs at scale. Kao Corporation anchors its position through integrated supply chains spanning raw material cultivation to finished goods. KOSÉ Corporation differentiates via fermentation-derived active ingredients targeting sensitive-skin segments.
Japan organic cosmetics comprise formulations containing certified organic agricultural ingredients processed without synthetic pesticides, petroleum-derived chemicals, or genetically modified organisms, typically requiring minimum organic content thresholds validated by third-party certification bodies. These products serve commercial purposes ranging from daily consumer skincare regimens to professional salon treatments emphasizing dermal compatibility and environmental traceability. Skincare dominates value generation due to Japan's aging demographic prioritizing preventive dermal health, while haircare segments gain traction through scalp-focused botanical therapies. Mineral pigments within makeup applications occupy niche premium positioning as consumers scrutinize ingredient transparency across e-commerce platforms.
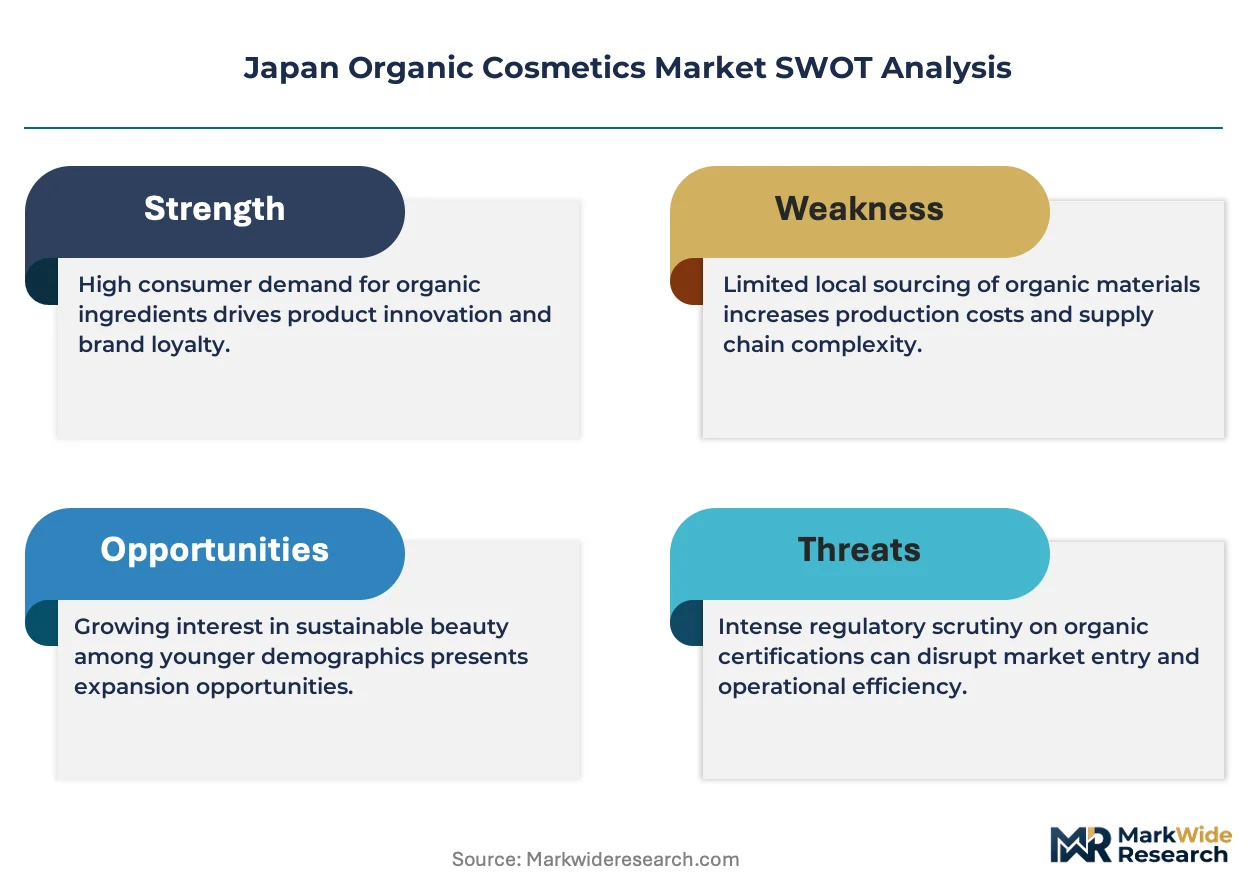
METI guidelines on sustainable chemical manufacturing, JIS standards for organic product labeling, and the Ministry of Health, Labour and Welfare's quasi-drug classification framework collectively shape formulation requirements and market access protocols for domestic and imported brands. Compliance with these overlapping standards elevates R&D expenditure but simultaneously filters out uncertified competitors, tightening legitimate supply channels. Stakeholders must monitor evolving prefectural sustainability mandates and certification harmonization pressures to anticipate which distribution formats and ingredient sourcing models will secure preferential retail placement.
Market Dynamics
Plant-derived fermentation technology is compressing formulation cycles across Japan's organic cosmetics sector, enabling domestic laboratories to bypass lengthy petrochemical synthesis routes while satisfying METI's escalating purity thresholds for sensitive-skin applications.
Growth Catalysts
- Prefectural sustainability mandates:Shizuoka and Tochigi prefectures now subsidize organic raw material cultivation, drawing laboratory capacity away from congested Tokyo-Osaka corridors and reducing land-cost overheads for extraction facilities.
- Aging-aware demographic pull:Consumers over fifty in metropolitan corridors prioritize preventive dermal health regimens, concentrating demand in premium skincare segments that command higher formulation investment.
- Quasi-drug classification pathway:The Ministry of Health, Labour and Welfare's framework rewards compliant organic formulations with enhanced retail placement in pharmacy channels, accelerating brand legitimacy.
Market Restraints
- Organic agricultural input volatility:Domestic rice bran and green tea extract supplies fluctuate with climate patterns in Kyushu and Shikoku, forcing brands to maintain costly buffer inventories.
- Third-party certification bottlenecks:JIS-compliant validation bodies concentrate in Tokyo, creating six-to-nine month approval queues that delay product launches regardless of formulation readiness.
- Synthetic preservative substitution limits:Natural antimicrobial alternatives derived from wasabi or shiso extracts demonstrate shorter shelf stability than petrochemical benchmarks, constraining distribution radius.
Strategic Opportunities
- Fermentation technology convergence:Integration of koji-derived enzyme processing with precision fermentation platforms enables novel active ingredient classes targeting microbiome-balancing applications.
- Professional salon channel expansion:Untapped scalp-focused botanical therapy demand in Osaka's aesthetic clinic clusters offers premium pricing power absent from mass retail.
- Prefectural circular economy incentives:METI's regional industrial symbiosis programs subsidize waste-stream upcycling from sake brewing into cosmetic-grade rice ferment filtrates.
Industry Challenges
- Cross-functional formulation talent scarcity:Chemists with simultaneous expertise in organic certification compliance and fermentation process engineering command premium compensation that strains mid-tier brand R&D budgets.
- Legacy supply chain reconfiguration friction:Brands transitioning from petrochemical to botanical feedstocks face qualification delays as existing manufacturing equipment requires retrofitting for temperature-sensitive organic processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Organic Cosmetics Market |
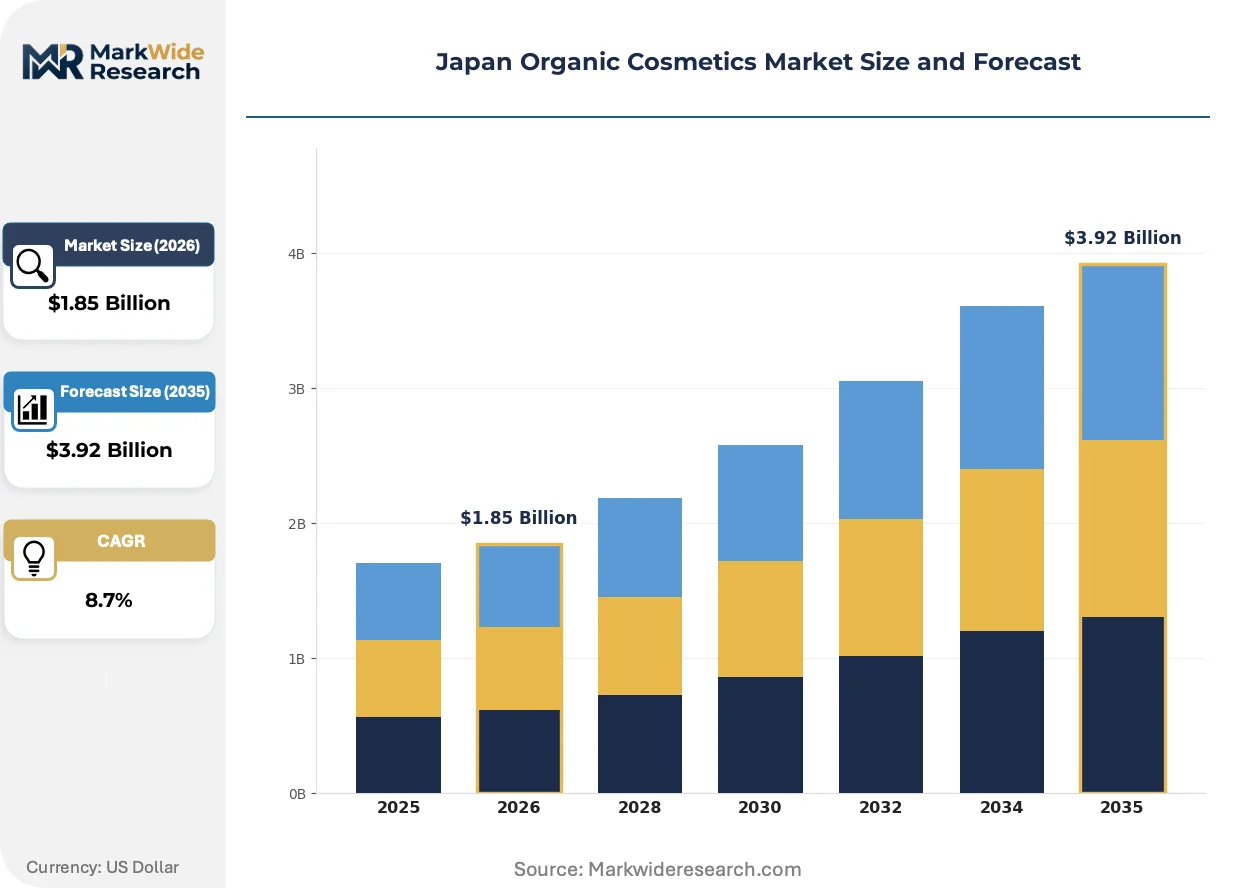
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Ingredient Type: Botanical Extracts, Essential Oils, Natural Butters, Mineral Pigments Customer Type: Individual Consumers, Salons, Retailers, E-Commerce Platforms Packaging Type: Biodegradable, Recyclable, Glass, Aluminum |
| Companies Covered | SK-II, Bloom Co., Ltd., Shiseido, Huit Laboratories, Cosme Create Products Co., Ltd., Kao Corporation, Asanuma, Milliona Cosmetics, KOSÉ Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Organic Cosmetics Market Strategic Shifts & Innovations
Fermentation-derived actives and digital traceability platforms are compressing the distance between agricultural source and finished formulation, while regulatory pressure from METI accelerates the obsolescence of synthetic-heavy legacy portfolios.
Precision fermentation platforms utilizing koji, yeast, and lactic acid bacteria strains are virtualizing traditional botanical extraction by generating bio-identical compounds without seasonal agricultural dependency. Premium sensitive-skin specialists in Tokyo's Ginza corridor have adopted these platforms at pilot scale, compressing ingredient sourcing timelines from eighteen-month harvest cycles to eight-week bioreactor batches. This virtualization is collapsing the traditional premium attached to rare botanical provenance, forcing brands to differentiate through fermentation process IP rather than origin storytelling.
METI's sustainable chemical manufacturing guidelines now mandate lifecycle assessment disclosure for organic claims exceeding seventy percent content thresholds, effective across all domestic production facilities. Formulators must document carbon intensity from agricultural cultivation through packaging, elevating compliance costs but simultaneously filtering uncertified imports from competing for pharmacy shelf space. Small-to-mid domestic brands with captive cultivation relationships in Shizuoka and Tochigi prefectures capture disproportionate advantage under this framework.
Ingredient transparency scrutiny now drives purchasing decisions among urban millennial consumers, compressing the traditional information asymmetry between manufacturer and end-user. E-commerce platforms with blockchain-verified supply chain visualization are displacing conventional department store counters as the primary discovery channel for certified organic skincare. This behavioral rotation concentrates most intensely in Tokyo and Osaka, where digital-native consumers prioritize verification over tactile sampling.
Japan Organic Cosmetics Market Segmentation
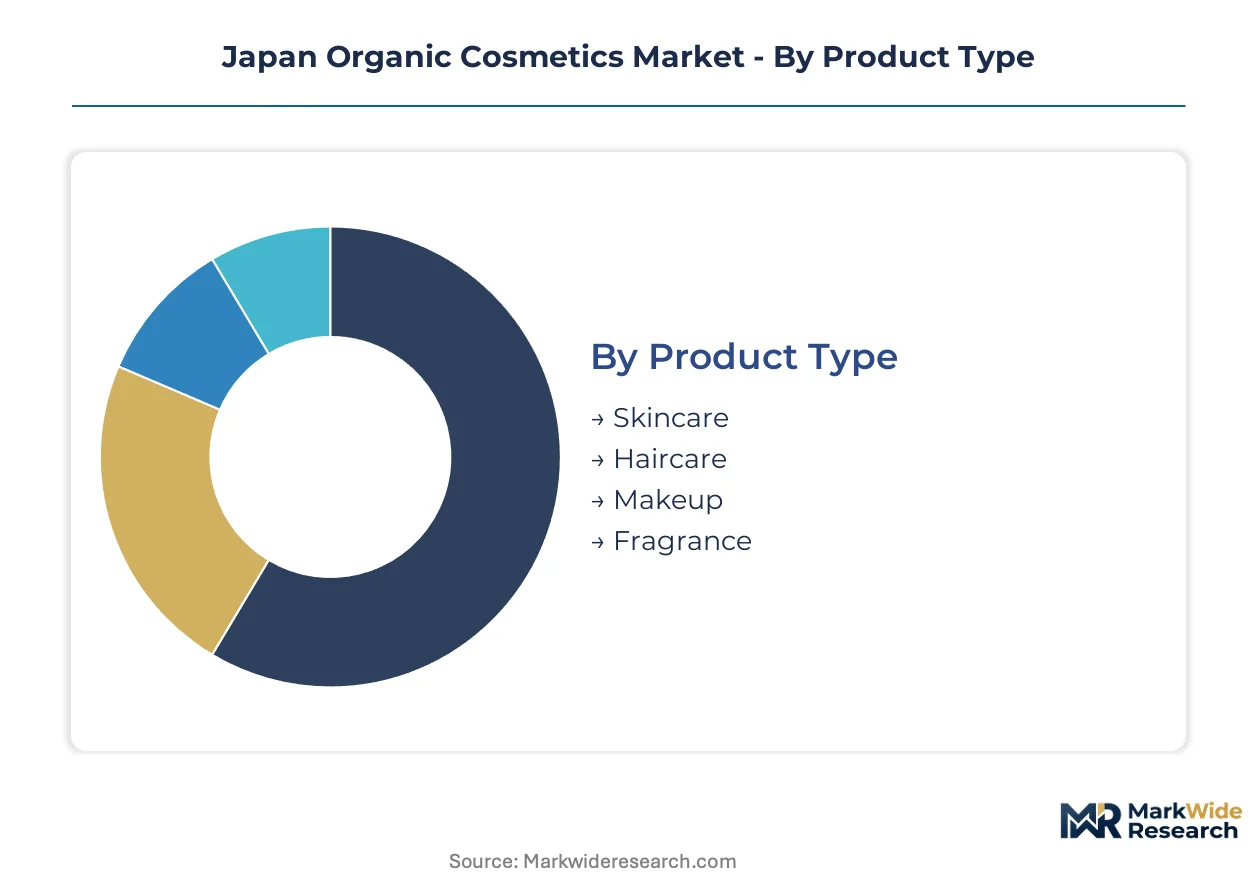
Segmentation in Japan's organic cosmetics market reveals how METI's sustainability mandates and aging-aware consumer preferences reshape commercial priorities across product tiers and distribution channels. Understanding these divides exposes where formulation investment concentrates and which customer interfaces command premium positioning.
Product Type:
Cost tier stratification across product categories concentrates R&D expenditure where preventive dermal health commands sustained consumer willingness to pay premium prices.
- Skincare:Formulations containing certified organic agricultural ingredients with minimum content thresholds validated by third-party certification bodies serve daily consumer regimens and professional salon treatments. Demand concentrates among aging-aware demographics over fifty in Tokyo and Osaka metropolitan corridors who prioritize preventive dermal health, driving premium pricing power in anti-aging and sensitive-skin segments.
- Haircare:Botanical therapies targeting scalp health utilize plant-derived fermentation technology to bypass petrochemical synthesis routes while satisfying METI purity thresholds. Osaka's aesthetic clinic clusters generate untapped demand for professional-grade scalp treatments absent from mass retail channels.
- Makeup:Mineral pigments occupy niche premium positioning as urban millennial consumers scrutinize ingredient transparency across e-commerce platforms.
- Fragrance:Natural essential oil compositions face shorter shelf stability constraints than synthetic benchmarks, limiting distribution radius for wasabi and shiso-derived antimicrobial alternatives.
Skincare commands the established base. The steepest expansion runs through haircare.
Ingredient Type:
Application-specific functional requirements determine which raw material classes absorb disproportionate cultivation subsidies from Shizuoka and Tochigi prefectures.
- Botanical Extracts:Rice bran and green tea extracts sourced from Kyushu and Shikoku face climate-driven supply volatility, forcing brands to maintain costly buffer inventories. Domestic laboratory capacity expansion in prefectural corridors reduces land-cost overheads for extraction facilities while meeting METI's escalating purity thresholds.
- Essential Oils:Wasabi and shiso extracts demonstrate natural antimicrobial properties but shorter shelf stability than petrochemical preservatives, constraining formulation flexibility for mass-market distribution.
- Natural Butters:Shea and cocoa derivatives serve emollient functions in sensitive-skin formulations targeting microbiome-balancing applications through koji-derived enzyme processing.
- Mineral Pigments:Iron oxides and mica alternatives occupy premium makeup positioning where blockchain-verified supply chain visualization displaces conventional department store discovery channels.
Botanical extracts anchor current revenue. Essential oils are climbing the fastest as fermentation technology compresses extraction timelines.
Customer Type:
Volume concentration varies sharply across customer interfaces, with digital-native discovery channels displacing traditional tactile sampling in metropolitan corridors.
- Individual Consumers:Urban millennial consumers in Tokyo and Osaka drive adoption through preference for clean-label skincare routines, prioritizing verification over physical product interaction. E-commerce platforms with blockchain-verified supply chain visualization concentrate discovery intensity in these metropolitan corridors.
- E-Commerce Platforms:Digital marketplaces with ingredient transparency scrutiny now drive purchasing decisions, compressing information asymmetry between manufacturer and end-user. Blockchain verification capabilities filter uncertified imports from competing for preferred placement.
- Salons:Professional aesthetic clinics in Osaka's clusters offer premium pricing power for scalp-focused botanical therapies absent from mass retail.
- Retailers:Pharmacy channels reward compliant organic formulations with enhanced placement under the Ministry of Health, Labour and Welfare's quasi-drug classification framework.
Individual consumers command the established base. E-commerce platforms are expanding most quickly as digital-native verification preferences reshape discovery patterns.
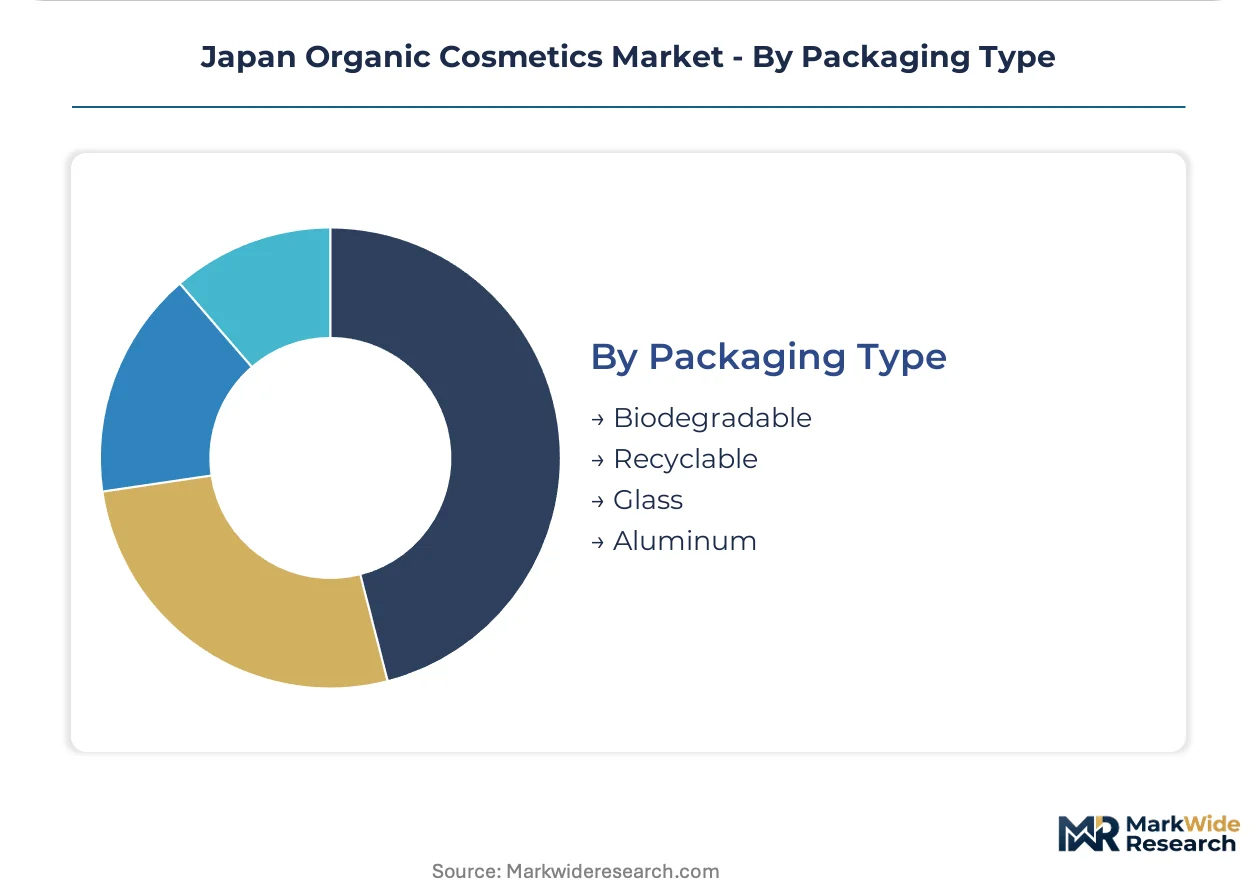
Packaging Type:
Customer type sensitivity to environmental traceability elevates packaging decisions from cost center to competitive differentiation lever in premium segments.
- Biodegradable:Materials meeting METI's lifecycle assessment disclosure mandates for organic claims exceeding seventy percent content thresholds command preferential retail placement. Formulators must document carbon intensity from agricultural cultivation through packaging, elevating compliance costs but filtering uncertified competitors.
- Recyclable:Post-consumer recycled content aligns with prefectural circular economy incentives subsidizing waste-stream upcycling from sake brewing into cosmetic-grade inputs.
- Glass:Inert containment for fermentation-derived actives preserves shelf stability of temperature-sensitive organic formulations requiring retrofit manufacturing equipment.
- Aluminum:Lightweight barrier properties suit mineral pigment makeup applications where premium positioning justifies material cost premiums.
Biodegradable packaging commands the established base. Recyclable formats are gaining share fastest under prefectural circular economy subsidy programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's sustainable manufacturing guidelines anchor formulation standards across Japan's prefectural corridors, concentrating laboratory capacity and retail legitimacy in metropolitan clusters while prefectural subsidies redistribute extraction infrastructure toward lower-cost hinterlands.
Kanto/Tokyo
Urban millennial consumers in Tokyo's 23 wards drive clean-label skincare adoption through e-commerce platforms with blockchain verification capabilities. METI's lifecycle assessment disclosure mandates for organic claims exceeding seventy percent content thresholds filter uncertified competitors from pharmacy channel placement. Ginza corridor laboratories pilot precision fermentation platforms utilizing koji and yeast strains to compress ingredient sourcing timelines from harvest cycles to bioreactor batches.
Kansai/Osaka
Consumers over fifty in Osaka's metropolitan corridor prioritize preventive dermal health regimens, concentrating demand in premium anti-aging and sensitive-skin segments. The Ministry of Health, Labour and Welfare's quasi-drug classification framework rewards compliant organic formulations with enhanced retail placement in pharmacy channels. Aesthetic clinic clusters in Osaka generate untapped demand for professional-grade scalp-focused botanical therapies absent from mass retail.
Chubu/Nagoya
Mid-tier domestic brands with captive cultivation relationships capture disproportionate advantage under METI's escalating purity thresholds for sensitive-skin applications. Prefectural sustainability mandates subsidize organic raw material cultivation, drawing laboratory capacity away from congested Tokyo-Osaka corridors. Shizuoka prefecture's industrial symbiosis programs subsidize waste-stream upcycling from sake brewing into cosmetic-grade rice ferment filtrates.
Tohoku
Climate-driven supply volatility in Kyushu and Shikoku forces brands to maintain costly buffer inventories of rice bran and green tea extracts. Tochigi prefecture's subsidized organic raw material cultivation programs reduce land-cost overheads for extraction facilities while meeting METI purity benchmarks. Regional laboratory capacity expansion fragments production bases away from metropolitan congestion.
Kyushu
Agricultural cultivation of rice bran and green tea extracts faces climate pattern fluctuations that destabilize input supply security for domestic formulation networks. JIS-compliant validation bodies concentrate in Tokyo, creating six-to-nine month approval queues that delay product launches regardless of formulation readiness. Local cultivation cooperatives supply raw materials to brands with backward integration into prefectural sourcing corridors.
Japan Organic Cosmetics Market Key Industry Players
Capability concentration sits with heritage research infrastructure holders; scale advantage sits with integrated supply chain operators. The market structures around three tiers: century-old research laboratories sustaining botanical extraction programs, vertically integrated conglomerates spanning cultivation to finished goods, and fermentation technology specialists targeting microbiome-balancing applications. Dominant competitive moves include laboratory capacity expansion in subsidized prefectural corridors and strategic positioning for quasi-drug classification pathways that secure pharmacy channel legitimacy.
Within the heritage research tier, Shiseido leverages century-old infrastructure to sustain botanical extraction programs at scale. Kao Corporation anchors the integrated supply chain archetype through captive relationships spanning raw material cultivation to finished goods distribution. KOSÉ Corporation exemplifies the fermentation technology specialist vector, differentiating via koji-derived active ingredient development targeting sensitive-skin segments.
| Leading Market Players |
|---|
| SK-II |
| Bloom Co., Ltd. |
| Shiseido |
| Huit Laboratories |
| Cosme Create Products Co., Ltd. |
| Kao Corporation |
| Asanuma |
| Milliona Cosmetics |
| KOSÉ Corporation |
| Others |
Cost & Logistics Intelligence
The Tokyo-Osaka freight corridor compresses logistics costs for domestic brands while amplifying price spreads between metropolitan premium tiers and prefectural value tiers. METI's lifecycle assessment mandates force certification-grade pricing differentiation that rewards Shizuoka and Tochigi cultivation networks with margin capture unavailable to import-reliant competitors.
Pricing Analysis
Metropolitan price spreads widen between Ginza corridor premium positioning and mass-market pharmacy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects JIS certification grade and fermentation-derived active concentration. Cost compression in mid-tier segments intensifies because domestic laboratory capacity expansion fragments production bases. Individual consumers over fifty in Osaka show least price sensitivity for preventive dermal health regimens, while urban millennials in Tokyo exhibit highest elasticity across e-commerce discovery channels.
Supply Chain Analysis
Export-control regimes on precision fermentation equipment limit bioreactor technology flows into domestic laboratory networks. Supply concentrates in Japan, South Korea, and Germany for koji-derived enzyme processing platforms. Raw material dependencies center on Kyushu rice bran, Shikoku green tea extracts, and Tochigi prefectural cultivation cooperatives. Single-source vulnerability runs through climate-driven agricultural input volatility forcing costly buffer inventories. Distribution runs through pharmacy channels rewarding quasi-drug classification compliance with enhanced retail placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-verified supply chain visualization is shifting discovery economics toward platform-mediated transparency, collapsing traditional information asymmetry between Shiseido-scale incumbents and emerging fermentation specialists.
For Market Incumbents: Build certification moats through accelerated JIS-compliant validation body relationships to bypass six-to-nine month approval queues threatening product launch timelines. Deepen captive cultivation relationships in Shizuoka and Tochigi prefectures to capture METI subsidy advantages filtering uncertified imports from pharmacy channel placement. Threat of precision fermentation platform commoditization demands proprietary koji-derived enzyme IP development. For New Entrants and Emerging Players: Build out professional salon channel presence in Osaka's aesthetic clinic clusters where scalp-focused botanical therapies command premium pricing absent from mass retail saturation. Target underpenetrated haircare segments with fermentation-derived scalp health formulations. Go-to-market angle leverages prefectural circular economy subsidies for sake brewing waste-stream upcycling into cosmetic-grade rice ferment filtrates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation infrastructure holders over legacy botanical extraction networks as virtualization compresses eighteen-month harvest cycles to eight-week bioreactor batches. Long-term viability hinges on backward integration into prefectural cultivation corridors securing METI-compliant supply chain documentation. Acquisition target archetype: mid-tier domestic brands with captive Shizuoka relationships and quasi-drug classification pathway progress. Signal to watch: JIS validation body capacity expansion indicating regulatory bottleneck easing.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Technology Convergence | Koji-derived enzyme processing with precision platforms enables novel microbiome-balancing active classes. |
| Prefectural Laboratory Expansion | Shizuoka and Tochigi capacity draws production from congested Tokyo-Osaka corridors reducing land-cost overheads. |
| Quasi-Drug Classification Pursuit | Ministry of Health, Labour and Welfare framework rewards compliant formulations with pharmacy channel legitimacy. |
| Blockchain Traceability Integration | E-commerce platforms with verified supply chain visualization displace department store discovery for millennial consumers. |
| Circular Economy Sourcing | METI industrial symbiosis programs subsidize sake brewing waste-stream upcycling into cosmetic-grade inputs. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across formulation chemists, pharmacy channel buyers, prefectural cultivation cooperative managers, and METI regulatory affairs specialists. Secondary validation drew from JIS standard documentation, Ministry of Health, Labour and Welfare quasi-drug classification filings, prefectural sustainability mandate records, and customs trade data on organic agricultural input flows. Bottom-up brand-level revenue triangulation against top-down category spend estimates anchored market sizing.
Calibration against historical JIS certification issuance rates and fermentation technology adoption curves shaped projection parameters across the analysis window. Segmentation dimensions modeled include product type tier, ingredient source class, customer interface channel, and prefectural production cluster. CAGRs derived from slope analysis of certified organic content threshold compliance trajectories and precision fermentation platform deployment timelines. Forecast inputs incorporated METI lifecycle assessment mandate phase-in schedules and climate volatility patterns affecting Kyushu and Shikoku agricultural yields.
Sensitivities concentrate around JIS validation body capacity expansion, precision fermentation equipment import licensing shifts, and prefectural subsidy program continuity. Forecasts reflect assumptions on certification harmonization pressures and blockchain traceability platform adoption curves. Material shifts in METI purity threshold escalations or climate-driven agricultural input disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Eye Cream Market
Cosmetics & Skincare
Halal Cosmetics Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market
Cosmetics & Skincare
Massaging Cosmetic Applicators Market
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
Anti-Fatigue Cosmetics Market
Cosmetics & Skincare
Bangladesh Face Wash Market
Cosmetics & Skincare
Sun Care Market
Cosmetics & Skincare
Global Cosmetic Shea Butter Market
Cosmetics & Skincare
Chile Cosmetics Products Market
Cosmetics & Skincare
Bath Soap Market
Cosmetics & Skincare
Beauty Facial Mask Market
Cosmetics & Skincare
Eyeliner Industry Status and Prospects Professional Market
Cosmetics & Skincare
E Commerce Cosmetic and Fragrance Market
Cosmetics & Skincare
Microbiome Cosmetic Products Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market