
 UAE Telecom Towers Market | 2026-2036
UAE Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Telecom Towers Market Insights
Buyer concentration among UAE mobile operators is hardening as Etisalat by e& Infrastructure and du Tower Operations consolidate tower demand under long-term infrastructure-sharing agreements. Etisalat leverages its nationwide fiber backbone to anchor co-location tenancy rates across its tower portfolio. TASC Towers competes through specialized engineering services for concealed and rooftop structures in Dubai's dense commercial zones. American Tower extends its operational footprint by applying standardized asset management protocols developed in mature North American markets.
UAE telecom towers are steel or reinforced concrete structures engineered to support antenna arrays, transmission equipment, and power systems at heights typically ranging from 20 to 120 meters, with wind-load ratings calibrated to Gulf Cooperation Council environmental standards. Lattice towers dominate the Type segment due to their load-bearing efficiency for multi-tenant 5G macro installations, while concealed structures command premium lease rates in Dubai Marina and Abu Dhabi Corniche districts where municipal aesthetic codes restrict visible infrastructure. The Technology segment tilts toward 5G as TDRA-mandated spectrum deadlines push mobile operators to upgrade existing 4G/LTE sites with massive MIMO-capable arrays.
TDRA licensing frameworks and Dubai Municipality building codes jointly determine tower siting permissions, setback requirements, and electromagnetic exposure thresholds, directly constraining deployment velocity in urban emirates. MOHAP safety standards and UAE civil defense regulations govern technician access protocols and structural inspection frequencies, adding compliance layers to operational expenditure models. Stakeholders must monitor TDRA's evolving infrastructure-sharing mandates and emirate-level zoning harmonization to anticipate tenancy pricing and co-location priority shifts.
Market Dynamics
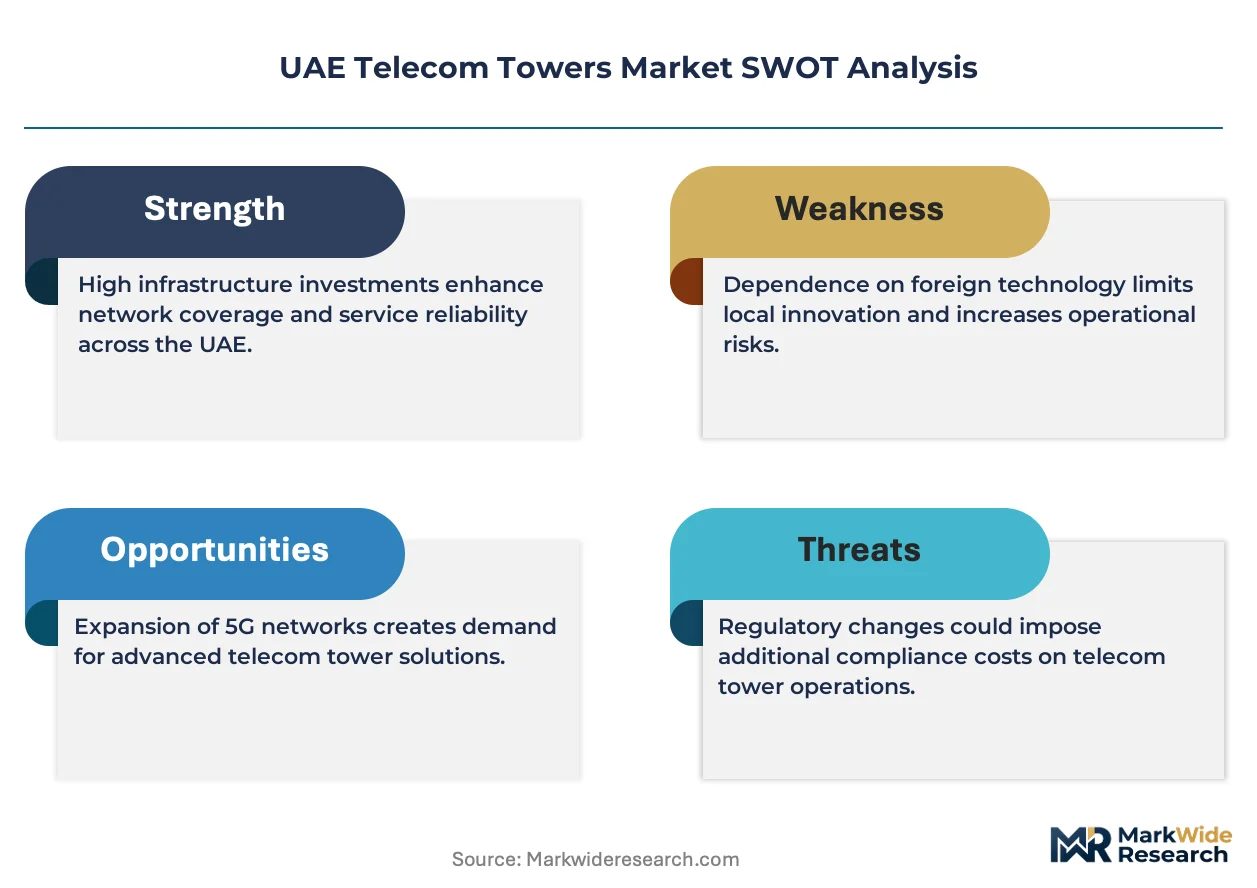
Etisalat by e& Infrastructure's national fiber-tower convergence strategy is compressing tenancy pricing power while du Tower Operations consolidates demand through infrastructure-sharing mandates. TDRA spectrum deadlines are forcing simultaneous 5G densification and 4G site rationalization across Abu Dhabi, Dubai, and Sharjah.
Growth Catalysts
- TDRA 5G Spectrum Mandates:The regulator's deployment deadlines compel mobile operators to upgrade existing macro sites with massive MIMO arrays, accelerating steel lattice tower modifications for multi-tenant capacity.
- Smart City Integration:Dubai Municipality's concealed structure aesthetic codes in Marina and Downtown districts drive premium deployments of rooftop and building-integrated small-cell backhaul solutions.
- Fiber-Tower Convergence:Etisalat by e& Infrastructure leverages its nationwide fiber backbone to anchor co-location tenancy agreements, reducing fronthaul costs for mobile network operators.
Market Restraints
- Steel Input Cost Volatility:GCC wind-load rated steel lattice specifications face pricing pressure from regional mill capacity constraints and import dependency for high-tensile structural grades.
- Emirate-Level Zoning Fragmentation:Dubai Municipality building codes and Abu Dhabi Department of Municipalities standards create non-harmonized setback and height restrictions that delay site approvals.
- Electromagnetic Exposure Thresholds:TDRA and MOHAP joint safety standards impose conservative radiation limits that restrict antenna density in residential zones, constraining urban small-cell deployment velocity.
Strategic Opportunities
- Sharjah Industrial Corridor Expansion:Underpenetrated zones between Sharjah and Ajman present greenfield lattice tower opportunities for logistics and port connectivity backhaul.
- Renewable Energy Integration:Solar-hybrid power systems converge with tower infrastructure to reduce diesel generator dependency in remote desert macro sites, aligning with UAE Net Zero 2050 commitments.
- Indoor Distributed Antenna Systems:Dubai Metro expansion and new airport terminals create demand for concealed DAS infrastructure where outdoor macro coverage proves insufficient.
Industry Challenges
- RF Engineer Scarcity:Massive MIMO configuration and beamforming optimization require specialized microwave engineering skills that outpace UAE technical training pipeline output.
- Legacy 2G/3G Decommissioning Complexity:Operators must maintain dual-band equipment during 4G/5G overlay transitions, complicating tower load assessments and structural recertification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Telecom Towers Market |
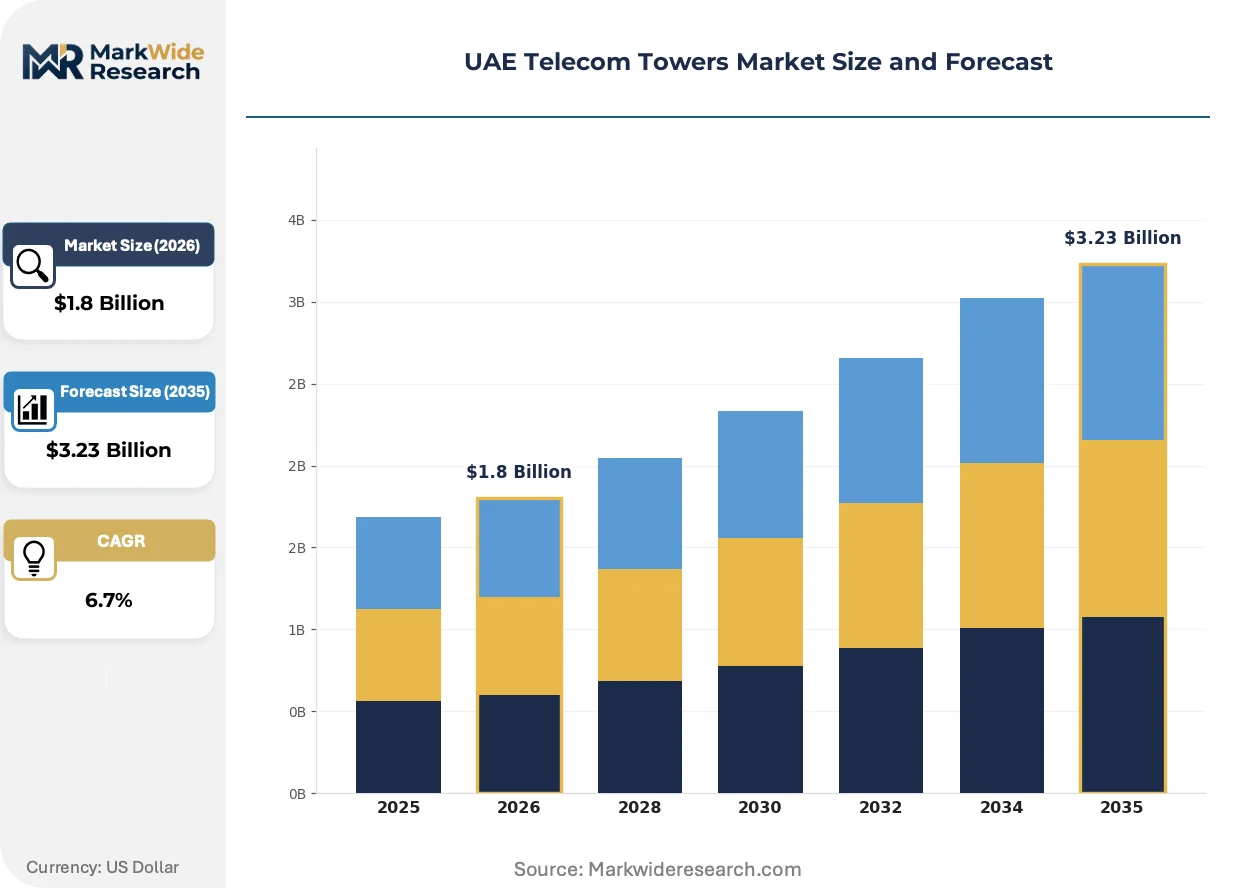
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Monopole, Lattice, Concealed, Guyed Technology: 4G, 5G, LTE, Microwave End User: Mobile Operators, ISPs, Enterprises, Government Deployment: Urban, Suburban, Rural, Remote |
| Companies Covered | Etisalat, Emirates Integrated Telecommunications Company (du), TASC Towers, American Tower, Etisalat by e& Infrastructure, du Tower Operations, Helios Towers, IHS Holding, Phoenix Tower International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Telecom Towers Market Trends and Innovations
Active antenna systems and intelligent power management are compressing tower spatial requirements while elevating thermal and structural engineering complexity. These shifts demand concurrent advances in materials science, regulatory compliance automation, and tenancy contract restructuring.
Massive MIMO active antenna units with integrated radio and phased-array elements are rewriting tower design specifications across the UAE. Mobile operators in Abu Dhabi and Dubai are retrofitting existing 30-meter monopoles with 64T64R configurations that triple wind-load moments and require foundation reinforcement. This compression of radio equipment into antenna housings is rewriting co-location space allocation and forcing landlords to renegotiate weight-bearing lease terms mid-contract.
TDRA's evolving infrastructure-sharing mandates are tightening operational frameworks for tower access and tenancy pricing transparency. The regulator's draft co-location priority rules would force Etisalat by e& Infrastructure to open fiber-tethered sites to du Tower Operations on regulated terms. Mobile network operators in dense urban emirates are responding by front-loading site acquisition to lock in exclusive positions before mandatory sharing takes effect.
Power purchase agreement structures for tower energy supply are displacing traditional diesel-generator-rental contracts across remote UAE macro sites. Tower operators in Ras Al Khaimah and Fujairah mountain corridors are contracting solar-hybrid microgrids through 10-year offtake agreements that transfer fuel-price risk to renewable developers. This procurement evolution is most visible in off-grid deployments where grid extension costs exceed $50,000 per kilometer and diesel logistics consume 15% of site opex.
UAE Telecom Towers Market Segmentation
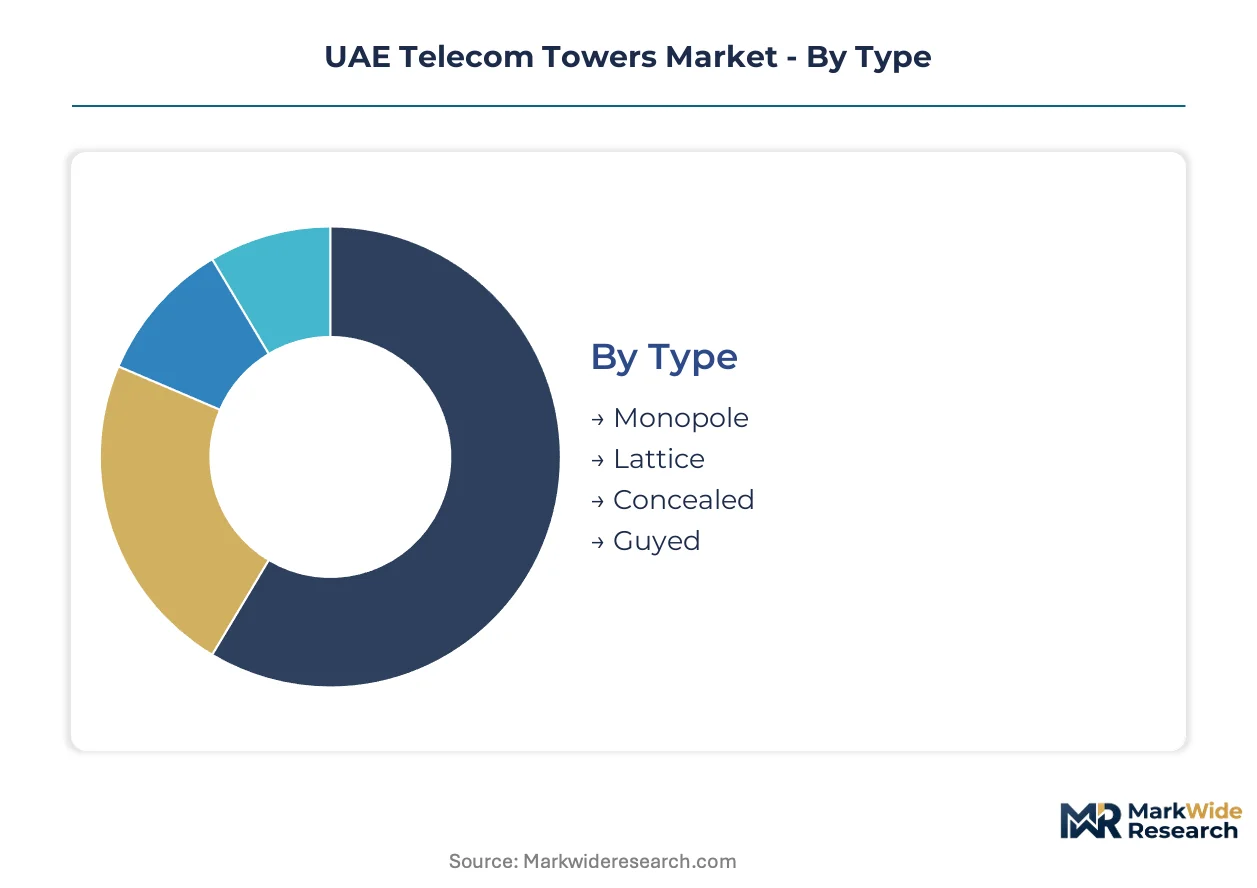
Segmentation in the UAE telecom towers market reveals how infrastructure requirements diverge across technology generations, regulatory environments, and deployment geographies. Tower specifications, tenancy configurations, and capital deployment patterns vary systematically by segment, shaping vendor specialization and operator procurement strategies.
Type:
Upgrade cycles from 4G to 5G massive MIMO configurations are forcing structural recertification across tower portfolios, with load-bearing capacity becoming the decisive selection criterion.
- Lattice:Steel lattice structures engineered for multi-tenant macro installations support the heaviest antenna arrays through triangulated load distribution. Demand concentrates in Abu Dhabi and Sharjah industrial corridors where Etisalat by e& Infrastructure anchors co-location hubs for multiple mobile operators under TDRA infrastructure-sharing mandates.
- Monopole:Single-pole steel or reinforced concrete structures ranging 20-50 meters suit dense urban deployments with limited footprint availability. Dubai Municipality aesthetic codes in Marina and Downtown districts drive specifications for slim-profile monopoles with concealed cable routing and integrated lighting suppression.
- Concealed:Architecturally integrated structures disguised as building elements, palm trees, or flagpoles command premium lease rates where visibility restrictions apply.
- Guyed:Tension-stabilized masts using guy wires achieve height-to-cost efficiency for temporary or remote deployments with lower wind-load requirements.
Volume placements concentrate in Lattice; the faster expansion belongs to Concealed.
Technology:
Cost tiers separate legacy equipment maintenance from next-generation deployment capital, with spectrum license deadlines compressing upgrade timelines.
- 5G:Massive MIMO active antenna systems with 64T64R configurations integrate radio and phased-array elements into compact housings. Abu Dhabi and Dubai mobile operators retrofit existing sites with these arrays, tripling wind-load moments and forcing foundation reinforcement under TDRA-mandated deployment schedules.
- 4G:LTE-Advanced macro equipment continues serving capacity layers during transition periods, maintaining tenancy revenue while 5G overlays proceed. Suburban corridors between Dubai and Sharjah retain 4G-dominant configurations where 5G spectrum allocation remains pending.
- LTE:Legacy FDD-LTE infrastructure supports voice fallback and IoT narrowband applications in rural Emirates.
- Microwave:Point-to-point backhaul links bridge fiber gaps in mountain terrain and maritime zones.
Deployment volumes favor 4G during the transition window; steepest expansion trajectory attaches to 5G.
End User:
Customer type determines tenancy contract structures, with mobile operators driving co-location density and enterprises seeking dedicated micro-cell coverage.
- Mobile Operators:Etisalat by e& and du Tower Operations consolidate demand through long-term infrastructure-sharing agreements, anchoring national fiber-tower convergence strategies. These tenants specify multi-tenant capacity, redundant power, and TDRA-compliant electromagnetic exposure documentation.
- ISPs:Fixed wireless access providers lease tower space for last-mile connectivity in fiber-underpenetrated zones, particularly in Sharjah industrial areas and Northern Emirates.
- Enterprises:Logistics, port operators, and smart city developers procure dedicated small-cell infrastructure for private network applications.
- Government:Federal and emirate-level agencies deploy emergency communications and surveillance backhaul on sovereign infrastructure.
Contract volumes cluster with Mobile Operators; Enterprise represents the fastest-climbing customer category.
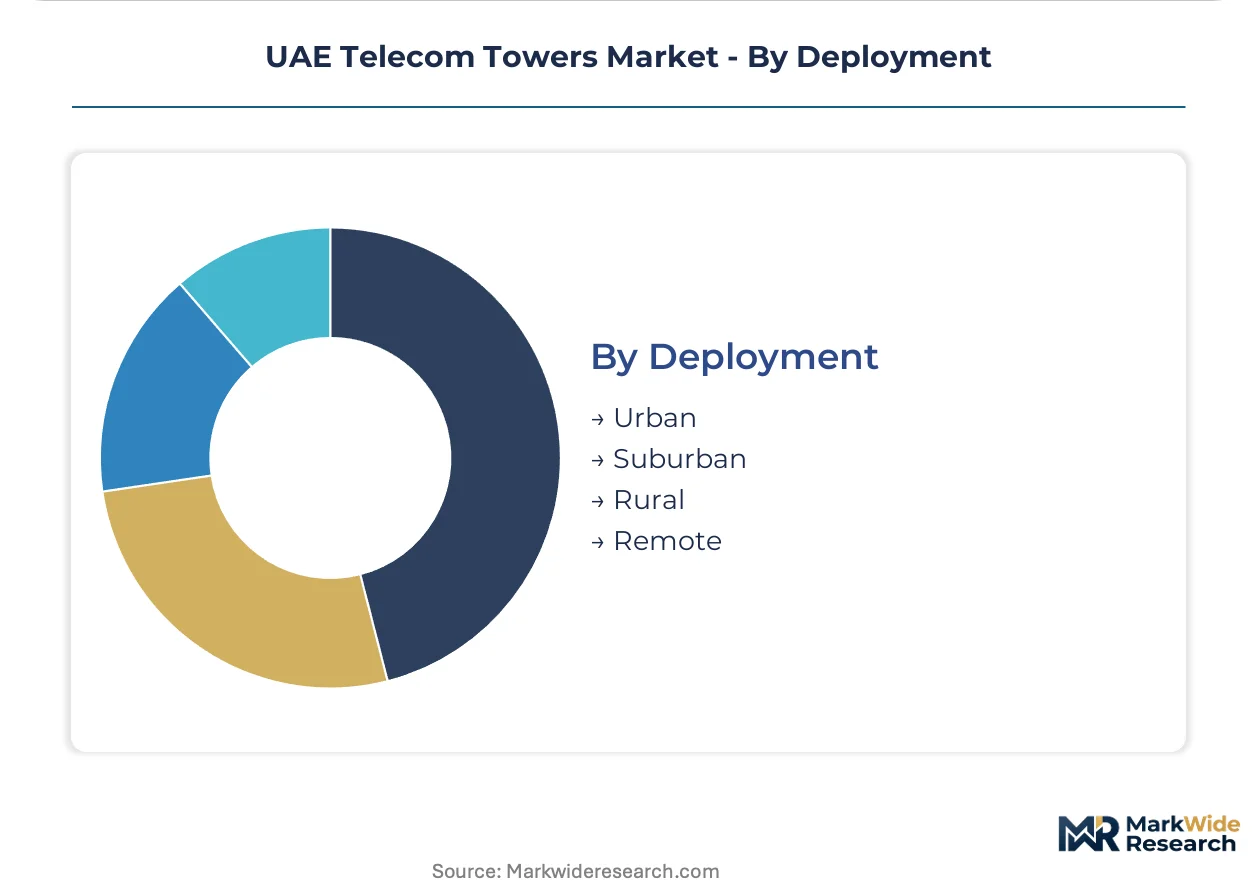
Deployment:
Geographic maturity shapes site acquisition difficulty and tenancy pricing, with urban saturation pushing capital toward underpenetrated zones.
- Urban:Dubai and Abu Dhabi city centers face severe site scarcity, driving rooftop and concealed structure premiums. Dubai Municipality building codes and TDRA electromagnetic thresholds restrict antenna density, elongating approval timelines and elevating lease rates.
- Suburban:Transition zones between Dubai-Sharjah and Abu Dhabi-Al Ain corridors balance coverage expansion with lower site acquisition costs. These areas host the majority of greenfield lattice deployments for 5G capacity layering.
- Rural:Agricultural and desert peripheries rely on solar-hybrid power systems where grid extension proves uneconomical.
- Remote:Mountain corridors in Ras Al Khaimah and Fujairah, plus offshore platforms, require helicopter-accessible structures with autonomous power and monitoring.
Investment deployment concentrates in Suburban zones; Remote deployments are gaining share fastest as coverage mandates extend to Northern Emirates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE mobile operators anchor tower demand through consolidated infrastructure-sharing agreements, with TDRA-mandated 5G deadlines compressing deployment timelines across all emirates. Site scarcity in mature urban centers is redirecting capital toward suburban corridors and Northern Emirates expansion zones.
Dubai
Dubai Municipality aesthetic codes in Marina and Downtown districts drive concealed structure premiums for rooftop and building-integrated deployments. TDRA electromagnetic exposure thresholds restrict antenna density in residential zones, elongating approval timelines. Jumeirah Lakes Towers and Business Bay host the majority of premium monopole installations serving financial district connectivity.
Abu Dhabi
Abu Dhabi Department of Municipalities standards govern setback requirements for industrial corridor lattice towers serving port and logistics backhaul. TDRA spectrum allocation policies prioritize 5G densification along the E11 highway corridor. Khalifa Industrial Zone anchors co-location hubs where Etisalat by e& Infrastructure consolidates multi-tenant macro sites.
Sharjah
Sharjah's underpenetrated industrial zones between the emirate and Ajman present greenfield lattice opportunities for logistics connectivity. The emirate's building codes harmonize with federal TDRA infrastructure-sharing mandates more rapidly than Dubai's municipal framework. Hamriyah Free Zone and Sharjah Airport International Free Zone concentrate new tower deployments for port and aviation backhaul.
Northern Emirates
Ras Al Khaimah and Fujairah mountain corridors require helicopter-accessible structures with autonomous solar-hybrid power systems where grid extension proves uneconomical. MOHAP safety standards and UAE civil defense regulations govern technician access protocols in remote terrain. Jebel Jais and Hajar Mountain deployment zones gain share fastest as coverage mandates extend to these peripheral regions.
UAE Telecom Towers Market Competitive Landscape
UAE-based infrastructure operators anchor one tier; international tower specialists hold positions in standardized asset management and operational protocols. Market structure tilts toward consolidation as Etisalat by e& Infrastructure leverages nationwide fiber backbones to compress tenancy pricing. Three archetypes dominate: integrated telecom infrastructure divisions, pure-play tower specialists, and international operators applying mature-market protocols. Dominant competitive moves include infrastructure-sharing mandate compliance and fiber-tower convergence strategies.
Within the integrated infrastructure tier, Etisalat by e& Infrastructure and du Tower Operations exemplify operators consolidating demand through long-term tenancy agreements. TASC Towers occupies a position among specialized engineering providers focused on concealed and rooftop structures in dense commercial zones. American Tower represents international operators extending standardized protocols from mature North American markets into UAE deployment frameworks.
| Leading Market Players |
|---|
| Etisalat |
| Emirates Integrated Telecommunications Company (du) |
| TASC Towers |
| American Tower |
| Etisalat by e& Infrastructure |
| du Tower Operations |
| Helios Towers |
| IHS Holding |
| Phoenix Tower International |
| Others |
Pricing and Supply Chain Analysis
TDRA-mandated 5G massive MIMO retrofits are compressing tenancy pricing power as tower operators absorb structural reinforcement costs without proportional lease rate recovery. Etisalat by e& Infrastructure's fiber-tower convergence strategy locks in multi-year co-location agreements at compressed rates, forcing competitors to match or exit dense urban corridors.
Pricing Analysis
Volume placements in lattice towers for suburban 5G corridors generate thin margins, while concealed structures in Dubai Marina and Downtown districts capture premium lease multiples through municipal aesthetic mandates. Pricing stratifies across concealed premium, lattice standard, and guyed economy tiers based on wind-load certification grade and fiber backhaul proximity. Cost compression in standard lattice segments is intensifying because Etisalat leverages captive fiber infrastructure to undercut third-party tower rents. Mobile operators exhibit lowest price sensitivity for concealed rooftop deployments where site scarcity overrides cost concerns, while ISP tenants in Sharjah industrial zones negotiate aggressively on per-meter rates.
Supply Chain Analysis
Regional distribution centers in Jebel Ali and Sharjah anchor hub-and-spoke steel delivery patterns, with mill-direct shipments from China, South Korea, and Turkey feeding GCC wind-load rated fabrication. High-tensile structural steel, galvanized coating materials, and foundation-grade concrete draw from concentrated Asian and European sources. Single-source vulnerability in specialized antenna mounting hardware creates procurement risk during TDRA-mandated deployment surges. Distribution runs through Etisalat by e& Infrastructure's captive logistics network for integrated projects, while independent tower operators rely on third-party EPC contractors for site assembly and commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE telecom towers market sits in a technology-transition phase as 5G massive MIMO active antenna systems displace legacy 4G passive equipment, rewriting structural engineering specifications and tenancy economics simultaneously.
For Market Incumbents: To counter TDRA's draft co-location priority rules that would force fiber-tethered site sharing, Etisalat by e& Infrastructure should accelerate exclusive site acquisition in Dubai Marina and Business Bay before mandatory sharing takes effect. Backward integration into solar-hybrid power systems for remote Northern Emirates sites reduces diesel opex exposure and aligns with UAE Net Zero commitments. For New Entrants and Emerging Players: Begin with underpenetrated Sharjah-Ajman industrial corridors where logistics and port connectivity backhaul demand outstrips current lattice tower supply. Target concealed DAS infrastructure for Dubai Metro expansion phases and new airport terminals, positioning as specialized engineering partners rather than asset owners to bypass Etisalat's fiber-anchored pricing power. For Investors and Strategic Acquirers: The window for entry favors pure-play engineering specialists with concealed structure capabilities in dense urban emirates, as asset-heavy tower ownership faces tenancy compression from infrastructure-sharing mandates. Monitor TDRA's final co-location priority rule publication as the inflection signal determining whether fiber-tethered site valuations hold or reset downward.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-Tower Convergence | Etisalat leverages captive fiber backbone to anchor multi-tenant co-location agreements at below-market rates. |
| Concealed Structure Engineering | Dubai Municipality aesthetic codes in Marina and Downtown districts create premium pricing tiers for architecturally integrated deployments. |
| Solar-Hybrid Power Integration | Remote desert and mountain sites in Ras Al Khaimah displace diesel generators through renewable microgrid offtake contracts. |
| 5G Massive MIMO Retrofit | TDRA spectrum deadlines force foundation reinforcement and wind-load recertification across existing lattice portfolios. |
| Infrastructure-Sharing Compliance | Draft co-location priority rules would compel Etisalat to open fiber-tethered sites to du Tower Operations on regulated terms. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with tower engineering directors, mobile network infrastructure planners, TDRA regulatory affairs specialists, and EPC procurement managers. TDRA spectrum allocation databases, Dubai Municipality building permit records, Etisalat and du infrastructure disclosure filings, and GCC steel import manifests provided demand-side and supply-side validation. Bottom-up site deployment counts triangulated against top-down mobile operator capex allocations.
Granularity-level modeling captured tower type specifications, technology generation transitions, end-user contract structures, and emirate-level deployment geographies across the analysis window. CAGRs derived from regression against mobile subscriber density, data traffic growth curves, and TDRA-mandated coverage obligations. Massive MIMO equipment weight specifications and wind-load engineering standards fed structural upgrade cost assumptions.
Underlying measurement precision varies by segment; urban concealed deployments carry tighter precision than remote Northern Emirates estimates due to municipal permit transparency. Forecasts reflect documented assumptions regarding TDRA infrastructure-sharing rule finalization and Etisalat fiber-tower convergence pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
Nigeria Telecom Tower Market
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
Mexico Telecom Tower Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
Communication Repeater Market
Telecommunications Infrastructure
Canada Telecom Towers Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Carrier Infrastructure in Telecom Applications Market
Telecommunications Infrastructure
Fixed-Line Communications Market
Telecommunications Infrastructure
Iraq Telecom Market
Telecommunications Infrastructure
Bangladesh Telecom Towers Market