
 Fixed-Line Communications Market | 2026-2036
Fixed-Line Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed-Line Communications Market Analysis
The divergence between premium fiber services and legacy copper infrastructure is hardening across developed markets. Deutsche Telekom leverages its extensive fiber backbone to dominate enterprise-grade deployments in Germany. Verizon sustains competitive positioning through dense metropolitan fiber networks and vertical integration into last-mile infrastructure. AT&T differentiates by controlling both wholesale fiber access and direct-to-enterprise service layers.
Fixed-line communications encompasses terrestrial wired transmission systems using copper, coaxial, or fiber-optic media to deliver voice, data, and video services with guaranteed bandwidth and sub-millisecond latency parameters. These networks serve as the foundational transport layer for commercial broadband, mission-critical enterprise connectivity, and broadcast distribution. Fiber optic technology leads capital allocation due to its superior capacity scalability and operational longevity versus aging DSL and PSTN alternatives. Enterprise end users represent the fastest-growing demand pool as organizations migrate from on-premises PBX systems to cloud-based unified communications platforms requiring symmetric, high-availability links. Residential voice services occupy a mature, declining margin pool as mobile substitution accelerates.
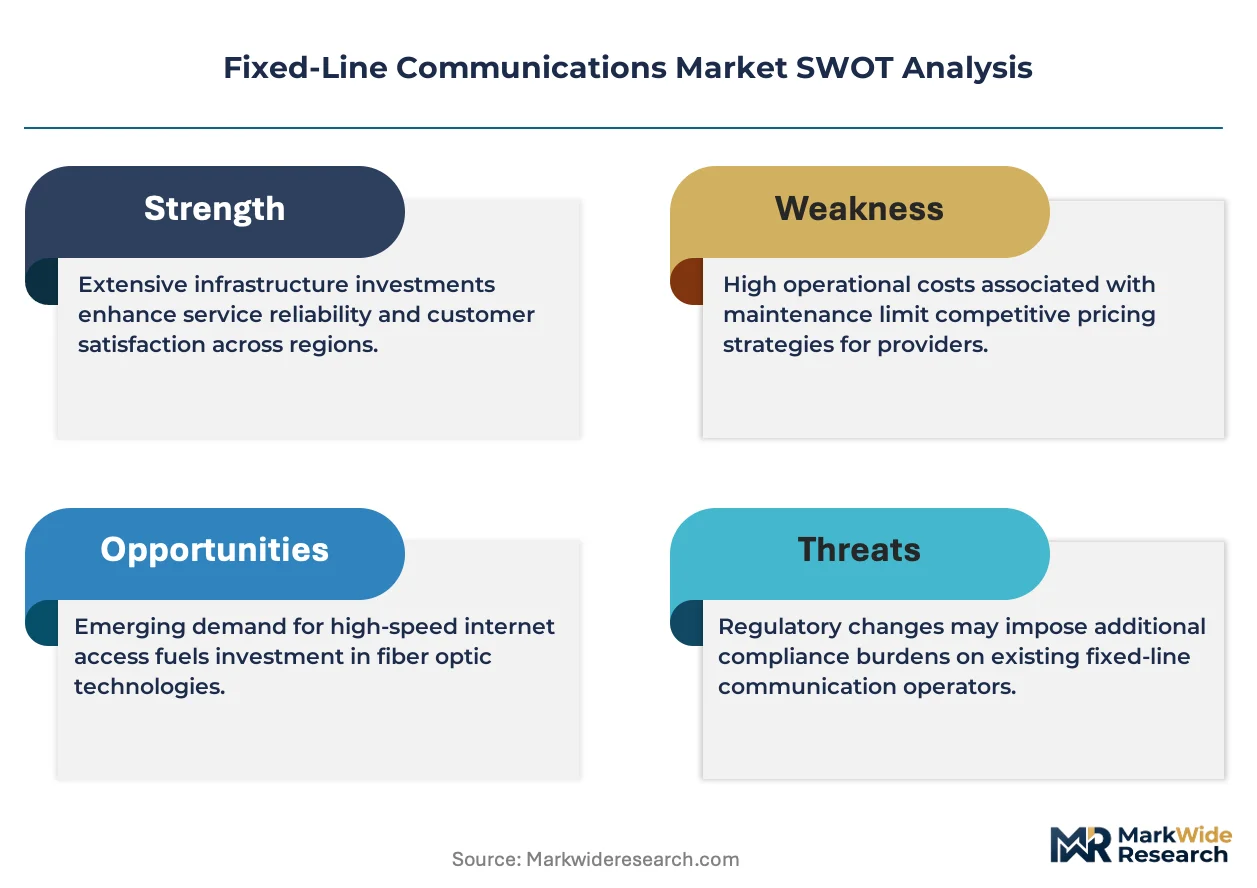
FCC broadband deployment mandates in the United States, EU Green Deal connectivity targets under the European Commission, and Japan's Ministry of Internal Affairs and Communications fiber penetration standards collectively shape infrastructure investment timelines and product certification requirements. These frameworks compel incumbents to retire legacy copper assets while accelerating fiber-to-the-premises obligations. Stakeholders must monitor regulatory phase-out schedules for PSTN networks and calibrate capital migration toward software-defined access architectures that unify fiber transport with cloud orchestration layers.
Market Dynamics
Copper retirement mandates from Germany, Japan, and the United States are forcing synchronized capital reallocation toward fiber-to-the-premises infrastructure, compressing legacy revenue streams while enterprise demand for symmetric bandwidth accelerates.
Growth Catalysts
- EU Green Deal connectivity targets:The European Commission's fiber penetration standards compel incumbents to accelerate fiber-to-the-premises rollouts, triggering wholesale network modernization investments across Germany and France.
- Enterprise unified communications migration:Organizations replacing on-premises PBX systems with cloud-based platforms require guaranteed sub-millisecond latency, pulling fiber deployments into commercial districts.
- Japan's MIC fiber standards:The Ministry of Internal Affairs and Communications mandates 100% fiber coverage timelines, directing capital toward last-mile infrastructure upgrades in metropolitan and rural prefectures.
Market Restraints
- Copper retirement cost overhang:Decommissioning legacy PSTN infrastructure requires parallel maintenance of dual networks during transition windows, elevating operational expenditure burdens.
- Construction labor scarcity:Specialized fiber splicing and micro-trenching technicians concentrate in urban Germany and Japan, constraining rural deployment velocity.
- Mobile substitution for residential voice:Wireless carriers capture remaining consumer voice minutes, eliminating margin contribution from legacy copper subscriber bases.
Strategic Opportunities
- Software-defined access convergence:Integration of fiber transport with cloud orchestration layers enables programmable bandwidth provisioning for enterprise customers.
- Hybrid work infrastructure gaps:Small and mid-sized enterprises in secondary German cities lack symmetric connectivity, creating whitespace for competitive fiber overbuilds.
- FCC broadband equity programs:Federal subsidies for underserved census tracts offset capital intensity of rural fiber deployments in the United States.
Industry Challenges
- Legacy OSS/BSS integration complexity:Incumbent operational support systems require multi-year transformation to interface with software-defined network controllers.
- Permitting timeline variability:Municipal right-of-way approvals for fiber construction differ across German states, Japanese prefectures, and US municipalities, compressing deployment predictability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed-Line Communications Market |
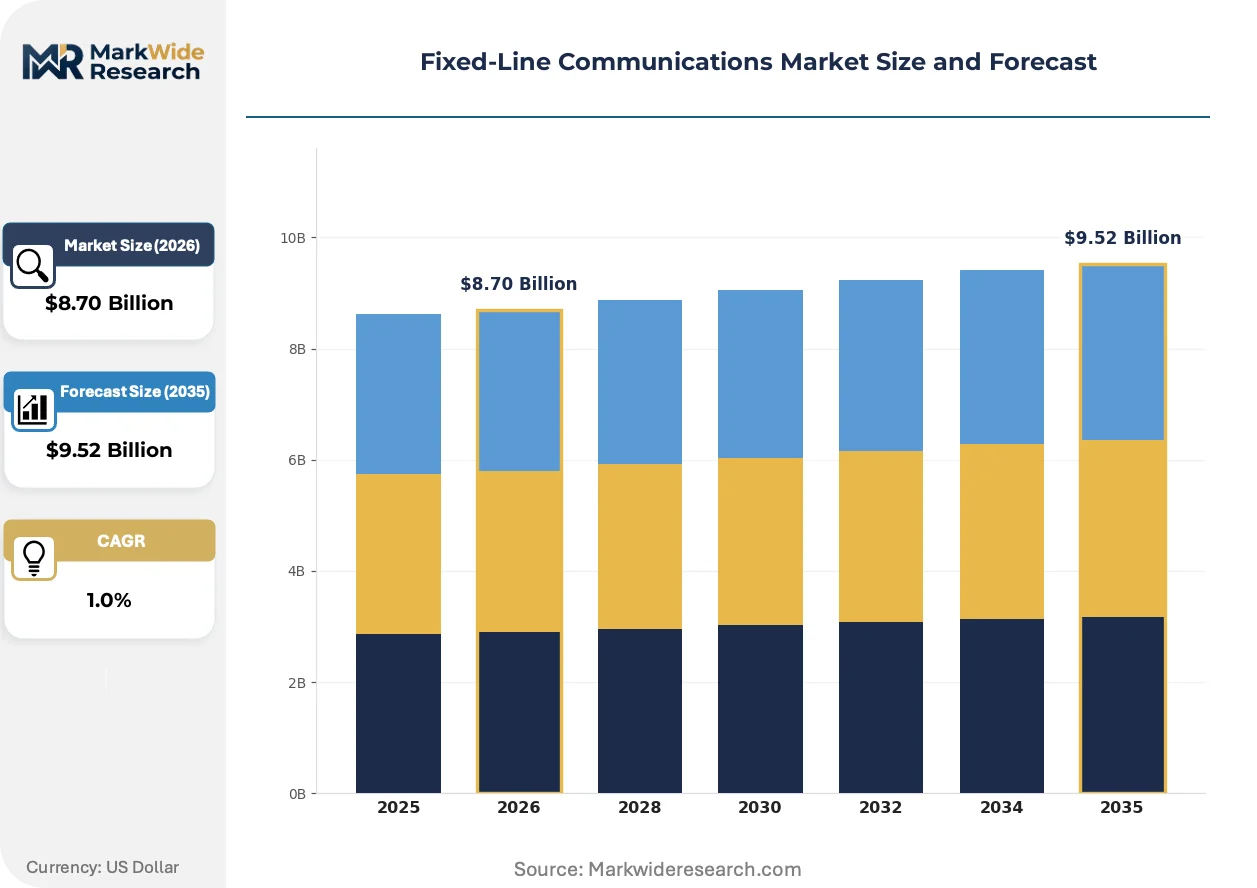
| Market Size in 2026 | $8.70 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: DSL, Fiber Optic, Cable, PSTN End User: Residential, Small Business, Enterprise, Government Service Type: Voice, Broadband, IPTV, Unified Communications Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | AT&T, Verizon, Comcast, Deutsche Telekom, Nippon Telegraph and Telephone, China Telecom, China Mobile, BT Group, Telefónica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed-Line Communications Market Emerging Trajectories
Passive optical network architectures are converging with software-defined layers, enabling programmable service delivery that compresses provisioning cycles and shifts competitive differentiation toward orchestration capabilities rather than raw transport capacity.
XGS-PON technology is unifying residential and enterprise service delivery onto single fiber strands, eliminating parallel infrastructure builds. German operators deploy XGS-PON to serve both consumer gigabit tiers and business symmetric services from shared optical line terminals. This convergence is unifying capital efficiency metrics across previously segmented customer bases, forcing vendors to recalibrate equipment roadmaps toward higher split ratios and extended reach optics.
The FCC's broadband nutrition label requirements mandate standardized disclosure of latency, packet loss, and pricing, introducing comparability pressure previously absent in business connectivity procurement. Enterprise buyers now demand contractual latency guarantees backed by service level agreements with financial remedies. Wholesale fiber access seekers in the United States are responding by requiring operational transparency from underlying transport providers before contract execution.
Enterprise procurement committees now separate connectivity purchasing from managed service bundling, disaggregating transport from value-added layers. Channel partners in Japan and Germany face compression as direct fiber procurement through carrier-neutral data centers expands. This pattern concentrates most visibly among financial services and cloud-native software firms with internal network engineering capabilities.
Fixed-Line Communications Market Segmentation
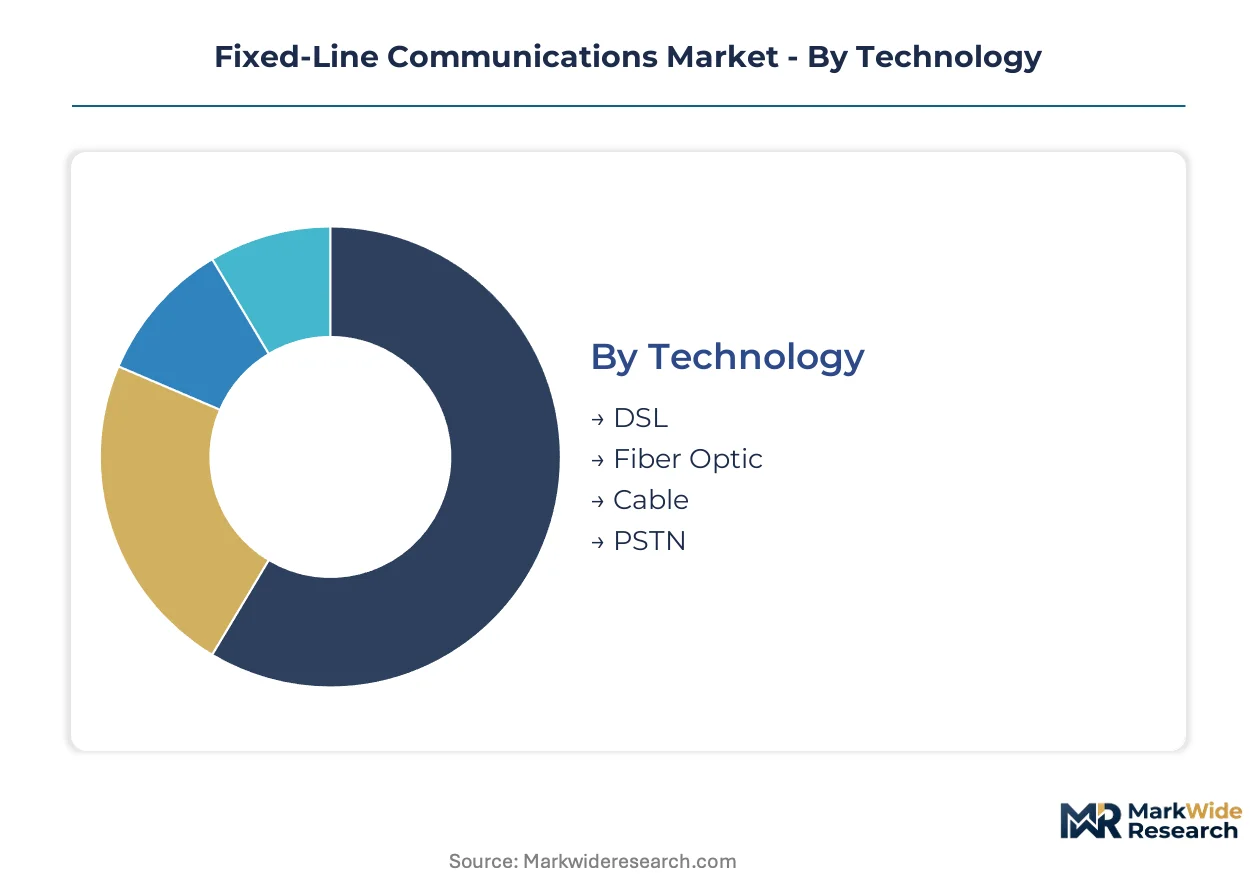
Fixed-line communications markets fragment across infrastructure generations, customer scale, and service orchestration models. Segmentation reveals where capital migrates from depreciating copper assets toward programmable fiber architectures.
Technology:
Upgrade cycles and replacement timelines determine technology mix as operators synchronize copper retirement with fiber overbuild economics.
- Fiber Optic:Single-mode and multi-mode silica waveguides deliver symmetric gigabit throughput with sub-millisecond latency specifications. Deutsche Telekom and NTT East concentrate deployment capital in German metropolitan zones and Tokyo prefectures where enterprise cloud connectivity requirements justify trenching intensity.
- Cable:Hybrid fiber-coaxial networks leverage DOCSIS 3.1 and 4.0 upgrades to extend serviceable life of existing plant. Comcast and Charter Communications prioritize HFC node splits in US suburban corridors where fiber-to-the-premises economics remain prohibitive.
- DSL:Copper-pair digital subscriber line technology operates over legacy PSTN infrastructure with asymmetric bandwidth profiles. Rural Germany and Japanese mountain prefectures retain DSL where fiber construction labor scarcity delays overbuild schedules.
- PSTN:Circuit-switched analog voice infrastructure faces mandated sunset dates across EU member states and Japan. Carriers maintain parallel operational support systems during transition windows, elevating cost burdens.
Fiber Optic sits at the top of the volume ranking, with Cable climbing the fastest as DOCSIS upgrades defer full fiber replacement.
End User:
Customer scale and service criticality drive diverging procurement patterns across connectivity tiers.
- Enterprise:Multi-site organizations demand contractual latency guarantees and diverse path routing for unified communications platforms. Financial services clusters in Frankfurt and cloud-native firms in Tokyo Bay area specify dark fiber and wavelength services.
- Small Business:Single-location commercial entities prioritize cost-competitive symmetric broadband without managed service bundling. Secondary German cities and US Midwest metropolitan areas present whitespace for competitive overbuilds.
- Government:Federal, state, and municipal agencies mandate secure, sovereign infrastructure with certified encryption standards. EU public sector procurement favors operators with CSRD disclosure compliance and green energy sourcing.
- Residential:Consumer households exhibit price elasticity and service substitution toward mobile broadband. Voice revenue erosion accelerates as wireless carriers capture remaining subscriber minutes.
Enterprise commands premium pricing tiers, while Small Business segments gain share fastest through disaggregated procurement models.
Service Type:
Service layering determines margin architecture as transport commoditization pressures value-added bundles.
- Unified Communications:Integrated voice, video, and messaging platforms delivered via software-as-a-service models. Microsoft Teams and Zoom certification requirements pull fiber deployments into commercial districts.
- Broadband:High-capacity internet access with standardized throughput tiers. FCC nutrition label mandates introduce comparability pressure on latency and packet loss disclosures.
- Voice:Traditional telephony services over circuit-switched or packet-switched infrastructure. Regulatory phase-out schedules compress remaining revenue streams.
- IPTV:Internet protocol television distribution bundled with broadband subscriptions. German and Japanese operators leverage multicast capabilities over fiber networks.
Broadband generates foundational volume, with Unified Communications expanding most quickly as PBX replacement accelerates.
Deployment:
Infrastructure control and operational responsibility partition risk allocation between carriers and customers.
- Cloud-Based:Fully managed service delivery with zero customer premises equipment ownership. Financial services firms in London and Singapore specify cloud-native connectivity for trading floor applications.
- Managed Services:Outsourced network operations with guaranteed service level agreements and proactive monitoring. Mid-market enterprises in Osaka and Munich delegate CPE management to specialist integrators.
- Hybrid:Split architecture combining on-premises switching with cloud-orchestrated transport. Manufacturing facilities in Stuttgart industrial zones retain local control over critical systems.
- On-Premises:Customer-owned and operated infrastructure with carrier-provided transport only. Large enterprises with internal network engineering capabilities pursue this disaggregated model.
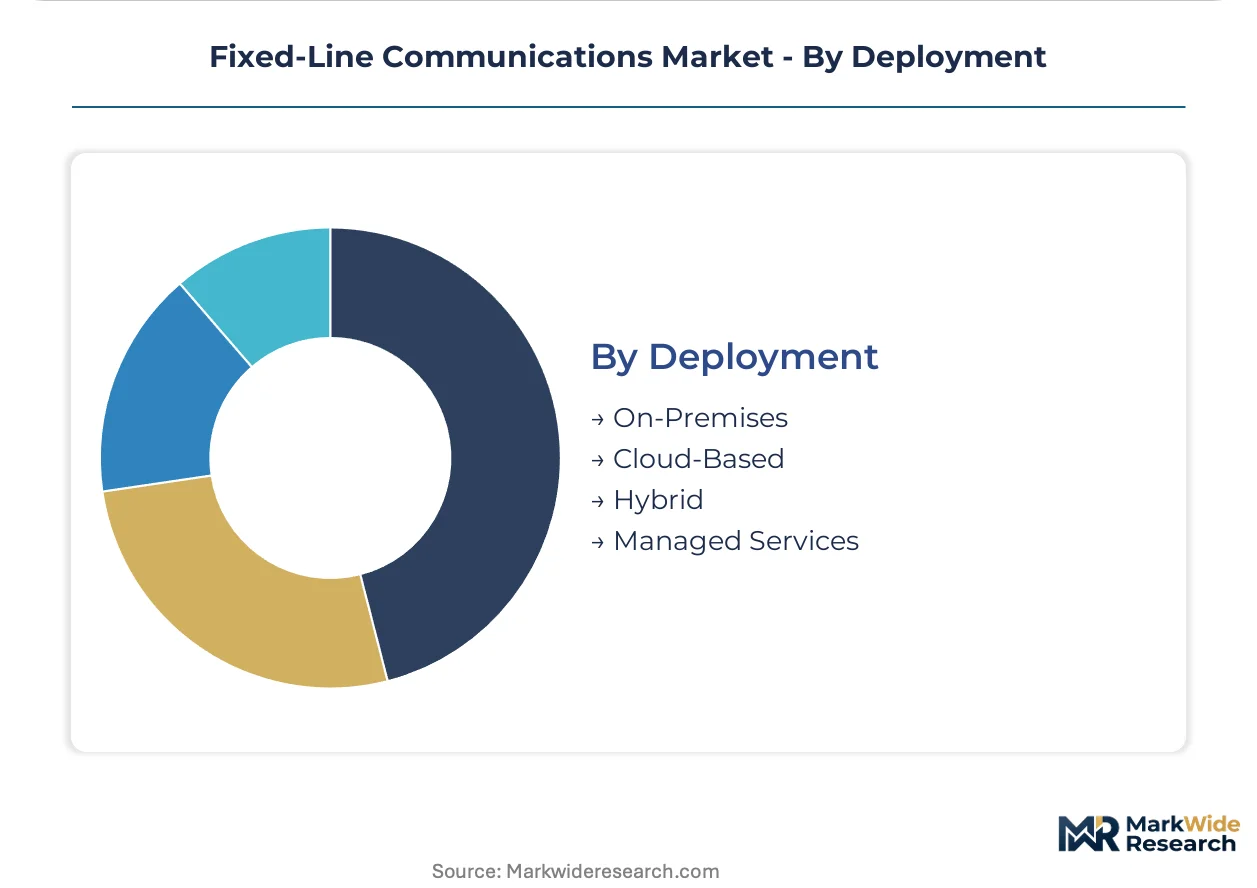
Managed Services anchor current revenue composition, though Cloud-Based deployment climbs fastest among digitally native organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fiber splicing technicians and network engineering talent concentrate in German metropolitan zones, Japanese prefectures, and US coastal corridors, anchoring deployment velocity in these markets while constraining rural expansion elsewhere.
United States
Enterprise cloud migration and hybrid work infrastructure demands pull fiber investments into commercial districts. FCC broadband equity programs subsidize rural deployments in underserved census tracts. Dense metropolitan fiber networks in New York and Chicago sustain competitive positioning for wholesale access seekers.
Germany
Copper retirement mandates from the federal network agency force synchronized capital reallocation toward fiber-to-the-premises infrastructure. EU Green Deal connectivity targets compel incumbents to accelerate modernization timelines. Frankfurt's financial services cluster specifies dark fiber and wavelength services with contractual latency guarantees.
Japan
Ministry of Internal Affairs and Communications fiber penetration standards mandate 100% coverage timelines across metropolitan and rural prefectures. Enterprise unified communications migration requires symmetric, high-availability links for cloud-based platforms. Tokyo Bay area cloud-native firms drive direct fiber procurement through carrier-neutral data centers.
United Kingdom
Regulatory phase-out schedules for PSTN networks compress remaining copper revenue streams while accelerating fiber overbuild obligations. BT Group's infrastructure arm faces wholesale access pricing controls from the national communications regulator. London's enterprise corridor demands sub-millisecond latency specifications for trading floor applications.
China
State-directed infrastructure investment prioritizes fiber optic backbone expansion across provincial networks. MIIT broadband penetration targets shape capital allocation toward last-mile upgrades in secondary cities. Yangtze River Delta manufacturing zones retain hybrid architectures combining on-premises switching with cloud-orchestrated transport.
Fixed-Line Communications Market Vendor Landscape
Capital-heavy infrastructure owners compete with asset-light service orchestrators across diverging margin architectures. The market structure concentrates around incumbent national carriers with captive fiber plant, cable operators extending hybrid fiber-coaxial assets, and emerging wholesale fiber specialists. Three archetypes dominate: vertically integrated incumbents controlling both transport and service layers, facility-based competitors leveraging dense metropolitan footprints, and carrier-neutral platform players disaggregating access from service delivery. Competitive moves center on copper retirement synchronization with fiber overbuild economics, and strategic partnerships with cloud providers to embed connectivity into unified communications stacks.
Among US-based integrated carriers, AT&T and Verizon exemplify the vertically integrated archetype, each controlling wholesale fiber access and direct-to-enterprise service layers. Deutsche Telekom represents the European incumbent model, leveraging extensive fiber backbone dominance in German metropolitan zones. These three operators anchor competitive positioning through infrastructure ownership depth rather than service-layer differentiation alone.
| Leading Market Players |
|---|
| AT&T |
| Verizon |
| Comcast |
| Deutsche Telekom |
| Nippon Telegraph and Telephone |
| China Telecom |
| China Mobile |
| BT Group |
| Telefónica |
| Others |
Supply Flow & Price Mechanics
XGS-PON technology migration is compressing per-port equipment costs while concentrating optical component sourcing among specialized East Asian foundries, simultaneously reshaping service economics and supply chain geography.
Pricing Analysis
The bundled-vs-unbundled service split defines margin architecture across customer tiers. Three-tier pricing structure across premium, standard, and economy levels segments enterprise dark fiber, managed wavelength services, and wholesale broadband access. Price differentiation hinges on latency certification grade and symmetric bandwidth guarantees. Cost compression in standard tiers is intensifying because XGS-PON convergence eliminates parallel infrastructure builds. Small business segments exhibit highest price sensitivity, while financial services clusters in Frankfurt and Tokyo Bay tolerate premium positioning for sub-millisecond contractual guarantees.
Supply Chain Analysis
Reverse-logistics flows for optical line terminals and customer premises equipment concentrate refurbishment activity in Shenzhen, Dongguan, and Kaohsiung, extending hardware service life and compressing replacement cycle revenues. Optical transceiver production draws from Taiwan, China, and Japan. Key inputs span indium phosphide wafers, silica fiber preforms, and specialized splicing equipment. Single-source vulnerability in indium supply from Chinese smelters elevates geopolitical risk exposure. Distribution runs through carrier-neutral data centers and direct enterprise procurement channels, bypassing traditional telecom resale hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed-line communications operates as a stable compounder where fiber infrastructure longevity and regulated copper retirement timelines generate predictable replacement demand across enterprise and residential segments.
For Market Incumbents: Lock in enterprise customer relationships through software-defined access orchestration platforms that embed connectivity into unified communications workflows. Accelerate copper retirement synchronization with fiber overbuild economics in German metropolitan zones and Tokyo prefectures. Defend against wholesale fiber specialists by controlling both transport and service layers through backward integration into last-mile infrastructure.
For New Entrants and Emerging Players: Capture whitespace in secondary German cities and US Midwest metropolitan areas where small and mid-sized enterprises lack symmetric connectivity options. The most penetrable segment spans cloud-native firms with internal network engineering capabilities pursuing disaggregated transport procurement. Pursue carrier-neutral data center partnerships as primary go-to-market angle, bypassing incumbent channel structures.
For Investors and Strategic Acquirers: Valuations sit cheapest among facility-based competitors with dense metropolitan fiber footprints but limited service-layer differentiation. Long-term viability centers on infrastructure ownership depth rather than software differentiation alone. Target acquisition archetype: wholesale fiber specialists with municipal right-of-way permits in underserved US census tracts. Monitor FCC broadband equity program disbursement velocity as inflection indicator for rural deployment profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Copper Retirement Synchronization | Aligns legacy asset decommissioning with fiber overbuild economics mandated by EU Green Deal targets. |
| XGS-PON Technology Migration | Unifies residential and enterprise service delivery onto single fiber strands, eliminating parallel capital deployment. |
| Software-Defined Access Integration | Enables programmable bandwidth provisioning for enterprise customers through cloud orchestration layer convergence. |
| Carrier-Neutral Data Center Partnership | Captures direct fiber procurement from cloud-native firms bypassing traditional incumbent channel structures. |
| FCC Broadband Equity Program Participation | Offsets capital intensity of rural fiber deployments through federal subsidies for underserved census tracts. |
Methodological Framework
Bottom-up enterprise connectivity modeling reconciled against top-down fiber infrastructure tracking forms the analytical core of this study. Primary interviews with network planning executives, enterprise IT procurement officers, data center interconnection specialists, and municipal broadband coordinators informed demand-side assumptions. Secondary validation drew from FCC deployment databases, EU Green Deal progress reports, Japanese MIC coverage statistics, and carrier capital expenditure disclosures. Triangulation across these sources anchored volume estimates for fiber-to-the-premises rollouts and unified communications migration timelines.
Input-output matrix framing connects subscriber growth assumptions to equipment deployment requirements across the projection horizon. Segmentation dimensions modeled span technology generation, end-user scale, service orchestration model, and regional regulatory cluster. CAGRs derive from slope analysis of historical infrastructure investment patterns projected against mandated copper retirement schedules. Industry-specific forecast inputs include fiber splicing technician availability constraints and municipal permitting timeline variability across German states and Japanese prefectures.
Underlying measurement precision varies by segment; fiber optic deployment volumes carry tighter precision than legacy DSL retention estimates due to more transparent carrier reporting obligations. Forecasts reflect assumptions about regulatory phase-out adherence and construction labor mobility that could shift materially. Practitioners should monitor copper retirement schedule acceleration, XGS-PON equipment cost curves, and enterprise SaaS procurement committee composition for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Mexico Telecom Tower Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Nigeria Telecom Tower Market
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
Latin America Telecom Tower Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
Global Cellular Networks Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Japan Telecom Towers Market
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Kenya Telecom Tower Market