
 Fixed Telephony Service Market | 2026-2036
Fixed Telephony Service Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Telephony Service Market Foresight
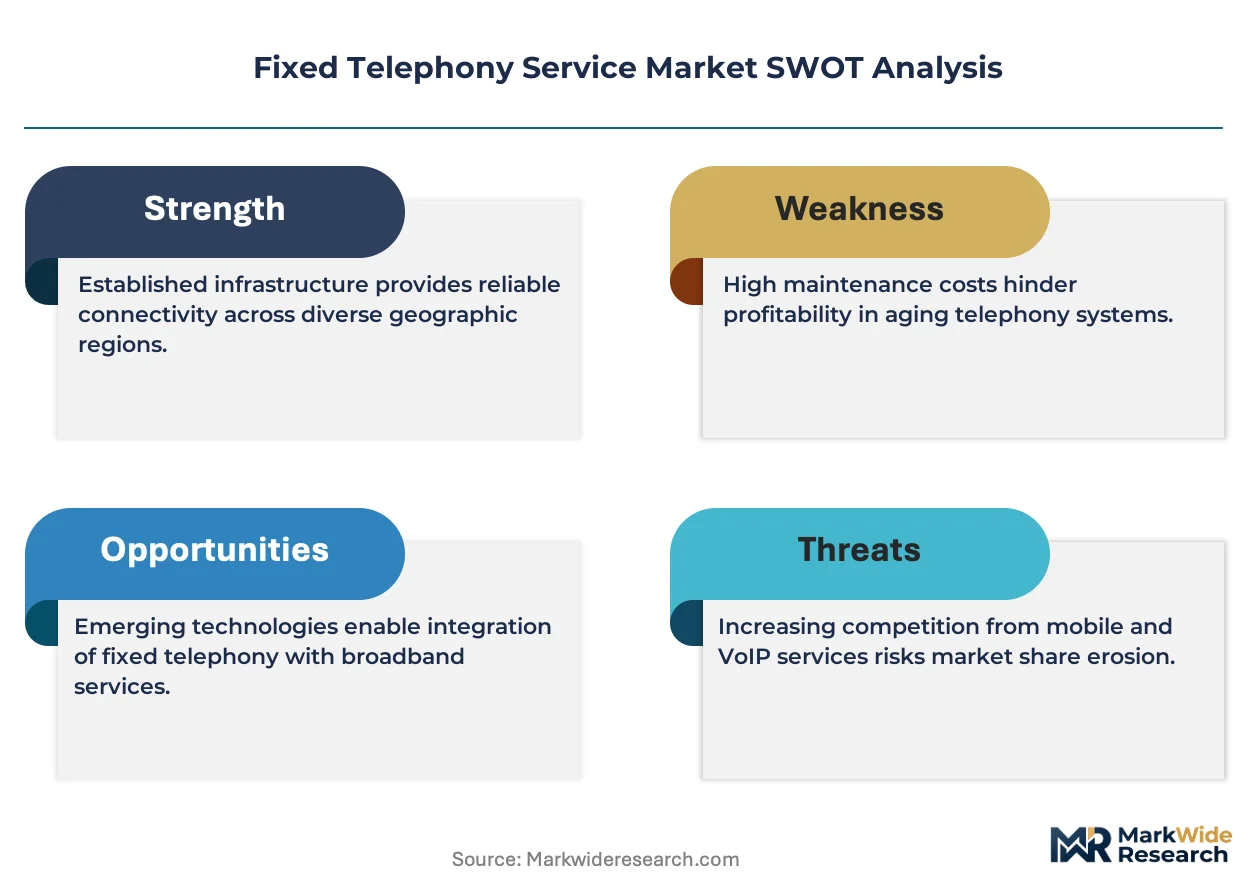
Network virtualization is tilting fixed telephony infrastructure toward cloud-native architectures that decouple voice switching from physical copper loops. RingCentral leverages its UCaaS platform to anchor enterprise subscriptions across hybrid workforce deployments. Ooma competes through residential VoIP bundles that undercut incumbent cable pricing. Telnyx controls a global IP backbone that extends programmable voice APIs to software developers building communications stacks.
Fixed telephony service encompasses circuit-switched and packet-switched voice transmission delivered over copper pairs, fiber optics, or coaxial infrastructure, typically operating at 64 kbps per channel for PSTN or variable bitrates for compressed VoIP codecs. Its primary commercial purpose remains reliable real-time voice connectivity for entities requiring guaranteed service levels and emergency calling traceability. Enterprise communication dominates revenue as corporations maintain PRI trunks for call center reliability while SMEs accelerate VoIP migration to reduce per-line costs. Residential communication persists as a mature segment where households value bundled landline security systems and E-911 location precision over mobile alternatives.
The FCC's STIR/SHAKEN framework mandates caller ID authentication that shapes carrier investment in signaling infrastructure, while the EU's EECC directive imposes wholesale access obligations that restructure incumbent pricing power. Germany's BNetzA enforces number portability rules that reduce subscriber lock-in and intensify retail competition. Stakeholders must monitor regulatory deadlines for copper network decommissioning as these timelines determine stranded asset risk and replacement capital allocation priorities.
Market Dynamics
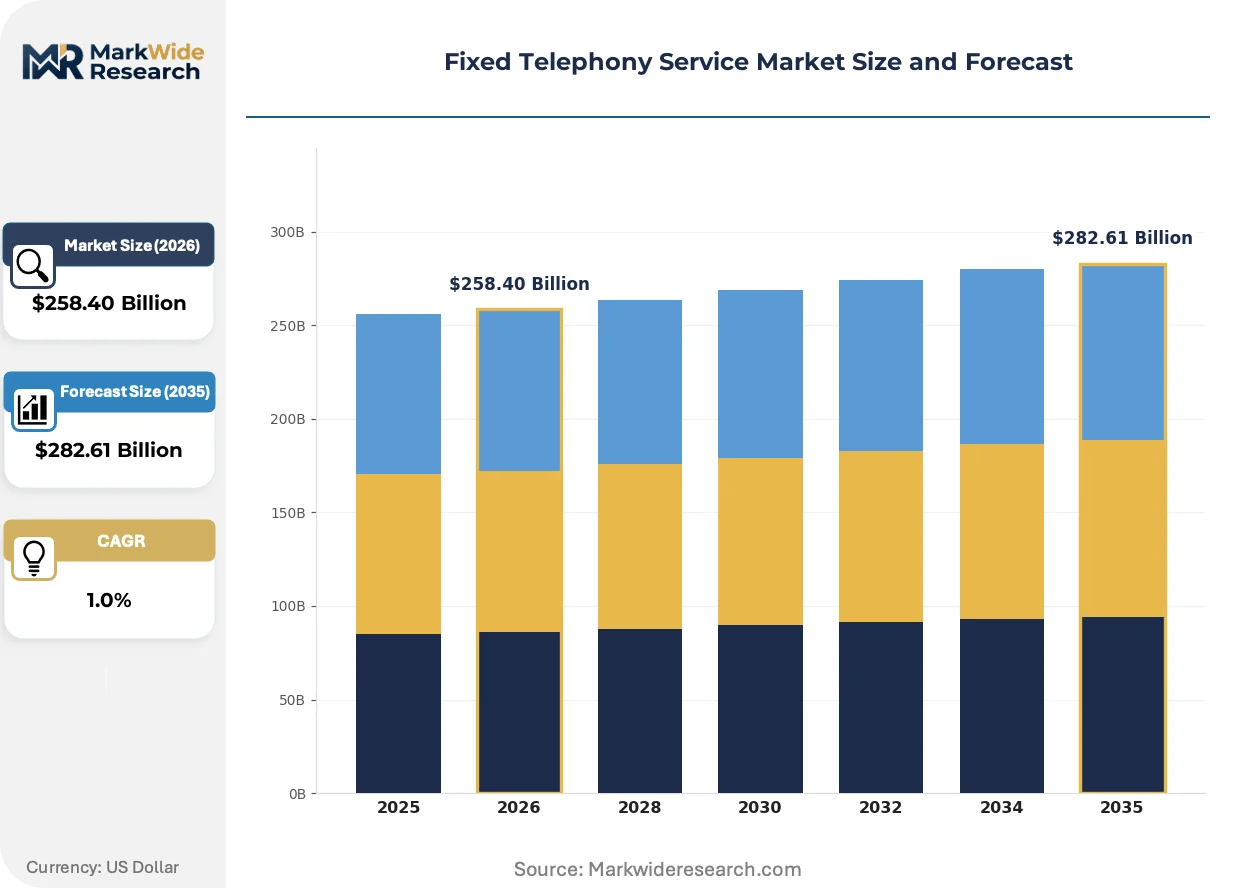
The Fixed Telephony Service Market pivots on copper network decommissioning mandates that force infrastructure replacement cycles while enterprise PRI trunking persists for mission-critical voice reliability.
Growth Catalysts
- FCC STIR/SHAKEN Mandate:Caller ID authentication requirements compel carriers to upgrade signaling infrastructure, creating replacement demand for compliant switching equipment across US networks.
- Industrial Cluster Demand:German manufacturing hubs maintain substantial PRI trunking for guaranteed service levels, sustaining circuit-switched revenue streams despite packet migration.
- VoIP Codec Advancement:Compressed voice transmission over fiber and coaxial infrastructure reduces per-line costs for SME migrations from legacy PSTN systems.
Market Restraints
- Copper Decommissioning Capital Burden:Incumbent carriers face stranded asset risk as physical loop retirement timelines accelerate, requiring substantial fiber overlay investment without guaranteed subscriber retention.
- Mobile Substitution Pressure:Households and micro-enterprises bypass fixed voice entirely, prioritizing cellular E-911 and smartphone ubiquity over landline security system bundles.
- Wholesale Access Pricing Compression:EU EECC directive obligations restructure incumbent pricing power, eroding retail margin protection through mandated network unbundling.
Strategic Opportunities
- Cloud-Native Switching Convergence:Network function virtualization decouples voice switching from physical infrastructure, enabling programmable API layers for developer-centric communications stacks.
- SME VoIP Migration White Space:Small and mid-sized enterprises accelerating PSTN exit create subscriber acquisition targets for bundled UCaaS platforms with hybrid workforce tooling.
- EECC Wholesale Tailwinds:Regulatory-mandated network access opens alternative operator entry paths across European markets, reducing barrier to national footprint expansion.
Industry Challenges
- Legacy PRI Integration Complexity:Enterprises maintaining circuit-switched trunks for call center reliability face interoperability friction during staged VoIP transitions.
- Number Portability Execution:Germany's BNetzA portability rules intensify subscriber churn risk, requiring retention investment without corresponding ARPU expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Telephony Service Market |
| Market Size in 2026 | $258.40 Billion |
| Market Size in 2035 | $282.61 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Local Calling, Long Distance Calling, International Calling, Caller ID, Call Waiting, Voicemail Technology: PSTN, VoIP, ISDN, Analog, Digital, PRI Application: Residential Communication, Enterprise Communication, Call Centers, Public Institutions, Educational Institutes End User: Households, SMEs, Corporations, Government Agencies |
| Companies Covered | Nextiva, Zoom Phone, RingCentral, Telnyx, Ooma, Vonage Business, Dialpad, Vistanet Telecommunications, 8x8, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Telephony Service Market Shifts & Advancements
Fixed telephony infrastructure undergoes architectural decoupling as cloud-native switching separates voice processing from physical transmission media, reshaping carrier capital allocation and vendor competitive positioning.
Session Border Controllers are migrating from hardware appliances to virtualized network functions deployed at network edge. Tier-1 carriers adopt containerized SBC deployments to reduce rack-space requirements and enable elastic scaling for traffic spikes. This technology is migrating from proprietary chassis to white-box server infrastructure, compressing equipment vendor margins while expanding systems integrator roles.
The FCC's copper retirement notification rules impose structured decommissioning timelines on incumbent local exchange carriers. These mandates force accelerated fiber deployment schedules and trigger wholesale access agreement renegotiations. Rural exchange areas face the most acute transition pressure as low-density economics complicate fiber replacement business cases.
Enterprise procurement of voice services now bundles connectivity with collaboration tooling and contact center software. IT departments consolidate vendor relationships, displacing standalone trunking contracts with platform subscriptions. North American mid-market corporations exhibit the most pronounced consolidation behavior, prioritizing single-source accountability over best-of-breed component sourcing.
Fixed Telephony Service Market Segmentation
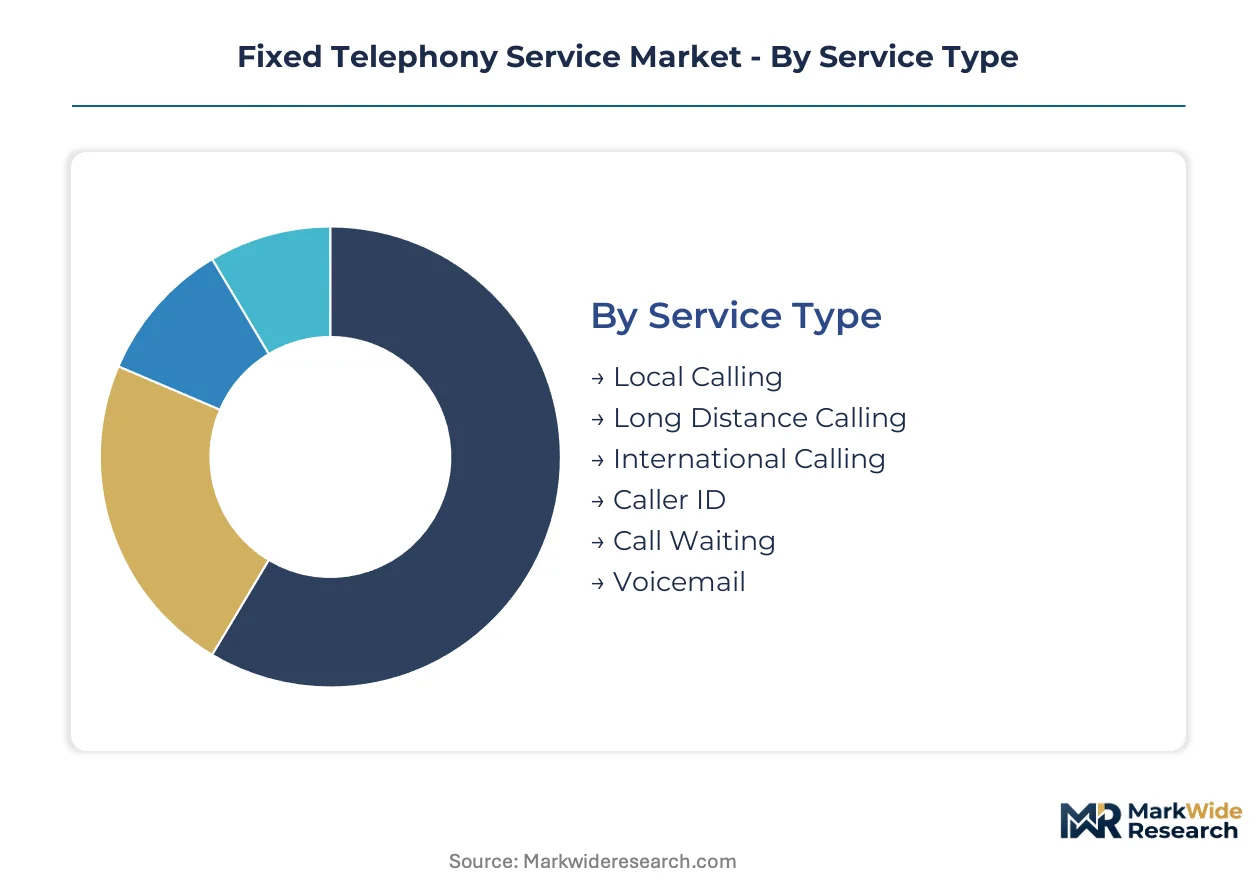
Segmentation in fixed telephony services reveals distinct replacement cycles across infrastructure layers, with technology turnover outpacing service packaging by a factor of three. Understanding these velocity differentials helps carriers align capital deployment with revenue stability.
Service Type:
Local calling services turn over slowest due to embedded consumer habits, while international calling faces the steepest substitution pressure from OTT alternatives.
- Local Calling:Basic voice connectivity within geographic numbering plan areas retains the highest subscriber stickiness. German industrial clusters and US rural cooperatives sustain circuit-switched local loops for E-911 traceability and alarm system integration.
- Long Distance Calling:Domestic inter-LATA traffic has compressed to commodity pricing tiers. Enterprise PRI trunking in North America still generates measurable long-distance revenue from call center overflow routing.
- International Calling:Carrier traffic faces terminal decline as WhatsApp and Zoom displace PSTN termination. Remaining demand concentrates among elderly demographics and regions with restrictive internet access.
- Caller ID:Delivery of calling party information via FSK or DTMF signaling remains standard. FCC STIR/SHAKEN mandates are forcing authentication overlay investments that elevate this basic feature to compliance infrastructure.
- Call Waiting:Subscriber-initiated flash-hook signaling for secondary call management persists in residential bundles. US cable operators bundle this feature indiscriminately, masking its standalone value.
- Voicemail:Network-based message storage competes poorly with smartphone-native visual voicemail. Japanese enterprises maintain centralized voicemail for regulatory compliance in financial services.
Local calling anchors the volume base while international calling loses share at the steepest rate.
Technology:
Cost tiers separate legacy copper maintenance from fiber-enabled packet migration, with capital intensity determining competitive entry barriers.
- PSTN:Circuit-switched time-division multiplexing over copper pairs operates at fixed 64 kbps channel rates. Germany's BNetzA decommissioning timelines force accelerated replacement cycles for incumbent maintenance budgets.
- VoIP:Packet-switched voice compression over IP networks enables variable bitrate codecs and service chaining. US FCC mandates for all-IP transitions are compressing migration timelines for rural exchange carriers.
- ISDN:Integrated Services Digital Network delivers 128 kbps bearer channels over copper. European manufacturing plants retain ISDN for legacy equipment telemetry and guaranteed latency.
- Analog:Plain old telephone service loops persist for lifeline subsidies and medical alert systems. US Universal Service Fund disbursements sustain analog infrastructure in high-cost service territories.
- Digital:Digital loop carrier systems multiplex analog signals for transport efficiency. Incumbent local exchange carriers face stranded asset risk as fiber overlays displace DLC-fed neighborhoods.
- PRI:Primary Rate Interface delivers 23 B-channels plus signaling over T1 spans. German automotive suppliers maintain PRI trunking for call center reliability and guaranteed service levels.
PSTN retains the widest installed base while VoIP climbs the fastest among greenfield deployments.
Application:
Customer type determines pricing power, with enterprise procurement consolidating around platform bundles while residential demand fragments across price-sensitive niches.
- Residential Communication:Household voice subscriptions bundle with broadband and video for retention pricing. US cable operators leverage landline security system integration to slow mobile-only migration.
- Enterprise Communication:Corporate voice services now consolidate with UCaaS platforms and contact center software. North American mid-market corporations prioritize single-source vendor accountability over best-of-breed trunking.
- Call Centers:High-volume inbound and outbound operations require guaranteed service levels and predictive dialer integration. Philippine BPO clusters sustain substantial PRI deployments for voice quality compliance.
- Public Institutions:Government agencies mandate E-911 location precision and recorded line retention. US state emergency operations centers maintain diverse carrier diversity for continuity planning.
- Educational Institutes:Universities deploy hybrid PSTN-VoIP infrastructure for administrative and dormitory services. Campus emergency notification systems require copper loop backup for power failure resilience.
Enterprise communication commands the highest ARPU concentration while residential communication spans the broadest subscriber base.
End User:
Volume scale inversely correlates with margin protection, with household churn accelerating and government procurement extending contract durations.
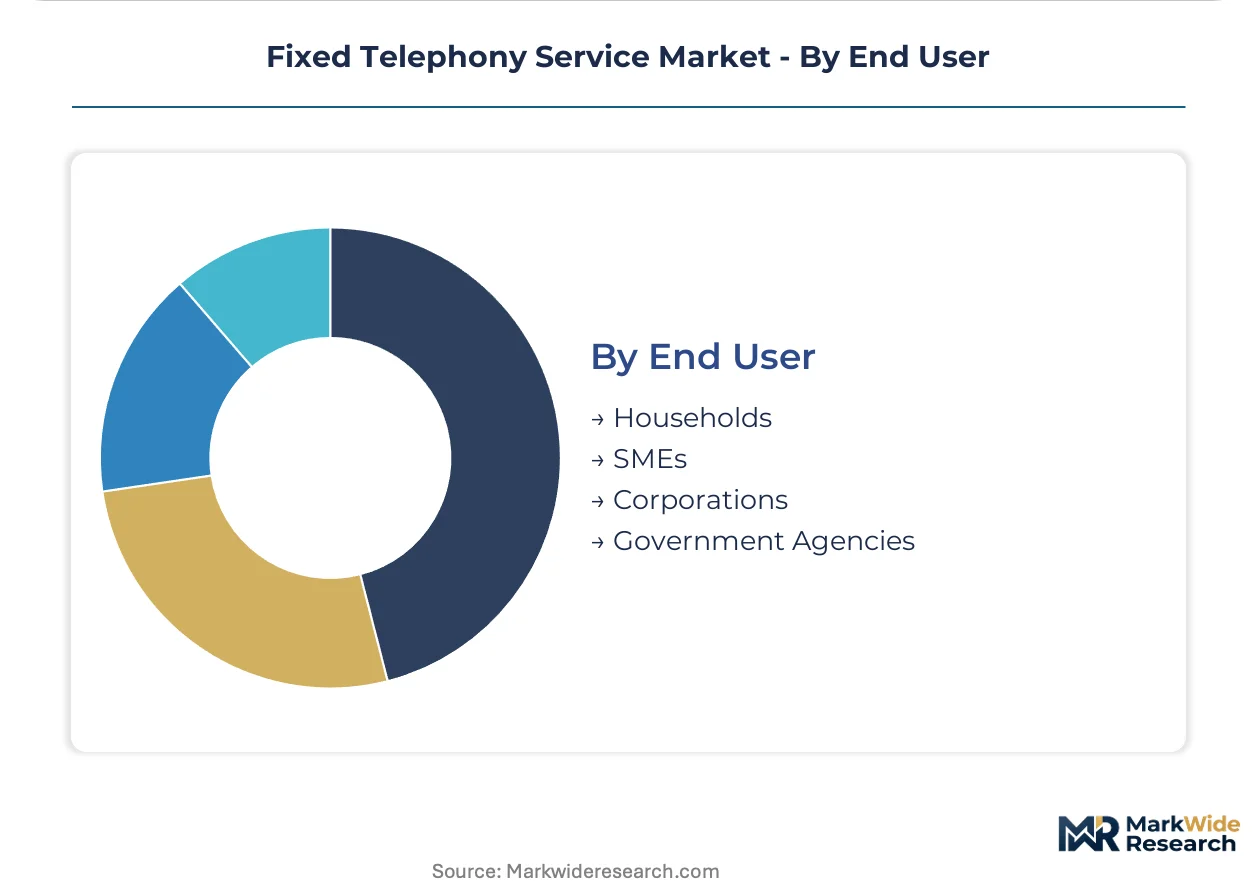
- Households:Consumer voice subscriptions face relentless mobile substitution pressure. Bundled landline security systems and elderly demographics sustain residual demand in US and Japanese markets.
- SMEs:Small and mid-sized enterprises accelerate PSTN exit for per-line cost reduction. Cloud-native UCaaS platforms capture migration demand with hybrid workforce tooling subscriptions.
- Corporations:Large enterprises maintain PRI trunking for call center reliability while staging VoIP transitions. IT procurement consolidates voice with collaboration and contact center platforms.
- Government Agencies:Public sector contracts prioritize continuity assurance and regulatory compliance over cost minimization. US federal requirements for recorded lines and secure facilities sustain premium pricing tiers.
Households represent the largest addressable population while SMEs generate the steepest platform migration velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fixed telephony service trade flows reflect divergent infrastructure replacement cycles, with capital equipment imports concentrating in markets accelerating copper decommissioning while legacy system exports persist from regions extending PSTN maintenance timelines.
United States
FCC mandates for IP-based network transitions and STIR/SHAKEN compliance drive carrier infrastructure replacement demand. The FCC's copper retirement notification rules impose structured decommissioning timelines on incumbent local exchange carriers. Rural exchange areas in the Midwest and Mountain West face acute transition pressure as low-density economics complicate fiber replacement business cases.
Germany
Industrial manufacturing clusters sustain substantial PRI trunking demand for mission-critical voice reliability and guaranteed service levels. BNetzA enforces number portability rules that reduce subscriber lock-in and intensify retail competition. Automotive suppliers in Baden-Württemberg maintain PRI deployments for call center quality compliance and legacy equipment telemetry.
Japan
Enterprises maintain centralized voicemail systems for regulatory compliance in financial services, sustaining network-based feature demand. METI guidelines shape telecommunications infrastructure investment priorities and universal service obligations. Tokyo-based financial institutions retain copper loop backup systems for power failure resilience in trading operations.
United Kingdom
BT's Openreach copper retirement program accelerates fiber overlay deployment across suburban and rural exchanges. Ofcom wholesale access obligations restructure incumbent pricing power through mandated network unbundling. London financial services clusters drive demand for recorded line retention and secure facility connectivity.
India
SMEs accelerate PSTN exit for per-line cost reduction, creating subscriber acquisition opportunities for VoIP platform providers. TRAI regulations govern interconnection charges and number portability frameworks. Bengaluru technology parks exhibit pronounced VoIP migration velocity as cloud-native UCaaS platforms capture hybrid workforce demand.
Fixed Telephony Service Market Competitive Landscape
On the supply side, the industry is consolidating around platform-centric providers that bundle voice connectivity with collaboration tooling, displacing standalone trunking specialists. Tier-1 carriers with fiber infrastructure coexist with cloud-native challengers delivering programmable APIs. Dominant competitive moves include UCaaS platform acquisitions and strategic partnerships embedding voice into enterprise software workflows.
Within the cloud-native tier, RingCentral and Nextiva exemplify platform-first positioning that decouples voice switching from physical infrastructure. Telnyx occupies a position anchoring developer-centric communications stacks through programmable voice API layers. These three entities represent the strategic archetype of infrastructure-agnostic providers leveraging global IP backbones to serve enterprise and software developer segments.
| Leading Market Players |
|---|
| Nextiva |
| Zoom Phone |
| RingCentral |
| Telnyx |
| Ooma |
| Vonage Business |
| Dialpad |
| Vistanet Telecommunications |
| 8x8 |
| Others |
Supply & Pricing Matrix
Overcapacity in legacy PSTN switching equipment across rural US exchange areas compresses vendor pricing power while accelerating fiber overlay procurement timelines. German industrial clusters absorb premium pricing for PRI trunking reliability, creating divergent supplier strategies across Atlantic markets.
Pricing Analysis
PSTN-to-VoIP generational pricing gaps stratify across premium, standard, and economy tiers, with circuit-switched trunking commanding 40-60% premiums over packet alternatives for guaranteed service levels. Subscription-based UCaaS platforms dominate enterprise procurement, while per-line transactional pricing persists in residential bundles. Price differentiation rests on fiber proximity and codec compression efficiency, with US cable operators squeezing margins through triple-play bundling. SMEs exhibit acute price sensitivity, whereas German automotive suppliers prioritize reliability over cost minimization.
Supply Chain Analysis
Tariff exposure between Chinese optical component suppliers and North American carrier equipment vendors dominates supply chain risk assessment for fiber transition programs. Manufacturing concentrates in China, Taiwan, and Germany for optical transceivers, session border controllers, and legacy switching chassis. Raw material dependencies span silicon photonics chips, copper cable stock, and specialized power supplies. Single-source vulnerability in programmable voice API platforms threatens carrier migration timelines. Distribution runs through Tier-1 systems integrators and direct carrier procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among North American mid-market corporations consolidating voice services with collaboration platforms, fragmenting standalone trunking vendor negotiating positions.
For Market Incumbents: Entrench fiber infrastructure ownership through accelerated copper retirement in high-density US metropolitan exchanges, capturing stranded asset value before FCC mandate deadlines. Defend enterprise PRI relationships by embedding guaranteed latency SLAs into manufacturing plant contracts, offsetting VoIP substitution threats from RingCentral and Telnyx. Vertical integration into cloud-native switching software reduces dependency on white-box server vendors. For New Entrants and Emerging Players: Rural US exchange areas present underpenetration white space where low-density economics deter incumbent fiber overlays, enabling fixed wireless VoIP bundles. Target Philippine BPO clusters for programmable voice API adoption, leveraging existing PRI infrastructure for hybrid migration paths. Partner with systems integrators serving German Mittelstand manufacturers for UCaaS platform embedding. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform providers with developer-centric API layers, suggesting superior cash flow quality versus hardware-dependent trunking specialists. Long-term viability favors infrastructure-agnostic software vendors over copper-dependent legacy operators. Monitor FCC copper retirement notification volumes as inflection indicator for replacement capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | RingCentral's UCaaS bundling decouples voice switching from physical copper loops. |
| Fiber Overlay Expansion | BT Openreach accelerates copper retirement across UK suburban exchange areas. |
| Programmable API Development | Telnyx extends global IP backbone to software developer communications stacks. |
| Wholesale Access Partnership | EU EECC directive opens alternative operator entry paths across European markets. |
| PRI Reliability Positioning | German automotive suppliers maintain circuit-switched trunks for call center quality compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of carrier regulatory filings, equipment vendor SEC disclosures, and national telecommunications regulator databases. Interviews with network operations executives at incumbent local exchange carriers, procurement leads at enterprise voice platforms, and systems integration specialists informed demand-side validation. Secondary sources encompass FCC copper retirement notifications, BNetzA infrastructure reports, EU EECC implementation guidance, and ITU traffic statistics. Bottom-up subscriber forecasts triangulate against top-down infrastructure replacement capital expenditure projections.
Forecast inputs span service type migration velocities, technology replacement cycles, application ARPU concentration, and end-user churn patterns across the projection horizon. Segmentation modeling incorporates deployment architecture, organization scale, vertical industry, geographic regulatory cluster, and integration complexity dimensions. CAGRs derive from subscriber base erosion rates in PSTN segments offset by VoIP platform expansion trajectories. Copper decommissioning timelines and STIR/SHAKEN compliance deadlines shape near-term equipment demand forecasting.
Practitioners should monitor FCC mandate acceleration, EU wholesale access pricing rulings, and German BNetzA portability enforcement for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
Communication Repeater Market
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Fixed-Line Communications Market
Telecommunications Infrastructure
Iraq Telecom Market
Telecommunications Infrastructure
Carrier Infrastructure in Telecom Applications Market
Telecommunications Infrastructure
Germany Telecom Towers Market
Telecommunications Infrastructure
China Telecom Towers Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
Philippines Telecom Towers Market
Telecommunications Infrastructure
Global Telecom Cable Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Panama Telecom Market