
 Nepal Telecom Market | 2026-2036
Nepal Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Nepal Telecom Market Outlook
Enterprise and government buyers are unwinding legacy voice-centric contracts as residential mobile data consumption accelerates. Nepal Telecom leverages its state-backed infrastructure to sustain dominance in rural tower deployment. WorldLink Communications anchors the fixed broadband segment through aggressive fiber-to-the-home expansion across the Kathmandu Valley. Ncell Axiata Limited competes on mobile money integration, differentiating its wallet services from state-backed alternatives.
Nepal telecom encompasses terrestrial and wireless communication services operating across microwave, fiber optic, and cellular radio frequency bands from 700 MHz to 3.5 GHz, primarily enabling voice, data transmission, and digital financial inclusion for a mountainous, landlocked economy. Mobile services generate the largest revenue pool while fiber optic deployment represents the fastest-growing infrastructure category as cable operators replace copper last-mile connections. Business customer segments command premium pricing due to service-level agreements, whereas residential demand concentrates on unlimited data bundles with over-the-top video consumption driving bandwidth requirements upward.
Nepal Telecommunications Authority sets interconnection tariffs and spectrum allocation frameworks, while the country's national telecommunications regulator enforces quality-of-service benchmarks that operators must meet for license renewal. The central bank, Nepal Rastra Bank, governs mobile financial services licensing, directly shaping how telecom operators expand payment platforms. Stakeholders must monitor spectrum auction timelines and rural infrastructure subsidy disbursements to anticipate competitive repositioning.

Market Dynamics
The Nepal Telecom Authority's 2022 Broadband Policy mandate for universal internet access by 2025 is compressing infrastructure deployment timelines while forcing operators to prioritize fiber over legacy copper networks. This regulatory pressure is redrawing competitive positioning between state-backed incumbents and private challengers.
Growth Catalysts
- Rural banking digitization:Microfinance institutions are expanding mobile platform service delivery, creating demand for reliable cellular coverage in previously underserved districts.
- Fiber optic infrastructure density:Kathmandu Valley corridor deployment exceeds other provinces, establishing a template for provincial replication.
- Spectrum allocation frameworks:Nepal Telecommunications Authority's interconnection tariff structures incentivize tower sharing agreements between operators.
Market Restraints
- Topographical input costs:Mountainous terrain elevates tower construction and backhaul fiber deployment expenses relative to flatland benchmarks.
- Single-supplier equipment risk:Core network hardware concentration among limited international vendors creates procurement vulnerability.
- Copper network stranded assets:Legacy last-mile infrastructure cannot support bandwidth requirements for over-the-top video consumption.
Strategic Opportunities
- Provincial underpenetration:Madhesh and Karnali provinces exhibit sub-30% broadband penetration, presenting greenfield deployment zones.
- Mobile money convergence:Nepal Rastra Bank licensing frameworks enable wallet integration with utility billing and agricultural payments.
- Enterprise service-level agreements:Business segments command premium pricing for guaranteed uptime, diverging from residential unlimited bundle economics.
Industry Challenges
- Radio frequency engineering scarcity:Microwave link planning and 3.5 GHz propagation modeling expertise remains concentrated in Kathmandu.
- Right-of-way negotiations:Municipal permitting for fiber trenching across multiple jurisdictions extends deployment timelines unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nepal Telecom Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Internet, Landline, Satellite Technology: 4G, 5G, Fiber Optic, VoIP Customer Type: Residential, Business, Government, Educational Deployment Model: On-Premises, Cloud, Hybrid, Managed |
| Companies Covered | United Telecom Limited, WorldLink Communications, Nepal Telecom, Classic Tech, FiberWorld Communications, Ncell Axiata Limited, Broadlink Communications, Subisu Cablenet, Smart Telecom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nepal Telecom Market Strategic Shifts
Fixed-mobile convergence is dissolving traditional service boundaries as operators bundle fiber-to-the-home with cellular family plans. This integration is reshaping how residential customers evaluate providers and how enterprises negotiate connectivity contracts.
Network function virtualization is bifurcating core infrastructure deployment strategies. Larger operators virtualize billing and subscriber management on commodity servers. Smaller competitors retain appliance-based systems due to capex constraints. This technology divergence is compressing vendor consolidation timelines as equipment suppliers face diverging customer roadmaps.
Nepal Telecommunications Authority's quality-of-service benchmarks are tightening license renewal criteria. Operators must demonstrate minimum uptime percentages and complaint resolution timelines. Mobile money wallet providers face the steepest compliance burden as financial inclusion mandates expand audit requirements.
Enterprise buyers are unbundling connectivity from managed services. Large Kathmandu Valley corporations now procure raw bandwidth separately from security and cloud access layers. This purchasing fragmentation is visible most acutely in the banking and hospitality verticals, where internal IT teams absorb functions previously outsourced to telecom operators.
Nepal Telecom Market Segmentation
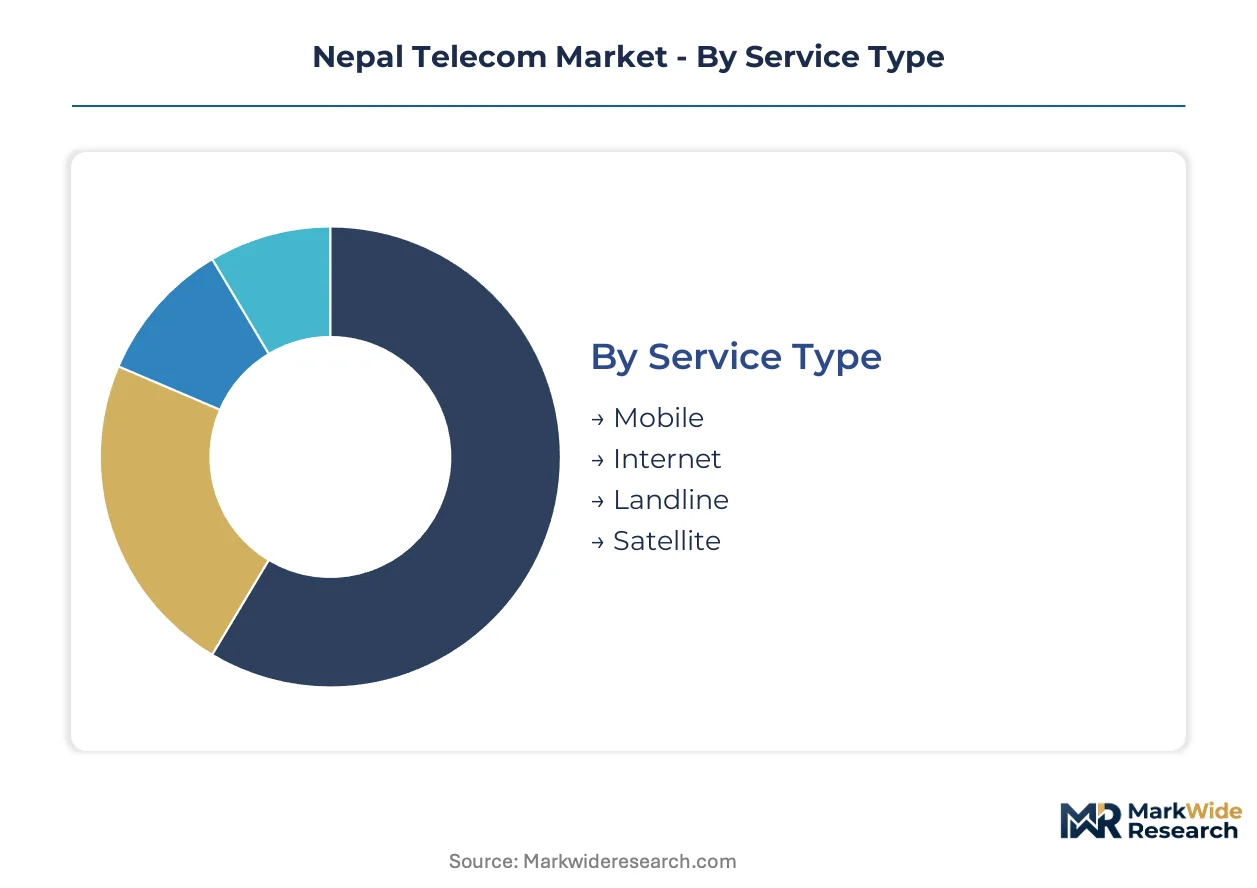
Segmentation reveals how Nepal Telecom Authority's 2022 Broadband Policy differentially shapes operator investment across service tiers and customer categories. Regulatory mandates for universal access by 2025 compress deployment timelines unevenly, creating distinct competitive dynamics within each segment cluster.
Service Type:
Nepal Telecommunications Authority's interconnection tariffs and spectrum allocation frameworks create divergent margin structures across voice and data services, with rural universal service obligations disproportionately burdening certain categories.
- Mobile:Cellular services operating across 700 MHz to 3.5 GHz bands enable voice and data transmission through terrestrial tower infrastructure. Demand concentrates in the Kathmandu Valley corridor where fiber backhaul density supports 4G capacity expansion; Nepal Rastra Bank's mobile financial services licensing directly amplifies wallet transaction volumes on these networks.
- Internet:Broadband connectivity delivered via fixed wireless and fiber-to-the-home architectures. WorldLink Communications anchors fixed broadband expansion across Kathmandu Valley municipalities; over-the-top video consumption drives residential bandwidth requirements upward while enterprise buyers unbundle raw bandwidth from managed service layers.
- Landline:Legacy copper-based voice services operating through Nepal Telecom's state-backed infrastructure. Copper network stranded assets cannot support modern bandwidth requirements.
- Satellite:Geostationary and low-earth orbit connectivity for mountainous terrain beyond terrestrial reach. Karnali Province districts rely on satellite where microwave backhaul proves economically unviable.
Mobile handles the majority of throughput; Internet is the fastest mover on share.
Technology:
Cost tier differentiation separates capital-intensive fiber deployment from spectrum-dependent wireless upgrades, with mountainous topography elevating total cost of ownership for physical infrastructure categories.
- 4G:LTE cellular networks providing mobile broadband through existing tower infrastructure. Nepal Telecom leverages state-backed rural tower deployment to sustain coverage dominance; spectrum allocation frameworks incentivize tower sharing agreements that reduce duplicate capital expenditure.
- 5G:Next-generation cellular technology requiring 3.5 GHz spectrum and dense small cell deployment. Kathmandu Valley municipalities represent the initial deployment zone due to population density and enterprise demand concentration.
- Fiber Optic:Glass-core transmission infrastructure replacing copper last-mile connections. Madhesh Province exhibits sub-30% broadband penetration, presenting greenfield deployment zones where trenching costs fall below Himalayan benchmarks.
- VoIP:Packet-switched voice services riding data networks, displacing circuit-switched alternatives. Business segments command premium pricing for service-level agreements guaranteeing uptime.
Fiber Optic absorbs the largest share of new capital deployment; 5G is climbing the fastest as spectrum auctions approach.
Customer Type:
Volume concentration varies sharply across customer categories, with government and educational procurement subject to public tender regulations that extend sales cycles while reducing margin volatility.
- Residential:Individual households purchasing unlimited data bundles and family mobile plans. Fixed-mobile convergence bundles reshape provider evaluation criteria as customers seek single-voice solutions.
- Business:Corporate entities procuring connectivity with guaranteed uptime and security layers. Large Kathmandu Valley banking and hospitality corporations now absorb functions previously outsourced to operators.
- Government:Public sector entities requiring compliant procurement through national tender processes. Universal internet access mandates direct subsidy flows toward rural government facility connectivity.
- Educational:Schools and universities demanding bandwidth for digital learning platforms. Broadband Policy targets directly elevate this segment's infrastructure priority.
Residential generates the highest connection count; Business delivers the steepest expansion trajectory in revenue per user.
Deployment Model:
Margin structure differentiates capital-heavy on-premises installations from recurring-revenue managed services, with hybrid architectures gaining traction among enterprises seeking workload flexibility.
- On-Premises:Customer-owned infrastructure requiring upfront capital expenditure and internal technical staffing. Mountainous terrain elevates equipment transport and installation costs relative to flatland deployments.
- Cloud:Fully outsourced infrastructure delivered as operational expenditure. Network function virtualization enables larger operators to virtualize subscriber management on commodity servers.
- Hybrid:Mixed architecture combining retained on-site equipment with cloud-hosted workloads. Enterprise buyers in Kathmandu Valley increasingly segment connectivity from security and cloud access layers.
- Managed:Operator-maintained infrastructure with service-level agreements covering maintenance and upgrade cycles. Quality-of-service benchmarks tighten license renewal criteria for providers offering this model.
Managed services capture the majority of enterprise value; Cloud is gaining share fastest among mid-market customers.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cross-border fiber optic links connecting Kathmandu to Bhairahawa and Birgunj trade corridors underwrite Nepal's telecom infrastructure role. These terrestrial routes anchor data transmission capacity for the landlocked economy. Mountainous topography dictates deployment patterns across provincial markets.
Kathmandu Valley
Enterprise data centers and banking headquarters concentrate mobile money transaction volumes. Nepal Telecommunications Authority's quality-of-service benchmarks enforce minimum uptime percentages for license renewal. Lalitpur and Kathmandu municipalities host dense fiber-to-the-home deployments exceeding other provinces.
Madhesh Province
Agricultural payment platforms and rural microfinance institutions drive cellular coverage expansion. Broadband Policy universal access mandates direct subsidy flows toward government facility connectivity. Janakpur and Birgunj industrial corridors exhibit sub-30% broadband penetration, presenting greenfield deployment zones.
Gandaki Province
Tourism-dependent hospitality verticals demand guaranteed bandwidth for international guest services. Nepal Rastra Bank licensing frameworks shape mobile wallet integration with utility billing. Pokhara's lakeside cluster anchors fixed wireless expansion where trenching costs exceed Himalayan benchmarks.
Lumbini Province
Buddhist pilgrimage circuits and border trade logistics require reliable cross-border connectivity. Interconnection tariff structures incentivize tower sharing agreements between operators. Bhairahawa's customs zone supports microwave backhaul density for terrestrial fiber extensions.
Karnali Province
Remote district administration and health post telemedicine create satellite-dependent demand pockets. Universal internet access mandates compress infrastructure deployment timelines in underserved areas. Jumla and Dolpa highland zones rely on geostationary links where terrestrial backhaul proves economically unviable.
Nepal Telecom Market Competitive Environment
Listed leaders compete with private specialists across infrastructure ownership models, creating a bifurcated market structure. State-backed incumbents leverage rural tower deployment concessions while private challengers concentrate fiber-to-the-home capacity in metropolitan corridors. Three archetypes dominate: integrated national operators, metropolitan fiber specialists, and mobile money wallet providers. Competitive moves center on tower sharing agreements and provincial license acquisitions.
Among integrated operators, Nepal Telecom exemplifies state-backed infrastructure leverage, while Ncell Axiata Limited occupies the private challenger position with mobile financial services differentiation. Metropolitan fiber expansion is anchored by WorldLink Communications, which represents the fixed broadband specialist archetype through Kathmandu Valley density concentration.
| Leading Market Players |
|---|
| United Telecom Limited |
| WorldLink Communications |
| Nepal Telecom |
| Classic Tech |
| FiberWorld Communications |
| Ncell Axiata Limited |
| Broadlink Communications |
| Subisu Cablenet |
| Smart Telecom |
| Others |
Value Chain & Pricing Dynamics
Fiber optic cable substitution for legacy copper last-mile infrastructure simultaneously concentrates procurement leverage among Chinese and Indian equipment vendors while compressing per-port pricing economics for residential broadband bundles. This input transition redistributes margin capture from installation labor toward optical transceiver and fiber cable suppliers, with Kathmandu Valley deployment density enabling volume-tier negotiations unavailable in Himalayan provinces.
Pricing Analysis
Volume-discount tiering structures separate enterprise service-level agreements from residential unlimited data bundles, with business segments commanding premium uptime guarantees while household pricing stratifies across premium, standard, and economy tiers based on bandwidth allocation and over-the-top video inclusion. Price differentiation rests on fiber backhaul availability and Nepal Telecommunications Authority quality-of-service certification tiers. Cost compression in the residential economy tier is intensifying because WorldLink Communications and Nepal Telecom are cross-subsidizing rural universal service obligations through metropolitan volume. Government and educational procurement exhibits lowest price sensitivity due to public tender compliance requirements, while microfinance institutions demonstrate highest sensitivity as they bundle connectivity into thin-margin digital payment services.
Supply Chain Analysis
Inbound logistics costs through Kolkata and Haldia ports constrain equipment delivery timelines for tower infrastructure and fiber optic cable, with container availability fluctuations rippling through Himalayan road corridors to Kathmandu distribution hubs. Hardware concentration draws from China for optical transport equipment, India for passive fiber components, and South Korea for radio frequency base stations. Single-source vulnerability sits with Huawei and ZTE core network gear subject to Nepal Telecommunications Authority spectrum licensing dependencies. Distribution runs through operator-direct procurement for large infrastructure builds and tiered distributor networks for customer-premises equipment across provincial markets.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates specialist opportunities as enterprise buyers unbundle connectivity from managed services, generating niche openings for security-layer and cloud-access pure-plays that incumbent integrated operators struggle to serve profitably.
For Market Incumbents: Consolidate tower sharing agreements with Ncell Axiata Limited and Smart Telecom to defray rural deployment costs mandated by Broadband Policy universal access obligations. Deepen backward integration into fiber cable manufacturing through Indian joint venture partnerships, reducing exposure to Chinese equipment vendor concentration and currency fluctuation. Prioritize Kathmandu Valley enterprise service-level agreement retention as banking and hospitality verticals absorb previously outsourced functions. For New Entrants and Emerging Players: Anchor in Madhesh Province's sub-30% broadband penetration zones where trenching costs fall below Himalayan benchmarks and agricultural payment platforms drive cellular coverage demand. Target Karnali Province satellite-to-fiber transition districts where Nepal Telecom's geostationary reliance creates latency-sensitive enterprise openings. Pursue Nepal Rastra Bank mobile financial services licensing as the primary go-to-market wedge, bundling wallet functionality with utility billing integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed metropolitan fiber specialists possessing Kathmandu Valley density but lacking provincial license coverage for long-haul expansion. Five-to-ten year viability hinges on Broadband Policy subsidy flow sustainability and spectrum auction timing clarity. Monitor Nepal Telecommunications Authority rural infrastructure subsidy disbursement schedules as the critical inflection signal for competitive repositioning capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Tower Sharing Agreement | Reduces duplicate capital expenditure across Nepal Telecom and Ncell Axiata Limited rural deployments. |
| Fiber-to-the-Home Expansion | WorldLink Communications anchors fixed broadband dominance through Kathmandu Valley density concentration. |
| Mobile Money Licensing | Nepal Rastra Bank frameworks enable Ncell Axiata Limited wallet differentiation from state-backed alternatives. |
| Provincial License Acquisition | Madhesh and Karnali greenfield zones offer first-mover advantage outside incumbent coverage footprints. |
| Network Function Virtualization | Larger operators commoditize subscriber management while smaller competitors retain appliance-based systems. |
Study Parameters
A standing panel of Nepal Telecommunications Authority regulatory officers, Nepal Rastra Bank digital payment specialists, rural microfinance institution technology heads, and Kathmandu Valley enterprise IT procurement managers provided ongoing calibration across the research cycle. Primary interview insights combined with secondary validation from Nepal Telecommunications Authority spectrum allocation records, Nepal Rastra Bank mobile financial services licensing databases, operator infrastructure disclosure filings, and provincial broadband penetration statistics. Bottom-up connection count modeling and top-down revenue triangulation cross-checked segmentation outputs.
Consistency checks validated volume and value outputs against Nepal Telecommunications Authority quality-of-service benchmark reports and operator license renewal disclosures across the projection horizon. The analytical framework modeled service type, technology tier, customer category, and deployment model dimensions alongside terrain-adjusted infrastructure cost differentials. CAGRs derived from historical connection growth trajectories, regulatory mandate compression effects, and mobile money transaction volume elasticity to digital payment adoption curves.
Decision-makers should treat outputs as directional under assumptions of Broadband Policy subsidy continuity and stable Nepal-India cross-border fiber capacity; material deviation would warrant model refresh. Forecasts reflect base-case infrastructure deployment timelines and interconnection tariff stability. Unforeseen Nepal Telecommunications Authority spectrum auction delays or Nepal Rastra Bank mobile wallet regulatory tightening would compress expansion trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Spain Telecom Towers Market
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
Latin America Telecom Tower Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
Japan Telecom Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
China Telecom Towers Market
Telecommunications Infrastructure
Philippines Telecom Towers Market
Telecommunications Infrastructure
Terrestrial Trunked Radio (TETRA) System Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Fixed Telephony Service Market