
 Asia Pacific Voice Over LTE Market | 2026-2036
Asia Pacific Voice Over LTE Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Voice Over LTE Market Insights
The Asia Pacific Voice Over LTE Market is recalibrating around a widening gap between premium carrier-grade deployments and commodity over-the-top voice services. Huawei Technologies Co., Ltd. anchors its position through deep R&D intensity in IMS core infrastructure, while Samsung Electronics Co., Ltd. competes via specialized chipset integration for device-side VoLTE enablement. China Mobile Ltd. dominates subscriber scale, leveraging its billion-plus user base to drive circuit-switched fallback displacement across provincial networks.
Voice Over LTE refers to the transmission of voice communications as packetized data over 4G LTE radio networks using the IP Multimedia Subsystem architecture, with QoS mechanisms ensuring sub-150 millisecond latency for conversational clarity. Its primary purpose is to replace legacy circuit-switched voice with spectrally efficient all-IP delivery while enabling simultaneous voice and broadband data sessions. Cloud-based deployment is pulling ahead fastest as operators shed capital-intensive on-premise switching, while IMS technology leads the protocol layer due to its native integration with evolved packet core networks and richer service enablement compared to basic VoIP overlays.
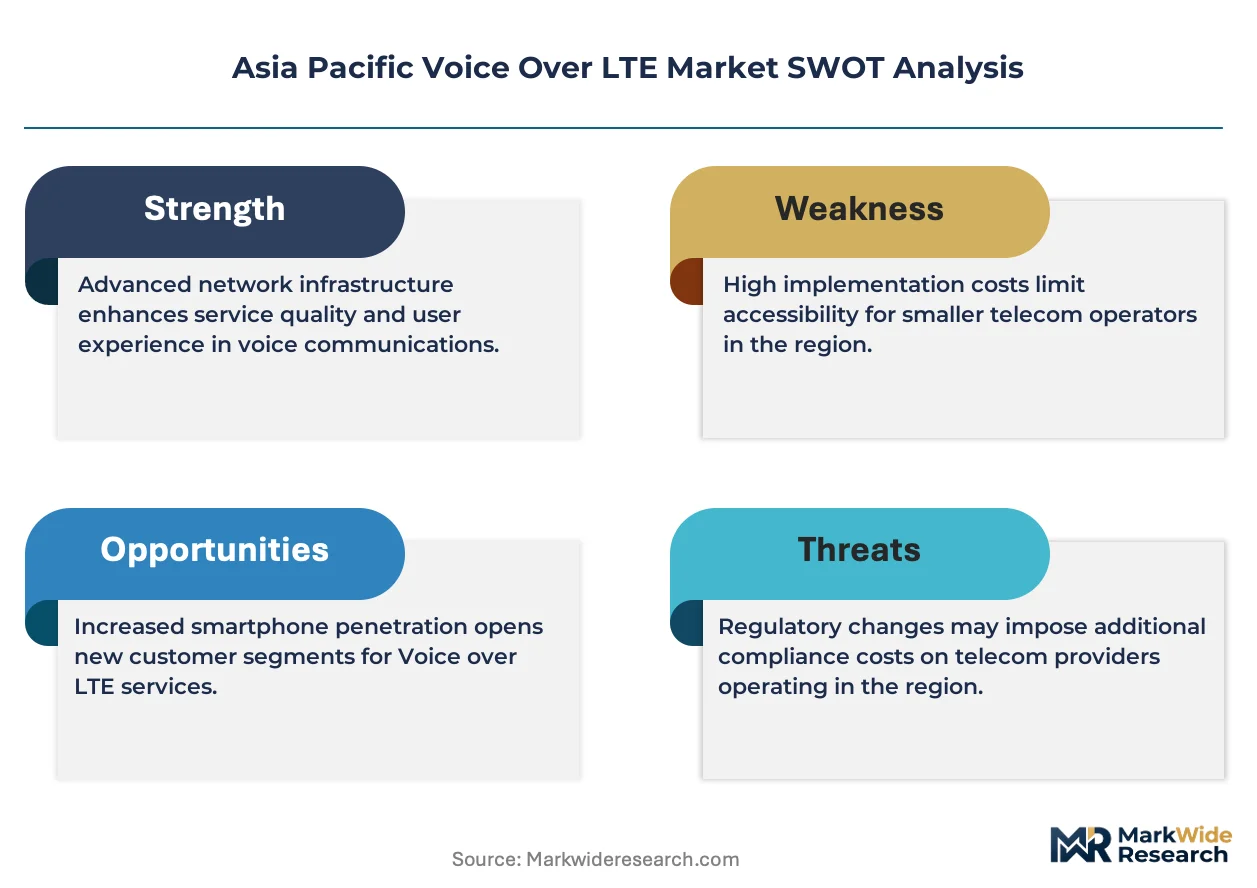
TRAI spectrum refarming directives in India, MIIT VoLTE interoperability mandates in China, and ARCEP quality-of-service requirements in France's Pacific territories collectively shape equipment certification timelines and operator rollout obligations across the region. South Korea's MSIT has accelerated 3G sunset clauses, forcing KT Corporation and SK Telecom Co., Ltd. to complete subscriber migrations or face license penalties. Stakeholders must weigh the capital trajectory of 5G voice against VoLTE refresh cycles as regulators tighten legacy network shutdown deadlines and enterprise buyers demand seamless handover between VoLTE and emerging NR voice standards.
Market Dynamics
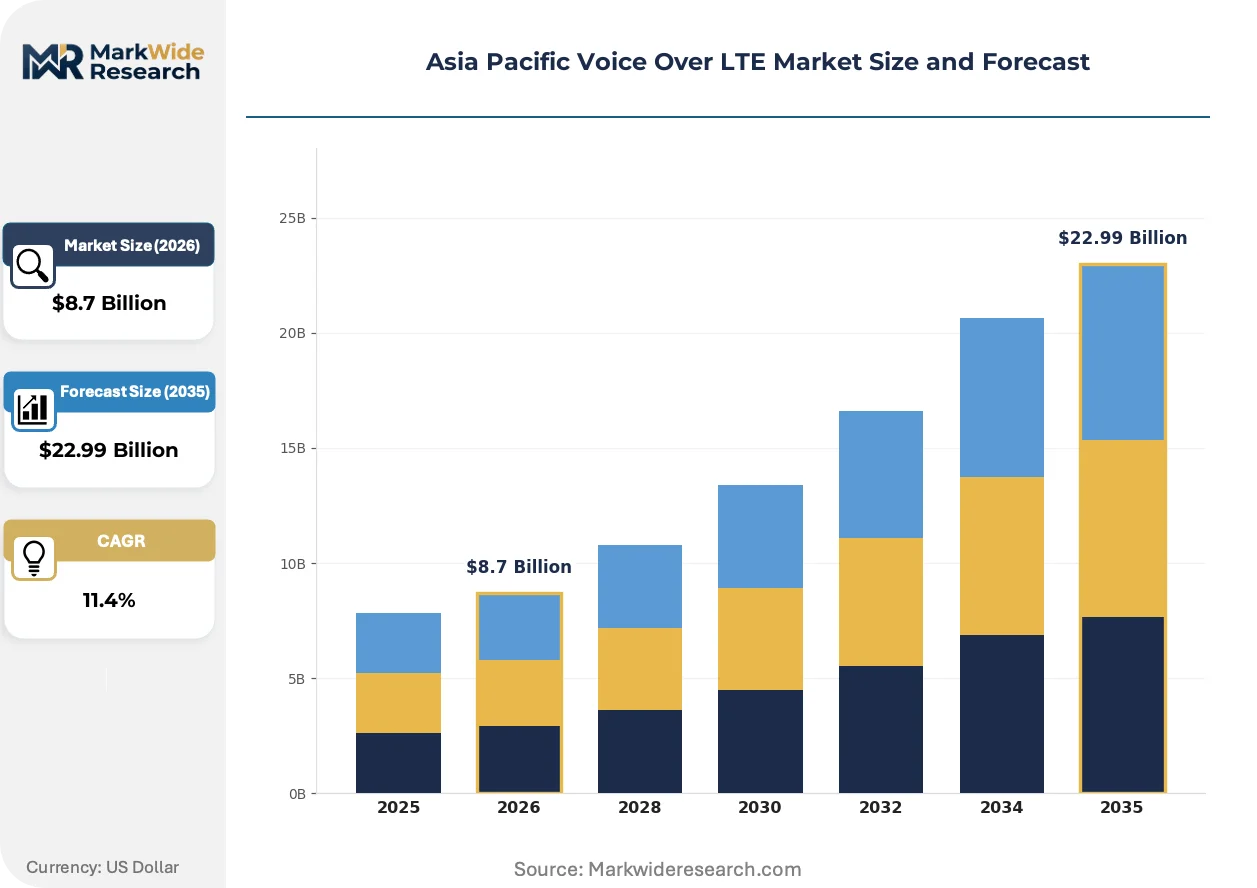
The Asia Pacific Voice Over LTE Market is being fundamentally restructured by regulatory-mandated 3G network sunsets, which are forcing carriers to accelerate packet-core voice migrations ahead of traditional depreciation cycles and creating compressed upgrade windows across Southeast Asian operator budgets.
Growth Catalysts
- TRAI spectrum refarming directives:India's telecom regulator is compelling operators to vacate 900MHz and 1800MHz bands for LTE redeployment, directly accelerating VoLTE core investments.
- Enterprise unified communications:South Korean and Japanese corporations are replacing legacy PBX systems with IMS-integrated VoLTE trunking for simultaneous voice-data sessions.
- Public safety network mandates:Mission-critical LTE deployments in Australia and New Zealand require carrier-grade voice QoS, driving specialized core infrastructure procurement.
Market Restraints
- IMS core capital intensity:Full IP Multimedia Subsystem deployment requires substantial upfront expenditure on session border controllers and diameter routing agents.
- Device ecosystem fragmentation:Low-cost handset manufacturers in Vietnam and Indonesia lag in VoLTE chipset integration, constraining subscriber migration velocity.
- Circuit-switched fallback dependency:Rural coverage gaps force operators to maintain dual-mode infrastructure, duplicating operational costs.
Strategic Opportunities
- Indonesia's archipelagic coverage gaps:Maritime and remote island enterprises represent underserved demand for satellite-backhauled VoLTE services.
- VoLTE-to-NR voice interworking:Early 5G standalone deployments in Japan and South Korea create first-mover advantage for seamless inter-RAT handover solutions.
- MIIT interoperability certification:China's streamlined type-approval processes for multi-band VoLTE devices lower barrier to entry for equipment vendors.
Industry Challenges
- IMS engineering talent scarcity:Operators across Thailand and Malaysia face acute shortages of SIP signaling specialists and core network architects.
- Legacy SS7 interconnection complexity:Maintaining signaling compatibility between packet voice cores and traditional PSTN gateways demands specialized protocol translation expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Voice Over LTE Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Private End User: Telecom Operators, Enterprises, Service Providers, Government Agencies Technology: VoIP, IMS, Circuit-Switched Fallback, LTE Advanced Application: VoIP Services, Video Calls, Messaging, Mobile Broadband |
| Companies Covered | China Mobile Ltd., Huawei Technologies Co., Ltd., SK Telecom Co., Ltd., NTT Docomo Inc., China Telecom, China Unicom, LG Uplus Corporation, KT Corporation, Samsung Electronics Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Voice Over LTE Market Trends and Innovations
VoLTE architecture is undergoing rapid virtualization as operators dismantle purpose-built hardware stacks, with software-defined IMS cores and cloud-native deployment models compressing both capital cycles and vendor lock-in structures across the region.
Cloud-native IMS cores are replacing appliance-based session border controllers and call session control functions. Tier-1 carriers in Japan and Australia are adopting containerized deployment for elastic scaling during peak traffic periods. This virtualization is converging with edge computing architectures to reduce latency for enterprise VoLTE services.
MIIT VoLTE interoperability mandates in China now require multi-carrier voice roaming certification before network access approval. Equipment vendors must demonstrate seamless handover between provincial operator cores. This regulatory tightening most affects multi-mode device manufacturers, who are consolidating certification testing into centralized Shanghai laboratories.
Enterprise procurement of VoLTE trunking is displacing traditional PRI and SIP trunking contracts in South Korea's manufacturing and financial sectors. Systems integrators are bundling IMS core access with managed SD-WAN services. This consolidation pattern is most visible in Seoul's Gangnam district enterprise clusters, where carrier-neutral data centers host multi-tenant voice infrastructure.
Asia Pacific Voice Over LTE Market Segmentation
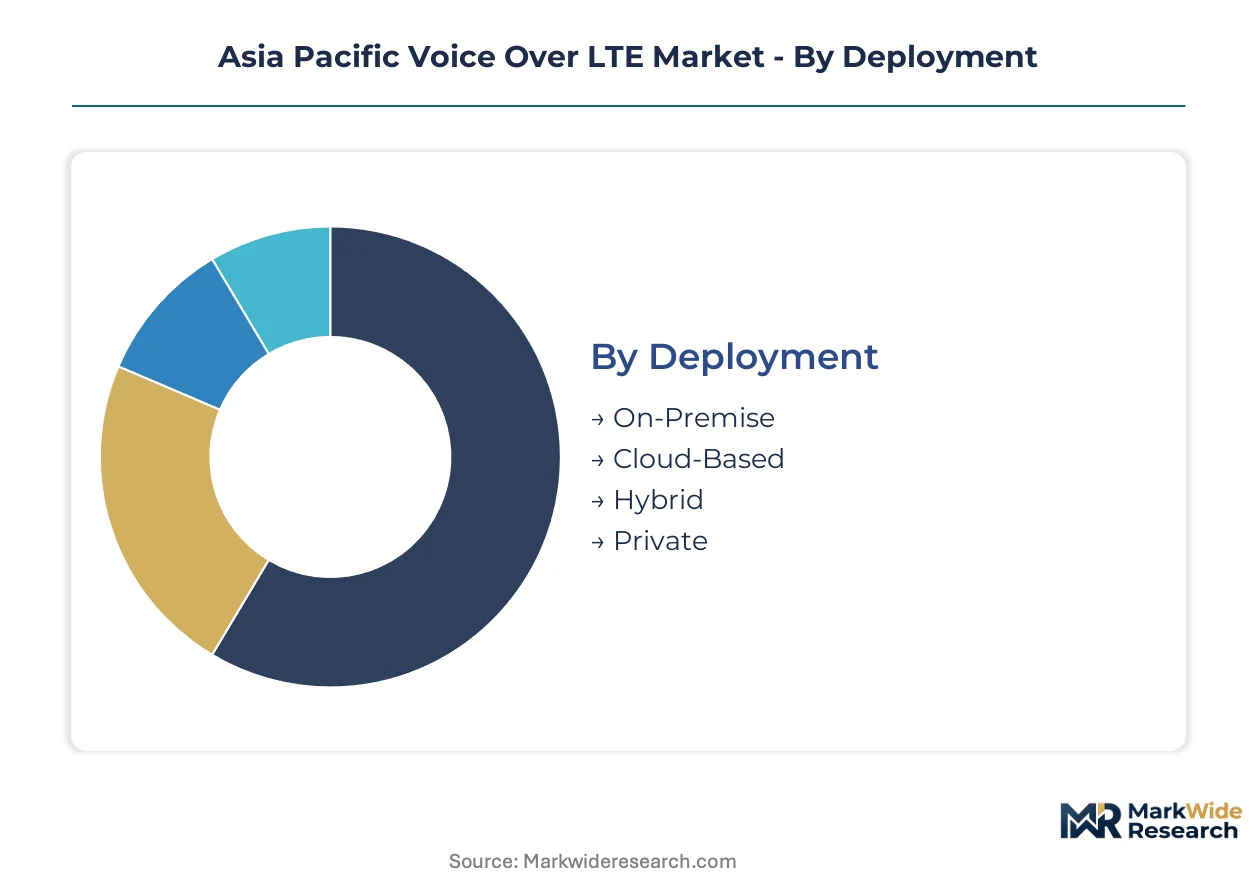
VoLTE procurement patterns diverge sharply across deployment models and buyer types, with regulatory certification timelines and spectrum efficiency mandates dictating which segments absorb capital first. Understanding these fracture lines reveals where equipment vendors must align product roadmaps with operator migration schedules.
Deployment:
MIIT type-approval requirements in China and TRAI infrastructure audits in India impose distinct certification burdens across deployment modes, with cloud-native architectures facing streamlined compliance pathways compared to legacy hardware stacks.
- Cloud-Based:Containerized IMS cores hosted on hyperscale infrastructure eliminate appliance certification cycles while enabling elastic scaling during provincial network peaks. South Korean carriers favor this model for enterprise VoLTE trunking in Seoul's Gangnam district clusters.
- On-Premise:Purpose-built session border controllers and call session control functions demand exhaustive MIIT interoperability testing before network access approval. Chinese provincial operators maintain these deployments for mission-critical voice QoS in public safety networks.
- Hybrid:Split architectures pair edge-resident media gateways with centralized signaling controllers, requiring dual certification tracks that prolong procurement timelines.
- Private:Captive LTE networks for mining and maritime operations in Indonesia's archipelago bypass public carrier certification but face specialized spectrum licensing from national regulators.
Cloud-Based sits at the top of the volume ranking, with Private climbing the fastest.
End User:
Capital allocation intensity varies dramatically across buyer categories, with government procurement cycles stretching 18-24 months while enterprise contracts consolidate through systems integrator bundling.
- Telecom Operators:Tier-1 carriers in Japan and South Korea drive standardization through volume commitments, forcing equipment vendors into multi-year IMS refresh roadmaps. KT Corporation and SK Telecom Co., Ltd. negotiate consolidated session border controller procurement across 3G sunset migration windows.
- Enterprises:Manufacturing and financial sectors in South Korea displace legacy PBX systems with IMS-integrated trunking, bundling voice infrastructure with managed SD-WAN services through carrier-neutral data centers.
- Service Providers:Over-the-top voice platforms and MVNOs purchase wholesale VoLTE access, concentrating procurement in Singapore and Hong Kong hub locations.
- Government Agencies:Mission-critical LTE deployments in Australia and New Zealand require specialized public safety certification, extending vendor qualification periods.
Telecom Operators command the largest procurement volumes, with Enterprises expanding most quickly.
Technology:
Protocol layer selection determines interoperability testing scope, with native IMS integration attracting streamlined MIIT approval compared to overlay VoIP implementations requiring additional validation.
- IMS:IP Multimedia Subsystem cores with native evolved packet core integration support richer service enablement and reduced certification friction. This architecture dominates carrier-grade deployments across China Mobile Ltd.'s provincial networks.
- VoIP:Basic packet voice overlays lack standardized QoS mechanisms, constraining adoption to low-latency-tolerant applications and extending approval timelines in regulated markets.
- Circuit-Switched Fallback:Dual-mode infrastructure maintains PSTN compatibility for rural coverage gaps, duplicating operational costs but preserving service continuity during migration.
- LTE Advanced:Carrier aggregation and enhanced MIMO capabilities support higher-definition voice codecs, requiring updated device certification from MIIT laboratories.
IMS holds the dominant volume position, with LTE Advanced gaining share fastest.
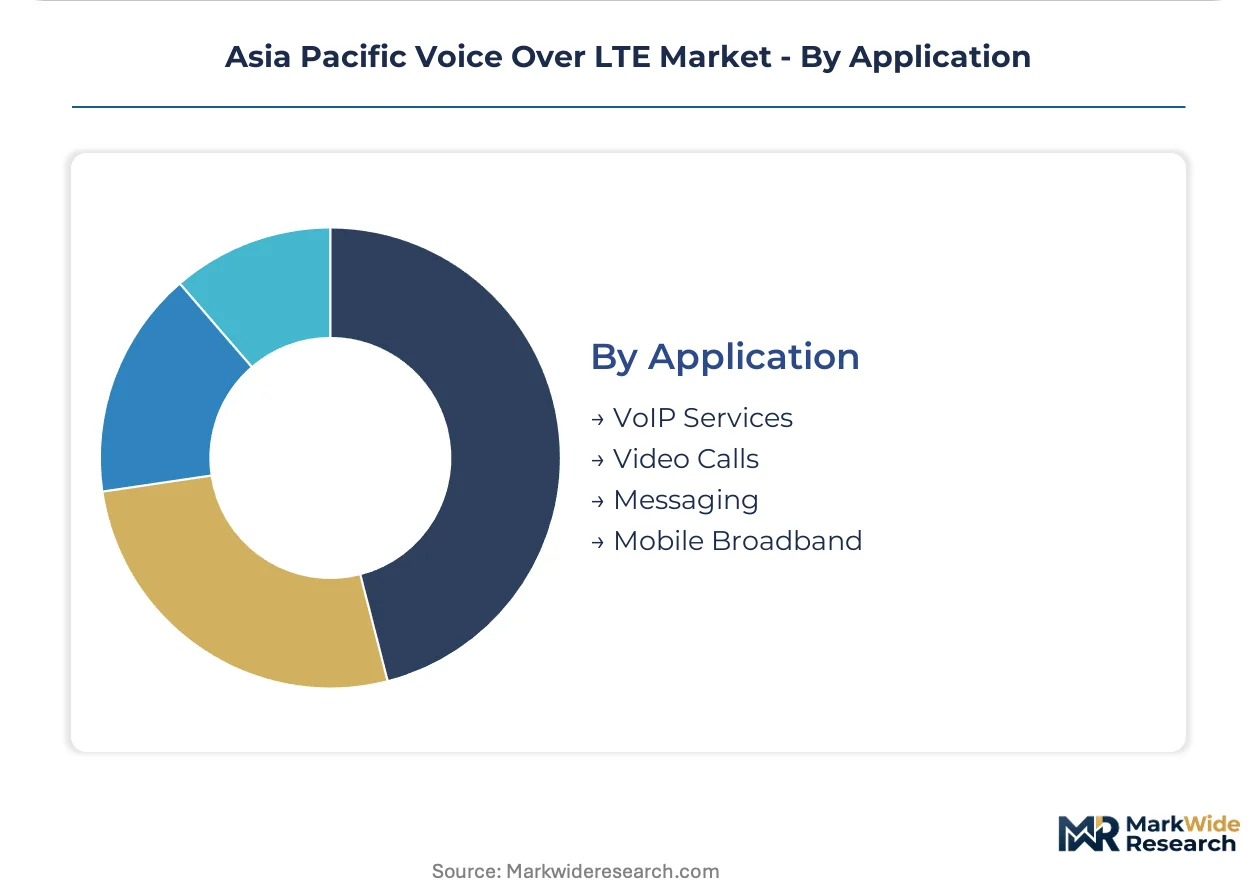
Application:
Service bundling patterns shape equipment specifications, with video-enabled VoLTE demanding enhanced media resource functions that extend core infrastructure certification requirements.
- VoIP Services:Packetized voice delivery with sub-150 millisecond latency targets concentrates procurement in urban corridors where fiber backhaul supports QoS enforcement.
- Video Calls:Simultaneous voice-data sessions require expanded media plane capacity, driving session border controller sizing in enterprise trunking deployments.
- Messaging:Rich Communication Services integration with IMS cores enables unified communications bundles, popular in Japanese corporate migrations.
- Mobile Broadband:Data-centric LTE usage with voice as secondary application dominates prepaid segments in Vietnam and Indonesia, constraining VoLTE chipset prioritization by low-cost manufacturers.
VoIP Services leads volume deployment, with Video Calls expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China Mobile Ltd. commands subscriber scale that dwarfs South Korea's combined carrier base, yet Seoul's enterprise corridor generates higher VoLTE trunking revenue per subscriber than any Chinese provincial network.
China
MIIT interoperability mandates compel multi-carrier voice roaming certification before network access approval, compressing equipment vendor timelines. Provincial operators under China Mobile Ltd. displace circuit-switched fallback across western regions where LTE coverage now exceeds 3G footprint. Shanghai laboratories consolidate certification testing for multi-mode device manufacturers seeking streamlined type-approval.
South Korea
MSIT accelerated 3G sunset clauses force KT Corporation and SK Telecom Co., Ltd. to complete subscriber migrations or face license penalties. Enterprise unified communications contracts in Seoul's Gangnam district clusters displace legacy PBX systems with IMS-integrated trunking bundled through carrier-neutral data centers. Manufacturing and financial sectors drive session border controller sizing for simultaneous voice-data sessions.
Japan
NTT Docomo Inc. extends VoLTE into public safety networks and enterprise unified communications as 5G standalone deployments create interworking complexity. METI guidelines shape equipment certification timelines for mission-critical LTE voice QoS. Osaka and Nagoya manufacturing corridors procure managed SD-WAN services with embedded IMS core access.
India
TRAI spectrum refarming directives compel operators to vacate 900MHz and 1800MHz bands for LTE redeployment, accelerating VoLTE core investments ahead of traditional depreciation cycles. Mumbai and Delhi-NCR carrier infrastructure faces compressed upgrade windows as 3G sunset deadlines tighten. Rural coverage gaps force maintenance of dual-mode infrastructure, duplicating operational costs.
Australia
Mission-critical LTE deployments require specialized public safety certification, extending vendor qualification periods for government agencies. Sydney and Melbourne enterprise clusters drive procurement of carrier-grade voice QoS infrastructure. Satellite-backhauled VoLTE services address coverage gaps in remote mining and maritime operations.
Asia Pacific Voice Over LTE Market Competitive Landscape
Top-tier vendors anchor carrier-grade IMS infrastructure, while mid-tier specialists compete on device-side chipset integration and enterprise trunking services. The market structure concentrates around three strategic archetypes: integrated telecom operators controlling end-to-end subscriber relationships, equipment vendors supplying session border controllers and call session control functions, and systems integrators bundling voice infrastructure with managed connectivity. Competitive moves center on multi-year IMS refresh roadmaps negotiated during 3G sunset migration windows, and geographic expansion into Indonesia's archipelagic coverage gaps.
Among Asia-Pacific headquartered operators, China Mobile Ltd., SK Telecom Co., Ltd., and NTT Docomo Inc. exemplify the scale-driven tier where subscriber volume dictates standardization timelines and equipment vendor consolidation. These carriers occupy positions that force multi-year commitment structures onto infrastructure suppliers, with provincial network scale in China and enterprise density in South Korea representing distinct demand archetypes that equipment vendors must simultaneously address.
| Leading Market Players |
|---|
| China Mobile Ltd. |
| Huawei Technologies Co., Ltd. |
| SK Telecom Co., Ltd. |
| NTT Docomo Inc. |
| China Telecom |
| China Unicom |
| LG Uplus Corporation |
| KT Corporation |
| Samsung Electronics Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Semiconductor wafer pricing indices cascade through IMS core equipment manufacturing, compressing margins for session border controller producers while amplifying bargaining power for cloud-native software vendors that decouple from silicon dependency.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for carrier-grade VoLTE infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-certified IMS cores from basic VoIP overlays and legacy circuit-switched fallback systems. Price differentiation stems from certification grade and volume scale, with provincial Chinese operators commanding discounts unavailable to Indonesian maritime enterprises. Pricing pressure intensifies as cloud-native vendors bypass appliance certification costs, forcing hardware incumbents toward managed service bundling. Enterprise buyers in Seoul's Gangnam district exhibit lowest price sensitivity, while Vietnamese MVNOs negotiate aggressively on per-subscriber licensing.
Supply Chain Analysis
IMS chipset supply rests on Taiwanese foundry capacity and South Korean memory fabrication. Session border controllers draw from Chinese PCB manufacturing, Japanese precision components, and Malaysian final assembly. Raw material dependencies include silicon wafers, high-frequency laminates, and specialized power management integrated circuits. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through carrier-direct procurement for tier-1 operators, systems integrator channels for enterprise trunking, and distributor networks for remote island deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific Voice Over LTE Market compounds steadily as regulatory-mandated 3G sunsets force carrier infrastructure refresh cycles regardless of macroeconomic conditions.
For Market Incumbents: Hedge against cloud-native displacement by accelerating software-defined IMS roadmaps while maintaining hardware certification relationships with MIIT and TRAI laboratories. Defensive consolidation should prioritize backward integration into session border controller silicon design to escape foundry pricing volatility. Threat vectors include hyperscale cloud vendors bundling voice infrastructure with compute contracts. For New Entrants and Emerging Players: Cloud marketplace routes offer lowest friction entry for satellite-backhauled VoLTE services targeting Indonesia's archipelagic coverage gaps. White-space concentrates in maritime enterprise segments and mission-critical public safety networks requiring specialized QoS certification. Systems integrator partnerships with Australian mining operators provide credible reference architecture pathways. For Investors and Strategic Acquirers: Asymmetric upside sits with containerized IMS core specialists possessing MIIT pre-certification and established China Mobile Ltd. provincial relationships. Long-term viability frames around 5G voice interworking capability as NR standalone deployments accelerate. Acquisition targets should demonstrate seamless VoLTE-to-NR handover engineering. The signal to watch is TRAI spectrum refarming timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native IMS Migration | Containerized cores enable elastic scaling during Seoul enterprise traffic peaks without appliance certification delays. |
| VoLTE-to-NR Voice Interworking | Seamless handover engineering captures early 5G standalone deployment premiums in Japan and South Korea. |
| MIIT Certification Pre-Approval | Streamlined type-approval accelerates multi-carrier roaming deployment across China Mobile Ltd. provincial networks. |
| Satellite Backhaul Integration | Specialized maritime and remote island coverage addresses Indonesia's archipelagic enterprise demand. |
| Enterprise SD-WAN Bundling | Carrier-neutral data center partnerships displace legacy PBX procurement in Gangnam district manufacturing clusters. |
Research Methodology
Coverage spans China, South Korea, Japan, India, and Southeast Asian archipelagic markets, with primary inputs from each. The approach combines structured interviews with IMS core network architects, carrier procurement officers, MIIT certification laboratory directors, and systems integrator technical leads with secondary validation from MIIT type-approval databases, TRAI spectrum auction records, carrier capex disclosures, and equipment vendor SEC filings. Bottom-up subscriber migration modeling triangulates against top-down infrastructure spend estimates.
Rate-of-change decomposition separates subscriber growth from ARPU compression and infrastructure refresh cycles across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user category, protocol layer technology, and application type, with additional granularity on regulatory certification tier. CAGRs derive from fitted S-curve adoption patterns anchored to 3G sunset deadlines. Industry-specific inputs include MIIT interoperability mandate compliance timelines and TRAI spectrum refarming auction schedules.
The model assumes a particular technology adoption path; alternative pathways for 5G NR voice standalone deployment would alter the outlook. Forecasts reflect assumptions around regulatory deadline adherence, equipment certification velocity, and enterprise migration willingness. Specific risk factors include IMS engineering talent scarcity in Thailand and Malaysia, and legacy SS7 interconnection complexity prolonging PSTN gateway maintenance. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Nigeria Telecom Tower Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Canada Telecom Towers Market
Telecommunications Infrastructure
5G Infrastructure Equipment Market
Telecommunications Infrastructure
Panama Telecom Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
Chile Telecom Tower Market
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Kenya Telecom Tower Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
UAE Telecom Towers Market