
 MCAD Software Market | 2026-2036
MCAD Software Market Size, Share, and Industry Trends Forecast 2026-2036
MCAD Software Market Analysis
Modular bundling of simulation, manufacturing, and analysis tools is restructuring how engineering teams evaluate total cost of ownership against standalone design licenses. Siemens NX leverages deep integration with PLM backends to anchor high-complexity aerospace workflows. SOLIDWORKS sustains broad mid-market penetration through reseller channel density. PTC Creo differentiates via parametric modeling heritage in industrial machinery segments.
Mechanical computer-aided design software encompasses parametric and direct modeling engines, finite element analysis solvers, and numerical control toolpath generators that translate geometric data into manufacturable instructions. The technology stack serves product development cycles from concept validation through production planning, with 3D CAD and PLM modules commanding the deepest enterprise commitments. Cloud-based and SaaS deployment architectures represent the fastest-expanding consumption layer, while on-premises installations retain dominance in defense-aerospace environments with stringent data sovereignty requirements. Simulation and analysis solutions capture premium pricing due to specialized solver licensing and compute-intensive workload profiles.
FDA 21 CFR Part 820 quality system regulations shape validation requirements for MCAD tools used in medical device design traceability. EASA certification standards and FAA airworthiness directives mandate digital thread integrity across European and North American aerospace supply chains. Stakeholders must monitor evolving CSRD disclosure obligations in Europe, where embodied carbon tracking demands tighter integration between design geometry and lifecycle assessment databases.
Market Dynamics
Cloud-native SaaS delivery architectures are compressing procurement cycles and fragmenting incumbent licensing power across aerospace and automotive engineering workflows. This structural shift forces vendors to rearchitect pricing models around consumption-based metering rather than perpetual seat licenses.
Growth Catalysts
- Digital twin mandates:EASA certification standards now require persistent digital thread documentation across European aerospace supply chains, forcing tier-one suppliers to upgrade MCAD infrastructure.
- CSRD disclosure obligations:The EU's Corporate Sustainability Reporting Directive demands embodied carbon tracking integrated directly into design geometry databases, pulling lifecycle assessment tools into core MCAD bundles.
- Generative design algorithms:Topology optimization engines embedded within parametric modeling suites are accelerating concept-to-prototype cycles for industrial machinery OEMs.
Market Restraints
- Defense data sovereignty requirements:On-premises installation mandates for classified aerospace programs in Germany, France, and the United States block cloud migration for 15-20% of addressable seat volume.
- Specialized solver licensing costs:Finite element analysis modules command 3-4x per-seat pricing versus base CAD licenses, creating procurement friction for mid-market engineering consultancies.
- Legacy PLM integration debt:Decades-old product lifecycle management backends at major automotive OEMs resist API modernization, delaying SaaS transition timelines.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for domestic aerospace and automotive component production are creating first-time MCAD demand among tier-two suppliers in Pune and Chennai industrial clusters.
- AI-assisted design validation:Machine learning models trained on simulation failure modes are converging with cloud MCAD platforms to automate mesh generation and results interpretation.
- Medical device traceability:FDA 21 CFR Part 820 quality system regulations are mandating design history file automation that links parametric geometry changes to risk management documentation.
Industry Challenges
- Multiphysics simulation talent scarcity:Shortages of engineers proficient in coupled thermal-structural-fluid analysis are extending project timelines for automotive thermal management system suppliers.
- Cross-platform interoperability gaps:Proprietary kernel differences between direct and parametric modeling engines force costly geometry translation and feature loss during supply chain handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MCAD Software Market |
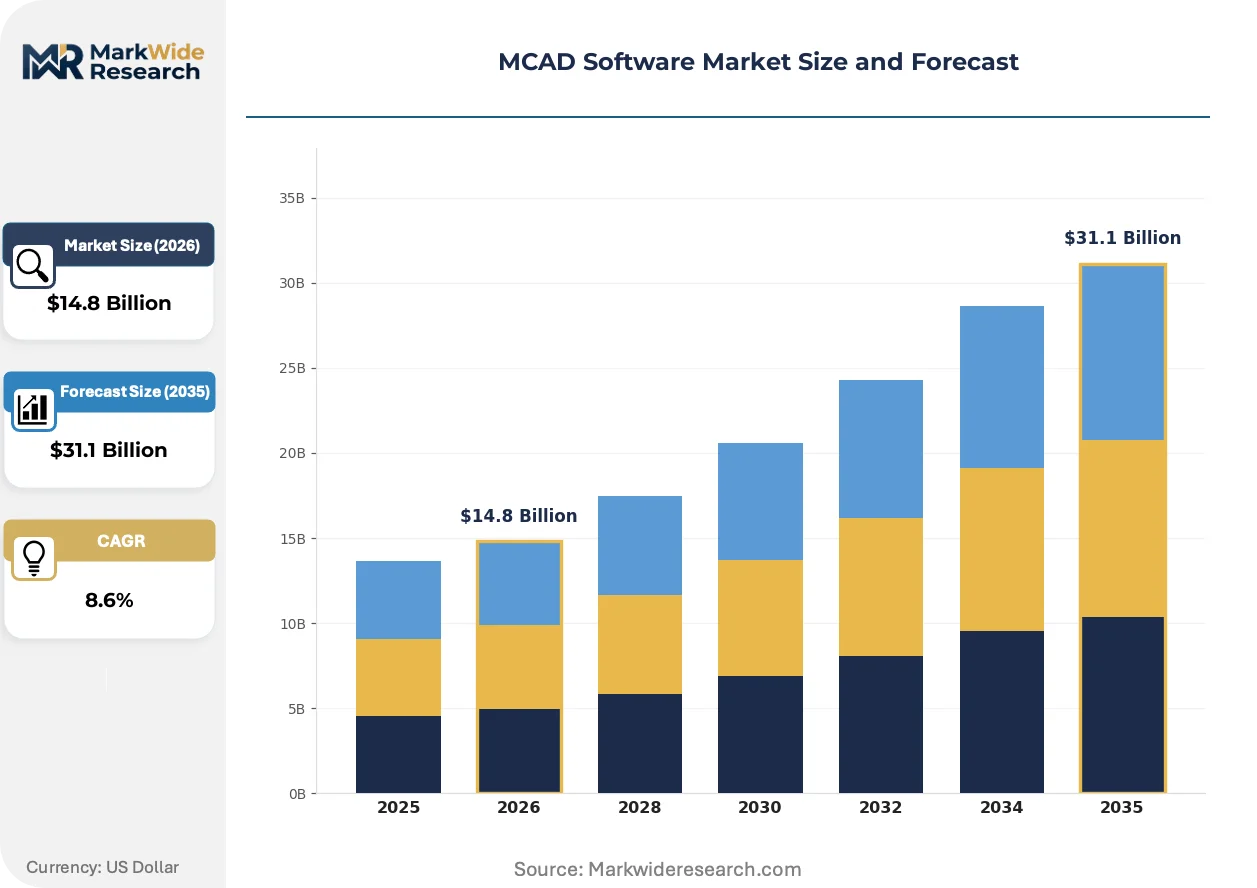
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D CAD, 3D CAD, CAM, PLM End User: Aerospace, Automotive OEMs, Consumer Electronics, Industrial Machinery Deployment: On-premises, Cloud-based, Hybrid, SaaS Solution: Design, Simulation, Manufacturing, Analysis |
| Companies Covered | Siemens Solid Edge, Siemens NX, SOLIDWORKS, Onshape, CATIA, Autodesk Fusion, PTC Creo, Designcenter NX, Autodesk Inventor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MCAD Software Market Emerging Trajectories
Computational infrastructure decentralization is redistributing engineering workloads from centralized data centers toward edge-deployed simulation nodes. This architectural migration is compressing latency for real-time collaboration while complicating vendor monetization strategies.
GPU-accelerated rendering engines are expanding into high-fidelity design review workflows previously dominated by CPU-bound visualization tools. Automotive styling studios in Germany and Japan are adopting these platforms to compress iterative feedback cycles with manufacturing engineering. Real-time ray tracing is expanding into supplier qualification processes, enabling non-specialists to validate surface quality without dedicated visualization hardware.
REACH substance restrictions and RoHS compliance deadlines are forcing material database updates within MCAD platforms to flag restricted substances during early design phases. Medical device manufacturers face the steepest adaptation curves as ECHA adds new SVHC candidates annually. The EU Green Deal's carbon border adjustment mechanism is pushing industrial machinery designers to prioritize steel and aluminum grades with verified environmental product declarations.
Subscription fatigue among mid-market engineering consultancies is fragmenting vendor loyalty as procurement teams evaluate modular point solutions against integrated suites. German automotive suppliers are unbundling simulation modules from core CAD licenses, purchasing solver capacity on hourly cloud metering instead. This consumption pattern shift is most visible among 50-200 seat engineering services firms in Baden-Württemberg and Bavaria manufacturing clusters.
MCAD Software Market Segmentation
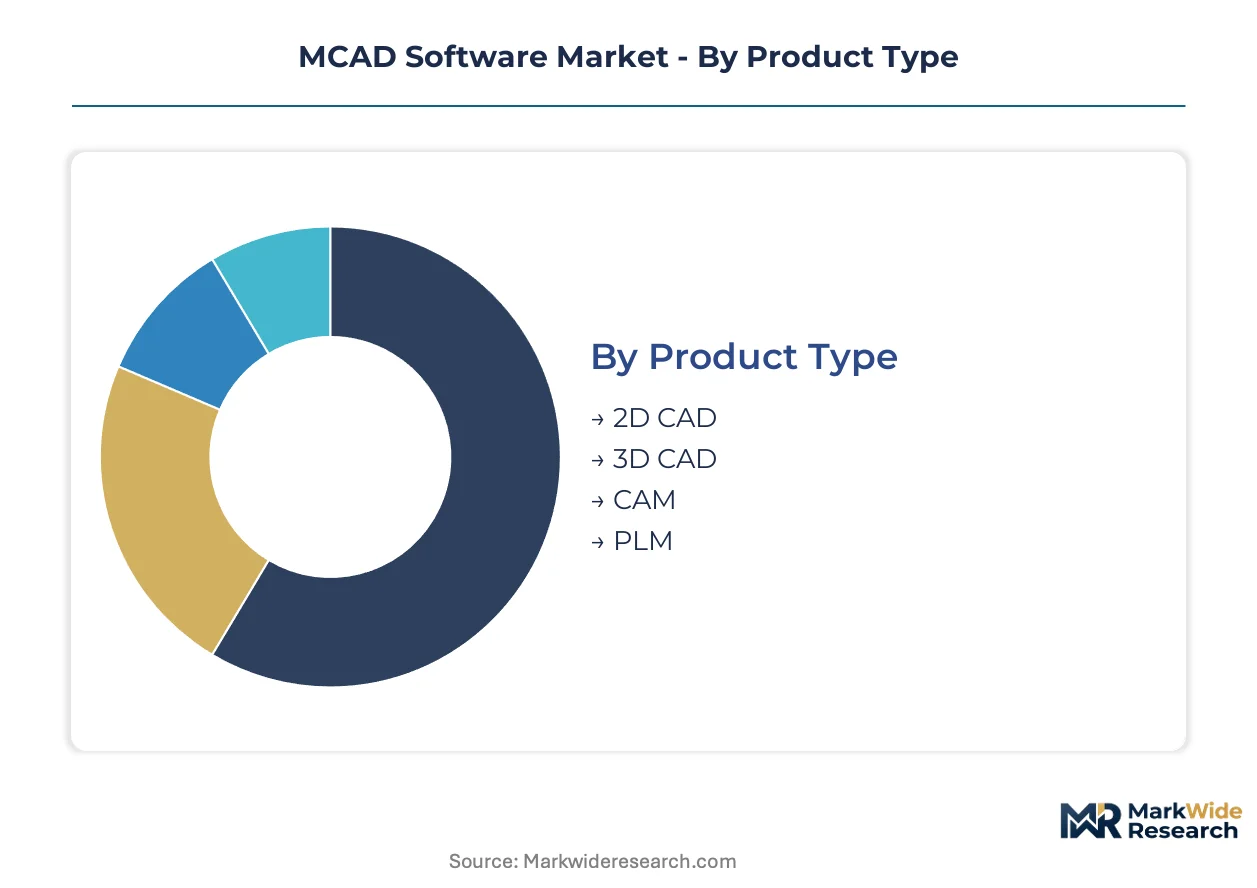
Segmentation in the MCAD Software Market reveals how procurement priorities diverge across engineering workflows. Upgrade cycles and replacement timelines vary sharply by deployment architecture and end-use regulatory exposure, forcing vendors to maintain parallel product roadmaps.
Product Type:
Upgrade cycles for established engineering teams now hinge on integration depth with adjacent manufacturing systems rather than standalone modeling improvements.
- 2D CAD:Legacy drafting tools persist in shop-floor documentation and electrical schematic workflows where 3D geometry adds no operational value. Maintenance contracts dominate revenue as aerospace suppliers in France and Germany delay full 3D migration for established airframe programs.
- 3D CAD:Parametric and direct modeling engines anchor product development cycles from concept through tooling release. Automotive OEMs in Japan and Germany are consolidating seat licenses around platforms with native PLM connectivity, compressing procurement evaluation timelines.
- CAM:Numerical control toolpath generators translate finished geometry into machine instructions for milling and additive processes.
- PLM:Product lifecycle management backends enforce version control and change propagation across distributed engineering teams.
Volume placements concentrate in 3D CAD; the faster expansion belongs to PLM as digital thread mandates deepen enterprise commitments.
End User:
Cost tier differentiation separates defense-aerospace programs with decade-long validation cycles from consumer electronics teams releasing quarterly hardware refreshes.
- Aerospace:EASA certification standards and FAA airworthiness directives mandate persistent digital thread documentation across tier-one supplier networks. Design traceability requirements in Germany, France, and the United States perpetuate on-premises infrastructure despite cloud migration pressure elsewhere.
- Automotive OEMs:Styling studios and manufacturing engineering groups share surface data through GPU-accelerated visualization platforms. German suppliers in Baden-Württemberg are unbundling simulation modules from core CAD licenses, purchasing solver capacity on hourly cloud metering instead.
- Consumer Electronics:Rapid prototyping demands favor subscription-based access with minimal upfront capital commitment.
- Industrial Machinery:Generative design algorithms embedded within parametric suites accelerate concept-to-prototype cycles for specialized equipment manufacturers.
Revenue concentration sits with Automotive OEMs; the steepest expansion trajectory belongs to Aerospace as digital twin mandates proliferate.
Deployment:
Application criticality determines whether engineering teams accept cloud latency trade-offs or maintain captive compute infrastructure.
- On-premises:Classified aerospace programs in Germany, France, and the United States enforce data sovereignty through physical infrastructure control. Defense contractors absorb higher total cost of ownership to satisfy national security regulations blocking external data residency.
- Cloud-based:Distributed rendering and simulation workloads exploit elastic compute scaling without capital expenditure. Japanese automotive styling studios compress iterative feedback cycles by provisioning GPU clusters on demand.
- Hybrid:Sensitive geometry remains local while collaboration layers sync through encrypted cloud gateways.
- SaaS:Browser-based modeling environments reduce IT overhead for mid-market engineering consultancies with limited technical staff.
Seat volume still favors On-premises installations; SaaS is climbing the fastest as procurement teams prioritize operational expenditure structures.
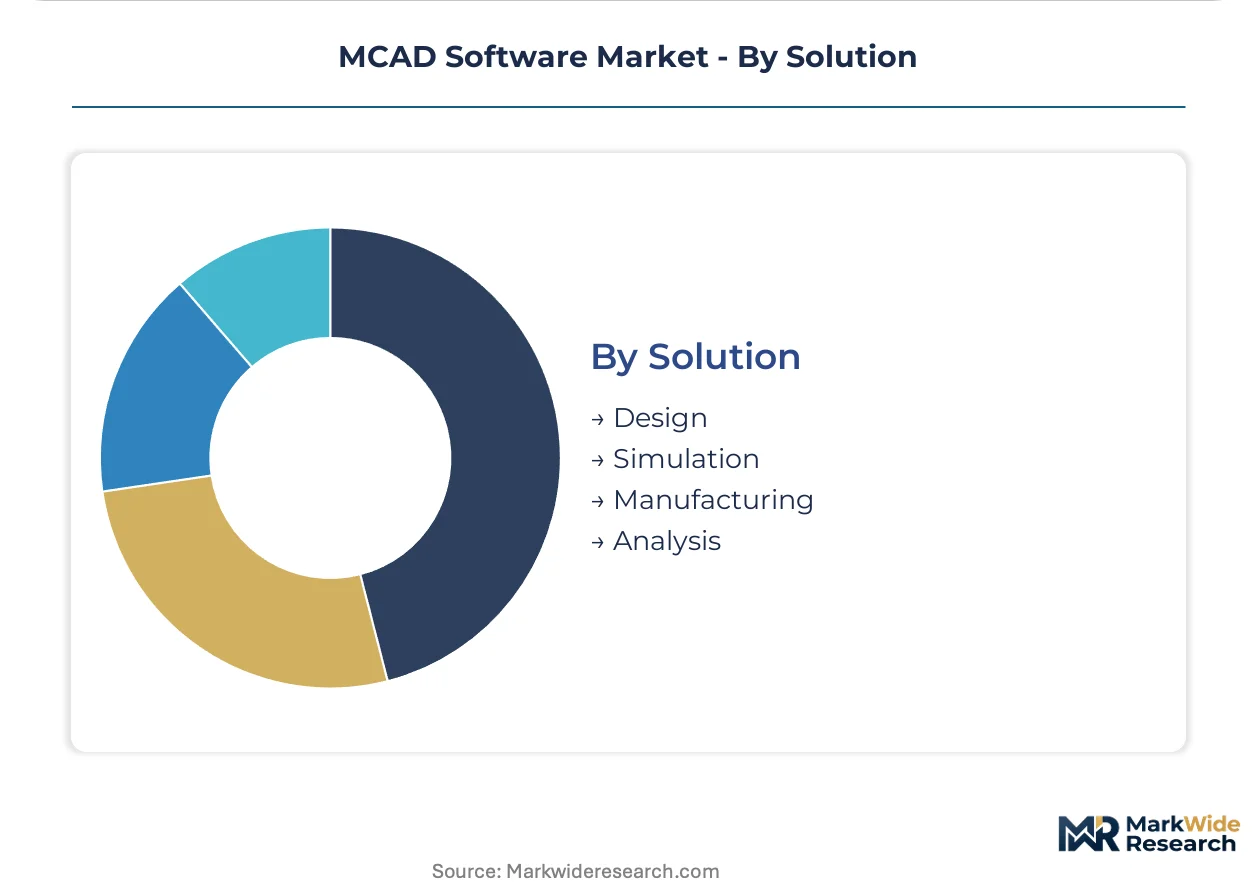
Solution:
Margin structures vary dramatically across the workflow stack, with specialized solvers commanding premium pricing against commodity design licenses.
- Design:Parametric and direct modeling kernels form the entry point for engineering software procurement. Mid-market penetration depends on reseller channel density and training ecosystem breadth.
- Simulation:Finite element analysis modules with coupled thermal-structural-fluid capabilities address multiphysics challenges in automotive thermal management. Talent scarcity for complex solver configuration extends project timelines and supports premium pricing.
- Manufacturing:Toolpath optimization and additive process planning bridge design intent with physical production.
- Analysis:Lifecycle assessment databases integrate with design geometry to satisfy CSRD disclosure obligations for embodied carbon tracking.
License revenue concentrates in Design; Simulation is gaining share fastest as engineering teams integrate validation earlier in development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of MCAD software concentrates heavily in the United States and Germany, while consumption spreads across manufacturing hubs in Japan, China, and India where aerospace and automotive OEMs drive seat license demand.
United States
FAA airworthiness directives and defense data sovereignty requirements sustain on-premises infrastructure demand across aerospace supply chains. The FDA's 21 CFR Part 820 quality system regulations mandate design history file automation for medical device manufacturers. Aerospace clusters in Seattle and Los Angeles anchor tier-one supplier networks upgrading digital thread capabilities.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria are unbundling simulation modules from core CAD licenses, purchasing solver capacity on hourly cloud metering instead. EASA certification standards enforce persistent digital thread documentation across European aerospace supply chains. Industrial machinery manufacturers in Stuttgart and Munich industrial clusters embed generative design algorithms within parametric modeling suites.
Japan
METI industrial policy promotes digital twin adoption across automotive and machinery sectors, accelerating cloud migration timelines. JIS standards govern interoperability requirements for MCAD platforms serving precision manufacturing supply chains. Automotive styling studios in Toyota City and Yokohama provision GPU clusters on demand for real-time rendering workflows.
China
MIIT smart manufacturing initiatives drive MCAD procurement among domestic automotive and industrial equipment producers seeking import substitution. GB standards and dual carbon goals pressure designers to integrate lifecycle assessment databases with geometry modeling. Aerospace manufacturing clusters in Xi'an and Chengdu expand digital twin deployments despite data localization requirements.
India
PLI scheme incentives for domestic aerospace and automotive component production create first-time MCAD demand among tier-two suppliers. BIS certification requirements shape validation protocols for engineering software used in critical infrastructure projects. Manufacturing clusters in Pune and Chennai industrial corridors upgrade from 2D drafting tools to full 3D parametric suites.
MCAD Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across multiple pricing tiers. The vendor base organizes around three strategic archetypes: integrated PLM-CAD suites with deep enterprise backends, mid-market platforms emphasizing channel density and training ecosystems, and cloud-native entrants exploiting consumption-based metering. Dominant competitive moves include portfolio diversification into adjacent simulation and manufacturing modules, and strategic partnerships with hyperscale cloud providers to anchor SaaS delivery architectures.
Within the integrated suite tier, Siemens NX and CATIA exemplify vendors anchoring high-complexity aerospace and automotive workflows through deep PLM backend integration. SOLIDWORKS occupies a distinct position in mid-market penetration, sustained by reseller channel density and broad training ecosystem accessibility. Cloud-native specialists include Onshape, which represents the browser-based delivery model reducing IT overhead for distributed engineering teams.
| Leading Market Players |
|---|
| Siemens Solid Edge |
| Siemens NX |
| SOLIDWORKS |
| Onshape |
| CATIA |
| Autodesk Fusion |
| PTC Creo |
| Designcenter NX |
| Autodesk Inventor |
| Others |
Supply Flow & Price Mechanics
Cloud compute spot pricing indices cascade through SaaS delivery models into three-tier subscription structures that stratify aerospace, automotive, and mid-market engineering consultancies by integration depth and solver licensing tiers.
Pricing Analysis
Cost-down pressure on perpetual seat licenses accelerates as German automotive suppliers in Baden-Württemberg unbundle simulation modules from core CAD packages. Pricing stratifies across premium, standard, and economy tiers anchored by PLM integration depth, FEA solver sophistication, and cloud rendering capacity. Certification-grade validation tools for FDA 21 CFR Part 820 and EASA digital thread mandates command 3-4x base license premiums. Mid-market engineering services firms with 50-200 seats exhibit highest price sensitivity, while defense-aerospace contractors absorb elevated TCO for data sovereignty compliance.
Supply Chain Analysis
Freight costs for GPU server clusters and edge compute nodes factor marginally into total procurement economics compared to licensing and integration services. Software production concentrates in the United States, Germany, and Japan, with development anchored in Seattle, Munich, and Tokyo metropolitan clusters. Distribution runs through hyperscale cloud provider marketplaces and specialized reseller networks serving vertical engineering workflows. Single-source vulnerability in PLM backend APIs at major automotive OEMs creates integration debt that delays SaaS transition timelines and fragments vendor switching costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Browser-native modeling environments are displacing on-premises installations across mid-market segments, compressing procurement cycles and forcing legacy vendors to rearchitect delivery architectures around consumption-based metering.
For Market Incumbents: Deepen PLM backend integration to anchor high-complexity aerospace workflows against cloud-native entrants exploiting hourly solver metering. Fortify reseller channel density in industrial machinery segments where parametric modeling heritage sustains switching costs. Counter subscription fatigue among German engineering consultancies by unbundling simulation capacity into granular consumption tiers.
For New Entrants and Emerging Players: Tier-two automotive suppliers in Pune and Chennai industrial clusters represent underserved buyer archetypes with first-time 3D parametric demand and limited legacy PLM integration debt. Target medical device manufacturers facing FDA 21 CFR Part 820 automation mandates with design history file solutions that link geometry changes to risk documentation. Pursue partnership routes with Indian PLI scheme beneficiaries seeking rapid capability buildout without capital-intensive perpetual licensing.
For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native specialists with established SaaS metering infrastructure in North American and European markets where procurement teams prioritize operational expenditure structures. Monitor EASA certification standard evolution as inflection signal for digital thread infrastructure upgrade cycles across European aerospace supply chains. Long-term viability hinges on solver talent acquisition and hyperscale cloud provider alliance depth.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native PLM connectivity anchors high-complexity aerospace workflows at tier-one suppliers. |
| Strategic Partnership | Hyperscale cloud alliances enable GPU-accelerated rendering for Japanese automotive styling studios. |
| Product Launch | Browser-based modeling environments reduce IT overhead for distributed engineering teams. |
| Acquisition of Specialist Firm | Multiphysics solver capabilities address talent scarcity in automotive thermal management. |
| Geographic Expansion | PLI scheme alignment captures first-time demand among Indian tier-two suppliers. |
Methodological Framework
SEC filings, EASA certification documentation, and hyperscaler capex disclosures formed the secondary backbone for vendor revenue segmentation and deployment architecture trends. Primary interviews with CTOs at aerospace OEMs, IT procurement officers at automotive suppliers, platform engineers at cloud-native entrants, and channel partners in German industrial clusters validated secondary findings. Bottom-up seat license enumeration across deployment models combined with top-down vendor revenue reconciliation to establish market sizing.
Historical trendline analysis across perpetual, subscription, and consumption-based revenue streams informed projection frameworks over the analysis window. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical regulatory exposure, PLM integration complexity, and regional cloud adoption pattern. CAGRs derived from elasticity-adjusted growth curves incorporating CSRD disclosure obligation timelines and PLI scheme incentive phases.
Revisions become necessary when EASA or FAA regulatory mandates accelerate, hyperscale cloud pricing architectures shift, or defense data sovereignty requirements expand to additional jurisdictions. Forecasts reflect documented assumptions about SaaS migration velocity and solver licensing unbundling patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
In-Memory Data Grids Software Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Product Analytics Software Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Global Contract Lifecycle Management Software Market
Software & Services
Lead Scoring Software Market
Software & Services
CAD Modeling Software Market
Software & Services
Global Website Builder Software Market
Software & Services
Global Recreation Management Software Market
Software & Services
Application Server Market
Software & Services
Predictive Dialer Software Market
Software & Services
Global Offshore Software Development Market
Software & Services
Quality Management Software Market
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Neurodiverse Workforce Productivity Tools Market