
 North America Automotive Software Market | 2026-2036
North America Automotive Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Software Market Analytics
Software-defined vehicle architecture is fragmenting legacy tiered supply relationships into direct OEM-platform partnerships. NVIDIA Corp anchors high-performance compute stacks for autonomous perception pipelines. BlackBerry Ltd specializes in embedded security kernels that harden vehicle-to-cloud interfaces. Microsoft extends Azure-based connected services that compete with native OEM cloud investments.
North America automotive software encompasses operating systems, middleware, application layers, and cloud-native services that govern powertrain control, infotainment rendering, and sensor fusion across heterogeneous electronic control units. These codebases execute on multi-core SoCs with deterministic real-time constraints, ISO 26262 functional-safety certification, and AUTOSAR adaptive platform compliance to ensure fail-operational behavior in production vehicles. Embedded Software dominates current bill-of-materials allocation due to legacy ECU proliferation, while Cloud-Based Solutions capture expanding margin pools as automakers pursue recurring revenue from subscription feature activation. Machine Learning applications within the technology dimension are displacing rule-based algorithms in advanced driver assistance, though Blockchain deployments remain confined to supply-chain traceability pilots rather than in-vehicle workloads.
NHTSA Federal Motor Vehicle Safety Standards and EPA greenhouse gas regulations are mandating software-verifiable compliance for crash avoidance and emissions optimization, forcing OEMs to architect traceable codebases with audit-ready documentation. The U.S. Department of Transportation's automated vehicle policy framework and Canada's Motor Vehicle Safety Act create dual-jurisdiction certification complexity for cross-border platform deployments. Stakeholders must monitor how NHTSA rulemaking on automated driving system safety assessment interacts with emerging state-level insurance liability frameworks to determine platform investment sequencing.
Market Dynamics
Software-defined vehicle architecture is collapsing the traditional tiered supply chain into direct OEM-platform partnerships, forcing semiconductor vendors and cloud providers to renegotiate their commercial relationships with Detroit and Silicon Valley automakers.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standards:Mandates for crash-avoidance software verification are compelling OEMs to architect traceable codebases with audit-ready documentation, expanding embedded security budgets.
- EPA greenhouse gas regulations:Emissions optimization protocols require real-time powertrain software calibration, accelerating over-the-air update infrastructure deployment across production fleets.
- Silicon Valley tech cluster concentration:Machine learning talent density in California's Bay Area is attracting autonomous perception R&D investment from established automakers and venture-backed startups alike.
Market Restraints
- ISO 26262 functional-safety certification costs:Multi-year validation timelines for deterministic real-time operating systems inflate development budgets and compress margin pools for mid-tier suppliers.
- Cross-border platform complexity:Divergent U.S. Department of Transportation automated vehicle policy and Canada's Motor Vehicle Safety Act create dual-jurisdiction certification friction for unified North American deployments.
- Legacy ECU hardware fragmentation:Heterogeneous electronic control unit architectures from disparate vendors constrain software stack portability and inflate integration testing overhead.
Strategic Opportunities
- Subscription feature activation:Cloud-native service monetization through over-the-air capability unlocking represents recurring revenue white space beyond traditional vehicle sale economics.
- Michigan's Detroit-Warren corridor:Proximity to OEM headquarters and tier-one engineering centers positions embedded software vendors for co-development partnerships on next-generation powertrain control.
- Sensor fusion convergence:Integration of lidar point-cloud processing with camera-based perception networks is opening architecture design wins for middleware specialists.
Industry Challenges
- AUTOSAR adaptive platform expertise scarcity:Shortage of engineers proficient in POSIX-based automotive operating systems is inflating recruitment costs and extending platform migration timelines.
- Deterministic real-time constraint verification:Validating fail-operational behavior across multi-core SoCs requires specialized hardware-in-the-loop testing infrastructure that strains capital allocation.
- Vehicle-to-cloud interface hardening:Cybersecurity kernel certification against evolving threat vectors demands continuous security patch cycles that conflict with automotive-grade stability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Software Market |
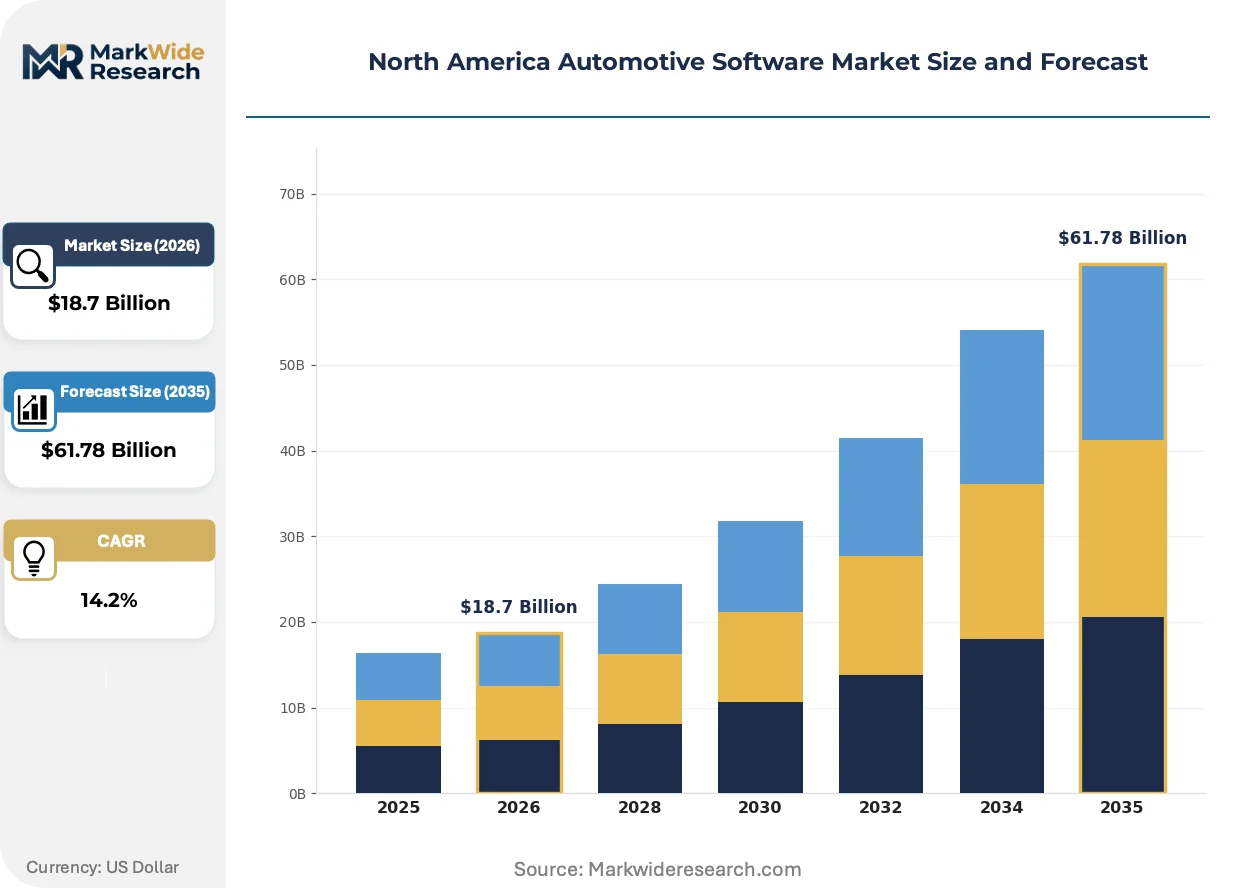
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Software, Cloud-Based Solutions, Infotainment Systems, Vehicle Control Software Application: Autonomous Driving, Fleet Management, Driver Assistance, Telematics End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Technology: Machine Learning, Blockchain, IoT, Big Data |
| Companies Covered | COX Automotive Inc., CDK Global, The Reynolds and Reynolds Company, Aptiv PLC, BlackBerry Ltd, NVIDIA Corp, Microsoft, Wind River, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Software Market Evolving Landscape
Deterministic real-time constraints are giving way to adaptive computing models, while regulatory pressure on emissions traceability and safety verification is rewriting how code ships to production vehicles.
End-to-end neural networks for autonomous perception are rendering obsolete rule-based computer vision algorithms that previously dominated advanced driver assistance systems. Tier-one suppliers and OEM internal teams are retraining engineering organizations around PyTorch and TensorRT workflows. The structural compression of algorithm development cycles is favoring cloud-native development environments over legacy embedded toolchains.
NHTSA rulemaking on automated driving system safety assessment is mandating simulation-validated performance documentation before public road deployment. OEMs must submit disengagement data and scenario coverage matrices that demonstrate behavioral predictability across edge cases. The compliance burden falls heaviest on full self-driving platform developers operating in California and Arizona testing corridors.
Fleet operators and commercial vehicle buyers are unbundling software maintenance from hardware procurement, negotiating multi-year service agreements separate from chassis acquisition. This consumption-pattern shift is pressuring traditional dealership networks that historically captured after-sales margin through parts and labor. The transformation is most visible in heavy-duty trucking segments operating across interstate corridors where uptime guarantees determine contract awards.
North America Automotive Software Market Segmentation
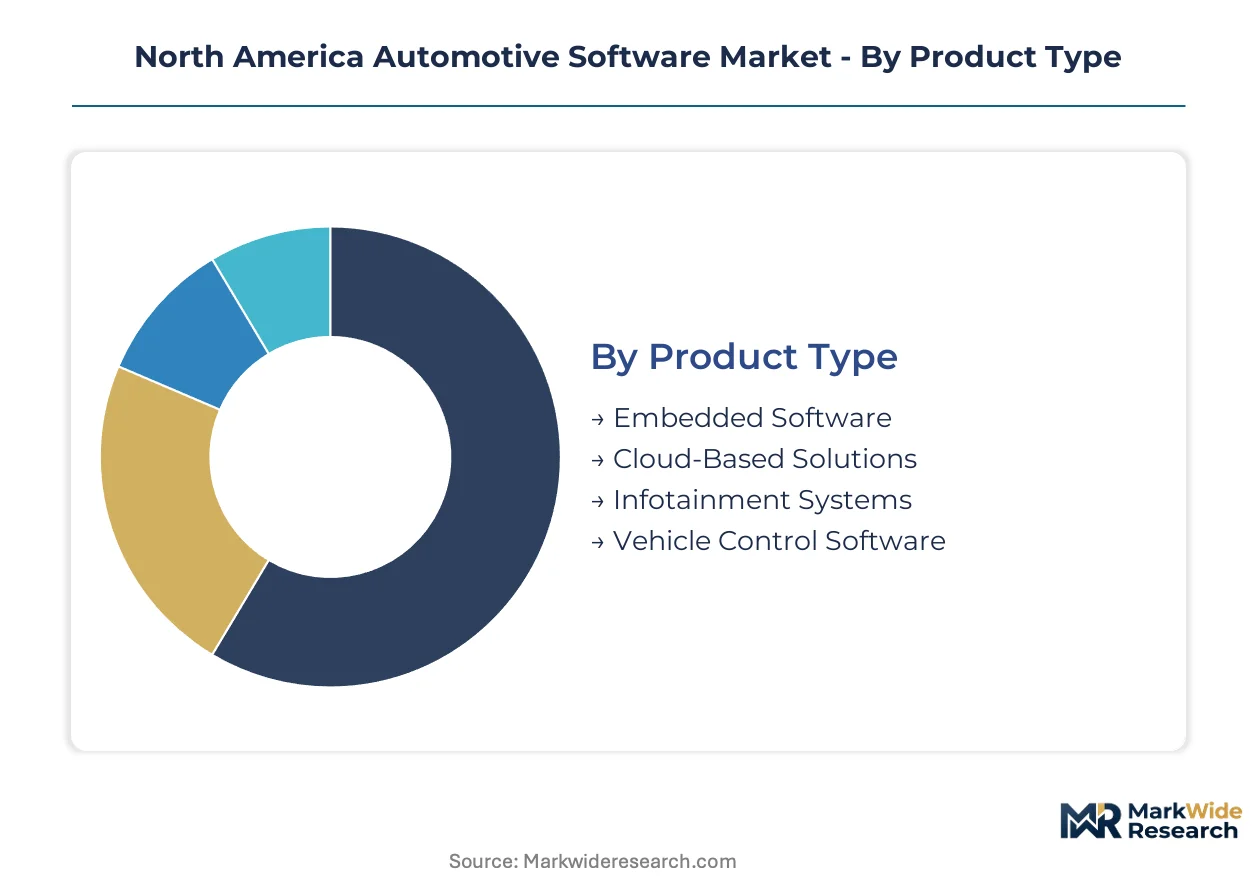
Software monetization in North America hinges on segment-specific service intensity. Embedded systems demand multi-year validation cycles, while cloud architectures unlock recurring revenue through over-the-air feature activation. Each segment carries distinct margin profiles and certification burdens that reshape supplier-OEM contracting terms.
Product Type:
After-sales service intensity varies sharply across product categories, with embedded systems requiring decade-long maintenance commitments versus cloud solutions that monetize through continuous subscription renewals.
- Embedded Software:Deterministic real-time operating systems execute powertrain and chassis control functions on multi-core SoCs with ISO 26262 ASIL-D certification requirements. Demand concentrates in Michigan's Detroit-Warren corridor where OEM engineering centers co-locate validation facilities for fail-operational behavior verification. NHTSA crash-avoidance mandates are extending code audit documentation obligations across production fleets.
- Cloud-Based Solutions:Over-the-air update infrastructure and remote diagnostics platforms operate on containerized microservices architectures with vehicle-to-cloud API gateways. California's Silicon Valley tech cluster anchors development talent pools for these recurring-revenue architectures. EPA emissions calibration protocols are accelerating deployment timelines as OEMs pursue subscription-based feature unlocking.
- Infotainment Systems:In-vehicle experience platforms integrate third-party app ecosystems with head-unit rendering pipelines and voice recognition middleware.
- Vehicle Control Software:Domain controllers for braking, steering, and suspension coordination require deterministic latency guarantees under AUTOSAR adaptive compliance.
Embedded Software holds the largest share; momentum sits with Cloud-Based Solutions.
Application:
Cost tier differentiation separates development budgets, with autonomous driving platforms absorbing tenfold engineering spend per vehicle versus telematics modules that scale across entire fleets.
- Autonomous Driving:End-to-end neural networks for perception and path planning execute on NVIDIA DRIVE or Qualcomm Snapdragon Ride compute fabrics with redundant sensor fusion pipelines. Arizona and California testing corridors host validation fleets submitting disengagement data to NHTSA safety assessment frameworks. Deterministic real-time constraints in safety-critical decision loops inflate hardware-in-the-loop testing infrastructure requirements.
- Fleet Management:Commercial vehicle uptime optimization platforms integrate predictive maintenance algorithms with route efficiency analytics for interstate trucking operators. Midwest logistics hubs spanning Illinois and Ohio anchor demand concentration where per-mile operating cost reduction determines contract awards. Uptime guarantees are unbundling software service agreements from chassis procurement.
- Driver Assistance:Lane-keeping and adaptive cruise control systems deploy rule-based and machine-learning algorithms across mid-range vehicle segments.
- Telematics:Usage-based insurance and stolen vehicle recovery services leverage cellular connectivity modules with embedded security kernels.
Driver Assistance commands current volume leadership; Autonomous Driving represents the steepest expansion trajectory.
End User:
Volume concentration patterns favor direct OEM relationships, though aftermarket channels are capturing expanding margin pools as vehicle owners seek post-warranty feature upgrades.
- OEMs:Detroit Three and transplanted automakers architect vertically integrated software stacks or direct platform partnerships with semiconductor vendors. Michigan and California engineering centers co-develop operating systems and middleware with tier-one suppliers. NHTSA Federal Motor Vehicle Safety Standards mandate traceable codebases with audit-ready documentation for production authorization.
- Tier-1 Suppliers:Bosch, Continental, and Denso deliver pre-integrated ECU software bundles to OEM assembly plants with validated functional-safety certification packages.
- Aftermarket Providers:Third-party infotainment upgrades and diagnostic tool vendors serve vehicle owners outside warranty coverage.
- Dealerships:Franchise networks capture software maintenance revenue through authorized service bay access and OEM-mandated update procedures.
OEMs retain dominant procurement volume; aftermarket channels are gaining share fastest.
Technology:
Supply concentration in machine learning frameworks is displacing legacy algorithm development, while blockchain deployments remain confined to pilot programs rather than production workloads.
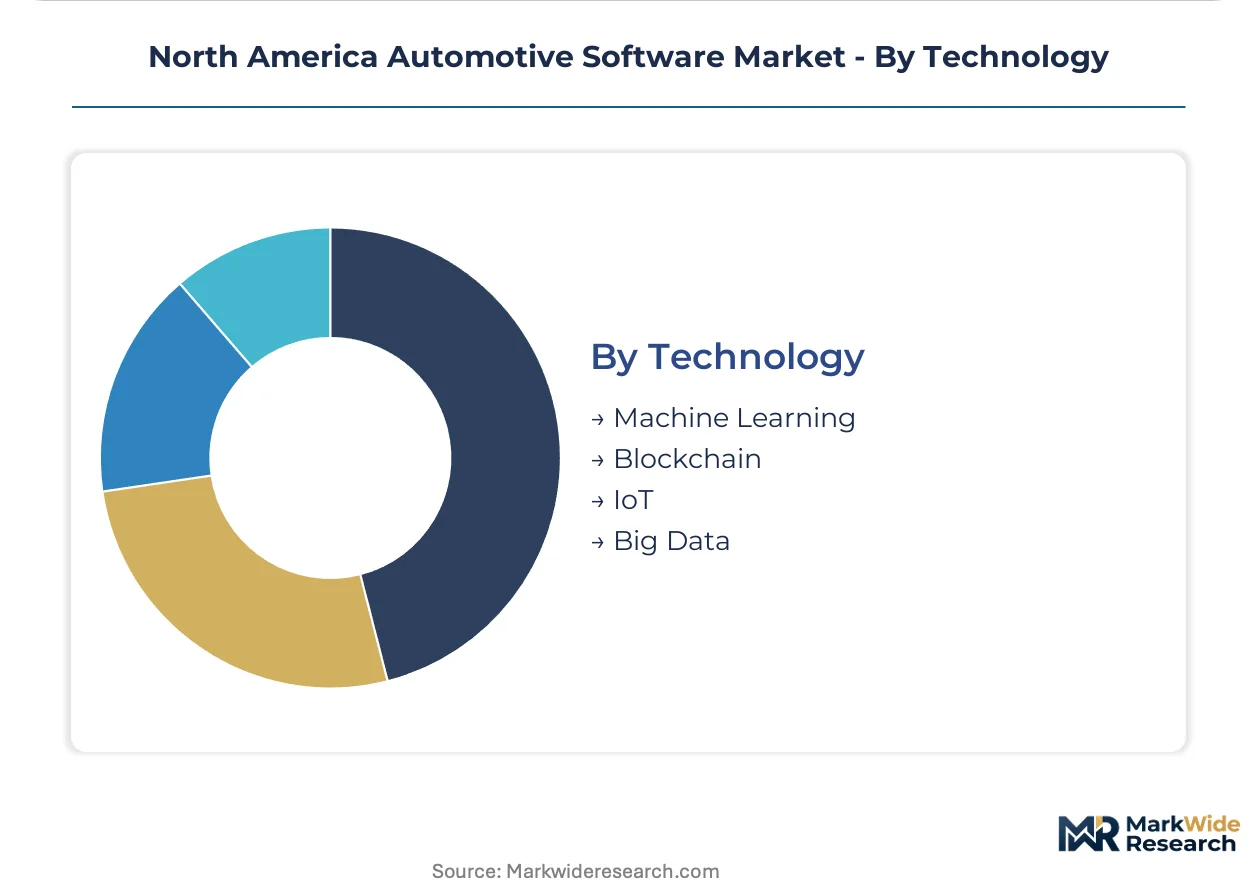
- Machine Learning:PyTorch and TensorRT workflows train perception models on cloud GPU clusters before quantization for edge deployment on automotive SoCs. Silicon Valley talent density attracts autonomous R&D investment from established automakers and venture-backed startups. End-to-end neural networks are rendering obsolete rule-based computer vision in advanced driver assistance.
- IoT:Vehicle-to-everything communication stacks integrate cellular V2X modules with edge computing gateways for traffic coordination.
- Big Data:Fleet telemetry aggregation pipelines process petabyte-scale sensor logs for predictive maintenance model refinement.
- Blockchain:Distributed ledger pilots trace supply chain provenance for critical semiconductor components without in-vehicle execution.
Machine Learning dominates technology investment; IoT connectivity layers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian automotive software exports flow predominantly to Detroit-based OEM engineering centers and Silicon Valley autonomous vehicle developers, creating cross-border R&D corridors that concentrate talent and procurement decisions in the Great Lakes and Pacific Coast zones.
United States
NHTSA Federal Motor Vehicle Safety Standards mandate crash-avoidance software verification with audit-ready documentation, compelling Detroit Three automakers to expand embedded security budgets. The EPA's greenhouse gas regulations require real-time powertrain calibration, accelerating over-the-air update infrastructure across production fleets. Michigan's Detroit-Warren corridor anchors validation facilities where OEMs co-locate with tier-one suppliers for fail-operational behavior testing.
Canada
Motor Vehicle Safety Act compliance creates dual-jurisdiction certification friction for unified North American platform deployments, particularly for autonomous perception stacks tested in Ontario and Quebec. Transport Canada harmonization efforts with NHTSA rulemaking reduce cross-border deployment barriers for software-defined vehicle architectures. Ontario's Waterloo-Toronto tech corridor hosts BlackBerry's embedded security kernel development for vehicle-to-cloud interface hardening.
California
Machine learning talent density in Silicon Valley attracts autonomous R&D investment from established automakers and venture-backed startups retraining engineering organizations around PyTorch workflows. California DMV autonomous vehicle testing permits require disengagement data submission that feeds NHTSA safety assessment frameworks. Arizona and California testing corridors host validation fleets demonstrating behavioral predictability across edge cases before production authorization.
Texas
Interstate trucking operators across Illinois-Ohio-Midwest logistics hubs demand uptime optimization platforms with predictive maintenance algorithms, unbundling software service agreements from chassis procurement. Fleet operators negotiate multi-year service agreements separate from vehicle acquisition, pressuring traditional dealership networks. Texas-based commercial vehicle engineering centers develop route efficiency analytics for per-mile operating cost reduction.
Arizona
Autonomous vehicle testing permits and permissive regulatory environments attract full self-driving platform developers operating validation fleets across desert corridors with favorable weather conditions. NHTSA rulemaking on automated driving system safety assessment falls heaviest on developers submitting scenario coverage matrices from Arizona operations. Phoenix-Tucson metro areas concentrate sensor fusion R&D for lidar point-cloud processing integration with camera-based perception networks.
North America Automotive Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around direct OEM-platform partnerships that collapse traditional tiered supply relationships. Semiconductor vendors and cloud providers renegotiate commercial terms with Detroit and Silicon Valley automakers as software-defined vehicle architectures fragment legacy procurement patterns. Three strategic archetypes dominate: high-performance compute stack providers, embedded security kernel specialists, and connected services platform operators. Competitive moves concentrate on strategic partnerships for autonomous perception pipelines and technology licensing for deterministic real-time operating systems.
Within the embedded security tier, BlackBerry Ltd exemplifies kernel hardening specialization for vehicle-to-cloud interfaces, while NVIDIA Corp anchors high-performance compute fabric provision for autonomous perception pipelines. Microsoft occupies a position competing with native OEM cloud investments through Azure-based connected services. These three companies represent the dominant competitive archetypes shaping direct OEM-platform partnership negotiations across Michigan and California engineering centers.
| Leading Market Players |
|---|
| COX Automotive Inc. |
| CDK Global |
| The Reynolds and Reynolds Company |
| Aptiv PLC |
| BlackBerry Ltd |
| NVIDIA Corp |
| Microsoft |
| Wind River |
| Robert Bosch GmbH |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Taiwan and South Korea for automotive-grade SoC fabrication determines both the three-tier pricing structure across premium, standard, and economy certification levels and the geographic clustering of tier-one validation facilities in Michigan and California. NHTSA audit documentation requirements and EPA emissions calibration mandates inflate embedded software development costs, compressing margin pools for mid-tier suppliers while concentrating pricing power with semiconductor vendors possessing certified safety-critical silicon.
Pricing Analysis
Next-generation autonomous perception platforms command 40-60% premiums over current-generation ADAS software stacks, while legacy powertrain control modules face commoditization pressure from rule-based algorithm displacement. Pricing stratifies across premium, standard, and economy tiers based on ISO 26262 ASIL certification grade and after-sales service bundling intensity. Cost compression in mid-tier embedded software is intensifying because AUTOSAR adaptive platform expertise scarcity inflates recruitment overhead. Fleet operators demonstrate the highest price sensitivity, while luxury OEMs absorb premium pricing for fail-operational deterministic stacks.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for North American automotive software deployments. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with advanced node GPU and AI accelerator production anchored in TSMC and Samsung foundries. Raw material dependencies span silicon wafers, rare earth elements for sensor magnetics, and cobalt for battery management system integration. Distribution runs through direct OEM-platform partnerships that displace traditional tiered procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America automotive software represents an early-cycle expansion story justified by accelerating over-the-air update infrastructure deployment across production fleets as EPA emissions protocols and NHTSA safety mandates harden software-verifiable compliance requirements.
For Market Incumbents: Pre-empt platform standardization initiatives by capturing AUTOSAR adaptive certification leadership before expertise scarcity peaks. Deepen backward integration into safety-critical silicon sourcing through direct foundry partnerships with Taiwan and South Korea fabricators. Secure exclusive co-development agreements with Detroit Three engineering centers in Michigan's Detroit-Warren corridor to lock out emerging middleware specialists. For New Entrants and Emerging Players: Cloud-native subscription platforms for commercial vehicle fleet management in the Midwest logistics corridor represent the most penetrable entry point, where uptime guarantee unbundling from chassis procurement creates recurring revenue white space. Sensor fusion middleware for lidar-camera integration in Arizona and California testing corridors offers architecture design wins with lower certification barriers than full-stack autonomous platforms. Target direct partnerships with interstate trucking operators bypassing traditional dealership networks. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors embedded security kernel specialists with vehicle-to-cloud hardening capabilities and deterministic real-time OS vendors with ISO 26262 ASIL-D track records. Long-term viability over the next decade hinges on recurring revenue attachment rates from over-the-air feature activation. Watch NHTSA automated driving system safety assessment rulemaking timelines as the inflection signal for autonomous platform authorization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | OEM platform engineering teams in Michigan and California are collapsing tiered supply relationships into direct semiconductor partnerships. |
| Battery Supply Agreement | Powertrain software calibration vendors require secured cobalt and lithium offtake to guarantee EPA emissions compliance timelines. |
| Platform Standardization | AUTOSAR adaptive compliance consolidation reduces heterogeneous ECU integration overhead across Detroit Three production lines. |
| Charging Infrastructure Partnership | Vehicle-to-grid communication stacks in Texas and California demand hardened cybersecurity kernels for bidirectional energy management. |
| Geographic Manufacturing Footprint | Proximity to Arizona and California autonomous testing corridors accelerates disengagement data collection for NHTSA safety submissions. |
Research Methodology
Desk research of SEC 10-K filings, vehicle production databases, and NHTSA regulatory dockets preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, autonomous vehicle testing directors, and aftermarket distribution operators. Primary fieldwork across Michigan's Detroit-Warren corridor and California's Silicon Valley tech cluster validated secondary estimates of embedded software versus cloud-native solution revenue splits. Bottom-up segment sizing triangulated against top-down OEM R&D expenditure disclosures from Detroit Three and transplanted automaker engineering centers.
Assumptions around NHTSA rulemaking velocity, EPA emissions calibration protocol stringency, and AUTOSAR adaptive platform migration timelines were held fixed across base-case scenarios while semiconductor supply availability and machine learning talent acquisition rates were stress-tested in sensitivity runs. Segmentation dimensions modeled include product type, application intensity, end-user procurement channel, and technology maturity tier. CAGRs were derived from regression analysis of historical OEM software R&D intensity ratios against projected vehicle production volumes across the analysis window.
Practitioners should monitor NHTSA automated driving system safety assessment finalization, cross-border harmonization between U.S. DOT and Transport Canada frameworks, and Taiwan semiconductor foundry capacity allocation for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Press Release Distribution Software Market
Software & Services
Online Whiteboard Software Market
Software & Services
Content Marketing Software Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Optical Design Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Construction Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Drone Mapping Software Market
Software & Services
VFX Software Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Chemical Manufacturing Software Market
Software & Services
Office Productivity Software Market
Software & Services
E-Invoicing Software Market
Software & Services
Collaborative Whiteboard Software Market
Software & Services
Global Accreditation Management Software Market