
 Poultry Farm Management Software Market | 2026-2036
Poultry Farm Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Farm Management Software Market Insights
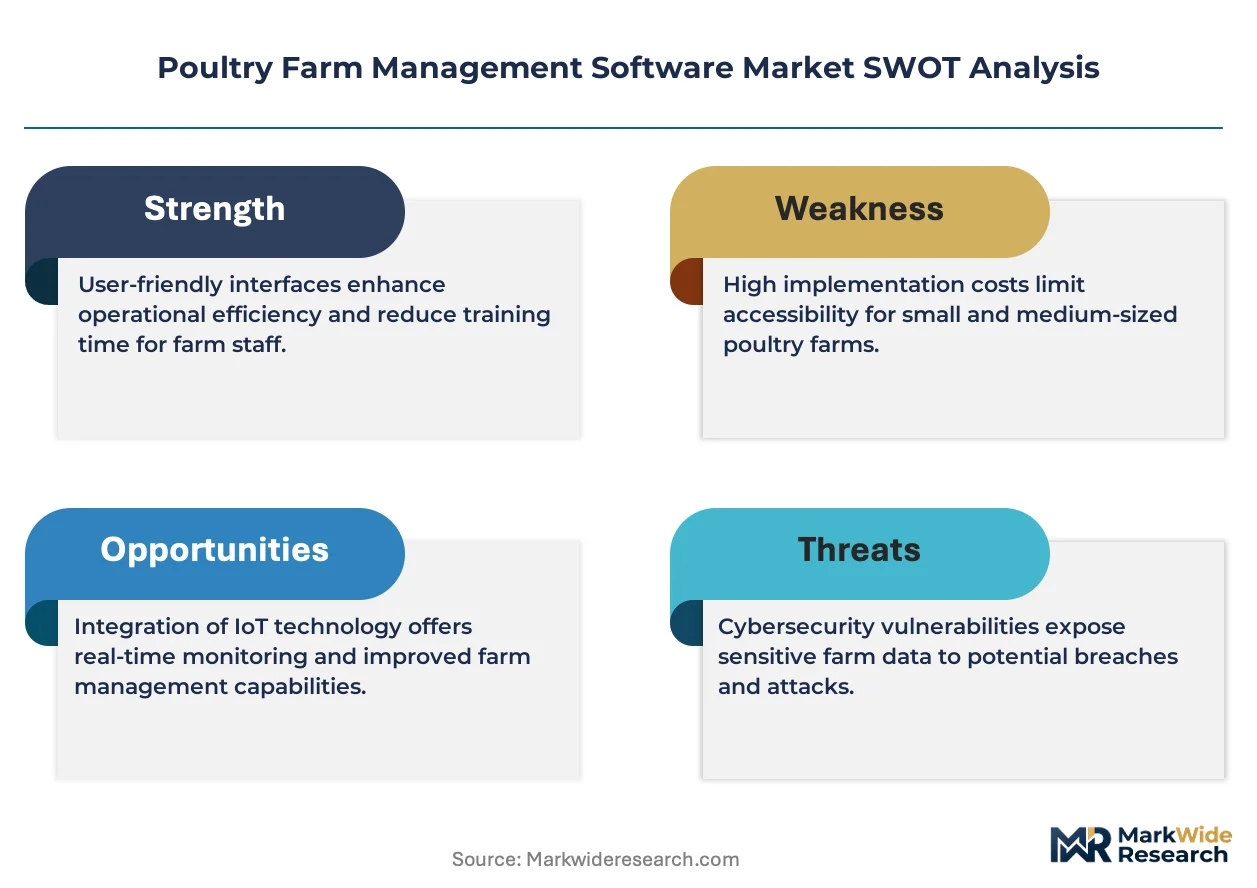
Project finance and equipment-leasing structures for sensor hardware bundled with software licenses is narrowing the capital barrier for mid-size poultry operations. BigFarmNet leverages its cloud-native architecture to compete across European markets where data residency rules fragment vendor selection. AGData Poultry anchors its position through deep integration with feed-mill ERP systems, creating captive switching costs for integrated agribusinesses. PoultryCare specializes in health monitoring modules that dominate the smallholder segment across Latin American cooperatives.
Poultry farm management software comprises digital platforms that coordinate flock tracking, feed optimization, mortality recording, and regulatory compliance reporting through centralized databases accessible via web dashboards or mobile interfaces. These systems typically integrate IoT sensors measuring barn temperature, humidity, and ammonia levels with algorithmic feed-conversion-ratio calculators to reduce input waste and improve batch uniformity. Cloud-based solutions now lead the product type category because subscription models lower upfront investment for farms scaling past single-site operations. Multi-farm deployment is accelerating fastest among cooperatives and vertically integrated agribusinesses that require consolidated visibility across geographically dispersed barns. Inventory management functionality captures the deepest margin pools where real-time feed and medication tracking prevents costly regulatory violations.
FDA guidelines on antibiotic residue monitoring and USDA biosecurity protocols shape software feature requirements for any vendor accessing US poultry operations. ANVISA traceability mandates in Brazil and EFSA food-chain integrity standards across Europe force comparable compliance module development, raising R&D thresholds for market entry. Stakeholders must monitor how emerging AI-driven mortality prediction tools alter the competitive balance between specialized health-monitoring vendors and full-suite platform providers.
Market Dynamics
Cloud-native architecture is compressing deployment timelines for multi-farm poultry operations while regulatory traceability mandates in Brazil, Vietnam, and Thailand force software vendors to embed compliance modules as standard features rather than premium add-ons.
Growth Catalysts
- ANVISA traceability mandates:Brazilian commercial farms must digitize flock records for antibiotic residue tracking, creating mandatory software procurement cycles.
- IoT sensor convergence:Temperature, humidity, and ammonia monitoring hardware bundled with SaaS licenses lowers capital barriers for mid-size operations.
- Contract farming networks:Southeast Asian integrators in Vietnam and Thailand require consolidated visibility across geographically dispersed barns.
Market Restraints
- Rural connectivity gaps:Last-mile broadband infrastructure in Brazilian interior states and Indonesian outer islands limits real-time data transmission.
- Feed price volatility:Soybean and corn input cost swings compress farm operating margins, delaying discretionary software investments.
- Data residency fragmentation:European EFSA compliance requirements and Vietnam's cybersecurity laws force vendors to maintain region-specific server infrastructure.
Strategic Opportunities
- Smallholder cooperatives:Latin American poultry associations with pooled procurement power represent underpenetrated demand for health monitoring modules.
- AI mortality prediction:Machine learning algorithms trained on historical flock data enable preventive intervention before disease outbreaks spread.
- Equipment-leasing structures:Sensor hardware financed through operating leases converts capex to opex for capital-constrained farms.
Industry Challenges
- Veterinary data science talent:Shortage of professionals combining livestock pathology expertise with predictive analytics modeling.
- Legacy ERP integration:Feed-mill and slaughterhouse systems using proprietary data formats require expensive custom API development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Farm Management Software Market |
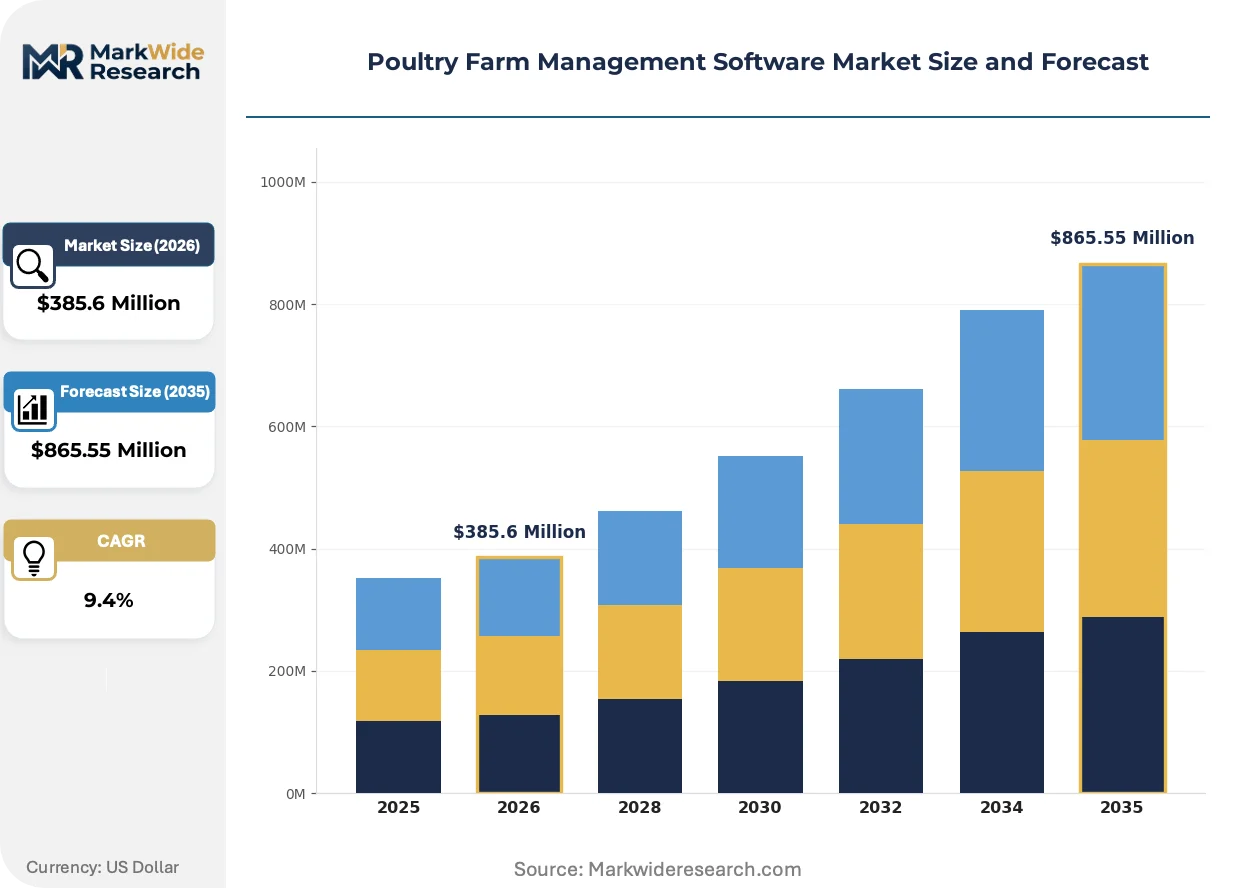
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $865.55 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premise Solutions, Mobile Applications, Hybrid Solutions End User: Commercial Poultry Farms, Smallholder Farmers, Cooperatives, Agribusinesses Deployment: Single Farm Deployment, Multi-Farm Deployment, Remote Monitoring, Integrated Systems Functionality: Inventory Management, Feed Management, Health Monitoring, Financial Reporting |
| Companies Covered | BigFarmNet, FarmNest, PoultryCare, Integrated Farm Software, AGData Poultry, Farm 2000, Poultry Wizard, Farmbrite, Sum-It Poultry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Farm Management Software Market Trends and Innovations
Algorithmic optimization is replacing rule-based flock management across commercial operations, compressing the gap between sensor data capture and actionable feeding decisions from days to minutes.
Edge computing nodes deployed directly in poultry barns are digitizing environmental control by processing temperature and ammonia readings locally before cloud synchronization. Mid-size farms with 50,000-200,000 bird capacities are adopting these systems fastest, attracted by subscription pricing that eliminates upfront server investment. This architecture is digitizing the competitive landscape by allowing specialized health-monitoring vendors to challenge full-suite platforms on latency-sensitive applications.
EFSA food-chain integrity standards across Europe now require batch-level traceability from hatchery to retail shelf, forcing software vendors to redesign database schemas for immutable record-keeping. Poultry processors exporting to EU markets must demonstrate compliance through third-party audit trails. Integrated agribusinesses with captive feed mills and processing plants are responding by consolidating vendor relationships to reduce audit fragmentation.
Cooperative procurement pooling is restructuring how smallholders access enterprise-grade software, with Vietnamese and Thai farming associations negotiating multi-farm licenses at volume discounts. Traditional direct sales through agricultural distributors are losing share to these collective purchasing arrangements. This shift concentrates most visibly in Mekong Delta contract farming clusters where integrators mandate software adoption as a supply condition.
Poultry Farm Management Software Market Segmentation
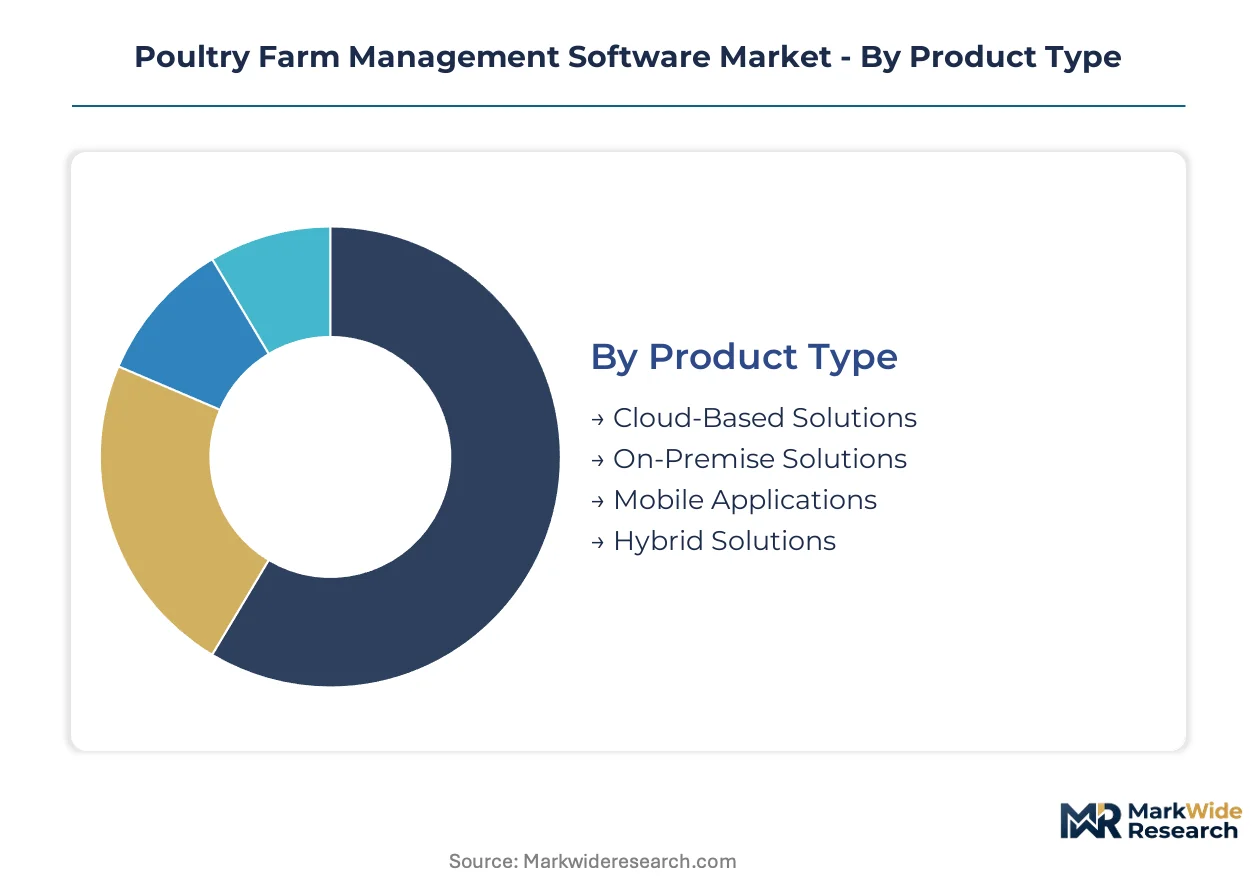
Poultry farm management software segments reflect divergent capital constraints, technical sophistication, and regulatory exposure across the producer base. Cloud-native architectures now dominate procurement among scaling operations, while specialized modules capture margin pools in compliance-intensive functions.
Product Type:
Mature subscription models coexist with emerging edge-computing architectures as farms weigh data sovereignty against operational agility.
- Cloud-Based Solutions:Browser-accessible platforms with centralized data lakes enable real-time flock visibility across dispersed barns. Vietnamese contract farming integrators in the Mekong Delta mandate these systems as supply conditions for their grower networks. Cloud-Based Solutions retain volume leadership; Hybrid Solutions hold the steepest expansion curve.
- On-Premise Solutions:Local server installations with offline functionality serve Brazilian interior farms where ANVISA audit trails must survive connectivity interruptions. These deployments concentrate in Mato Grosso and Paraná states where rural broadband remains unreliable.
- Mobile Applications:Smartphone-native interfaces with offline sync capabilities dominate smallholder cooperatives in Latin America.
- Hybrid Solutions:Edge nodes processing sensor data locally before cloud synchronization address European EFSA data residency requirements.
Cloud-Based Solutions retain volume leadership; Hybrid Solutions hold the steepest expansion curve.
End User:
Cost tier stratification separates enterprise-grade procurement from pooled-access arrangements among capital-constrained producers.
- Commercial Poultry Farms:Vertically integrated operations with 500,000-plus bird capacities deploy full-suite platforms integrating feed-mill ERP and slaughterhouse traceability. Thai integrators Charoen Pokphand Foods and Betagro anchor demand in Southeast Asia with multi-farm license purchases.
- Smallholder Farmers:Individual producers with under 10,000 birds access software through cooperative procurement pooling. Brazilian associations in Santa Catarina negotiate volume discounts for health monitoring modules.
- Cooperatives:Member-owned entities with pooled technical staff favor subscription models that convert software capex to operating expenses.
- Agribusinesses:Diversified agricultural conglomerates with captive poultry divisions require deep API integration with existing grain trading and logistics systems.
Commercial Poultry Farms command the deepest per-seat spending; Cooperatives are climbing the fastest as collective procurement spreads.
Deployment:
Application complexity rises with geographic dispersion and regulatory audit burden across the producer base.
- Single Farm Deployment:Standalone installations serving isolated operations with localized data storage. These configurations persist among Indonesian smallholders on outer islands where internet infrastructure remains underdeveloped.
- Multi-Farm Deployment:Consolidated dashboards spanning geographically dispersed barns enable integrators to enforce uniform biosecurity protocols. Vietnam's CP Vietnam and Thailand's GFPT deploy these systems across hundreds of contract grower facilities.
- Remote Monitoring:Cloud-connected sensor networks allowing off-site veterinary intervention. Brazilian commercial farms in São Paulo state leverage these capabilities to manage interior operations from coastal headquarters.
- Integrated Systems:Full-stack platforms connecting hatchery, feed mill, grow-out, and processing data streams. European exporters to EFSA-regulated markets require these configurations for batch-level traceability.
Multi-Farm Deployment captures the broadest addressable base; Integrated Systems are expanding most quickly on compliance mandates.
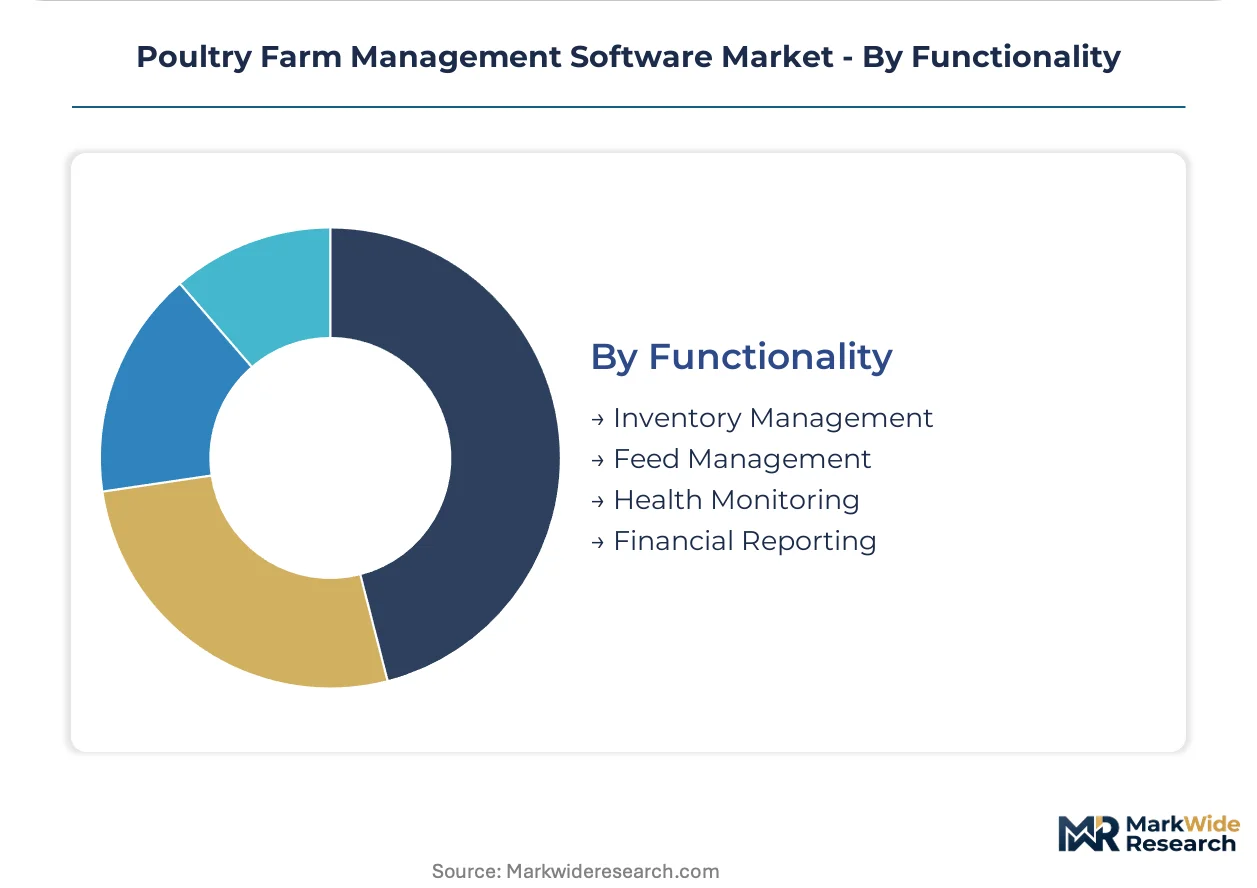
Functionality:
Margin concentration clusters around modules with direct regulatory exposure and input cost optimization leverage.
- Inventory Management:Real-time tracking of feed, medications, and vaccines with automated reorder triggers and expiration alerts. This functionality prevents costly ANVISA violations in Brazil where antibiotic residue documentation is mandatory.
- Feed Management:Algorithmic feed-conversion-ratio calculators integrating IoT weight sensors with ration formulation databases. Thai commercial farms deploy these tools to optimize soybean and corn input costs amid volatile commodity markets.
- Health Monitoring:Mortality logging, disease symptom tracking, and vaccination scheduling modules. Latin American cooperatives prioritize these capabilities for early outbreak detection.
- Financial Reporting:Batch profitability analysis with cost allocation across feed, labor, and veterinary expenses. These tools attract private equity-backed poultry rollups seeking operational transparency.
Inventory Management retains volume leadership; Health Monitoring holds the steepest expansion curve on AI mortality prediction development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial integrators and cooperative associations concentrate software procurement across five distinct national markets, each shaped by unique regulatory mandates and infrastructure constraints.
United States
Vertically integrated poultry conglomerates with multi-state operations drive enterprise platform adoption. USDA biosecurity protocols and FDA antibiotic residue monitoring force compliance module standardization. The Delmarva Peninsula cluster anchors deployment density, where integrators manage thousands of contract grower facilities through centralized dashboards.
Brazil
Mid-size commercial farms in São Paulo and Paraná states accelerate digital adoption amid ANVISA traceability enforcement. Equipment-leasing structures for sensor hardware bundled with SaaS licenses narrow capital barriers. The western Paraná corridor around Toledo concentrates deployment activity, where cooperatives negotiate volume discounts for health monitoring modules.
Vietnam
Mekong Delta contract farming networks mandate software adoption as a supply condition for integrator participation. Cybersecurity laws require region-specific server infrastructure, complicating vendor selection. Cần Thơ province hosts the densest implementation clusters, where CP Vietnam deploys multi-farm visibility systems across hundreds of dispersed barns.
Thailand
Charoen Pokphand Foods and Betagro anchor Southeast Asian demand with multi-farm license purchases spanning feed-mill integration. Algorithmic feed-conversion-ratio calculators attract farms optimizing volatile soybean and corn input costs. The Eastern Economic Corridor around Chonburi concentrates technology deployment, where integrated agribusinesses consolidate vendor relationships for EFSA export compliance.
Germany
EFSA food-chain integrity standards drive immutable record-keeping requirements for batch-level traceability from hatchery to retail. Data residency rules fragment vendor selection, favoring hybrid edge-computing architectures. Lower Saxony's poultry belt around Oldenburg leads implementation, where cloud-native platforms compete against on-premise systems for biosecurity-sensitive operations.
Poultry Farm Management Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single firm commands dominant share. Full-suite platform providers vie with modular health-monitoring specialists for procurement budgets at commercial farms and cooperatives. Two strategic archetypes define positioning: cloud-native architecture specialists leveraging subscription economics, and ERP-integrated incumbents creating captive switching costs through feed-mill system connectivity. Competitive moves center on geographic expansion into compliance-heavy markets and technology licensing partnerships with sensor hardware manufacturers.
Within the cloud-native tier, BigFarmNet leverages its browser-accessible platform to address European data residency fragmentation, while AGData Poultry anchors its position through deep ERP integration with feed-mill systems. PoultryCare exemplifies the health-monitoring specialist archetype, occupying a dominant position across Latin American smallholder cooperatives where mortality prediction modules drive procurement decisions.
| Leading Market Players |
|---|
| BigFarmNet |
| FarmNest |
| PoultryCare |
| Integrated Farm Software |
| AGData Poultry |
| Farm 2000 |
| Poultry Wizard |
| Farmbrite |
| Sum-It Poultry |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in cloud-native SaaS platforms across European poultry markets is compressing subscription pricing while simultaneously pressuring sensor hardware vendors to absorb margin erosion through bundled equipment-leasing structures. This utilization dynamic forces mid-tier software vendors to choose between maintaining price discipline or capturing market share through aggressive discounting to Vietnamese and Thai contract farming networks.
Pricing Analysis
Cost-plus contracts indexed to feed commodity benchmarks dominate enterprise procurement among Thai integrators like Charoen Pokphand Foods, with ANVISA compliance modules now standard rather than premium-tier add-ons. Price differentiation rests on API integration depth with feed-mill ERP systems and edge-computing latency performance. Pricing pressure stems from cooperative procurement pooling in Latin America, where Brazilian associations negotiate volume discounts that squeeze per-seat margins. Smallholder cooperatives exhibit acute price sensitivity, while vertically integrated agribusinesses prioritize interoperability over cost.
Supply Chain Analysis
Upstream feedstock volatility in Brazilian soybean and corn markets transmits directly into software vendor working capital cycles, as equipment-leasing structures tether sensor hardware financing to agricultural commodity price swings. Component sourcing concentrates in China for IoT sensors, Vietnam for assembly labor, and Germany for precision agriculture controllers. Single-source vulnerability runs through Taiwanese semiconductor foundries supplying edge-computing nodes. Distribution runs through agricultural equipment dealers in Brazil, integrator procurement offices in Thailand, and cooperative buying associations across Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poultry farm management software is approaching a platform-economics inflection where interoperability standards between feed-mill ERP and health-monitoring modules will determine competitive survival. The shift toward open API ecosystems in European markets signals which vendor architectures will capture multi-farm deployment growth.
For Market Incumbents: Build data-residency moats through hybrid edge-cloud architectures that satisfy EFSA traceability mandates without sacrificing real-time latency. Deepen API integration with feed-mill systems to raise switching costs for Thai and Vietnamese integrators. Counter cloud-native challengers by embedding AI mortality prediction tools that leverage proprietary historical flock datasets accumulated across decades of deployments. For New Entrants and Emerging Players: Establish a beachhead in Latin American smallholder cooperatives where health-monitoring modules remain underpenetrated and procurement pooling creates concentrated demand access. Target Brazilian interior states where ANVISA compliance mandates intersect with unreliable rural connectivity, favoring vendors offering offline-sync mobile applications. Pursue white-label partnerships with agricultural equipment manufacturers to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as subscription economics replace upfront server infrastructure investments. Prioritize acquisition targets with established veterinary data science teams capable of training predictive mortality algorithms on proprietary flock datasets. Monitor AI-driven health monitoring patent filings as the signal indicating which specialized vendors will challenge full-suite platform incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Open interoperability protocols enable third-party health-monitoring modules to integrate with Charoen Pokphand Foods' feed-mill ERP systems. |
| Edge-Computing Node Deployment | Local sensor processing addresses EFSA data residency requirements while reducing cloud transmission costs for German poultry operations. |
| Equipment-Leasing Restructuring | Operating-lease financing converts sensor hardware capex to opex, narrowing capital barriers for Brazilian mid-size farms. |
| AI Mortality Prediction Licensing | Machine-learning algorithm partnerships with veterinary research institutes differentiate health-monitoring specialists from full-suite platforms. |
| Cooperative Procurement Aggregation | Pooled licensing negotiations by Vietnamese Mekong Delta farming associations concentrate demand and accelerate multi-farm deployment adoption. |
Research Methodology
The analysis maps cloud-native architectures, hybrid edge-computing deployments, and on-premise legacy systems, each validated through poultry operations managers, veterinary data scientists, feed-mill procurement directors, and agricultural cooperative technical staff. Primary interviews with these stakeholders triangulate against secondary sources including ANVISA regulatory filings, EFSA food-chain integrity standards, USDA biosecurity protocols, and SEC disclosures from publicly traded agribusinesses. Bottom-up segment sizing and top-down macro validation cross-check volume estimates across deployment models and functionality modules.
Assumption sets held regulatory enforcement timelines and feed commodity price volatility bands fixed across the projection horizon, while varying cloud adoption curves and cooperative procurement penetration rates. Segmentation dimensions modeled include deployment architecture, farm scale tier, integration complexity with upstream feed systems, and regional regulatory cluster. CAGRs derive from historical adoption pattern analysis and vendor revenue trajectory benchmarking, with IoT sensor cost decline curves and broadband infrastructure buildout schedules as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates or Southeast Asian contract farming credit availability would shift the trajectory. Forecasts reflect documented assumptions about ANVISA enforcement intensity and EFSA audit trail standardization timelines. Material shifts in veterinary data science talent availability or edge-computing semiconductor supply constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Office Productivity Software Market
Software & Services
Europe Workforce Management Software Market
Software & Services
Web Scraping Software Market
Software & Services
Specification Management Software Market
Software & Services
Embedded Operating Systems Market
Software & Services
Europe Contract Lifecycle Management Software Market
Software & Services
Global Travel and Expense Management Software Market
Software & Services
Commissioning Software Market
Software & Services
CAD Modeling Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Change Control Management Software Market
Software & Services
Global Wedding Invitations Software Market
Software & Services
Binary Drivers Market
Software & Services
Software Repository Market
Software & Services
Enterprise Performance Management (EPM) Software Market
Software & Services
Middle-East Virtual Data Room Market