
 Edible Collagen Casing Market | 2026-2036
Edible Collagen Casing Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Collagen Casing Market Foresight
Skilled collagen extraction technicians is redrawing competitive boundaries in the edible collagen casing sector. Devro plc sustains manufacturing scale across multiple continents through captive gelatin supply chains. Viscofan Group dominates high-volume fresh casing output for European sausage processors. Nippi Inc. specializes in precision-dried formats for Japanese and Southeast Asian export channels.
Edible collagen casing consists of regenerated collagen fibers derived from bovine or porcine corium layers, extruded into uniform tubes with calibrated diameters ranging from 15 mm to 50 mm and moisture content typically between 12% and 35% depending on intended application. The material serves as an alternative to natural animal intestines in sausage manufacturing, providing consistent caliber, improved machinability, and elimination of pathogen variability associated with gut-derived casings. Fresh collagen casings anchor volume demand among industrial meat processors seeking high-speed stuffing compatibility. Dried formats command premium positioning in artisanal and export-oriented segments where shelf stability reduces cold-chain burden. Application concentration in meat products and sausages generates the dominant margin pools, while snack and cheese applications remain niche expansion zones.
FDA food-contact substance notifications and USDA FSIS labeling requirements govern collagen casing compliance in the United States, with particular scrutiny on species-origin declarations and allergen cross-contact protocols. EFSA and EU Commission Regulation 10/2011 on plastic materials and articles intended to come into contact with food establish migration limits and testing protocols for collagen-based casings entering European commerce. Stakeholders must monitor evolving clean-label certification schemes and species-traceability mandates as procurement criteria tighten across retail and food-service channels.
Market Dynamics
Collagen extraction technician scarcity is compressing capacity expansion timelines across the edible collagen casing sector, forcing processors to automate or pay premium wages for skilled labor.
Growth Catalysts
- REACH migration limit tightening:Europe's ECHA is lowering acceptable casing migration thresholds, accelerating replacement of older gut-derived alternatives with certified collagen formats in German sausage-processing clusters.
- High-speed stuffing compatibility:Industrial meat processors in Bavaria and Thuringia are retrofitting production lines for fresh collagen casings that tolerate 300+ pieces per minute throughput without caliber variation.
- Clean-label procurement mandates:Retail channel buyers are imposing species-traceability requirements that disqualify natural intestine suppliers lacking documented supply chain controls.
Market Restraints
- Bovine hide cost volatility:Corium layer prices fluctuate with leather tanning demand cycles, compressing margin predictability for casing manufacturers without captive tannery relationships.
- Species-origin declaration friction:USDA FSIS labeling requirements create compliance complexity for exporters serving multiple markets with divergent species-acceptance rules.
- Cellulose casing substitution:Plant-derived alternatives from viscose fiber producers are capturing price-sensitive segments where machinability requirements permit non-collagen formats.
Strategic Opportunities
- Snack application white space:Collagen-wrapped protein bars and meat sticks remain underpenetrated versus sausage dominance, offering format innovation potential for dried casing specialists.
- Cheese maturation casings:Artisanal dairy processors in France and Italy are testing permeable collagen wraps for soft-ripened varieties, creating adjacent demand outside meat.
- EFSA novel food pathways:Regulatory clarity on collagen-fortified functional foods is opening ingredient-grade casing derivatives for nutraceutical channels.
Industry Challenges
- Collagen extraction technician pipeline gaps:Vocational training programs for hide processing and fiber regeneration lag retirement rates in established manufacturing regions.
- Multi-jurisdiction certification timelines:Simultaneous FDA notification and EU 10/2011 compliance testing extends product launch cycles by 18-24 months for format innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Collagen Casing Market |
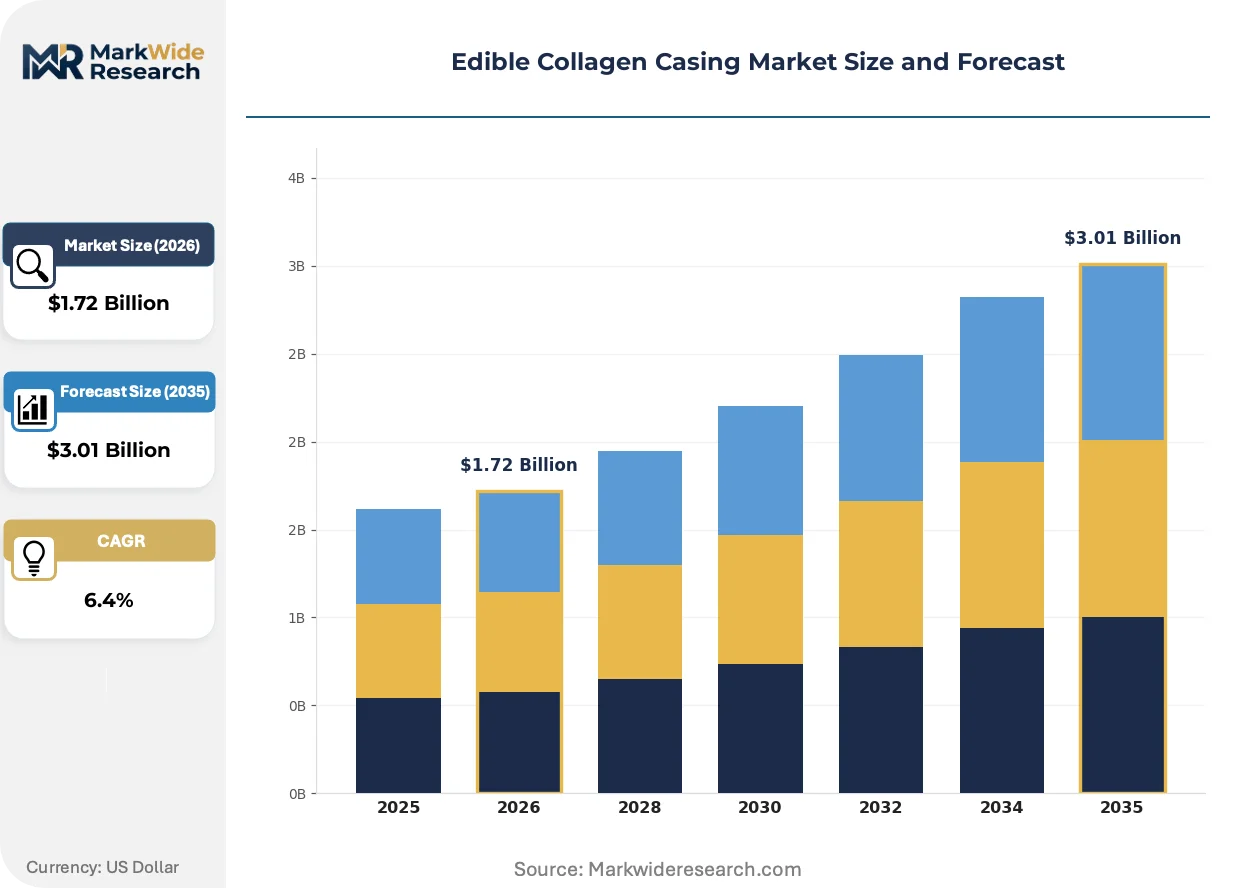
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fresh, Frozen, Dried, Smoked Application: Meat Products, Sausages, Snacks, Cheese End User: Food Manufacturers, Retailers, Food Service, Home Cooks Distribution Channel: Wholesale, Online, Supermarkets, Specialty Stores |
| Companies Covered | Fibran Group, Nippi Inc., Viscofan Group, Belkozin, FABIOS, Devro plc, Nitta Gelatin, Foodchem International Corporation, Shenguan Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Collagen Casing Market Shifts & Advancements
Extrusion die technology and moisture-control systems are redefining caliber precision standards, while regulatory divergence between major markets is fragmenting product development roadmaps.
Precision co-extrusion systems with multi-layer collagen deposition are decomposing the traditional fresh-versus-dried format dichotomy. Mid-scale sausage processors in Poland and the Czech Republic are adopting these hybrid systems to produce calibrated casings with variable moisture profiles from a single production line. The technology is decomposing established supplier-customer relationships by enabling in-house casing generation that bypasses merchant market purchases.
EU Commission Regulation 10/2011 amendments on plastic materials and articles intended to come into contact with food are extending testing protocols to collagen-based casings previously exempt from migration studies. Industrial laboratories in Germany are expanding analytical capacity for specific migration limit verification. Fresh casing segments serving retail-packaged sausages face the steepest compliance cost escalation, driving consolidation among testing service providers.
Direct-procurement relationships between meat processors and collagen suppliers are displacing distributor-mediated purchasing in high-volume segments. Large sausage manufacturers in Bavaria are negotiating multi-year supply agreements with specified species-origin traceability. This pattern is most pronounced in Germany's processing belt, where cold-chain integration requirements favor single-source accountability over fragmented supplier bases.
Edible Collagen Casing Market Segmentation
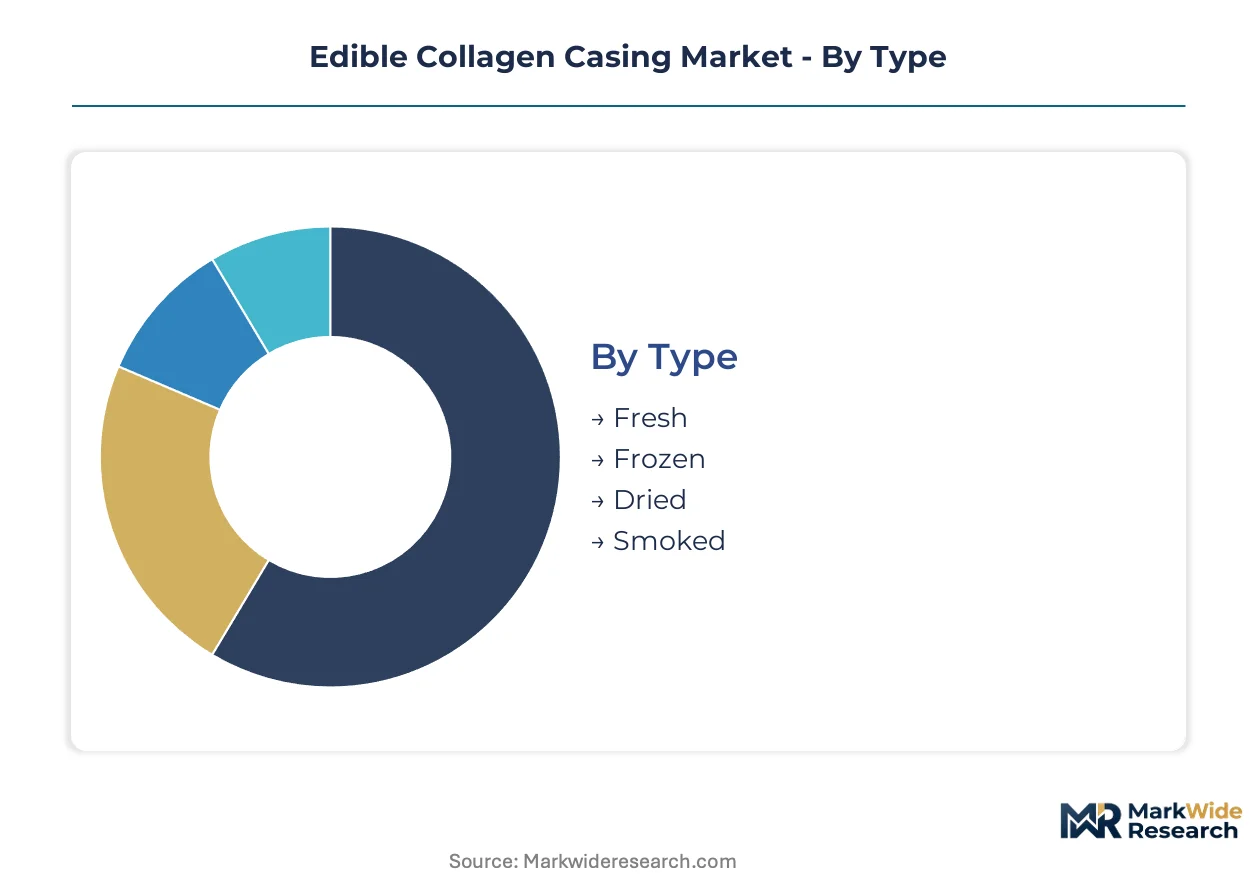
Segmentation in edible collagen casing markets reveals how regulatory frameworks, processing requirements, and distribution economics fragment demand across distinct product formats and customer tiers. Understanding these divisions exposes where margin pools concentrate and where compliance costs create competitive moats.
Type:
REACH migration limits and FDA food-contact notifications apply differentially across moisture-content tiers, with fresh formats facing stricter analytical verification than dried alternatives.
- Fresh:High-moisture collagen tubes with 30-35% water content deliver optimal elasticity for high-speed stuffing lines in Bavarian and Thuringian sausage plants. German processors retrofitting for 300+ pieces-per-minute throughput anchor volume demand, though EFSA migration testing cost escalation compresses margins for smaller suppliers.
- Dried:Low-moisture formats at 12-18% water content enable ambient storage and extended shelf stability for export channels serving Japanese and Southeast Asian markets. Japanese regulatory acceptance of precision-dried specifications creates premium positioning unavailable to fresh-format competitors.
- Frozen:Intermediate moisture preservation for regional distribution networks lacking cold-chain reliability.
- Smoked:Pre-treated variants absorbing flavor compounds during collagen regeneration.
Established volume favors fresh formats; emerging adoption favors dried variants.
Application:
End-use concentration determines species-origin certification intensity, with meat applications triggering full USDA FSIS traceability protocols.
- Meat Products:Industrial processors of portioned cuts and formed meats utilize collagen casings for binding and shape retention. Clean-label procurement mandates from German retail chains now require documented bovine-versus-porcine corium sourcing, disqualifying suppliers with opaque hide-procurement networks.
- Sausages:Fresh collagen tolerates extreme stuffing pressures without caliber variation, anchoring volume in Central European industrial plants. Poland and Czech Republic mid-scale processors increasingly adopt hybrid extrusion systems for in-house casing generation.
- Snacks:Protein bars and meat sticks represent underpenetrated expansion territory for dried casing specialists.
- Cheese:Artisanal French and Italian soft-ripened varieties test permeable collagen wraps for rind development.
Meat and sausage applications dominate current procurement; cheese and snack segments offer the steepest expansion trajectory.
End User:
Customer scale dictates whether procurement flows through distributor networks or direct supplier relationships.
- Food Manufacturers:Large sausage producers negotiate multi-year supply agreements with specified species-origin traceability, displacing fragmented supplier bases in Germany's processing belt.
- Retailers:Supermarket private-label programs impose clean-label certification schemes that cascade compliance requirements upstream.
- Food Service:Restaurant chains and institutional buyers prioritize machinability consistency over origin documentation.
- Home Cooks:Specialty store and online channels serve artisanal sausage-making enthusiasts with small-diameter dried formats.
Food manufacturers concentrate procurement volume; food service channels are climbing the fastest.
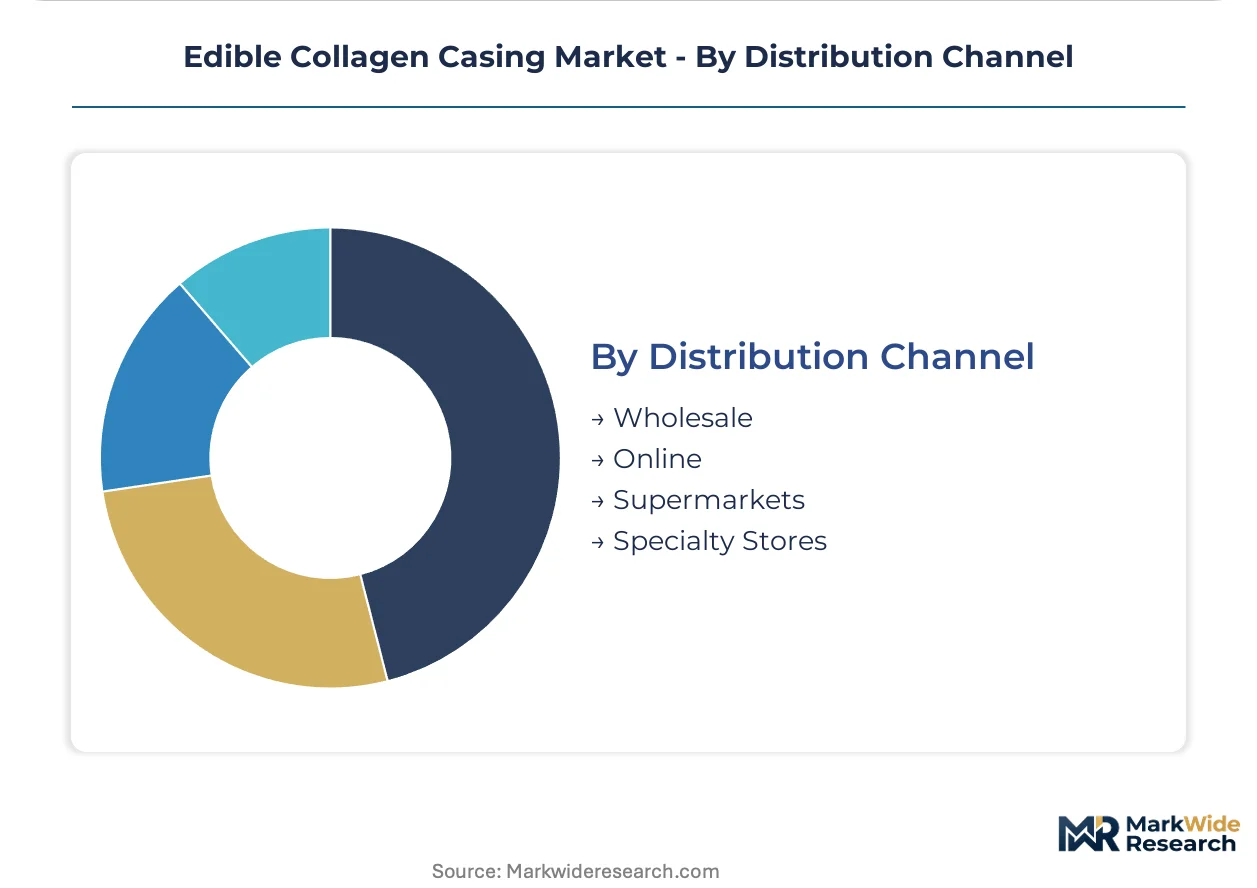
Distribution Channel:
Channel selection reflects cold-chain integration requirements and lot-size economics.
- Wholesale:Distributor-mediated purchasing persists in mid-volume segments where processors lack scale for direct supplier negotiation.
- Online:E-commerce platforms enable dried casing access for geographically dispersed artisanal producers and home cooks.
- Supermarkets:Retail shelf placement requires EFSA-compliant packaging and species-origin labeling for consumer-facing sales.
- Specialty Stores:Butcher supply shops and culinary equipment retailers serve small-batch processors with technical support.
Wholesale channels retain industrial volume; online distribution is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sausage processors consume fresh collagen casings at volumes unmatched elsewhere, while Japanese buyers favor precision-dried formats for ambient distribution. This consumption-mix differential shapes supplier specialization and regulatory investment priorities across manufacturing regions.
Germany
Bavarian and Thuringian processing clusters drive demand for high-speed stuffing compatibility exceeding 300 pieces per minute. ECHA REACH migration limit tightening forces casing replacement cycles in industrial plants. Munich-area laboratories now dominate EU-wide analytical capacity for specific migration verification.
United States
USDA FSIS species-origin declaration requirements create compliance friction for exporters serving multiple markets. FDA food-contact substance notification pathways govern new format introductions. Midwest meatpacking corridors around Chicago and Omaha anchor procurement volume for fresh collagen tubes.
Japan
Japanese regulatory acceptance of precision-dried specifications enables premium positioning unavailable to fresh-format competitors. METI standards for food-contact materials shape import testing protocols. Tokyo and Osaka distribution hubs concentrate demand for ambient-stable casings serving Southeast Asian re-export channels.
Poland
Mid-scale sausage processors in Poland accelerate adoption of hybrid extrusion systems for in-house casing generation. EU Commission Regulation 10/2011 compliance costs compress margins for smaller merchant suppliers. Warsaw and Łódź industrial zones witness fastest retrofitting activity for co-extrusion equipment.
China
Domestic sausage manufacturers expand collagen casing adoption as clean-label alternatives penetrate retail channels. SAMR food-contact material standards tighten safety thresholds for migration limits. Yangtze River Delta processing hubs around Shanghai drive volume procurement for standardized diameter formats.
Edible Collagen Casing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive gelatin supply chains separating scale players from merchant-market competitors. The upper tier commands multi-continent manufacturing footprints and direct procurement relationships with large processors. Specialist competitors occupy format-specific niches—dried precision, snack applications, or regional regulatory expertise. Dominant competitive moves include backward integration into hide processing and multi-year supply agreements with specified species-traceability terms.
Among the integrated leaders, Devro plc and Viscofan Group exemplify scale-driven archetypes with manufacturing breadth across multiple continents. Nippi Inc. occupies a specialist position within precision-dried formats, serving Japanese regulatory requirements and Southeast Asian export channels. These three anchors illustrate how supply chain control and format specialization separate competitive tiers in the sector.
| Leading Market Players |
|---|
| Fibran Group |
| Nippi Inc. |
| Viscofan Group |
| Belkozin |
| FABIOS |
| Devro plc |
| Nitta Gelatin |
| Foodchem International Corporation |
| Shenguan Holdings |
| Others |
Supply & Pricing Matrix
Capacity utilization at German tannery clusters shapes both supply concentration and price floors for collagen casing manufacturers. Devro plc and Viscofan Group leverage captive gelatin supply chains to insulate margin structures from bovine hide cost volatility that compresses merchant-market competitors.
Pricing Analysis
Long-term offtake agreements dominate procurement between large Bavarian sausage processors and integrated casing suppliers, displacing spot-market purchasing in high-volume segments. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified fresh formats from dried precision grades and unbranded commodity alternatives. Pricing pressure stems from cellulose casing substitution in price-sensitive applications where machinability requirements permit non-collagen formats. Small-scale artisanal processors exhibit highest price sensitivity, while industrial meat manufacturers prioritize species-traceability documentation over unit cost.
Supply Chain Analysis
Germany and China anchor collagen casing manufacturing through distinct specializations—fresh-format volume versus standardized diameter production for domestic retail channels. Raw material flows draw from bovine corium layers sourced through tanning industry relationships, porcine hide streams from meatpacking integration, and regenerated fiber inputs for precision-dried grades. Single-source vulnerability concentrates in skilled collagen extraction technician availability, where vocational training gaps lag retirement rates across established manufacturing regions. Distribution runs through direct-procurement relationships for large processors, with distributor-mediated channels serving mid-scale Polish and Czech Republic plants lacking scale for supplier negotiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in migration testing and certification compliance are expanding faster than casing hardware sales, as EFSA and FDA regulatory verification becomes a recurring revenue layer for laboratories and technical consultants.
For Market Incumbents: Compound defensive positioning through backward integration into hide processing and captive technician training programs that lock in capacity expansion timelines. Cellulose casing substitution from viscose fiber producers threatens price-sensitive segments, requiring incumbents to reinforce high-speed stuffing compatibility advantages through extrusion die technology investment in Bavarian manufacturing clusters. For New Entrants and Emerging Players: Lead with snack application white space where protein bars and meat sticks remain underpenetrated versus sausage dominance, targeting dried casing formats for ambient distribution channels. Cheese maturation casings for artisanal French and Italian soft-ripened varieties offer adjacent demand outside meat with lower incumbent saturation. Go-to-market positioning should emphasize EFSA novel food pathway expertise to differentiate from established sausage-supplier relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-dried specialists with regulatory acceptance in Japanese and Southeast Asian export channels over fresh-format commodity producers facing margin compression. Long-term viability across the projection horizon rests on supply chain control through tannery relationships and multi-year species-traceability contracts. The signal to watch is REACH migration limit tightening velocity, which accelerates replacement demand cycles and testing service provider consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hide Processing | Captive bovine corium supply insulates Devro plc and Viscofan Group from leather tanning demand cycles. |
| EFSA Novel Food Pathway Investment | Regulatory clarity on collagen-fortified derivatives opens nutraceutical ingredient channels beyond traditional casing applications. |
| Hybrid Extrusion System Deployment | Mid-scale Polish processors bypass merchant-market purchases through in-house casing generation with variable moisture profiles. |
| Multi-Year Species-Traceability Contracts | Bavarian sausage manufacturers impose documented supply chain controls that disqualify fragmented natural intestine suppliers. |
| Migration Testing Laboratory Expansion | Munich-area analytical capacity growth dominates EU-wide specific migration limit verification for REACH compliance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with collagen extraction technicians, sausage plant engineering managers, tannery procurement leads, and EFSA regulatory compliance officers. Secondary validation drew from EU Commission Regulation 10/2011 amendments, FDA food-contact substance notification filings, SAMR food-contact material standards, German customs trade data for hide imports, and SEC disclosures from publicly traded casing manufacturers. Bottom-up segment sizing triangulated against top-down market boundary estimates across fresh, dried, frozen, and smoked format categories.
Across the analysis window, volume and value outputs reflect analytical frameworks modeling moisture-content tiers, application concentration in meat versus emerging cheese and snack segments, end-user scale differentiation between food manufacturers and food service channels, and distribution channel evolution from wholesale toward online penetration. CAGRs were derived from regression analysis against historical capacity expansion timelines and regulatory compliance cost trajectories. Forecast inputs incorporated bovine hide price volatility indices and skilled technician pipeline gap projections.
The analysis sits within stated boundaries; outcomes outside sustained REACH migration limit enforcement or accelerated cellulose casing substitution would require recalibration. Forecasts reflect assumptions on clean-label procurement mandate adoption velocity and species-traceability certification penetration across retail channel buyers. Recalibration cycles align with material shifts in ECHA regulatory amendments and hybrid extrusion technology diffusion rates among mid-scale Central European processors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
Industrial Fryers Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
Industrial Food Milling Machine Market
Food Processing Equipment
Beverage Processing Equipment Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
Walk-In Refrigerators & Freezers Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Global Non Thermal Processing Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market