
 United Kingdom IT Services Market | 2026-2036
United Kingdom IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom IT Services Market Analytics
Channel partnerships between systems integrators and hyperscale cloud providers is reconfiguring how enterprise workloads reach end customers in the United Kingdom. Accenture leverages its consulting heritage to anchor multi-year digital transformation contracts with FTSE-listed clients. IBM sustains technology leadership in hybrid cloud and AI infrastructure through its Red Hat integration. TCS competes aggressively on cost-engineered delivery models from its UK delivery centers.
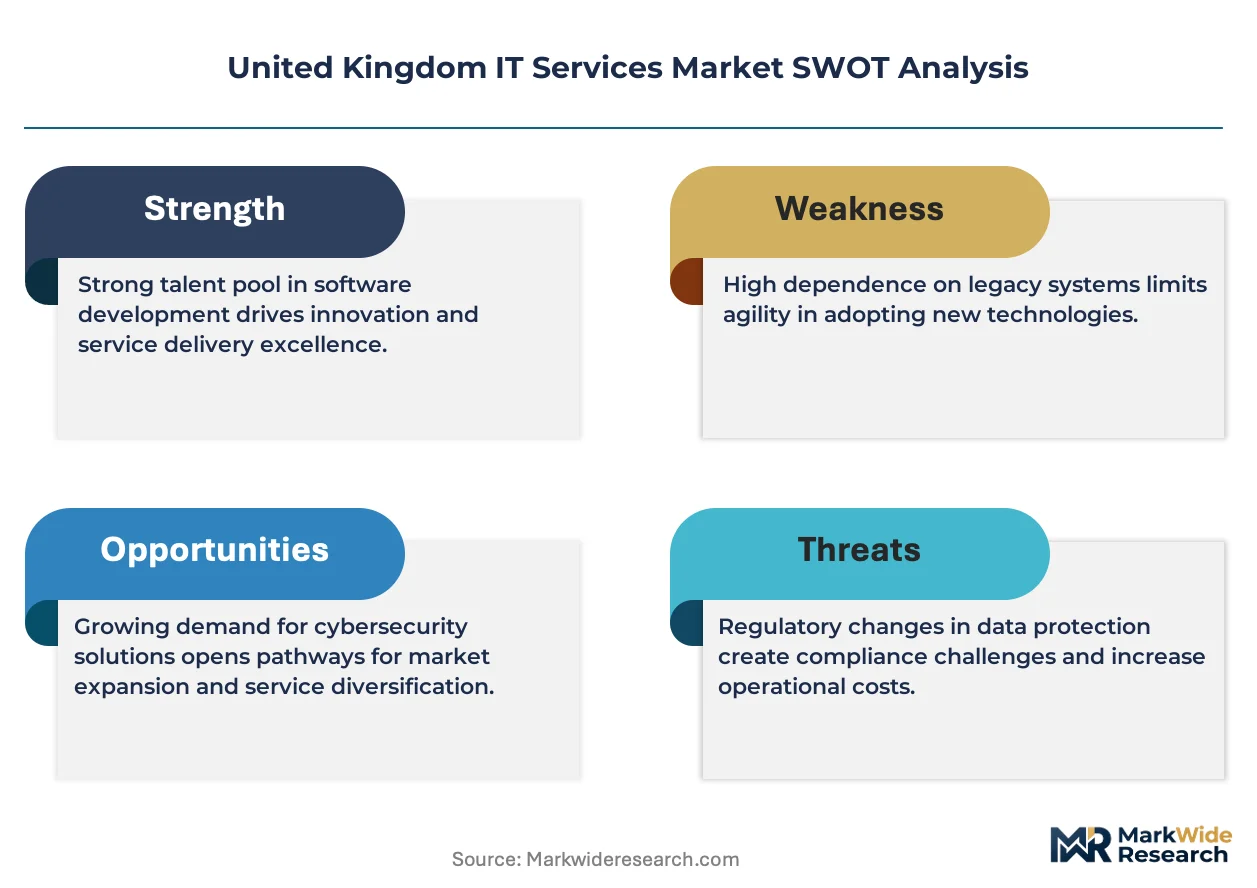
United Kingdom IT Services encompass the design, implementation, management, and optimization of information technology infrastructure, applications, and business processes delivered through on-premises, cloud-native, or hybrid architectures with service-level agreements typically spanning twelve to sixty months. These services enable operational continuity, regulatory compliance, and digital capability extension across public and private sector organizations. Managed Services commands the largest revenue pool as organizations outsource legacy infrastructure maintenance, while Cloud Services represents the fastest-expanding segment driven by public sector migration mandates and financial services resilience requirements. Software Development retains above-average margins in specialized domains such as fintech regtech and healthtech, where domain expertise creates differentiation. Consulting maintains steady demand for post-merger integration and ERP modernization, though pricing pressure intensifies from boutique firms and freelance platforms.
The UK National Cyber Security Centre mandates shape procurement standards for critical infrastructure operators, while the UK GDPR framework and post-Brexit data protection regime constrain cross-border data flows and elevate domestic hosting requirements. ISO 27001 certification has become a baseline qualifier for public sector tenders administered through the Crown Commercial Service frameworks. Stakeholders must monitor evolving UK AI regulation and the Financial Conduct Authority's operational resilience directives to anticipate compliance-driven service procurement shifts.
Market Dynamics
Post-Brexit data sovereignty mandates are forcing UK enterprises to repatriate cloud workloads from EU-based hyperscalers, creating structural demand for domestic infrastructure providers and managed security operators certified under Crown Commercial Service frameworks.
Growth Catalysts
- NCSC Cyber Assessment Framework:Critical infrastructure operators must achieve compliance by 2028, driving procurement of managed detection and response services from UK-based security operations centers.
- Financial services operational resilience mandates:The Prudential Regulation Authority requires firms to map third-party dependencies and test recovery capabilities, expanding contracts for business continuity and disaster recovery services.
- Hybrid cloud orchestration tooling:Kubernetes-native platforms enable workload portability between on-premises data centers and sovereign cloud regions, accelerating replacement of legacy virtualization estates.
Market Restraints
- Specialized cloud engineering talent scarcity:SRE and platform engineering skills command 40-60% salary premiums over generalist IT roles, compressing margins for labor-intensive managed services contracts.
- Hyperscale provider concentration:Three global cloud vendors control over 70% of UK public cloud infrastructure, creating vendor lock-in risks and limiting price negotiation leverage for mid-market enterprises.
- Cross-border data transfer friction:UK GDPR adequacy decisions remain under periodic EU Commission review, complicating multi-tenant architectures serving both UK and continental European users.
Strategic Opportunities
- NHS digital transformation programs:Federated Data Platforms and electronic patient record consolidation create multi-year implementation pipelines for systems integrators with healthtech domain expertise.
- AI sovereignty infrastructure:GPU-as-a-service offerings in UK Tier 3+ data centers address Financial Conduct Authority concerns about proprietary model training on foreign infrastructure.
- Scotland and Northern England delivery centers:Lower commercial real estate costs and university graduate pipelines in Glasgow, Manchester, and Leeds enable cost-competitive nearshore delivery models for London-headquartered clients.
Industry Challenges
- Security clearance bottlenecks:Developed Vetting and Security Check processing delays of 9-18 months constrain staffing for classified government contracts and defense-adjacent commercial work.
- Technical debt remediation complexity:Mainframe and COBOL estates in banking and insurance sectors resist cloud-native refactoring, requiring expensive strangler-fig migration patterns that extend project timelines.
- Carbon reporting integration:Streamlined Energy and Carbon Reporting mandates force IT service providers to attribute Scope 3 emissions across complex multi-vendor supply chains with immature measurement standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom IT Services Market |
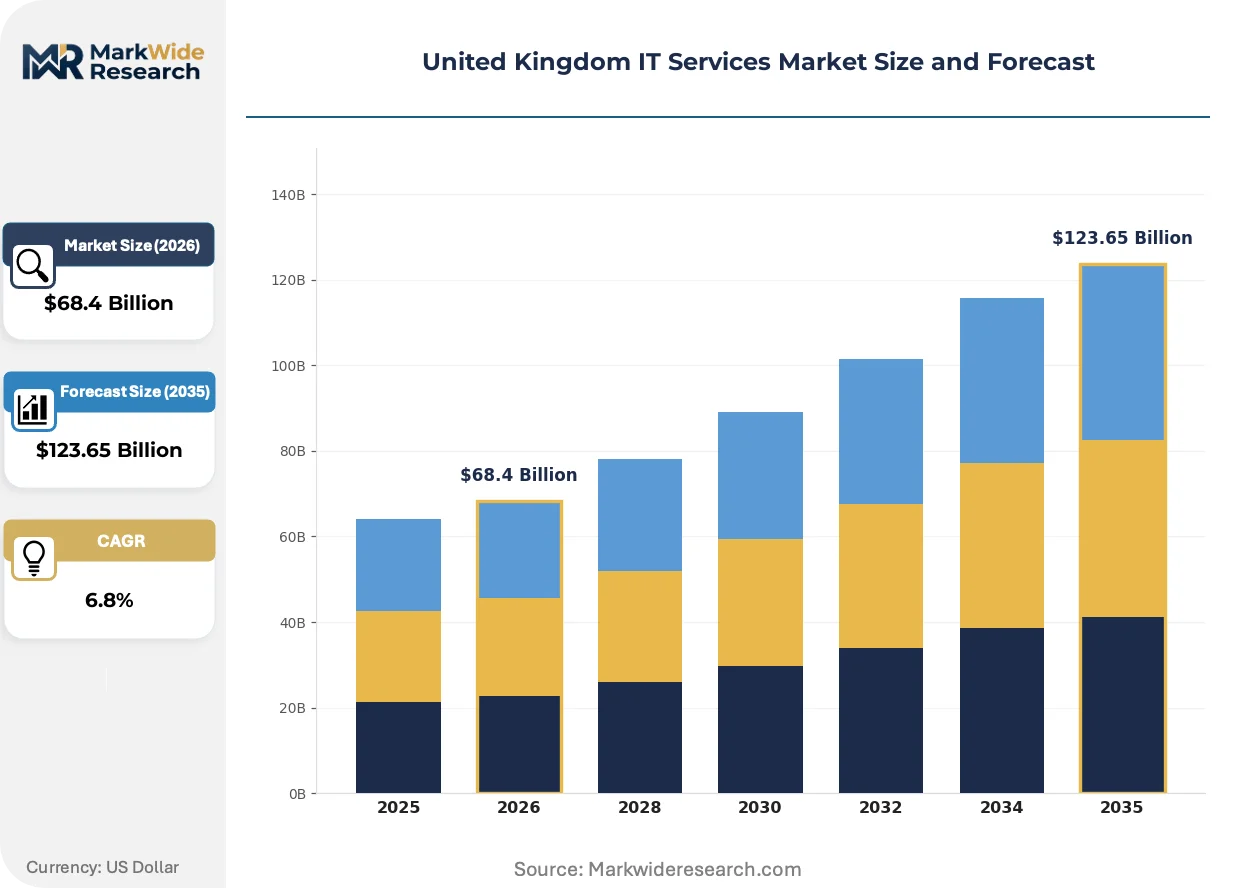
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Consulting, Managed Services, Software Development End User: Small Enterprises, Large Corporations, Government Agencies, Non-Profit Organizations Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud Industry Vertical: Healthcare, Finance, Education, Retail |
| Companies Covered | TCS, Capgemini, IBM, Cognizant, Accenture, Atos, Wipro, Infosys, Hewlett Packard Enterprise, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom IT Services Market Evolving Landscape
Generative AI tooling is compressing software development lifecycles and reconfiguring service delivery models across the UK IT services landscape. Three developments warrant particular attention.
Container orchestration is hybridizing enterprise infrastructure strategies. Kubernetes platforms enable consistent deployment patterns across on-premises VMware estates, UK sovereign cloud regions, and hyperscale public cloud. Financial services firms in the City of London are adopting these patterns fastest, driven by operational resilience requirements. The technology is hybridizing procurement approaches by collapsing distinctions between managed infrastructure and platform engineering services.
The UK AI White Paper and forthcoming statutory guidance from the Department for Science, Innovation and Technology are establishing sector-specific accountability frameworks. These measures impose documentation and testing obligations on AI system deployers that exceed current ISO management system standards. Healthcare and financial services sectors face the steepest compliance curves, with NHS trusts already requiring algorithmic impact assessments for diagnostic imaging workflows.
Enterprise buyers are consolidating vendor relationships to reduce interface complexity and aggregate purchasing leverage. Multi-year transformation contracts now bundle infrastructure, application development, and managed security under single accountability structures. This pattern is most pronounced among FTSE 250 companies headquartered in London and the South East, where procurement functions have matured vendor risk management capabilities.
United Kingdom IT Services Market Segmentation
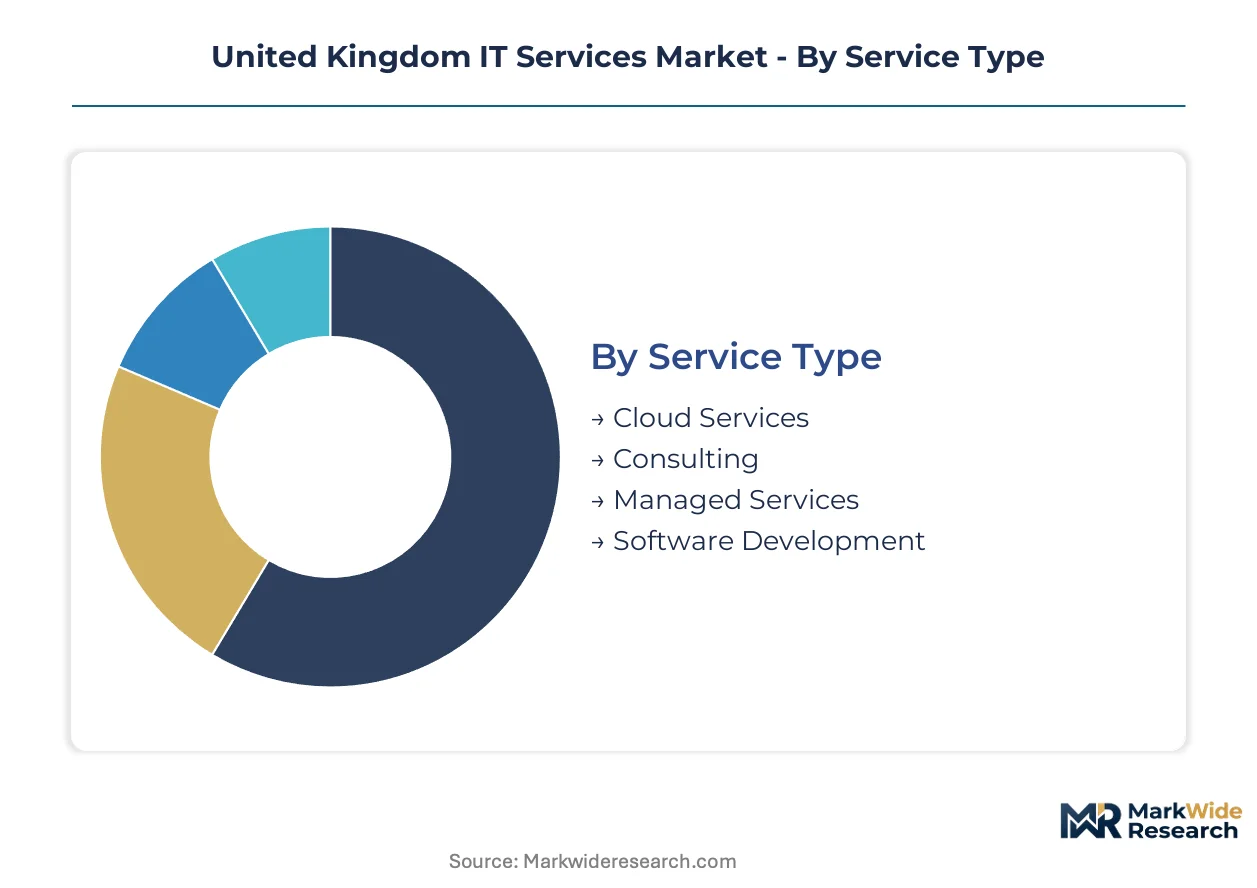
Service delivery configurations in the United Kingdom IT Services Market vary sharply by regulatory exposure, data sovereignty requirements, and legacy estate complexity. Procurement patterns cluster around compliance-driven segments where Crown Commercial Service frameworks and NCSC mandates create non-negotiable qualification thresholds.
Service Type:
Cost tier stratification separates commodity maintenance from premium advisory and engineering capabilities across UK buyer portfolios.
- Managed Services:Infrastructure monitoring, patch management, and legacy system maintenance delivered under fixed-fee arrangements with defined SLA matrices. Demand concentrates among FTSE 350 firms in London and the South East seeking to offload operational overhead from shrinking internal IT departments amid SRE talent scarcity.
- Cloud Services:Migration, modernization, and ongoing optimization of workloads across sovereign and hyperscale cloud regions. NHS trusts and financial services firms in Edinburgh and Manchester are driving procurement as post-Brexit data localization requirements harden.
- Consulting:Strategic advisory for digital transformation, ERP modernization, and post-merger integration.
- Software Development:Custom application engineering with specialized strength in fintech regtech and healthtech domains.
Managed Services holds installed capacity. Cloud Services is rotating up the share rankings.
End User:
Application intensity diverges between regulated institutions with complex compliance obligations and leaner organizations prioritizing cost-engineered delivery.
- Government Agencies:Central government departments, NHS trusts, and local authorities procuring through Crown Commercial Service frameworks with mandatory ISO 27001 and Cyber Essentials Plus certification. The NCSC Cyber Assessment Framework deadline is accelerating consolidated sourcing for managed detection and response capabilities.
- Large Corporations:FTSE-listed enterprises with multi-year transformation budgets and established vendor risk management functions. Financial services firms face Prudential Regulation Authority operational resilience mandates requiring mapped third-party dependencies and tested recovery capabilities.
- Small Enterprises:Mid-market firms with limited procurement sophistication and acute price sensitivity.
- Non-Profit Organizations:Charities and social enterprises with constrained budgets and grant-dependent funding cycles.
Large Corporations dominate current contract value. Government Agencies are climbing the fastest as NHS digital transformation programs expand.
Deployment Model:
Volume distribution reflects tension between legacy estate preservation and cloud-native replacement timelines across UK infrastructure strategies.
- Hybrid Cloud:Kubernetes-orchestrated workloads spanning on-premises data centers, UK sovereign cloud regions, and hyperscale public cloud with consistent deployment patterns. Financial services firms in the City of London are adopting these configurations fastest to satisfy operational resilience requirements while avoiding vendor lock-in.
- Public Cloud:Native consumption of compute, storage, and platform services from hyperscale providers with UK regions. Cost optimization and rapid scalability attract growth-stage technology firms and digital-native startups concentrated in London and Cambridge.
- Private Cloud:Single-tenant infrastructure dedicated to individual organizations with stringent data isolation requirements.
- On-Premises:Traditional data center and colocation arrangements for latency-sensitive or classified workloads.
On-Premises retains substantial installed base. Hybrid Cloud is gaining share fastest as Kubernetes platforms mature.
Industry Vertical:
Customer type differentiation tracks regulatory intensity, legacy technical debt, and digital maturity across UK sectoral economies.
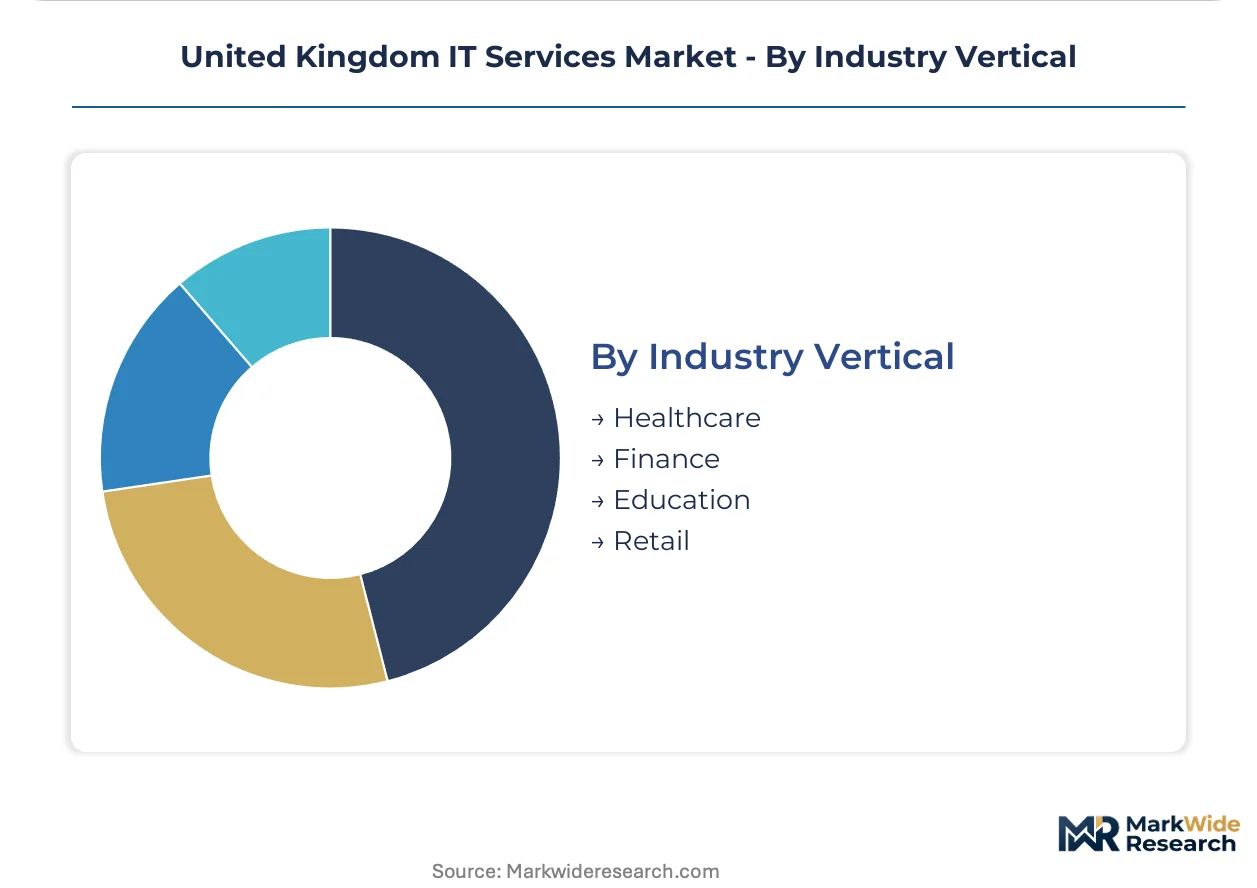
- Finance:Banking, insurance, and asset management institutions governed by Prudential Regulation Authority and Financial Conduct Authority mandates. Operational resilience directives and AI sovereignty concerns are expanding contracts for GPU-as-a-service infrastructure and algorithmic governance tooling.
- Healthcare:NHS trusts, private hospital groups, and health technology vendors implementing Federated Data Platforms and electronic patient record consolidation. Algorithmic impact assessments for diagnostic imaging workflows are already mandatory procurement filters.
- Retail:Omnichannel merchants and grocery chains with seasonal demand volatility and thin margins.
- Education:Universities and further education colleges with fragmented procurement autonomy and research computing requirements.
Finance commands premium pricing power. Healthcare is expanding most quickly as NHS digital funding pipelines lengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London commands premium pricing for NCSC-certified managed security services while Manchester and Edinburgh compete on cost-engineered delivery. This asymmetry shapes procurement patterns across the United Kingdom IT services landscape.
London and the South East
Financial services firms in the City of London drive demand for GPU-as-a-service infrastructure and algorithmic governance tooling. The Prudential Regulation Authority's operational resilience mandates require mapped third-party dependencies and tested recovery capabilities. Canary Wharf and the Square Mile host concentrated sourcing for multi-year transformation contracts bundling infrastructure, application development, and managed security.
Midlands
Automotive and advanced manufacturing clusters in Birmingham and Coventry generate demand for industrial IoT integration and legacy ERP modernization. The region's universities feed graduate pipelines into platform engineering and SRE roles. Birmingham's growing fintech sector is expanding procurement of regtech compliance automation.
North England
Manchester and Leeds delivery centers exploit lower commercial real estate costs to offer cost-competitive nearshore models for London-headquartered clients. NHS trusts in the region are implementing Federated Data Platforms and electronic patient record consolidation. The Northern Powerhouse initiative is accelerating public sector digital transformation funding.
Scotland
Edinburgh's financial services sector and Glasgow's university research computing drive specialized demand. The Scottish Government's digital strategy is expanding Crown Commercial Service framework procurement for cloud migration. Data center operators in Scotland leverage cooler climates and renewable energy access for carbon-efficient hosting.
Wales and Northern Ireland
Cardiff and Belfast are developing cyber security specialization aligned with UK government defense-adjacent contracting. Security clearance processing delays constrain staffing for classified contracts. Lower operating costs attract contact center and back-office IT service delivery.
United Kingdom IT Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying niche capabilities. The United Kingdom IT services market exhibits tiered concentration with global systems integrators anchoring large enterprise contracts and mid-tier providers competing on domain specialization. Three strategic archetypes dominate: consulting-led transformation platforms, cost-engineered offshore delivery networks, and sovereign cloud infrastructure operators. Competitive moves center on channel partnerships with hyperscale providers and geographic expansion of UK delivery centers to offset talent cost inflation.
Among India-based delivery networks, TCS, Infosys, and Wipro exemplify the cost-engineered offshore archetype, leveraging UK delivery centers in Glasgow, Manchester, and Leeds to balance rate competitiveness with data sovereignty requirements. These firms occupy positions that emphasize scale-driven resource deployment against regulatory constraints on cross-border data flows.
| Leading Market Players |
|---|
| TCS |
| Capgemini |
| IBM |
| Cognizant |
| Accenture |
| Atos |
| Wipro |
| Infosys |
| Hewlett Packard Enterprise |
| Others |
Value Network & Pricing Analysis
Channel freight corridors connecting UK Tier 3+ data centers to hyperscale cloud regions govern cost-to-serve calculations for domestic infrastructure operators. London-Manchester fiber routes and transatlantic cable landings at Cornwall and Scotland concentrate supply-side leverage among Crown Commercial Service-certified providers, compressing margins for uncertified competitors while enabling premium pricing for NCSC-assured workloads.
Pricing Analysis
Customization-premium spreads separate configured-to-order managed security contracts from standardized cloud migration packages. Subscription-based SaaS tiers dominate, with price differentiation anchored in Cyber Essentials Plus certification grade and SRE talent scarcity. Pricing pressure intensifies downward as Indian delivery networks expand Glasgow and Leeds centers, though FTSE 350 buyers show lowest sensitivity for sovereign AI infrastructure. Mid-market enterprises exhibit acute price responsiveness to hyperscale alternatives.
Supply Chain Analysis
Upstream feedstock dependencies center on GPU accelerator procurement from Taiwan and USA, alongside UK-based renewable energy contracts for carbon-efficient hosting. Software licensing costs from Ireland and USA, plus fiber optic infrastructure from China and Japan, complete critical input matrices. Single-source vulnerability concentrates in NVIDIA supply for AI sovereignty infrastructure. Distribution runs through direct enterprise sales teams and hyperscale marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom IT Services Market constitutes a high-growth disruption as post-Brexit data sovereignty mandates and NCSC compliance deadlines force structural procurement shifts away from EU-based hyperscalers toward domestic certified providers.
For Market Incumbents: Build switching-cost moats through deep Crown Commercial Service framework entrenchment and multi-year NHS digital transformation contracts. Anchor against margin compression from Indian delivery networks by embedding algorithmic governance tooling into managed security offerings. Prioritize Security Check-cleared talent pipelines to bypass clearance bottlenecks constraining defense-adjacent competitors. For New Entrants and Emerging Players: Northern England delivery center scarcity presents immediate white-space opportunity, with Manchester and Leeds offering 30-40% commercial real estate cost advantages versus London. Target mid-market financial services firms in Edinburgh and Birmingham facing Prudential Regulation Authority operational resilience mandates but lacking FTSE 100 procurement sophistication. Lead with GPU-as-a-service offerings addressing Financial Conduct Authority AI sovereignty concerns. For Investors and Strategic Acquirers: Carve-out targets emerge from hyperscale cloud providers' UK sovereign cloud divisions and legacy systems integrators' healthtech practices. Long-term viability favors operators with Crown Commercial Service accreditation depth and Kubernetes-native platform engineering capabilities. Watch NHS Federated Data Platform contract awards as inflection indicator for sector consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| NCSC Certification Investment | Crown Commercial Service framework eligibility unlocks central government and NHS procurement pipelines worth multi-year contract volumes. |
| UK Sovereign Cloud Region Buildout | Post-Brexit data localization requirements displace EU-hyperscale workloads toward domestic Tier 3+ facilities. |
| GPU-as-a-Service Launch | Financial Conduct Authority AI infrastructure guidance creates compliant training environments for proprietary financial models. |
| Scotland Delivery Center Expansion | Glasgow and Edinburgh university pipelines feed cost-competitive SRE talent for London-headquartered client delivery. |
| Healthtech Domain Acquisition | NHS electronic patient record consolidation and algorithmic impact assessment mandates reward specialized systems integrators. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this study. CTOs, IT procurement officers at FTSE-listed enterprises, platform engineers, and Crown Commercial Service framework managers provided operational perspectives. Secondary sources include NCSC guidance documents, Prudential Regulation Authority operational resilience directives, NHS digital transformation program disclosures, and hyperscaler UK region capex announcements. Bottom-up service line modeling and top-down macroeconomic calibration ensure triangulated output reliability.
Calibration against historical contract award patterns and talent cost indices shapes the projection framework across the analysis window. Segmentation dimensions span service type, deployment model, organization size tier, vertical regulatory intensity, and regional delivery center proximity. CAGRs derive from weighted average of demand elasticity estimates and supply-side capacity expansion schedules. Kubernetes adoption curves and Security Check processing timelines constitute industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian delivery networks or accelerated NHS funding disbursement would shift outcomes. Cross-checking against Crown Commercial Service contract award registers and NCSC certification issuance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Parametric Design Software Market
Software & Services
Employee Engagement Solutions Market
Software & Services
Petcare Software Market
Software & Services
Kennel Management Software Market
Software & Services
Decision Support System (DSS) Software Market
Software & Services
Global Home Inspection Software Market
Software & Services
Global Online Assessment Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Global Quoting Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Europe Saas-Based SCM Market
Software & Services
Digital Customer Onboarding Software Market
Software & Services
Global Catalog Management Systems Market
Software & Services
Canada HR Payroll Software Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Global Automation Software Market