
 Global Non Lethal Weapons Market | 2026-2036
Global Non Lethal Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non Lethal Weapons Market Intelligence
The integration of network connectivity and data-logging capabilities into electroshock devices is reorganizing the competitive landscape for law enforcement suppliers. This shift prioritizes systems that provide accountability and evidence capture over standalone tools. Axon Enterprise, Inc. leverages its ecosystem of connected devices and software to secure a dominant position. Meanwhile, Rheinmetall AG competes on the strength of its diversified portfolio for military and security force applications, while Combined Systems, Inc. specializes in crowd control solutions.
Non-lethal weapons are designed to incapacitate targets with a minimal probability of causing death or permanent injury. These devices, such as electroshock weapons delivering a specific electrical charge or chemical sprays containing oleoresin capsicum, serve to de-escalate conflicts without lethal force. Within product types, electroshock devices and chemical sprays command the largest share for personal and law enforcement use. The crowd control application segment represents the fastest-growing area, driven by procurement from law enforcement and military forces.
Market access and product design are governed by a patchwork of national regulations. In the United States, standards for law enforcement use are influenced by case law and departmental policies, while in Europe, CE marking ensures compliance with health and safety standards. The adoption of specific GB standards in China also dictates product specifications for domestic use. Navigating these disparate legal frameworks for use-of-force is a critical decision point for manufacturers expanding their geographic footprint.
Market Dynamics
The central dynamic in the non-lethal weapons market is the pivot from standalone incapacitation tools to integrated, data-centric systems. This shift is driven by law enforcement and military demand for accountability, evidence capture, and use-of-force analysis.
Growth Catalysts
- Police Modernization Programs:Government initiatives in the United States and India to equip law enforcement with advanced crowd control and de-escalation tools are a primary catalyst, specifying network-connected devices for enhanced oversight.
- Border Security Applications:Heightened geopolitical tensions are expanding the use case for non-lethal systems in border management, where they are deployed to manage migrant flows and deter incursions without escalating to lethal force.
- Directed Energy Advancements:Continuous innovation in directed energy technologies, such as acoustic and microwave devices, creates new operational capabilities for military and security forces, expanding the addressable market beyond traditional riot control scenarios.
Market Restraints
- Fragmented Regulatory Frameworks:Manufacturers face significant compliance hurdles due to a patchwork of national and local use-of-force laws, from CE marking requirements in Europe to disparate departmental policies across the United States.
- Public and Legal Scrutiny:Intense public debate and legal challenges regarding the safety and ethical use of devices like electroshock weapons can lead to restrictive operational protocols or outright bans, limiting market potential.
- High Unit Costs:The significant cost of advanced non-lethal systems, particularly directed energy weapons, compared to conventional alternatives like tear gas or rubber bullets, constrains procurement budgets for smaller agencies or in developing nations.
Strategic Opportunities
- Emerging Market Penetration:Untapped demand exists in Latin American and Southeast Asian megacities, where urban policing authorities are seeking modern solutions to manage civil unrest and organized crime with reduced lethality.
- Maritime Security Systems:The development of long-range acoustic devices and other non-lethal deterrents for anti-piracy and vessel protection roles opens a distinct and valuable new application segment for manufacturers.
- AI-Powered Targeting:Integrating artificial intelligence for object recognition and threat assessment into weapon systems offers a path to creating smarter devices that can minimize collateral harm and improve engagement accuracy.
Industry Challenges
- Complex Certification Pathways:The time and expense required to navigate stringent testing and approval processes, such as those mandated by specific GB standards in China, create substantial barriers to entry and slow product launch timelines.
- System Integration with Legacy Software:Ensuring seamless interoperability between new, connected non-lethal weapons and the diverse, often outdated, evidence management and command-and-control software used by police departments is a major technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non Lethal Weapons Market |
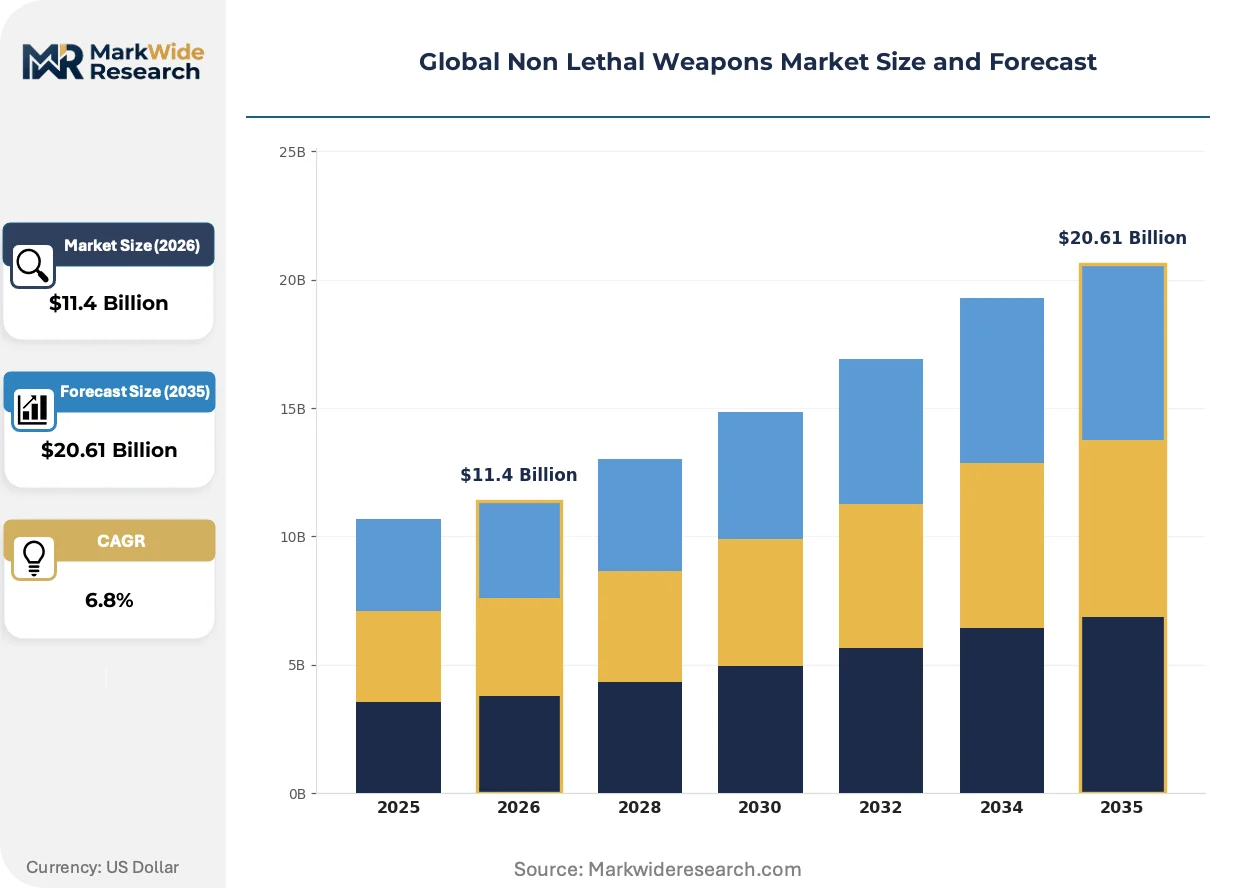
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroshock Devices, Chemical Sprays, Acoustic Weapons, Directed Energy Arms, Net Guns Technology: Infrared, Ultrasonic, Microwave, Sonic, Optical Application: Crowd Control, Personal Defense, Military Training, Correctional Facilities End User: Law Enforcement, Military Forces, Security Agencies, Private Protection Firms |
| Companies Covered | Axon Enterprise, Inc., Combined Systems, Inc., Safariland, LLC, Rheinmetall AG, BAE Systems, RTX Corporation, AMTEC Less-Lethal Systems Inc., Byrna Technologies Inc., FN Herstal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non Lethal Weapons Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of incapacitation hardware with sophisticated data ecosystems. This trend prioritizes accountability and tactical analysis, moving the value proposition from a simple tool to a comprehensive evidence-gathering and force-management platform.
Directed energy weapon technology serves to incapacitate targets using focused energy like microwaves or sound waves. Adoption is accelerating within specialized military and border control units for area denial and crowd dispersal. The core technology is miniaturizing from large, vehicle-mounted systems to man-portable configurations, enabling deployment by individual operators in complex tactical situations.
European Union regulations, particularly the forthcoming EU AI Act, are establishing a risk-based legal framework for intelligent systems. This legislation directly impacts the design of next-generation smart weapons by mandating transparency, human oversight, and data governance. Manufacturers targeting the European market must now engineer their products for compliance, affecting development roadmaps for systems with automated targeting features.
A distinct behavioral shift in purchasing is evident as agencies move from acquiring individual devices to procuring complete safety and evidence platforms. This disrupts the role of traditional single-product distributors, favoring suppliers who offer an integrated ecosystem of hardware, software, and cloud storage. This pattern is most pronounced among law enforcement bodies in North America seeking to unify their body-worn camera, electroshock weapon, and digital evidence workflows.
Global Non Lethal Weapons Market Segmentation
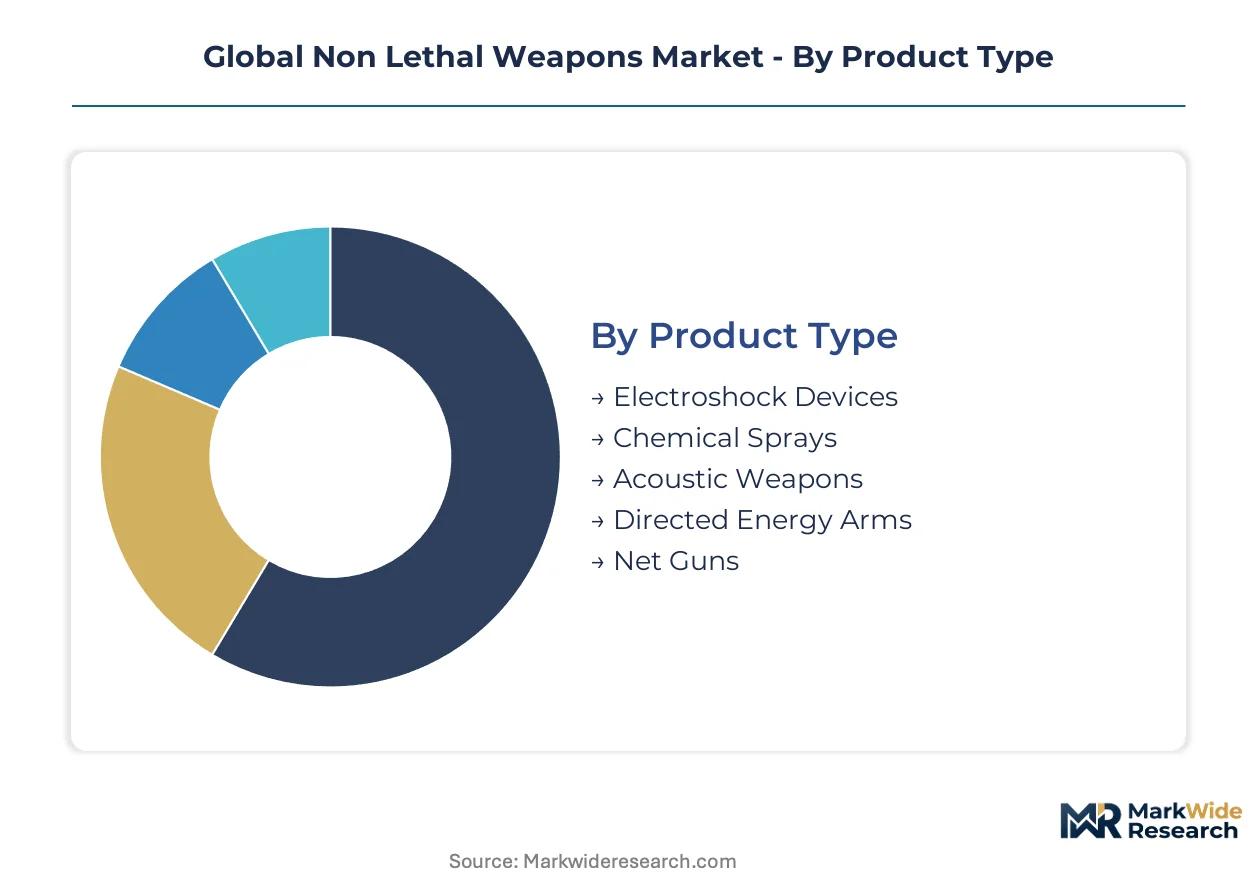
The non-lethal weapons market segments across product type, underlying technology, specific application, and primary end-user. Understanding these distinct segments provides clarity on procurement patterns and technological priorities for security forces globally.
Product Type:
The product type segmentation highlights the varying regulatory acceptance and operational deployment across different national contexts, influencing which devices dominate domestic procurement versus export-led markets.
- Electroshock Devices:These devices deliver a controlled electrical charge to temporarily incapacitate a target, often featuring integrated cameras for evidence capture. Law enforcement agencies in the United States and Europe widely procure these for de-escalation and subject control.
- Chemical Sprays:Containing irritants like oleoresin capsicum, these sprays cause temporary sensory incapacitation without lasting harm. Indian police forces and private security firms frequently use chemical sprays for crowd dispersal and personal defense.
- Acoustic Weapons:These systems utilize focused sound waves to deter or disperse individuals over a distance, often employed in maritime security. Military units deploy long-range acoustic devices for area denial and anti-piracy operations.
- Directed Energy Arms:These advanced systems project focused energy, such as microwaves or millimeter waves, to create discomfort and deter targets. Specialized military and border control units are exploring directed energy for perimeter defense and non-lethal interdiction.
- Net Guns:Net guns deploy a physical net to entangle and restrain a target from a distance. Correctional facilities and animal control agencies use net guns for safe apprehension.
Electroshock Devices holds the largest share; momentum sits with Directed Energy Arms.
Technology:
The technology segment reflects the underlying scientific principles and engineering innovations that enable non-lethal incapacitation, with advancements often driven by military research and then adapted for civilian security applications.
- Ultrasonic:This technology uses high-frequency sound waves, beyond human hearing, to create discomfort or disorientation. Specialized security units employ ultrasonic devices for perimeter control and area denial in sensitive locations.
- Microwave:Microwave systems project electromagnetic radiation to heat the skin's surface, causing a repelling sensation without permanent injury. Military forces are developing microwave-based systems for crowd dispersal and checkpoint security.
- Infrared:Infrared technology is primarily used for target acquisition and surveillance components within non-lethal systems, rather than direct incapacitation. Border security operations integrate infrared sensors for enhanced situational awareness during nighttime deployments.
- Sonic:Sonic technologies use audible sound waves, often at high decibel levels, to deter or disperse individuals. Crowd control applications leverage sonic devices for managing large gatherings and maintaining order.
- Optical:Optical systems employ intense light or lasers to temporarily blind or disorient targets. Naval forces utilize optical dazzlers for deterring small vessel approaches and enhancing maritime security.
Microwave technology is experiencing significant investment, while Ultrasonic systems continue to evolve for niche applications.
Application:
The application segment highlights the diverse operational contexts where non-lethal weapons are deployed, with procurement decisions heavily influenced by the specific threats and regulatory environments faced by different user groups.
- Crowd Control:This application involves managing and dispersing large groups of people using non-lethal means to prevent violence or maintain public order. Law enforcement agencies in major urban centers regularly procure systems designed for effective crowd management.
- Personal Defense:Individuals utilize non-lethal devices for self-protection against potential threats without resorting to lethal force. Civilian markets in countries like the United States see consistent demand for personal defense products.
- Military Training:Non-lethal weapons are integrated into military exercises to simulate realistic combat scenarios and practice de-escalation techniques. Defense forces worldwide use these tools to enhance tactical readiness and reduce training risks.
- Correctional Facilities:These institutions deploy non-lethal devices to manage unruly inmates and maintain order within secure environments. Prison systems in North America and Europe prioritize tools that minimize injury to both staff and detainees.
Crowd Control applications represent the steepest expansion trajectory, with Personal Defense remaining a consistent volume driver.
End User:
The end-user segmentation reveals the primary organizations responsible for procuring and deploying non-lethal weapons, reflecting their distinct operational mandates, budget constraints, and regulatory oversight.
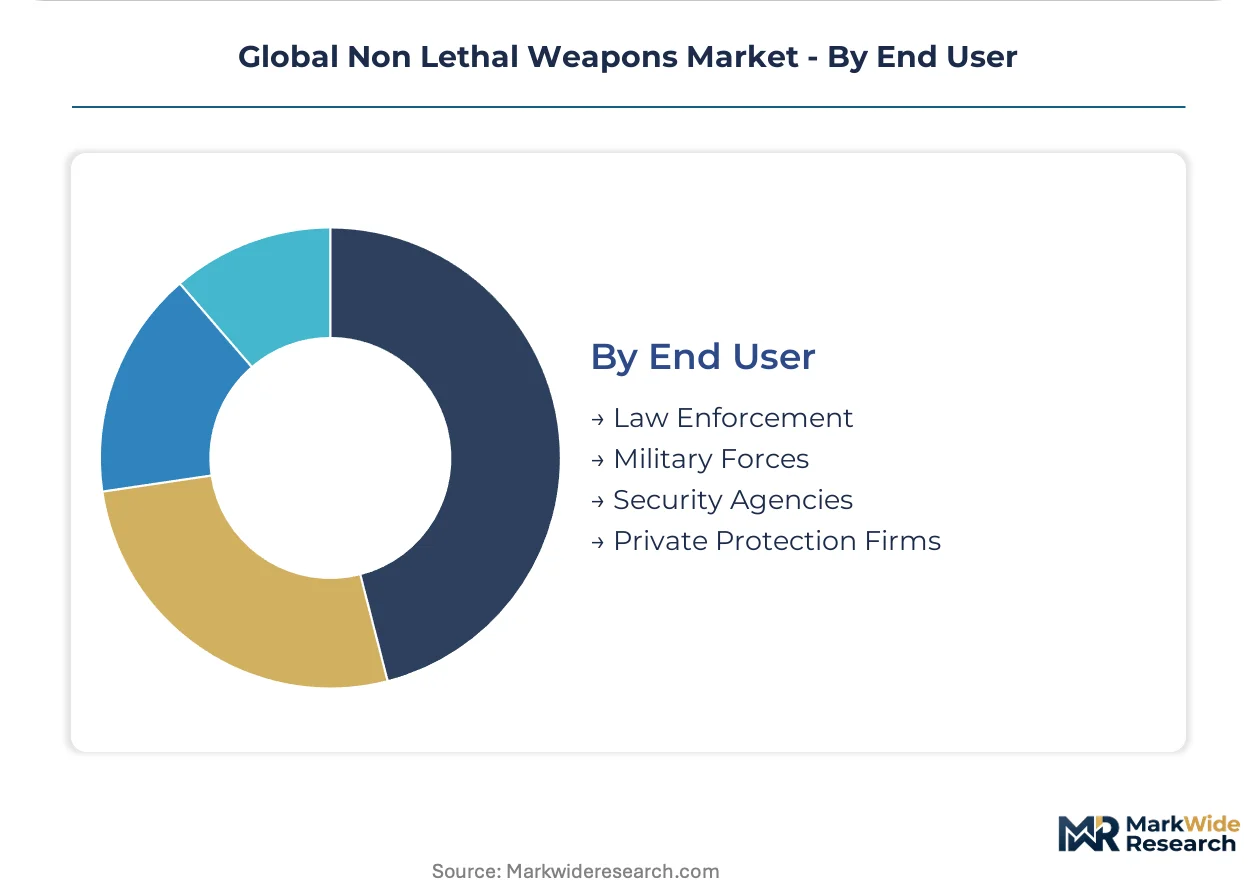
- Law Enforcement:Police departments and other civilian security forces employ non-lethal weapons for routine policing, crowd management, and de-escalation. Agencies in the United States are driving modernization efforts with integrated data-logging devices.
- Military Forces:National armed forces utilize non-lethal systems for peacekeeping missions, perimeter defense, and managing non-combatant populations. Defense ministries in Europe and Asia are investing in advanced directed energy technologies.
- Security Agencies:Government security organizations, including border patrol and intelligence services, deploy non-lethal tools for various protective and interdiction roles. Border security operations in India and the United States frequently use non-lethal systems.
- Private Protection Firms:Commercial security companies and private contractors use non-lethal weapons for asset protection, executive security, and event management. These firms often operate under specific regional licensing and use-of-force protocols.
Law Enforcement constitutes the largest purchasing segment, while Military Forces procurement indicates significant future technological advancements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Non-lethal weapons procurement exhibits varying price elasticity across different regions. Developed nations with robust budgets prioritize advanced, integrated systems, while developing countries often seek cost-effective, standalone solutions. This divergence shapes regional market dynamics and technology adoption.
United States
United States law enforcement agencies drive demand for integrated non-lethal systems, emphasizing accountability and evidence capture. Case law and departmental policies significantly influence the adoption and operational protocols for devices like electroshock weapons. Defense contractors in Virginia and tech clusters across California are innovating integrated hardware and software solutions for police forces.
India
India's market is propelled by border security operations and the need for effective crowd control solutions. The Ministry of Home Affairs' procurement policies prioritize non-lethal tools for managing public order and deterring incursions. Research centers in Hyderabad and defense manufacturers in Pune are focusing on developing cost-effective, locally manufactured non-lethal systems.
Germany
German military and security forces seek advanced non-lethal systems, particularly for diversified security applications. European CE marking regulations dictate product design and market access for all non-lethal weapons sold within the country. Industrial clusters around Munich and Düsseldorf are developing high-precision directed energy arms and integrated security solutions.
China
China's domestic non-lethal weapons market is driven by internal security requirements and border management. Compliance with specific GB standards is mandatory for all products, influencing design and manufacturing processes. Technology hubs in Shenzhen and research institutes in Shanghai are advancing indigenous directed energy weapons and crowd control devices.
United Kingdom
British police forces and military units are modernizing their non-lethal capabilities, particularly for de-escalation and maritime security. Home Office guidelines and national legal frameworks shape the operational deployment of non-lethal weapons. Defense clusters in Bristol and Farnborough are developing advanced acoustic weapons and integrated systems for naval protection roles.
Global Non Lethal Weapons Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the non-lethal weapons market. The market exhibits a tiered structure, with established defense contractors and specialized tech firms dominating advanced integrated solutions and data ecosystems. Smaller manufacturers often focus on niche product categories or offer more cost-effective, standalone incapacitation tools for budget-constrained agencies and emerging markets. Key competitive moves include portfolio diversification for military applications, strategic partnerships to integrate data-logging capabilities, and geographic expansion into new regions.
Archetypes focused on integrated data-centric systems include Axon Enterprise, Inc., a US-based corporation. This company exemplifies the shift towards comprehensive safety and evidence platforms, leveraging its ecosystem of connected devices and software. Meanwhile, Rheinmetall AG, a German Aktiengesellschaft, represents a diversified portfolio approach for broader military and security force applications, including advanced directed energy arms. Combined Systems, Inc., another US-based corporation, occupies a strong position specializing in crowd control solutions, offering a range of less-lethal munitions. These players anchor different segments of the market, from high-tech integration to specialized operational tools, shaping procurement patterns globally.
| Leading Market Players |
|---|
| Axon Enterprise, Inc. |
| Combined Systems, Inc. |
| Safariland, LLC |
| Rheinmetall AG |
| BAE Systems |
| RTX Corporation |
| AMTEC Less-Lethal Systems Inc. |
| Byrna Technologies Inc. |
| FN Herstal |
Cost & Logistics Intelligence
Extended lead times for advanced directed energy arms, driven by complex component sourcing, confer significant pricing power to specialized manufacturers. This supply chain dynamic influences procurement budgets for military forces globally.
Pricing Analysis
Software licensing and ongoing maintenance contracts represent a significant after-sales revenue tier, driving long-term value for integrated system providers. The dominant pricing model for non-lethal weapons is a hybrid of per-unit transactional hardware sales and subscription-based software services. Price differentiation is driven by certification levels, such as CE marking compliance, and the depth of integration with existing evidence management platforms. Pricing pressure stems from procurement budget constraints in emerging markets for advanced non-lethal solutions. Smaller municipal police departments exhibit high price sensitivity, while specialized military forces prioritize performance over cost.
Supply Chain Analysis
The United States anchors the production of integrated electroshock devices and software platforms, while Germany contributes advanced directed energy components. Supply chains draw from specialized electronics manufacturers for electroshock devices and rare earth elements critical for directed energy systems. A structural risk involves single-source vulnerability for specific microprocessors used in smart weapons. Distribution runs through direct sales channels to government procurement agencies and specialized defense contractors globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story, primarily due to significant regulatory entrenchment and the high switching costs associated with integrated evidence platforms. Agencies are locked into ecosystems once deployed, ensuring stable demand.
For Market Incumbents: Shield existing market share by accelerating R&D into miniaturized directed energy systems to counter emerging technological threats. Incumbents should strategically acquire niche AI firms to enhance threat assessment capabilities within their platforms. Investing in rigorous certification processes for new product lines, particularly across diverse European regulations, can secure market access against regional competitors. Deepening vertical integration into specialized sensor manufacturing can mitigate supply chain risks.
For New Entrants and Emerging Players: Post-deployment training and custom software integration for smaller law enforcement agencies represent a service-layer gap. New entrants should target Latin American megacities with cost-effective, modular crowd control solutions. The most penetrable segment involves standalone chemical spray and acoustic devices for private security firms in emerging markets. A compelling go-to-market angle involves offering cloud-agnostic software platforms designed for seamless integration with diverse legacy hardware systems.
For Investors and Strategic Acquirers: Long-term, this sits as a technology consolidation play because government agencies prioritize integrated solutions with high switching costs. Investors should seek specialized software firms offering AI-powered threat assessment or manufacturers of miniaturized directed energy components. These targets enhance ecosystem value and address evolving operational needs. The signal to watch is an increase in government procurement mandates for integrated data-logging and evidence capture capabilities across multiple security forces.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-Powered Targeting Module | This enhances engagement accuracy for law enforcement and minimizes collateral harm. |
| Platform Integration: Cross-Agency Data Sharing | This unifies evidence management workflows across diverse police departments. |
| Strategic Partnership: University Research Collaboration | This accelerates innovation in advanced acoustic and microwave technologies. |
| Geographic Expansion: Southeast Asian Markets | This addresses untapped demand for modern crowd control solutions in urban centers. |
| Capacity Expansion: Directed Energy Component Manufacturing | This secures critical supply for advanced military and border security applications. |
Research Approach
Findings reconcile primary fieldwork against secondary review of defense industry reports, government procurement databases, and academic studies on use-of-force. Primary interviews engaged law enforcement procurement officers, military strategists, security agency analysts, and non-lethal weapon manufacturers. This approach utilized both bottom-up market sizing and top-down validation to ensure data accuracy. Insights were triangulated across multiple independent sources.
Product type, underlying technology, specific application, end-user, and regional regulatory frameworks formed the core segmentation dimensions modeled across the analysis window. Compound Annual Growth Rates were derived from historical trends and projected growth drivers. The analytical framework integrated geopolitical tension indices and government defense spending allocations as key forecast inputs. This provided a robust projection throughout the forecast period.
Forecasts assume regulatory continuity in US, EU, India, and China; material policy shifts would require re-modeling. The projections reflect current market dynamics, acknowledging potential impacts from unforeseen use-of-force legislation or rapid technological obsolescence. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
National Security
Europe Non-Lethal Weapons Market
National Security
US Bulletproof Glass Market
National Security
Chemical, Biological, Radiological and Nuclear (CBRN) Security Market
National Security
Homeland Security Market
National Security
Service Handgun Market
National Security
Saudi Arabia Manned Security Market
National Security
Radiological and Nuclear Security Market
National Security
Research Department Explosive (RDX) Market
National Security
North America Non Lethal Weapons Market
National Security
Global Security Assessment Market
National Security
Asia-Pacific Border Security Market
National Security
Asia-Pacific Non-Lethal Weapons Market