
 US Bulletproof Glass Market | 2026-2036
US Bulletproof Glass Market Size, Share, and Industry Trends Forecast 2026-2036
US Bulletproof Glass Market Insights
Modular ballistic glazing kits is expanding as a preferred procurement format, letting facilities upgrade entry vestibules without full facade reconstruction. Total Security Solutions leverages in-house engineering to control specification-to-installation workflows. Armortex anchors its position through specialized manufacturing of fiberglass-reinforced frames paired with transparent armor. PPG Industries competes on optical clarity standards for high-threat architectural applications.
US bulletproof glass denotes transparent armor assemblies engineered to resist ballistic penetration, typically fabricated from alternating layers of glass, polycarbonate, and polyurethane interlayers bonded under heat and pressure to achieve specified threat-level ratings per NIJ Standard 0108.01. The primary purpose spans protecting personnel and assets in facilities and vehicles subject to armed attack or forced entry. Laminated glass and polycarbonate glass together command the dominant share of product type demand, with polycarbonate configurations gaining ground in retrofit transportation applications where weight reduction matters. Government facilities and correctional institutions represent the most structurally entrenched application segments, while VIP security applications carry the highest margin pools due to customization intensity and short production runs.
The National Institute of Justice sets ballistic resistance benchmarks that determine product eligibility for federal procurement, while OSHA workplace safety guidelines influence installation protocols in commercial environments. The Department of Homeland Security grant programs for school hardening and critical infrastructure protection directly shape demand timing and specification tiers across state and municipal buyers. Stakeholders must monitor evolving UL 752 revision cycles and state-level procurement consolidation trends to anticipate specification migrations and qualification barriers.
Market Dynamics
School districts across Texas and Florida are accelerating ballistic-resistant glazing procurement, while federal courthouse modernization programs compress specification timelines. This dual-channel demand surge is forcing manufacturers to reconfigure production workflows around modular kit formats.
Growth Catalysts
- NIJ Standard 0108.01 Revision:Tightened performance benchmarks for transparent armor systems are disqualifying legacy products and opening specification windows for certified suppliers.
- Department of Homeland Security Grants:School hardening and critical infrastructure protection programs directly shape demand timing across state and municipal buyers.
- Polycarbonate Configurations:Weight reduction advantages in retrofit transportation applications are displacing traditional laminated glass in fleet upgrade cycles.
Market Restraints
- Optical-Grade Raw Material Concentration:Specialty polycarbonate resin supply concentrates among a limited supplier base, creating input cost volatility.
- Polyurethane Interlayer Pricing:Chemical feedstock fluctuations directly compress transparent armor margins at the fabrication tier.
- Installation Skill Scarcity:Ballistic glazing certification requirements exceed available qualified technician pools in secondary metropolitan markets.
Strategic Opportunities
- VIP Security Customization:Short production runs and high specification intensity generate margin pools unavailable in standardized government contracts.
- Modular Vestibule Kits:Facilities can upgrade entryways without full facade reconstruction, expanding addressable building stock.
- Correctional Institution Retrofit:Aging facility infrastructure across state prison systems creates replacement demand independent of new construction cycles.
Industry Challenges
- UL 752 Qualification Timelines:Extended certification cycles delay product commercialization and lock working capital in testing protocols.
- Specification-to-Installation Coordination:Fragmented project delivery models create accountability gaps between engineering, fabrication, and field teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Bulletproof Glass Market |
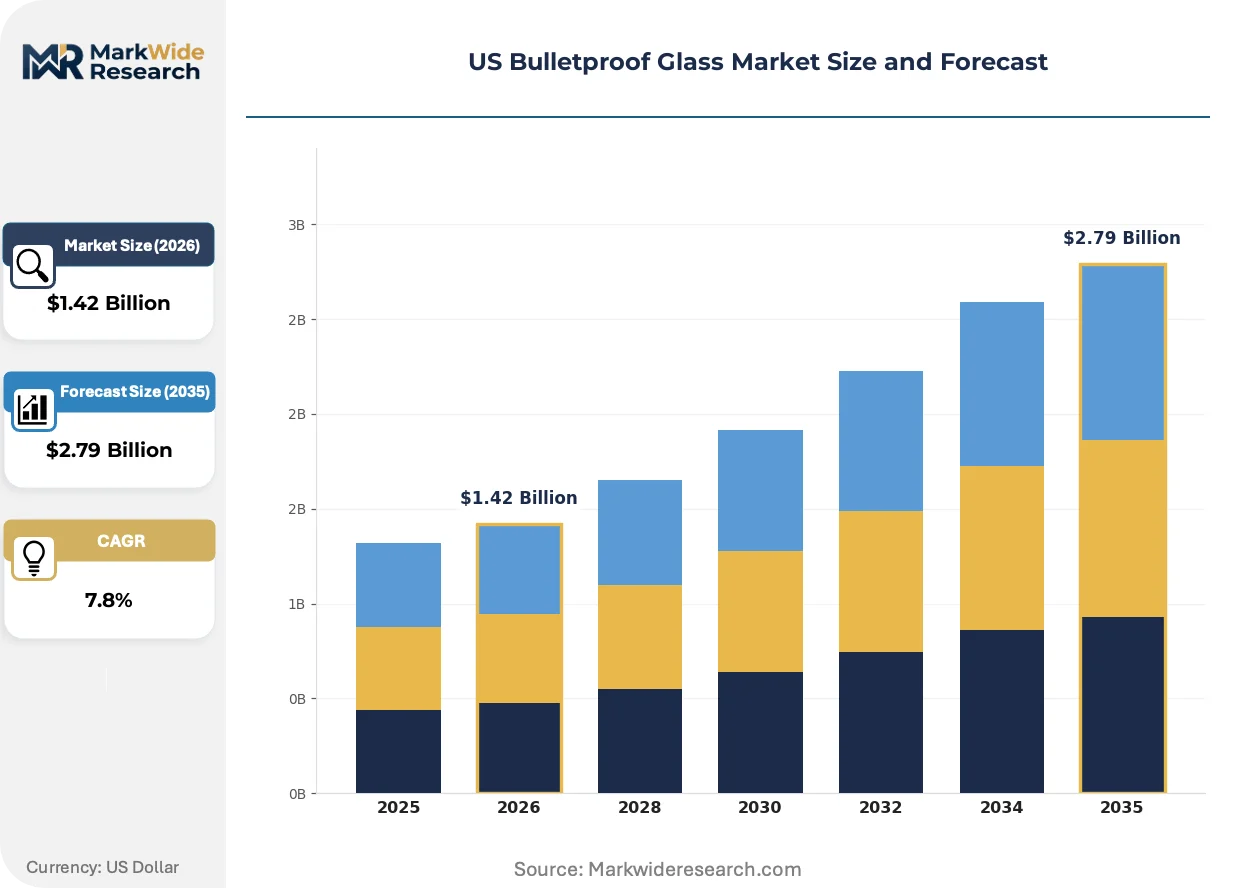
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laminated Glass, Tempered Glass, Acrylic Glass, Polycarbonate Glass, Hybrid Glass Application: Commercial Buildings, Government Facilities, Transportation Vehicles, VIP Security, Correctional Institutions End User: Security Contractors, Defense Agencies, Financial Institutions, Educational Institutions Distribution Channel: Direct Sales, Distributors, Online Retailers, System Integrators |
| Companies Covered | Total Security Solutions, Armortex, American Glass Products, Bullet Guard Corporation, Insulgard, Gaffco Ballistics, Precision Glass Bulletproofing, Apogee Enterprises, PPG Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Bulletproof Glass Market Trends and Innovations
Fabrication workflows are converging around digital specification tools that compress design-to-installation intervals. Three distinct vectors are reshaping competitive positioning in transparent armor.
Transparent ceramic composites are integrating into high-threat architectural applications where optical clarity and multi-hit resistance converge. Federal courthouse security teams specify these assemblies for judge chambers and public entry points. The technology is integrating specification authority directly into engineering departments, bypassing traditional general contractor intermediaries.
OSHA workplace safety guidelines are tightening installation protocol requirements for commercial environments. Contractors must now document fall protection and material handling procedures during ballistic glazing retrofit projects. Retail banking and healthcare facility managers in California and New York are extending project timelines to accommodate compliance verification.
State-level procurement consolidation is compressing vendor qualification windows. Texas and Florida school districts now coordinate specification tiers through shared service agreements rather than independent RFP processes. Regional fabricators with established NIJ certification are capturing multi-district contracts that previously fragmented across local suppliers.
US Bulletproof Glass Market Segmentation
Transparent armor procurement in the United States follows rigid certification hierarchies that segment buyers by threat-level requirements and installation complexity. Specification tiers determine which fabricators qualify for federal courthouse contracts versus school hardening grants or VIP residential installations.
Product Type:
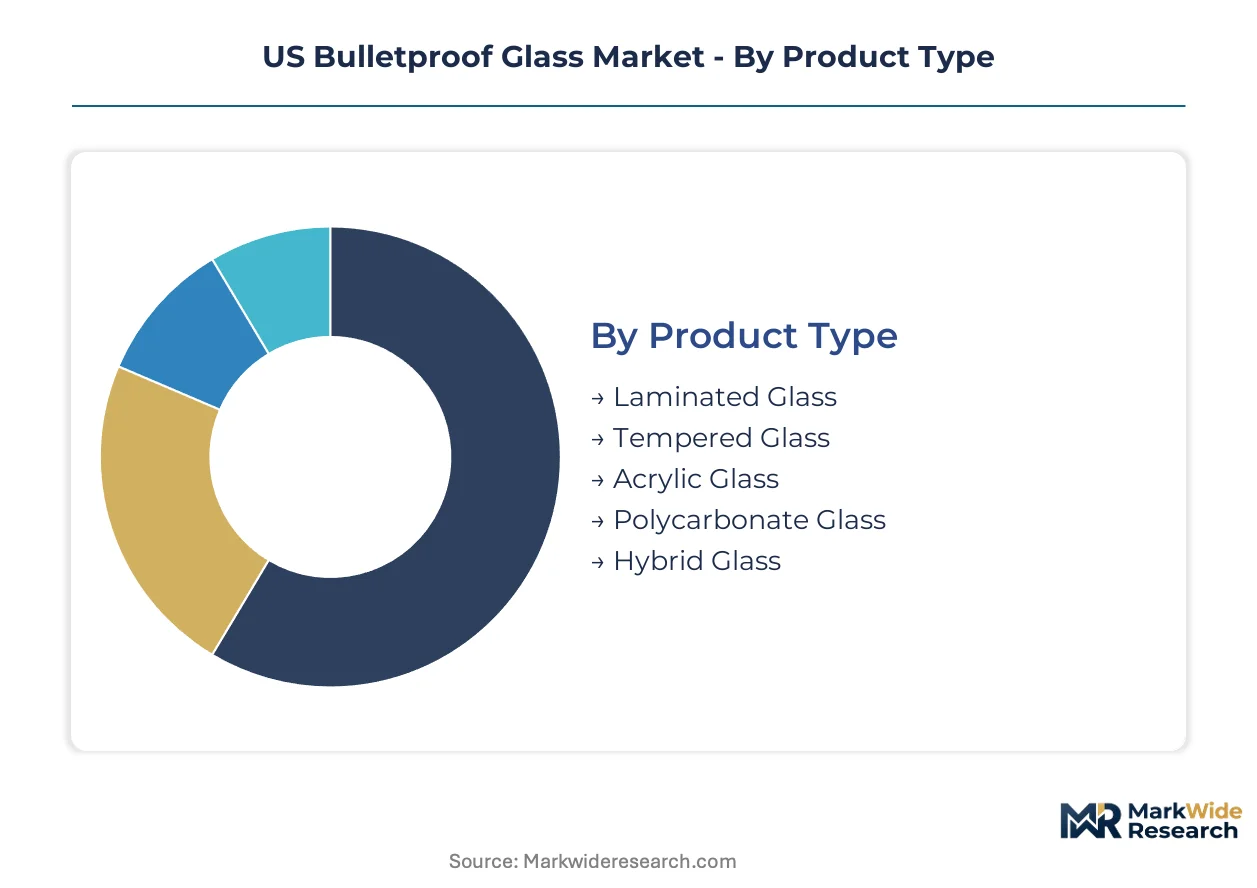
NIJ Standard 0108.01 and UL 752 certifications apply differentially across material compositions, with polycarbonate and hybrid configurations facing accelerated retesting schedules under the current revision cycle.
- Laminated Glass:Multiple glass layers bonded with polyvinyl butyral or polyurethane interlayers deliver optical clarity for federal courthouse judge chambers and witness protection environments. Texas and Florida school districts specify this format for entryway vestibules where visibility and ballistic resistance must coexist.
- Polycarbonate Glass:Solid thermoplastic construction achieves weight reductions of 60% versus all-glass assemblies, enabling retrofit installation in aging transportation fleets without chassis modification. Armored vehicle upfitters in Michigan and Ohio prefer this format for cash-in-transit vehicle modernization programs.
- Tempered Glass:Heat-strengthened monolithic panels serve lower threat-level applications where fragmentation resistance outweighs multi-hit requirements.
- Acrylic Glass:Cast polymethyl methacrylate sheets offer cost-effective transparent barriers for retail banking counters and pharmacy dispensing windows.
- Hybrid Glass:Glass-polycarbonate laminates combine optical performance with back-face spall control for correctional institution visitor booths.
Laminated glass sits at the top of the volume ranking, with polycarbonate glass climbing the fastest.
Application:
End-use segments stratify sharply by procurement channel, with federal agencies mandating NIJ-certified fabricators while commercial buyers prioritize speed-to-installation over maximum threat ratings.
- Government Facilities:Federal courthouse modernization programs compress specification timelines to 90-day windows, requiring transparent armor assemblies rated for rifle threats. The Administrative Office of the US Courts coordinates multi-site procurement through pre-qualified vendor pools.
- Correctional Institutions:State prison systems in California, Texas, and Florida drive replacement demand for aging visitor booth and control room glazing. These installations prioritize spall containment and forced-entry resistance over optical perfection.
- Commercial Buildings:Corporate headquarters and data centers specify transparent armor for lobby and executive floor protection, often through security consultant intermediaries.
- Transportation Vehicles:Armored SUV and cash-in-transit fleet operators demand lightweight configurations that preserve fuel efficiency and payload capacity.
- VIP Security:Residential and executive protection applications generate premium margins through custom fabrication and expedited delivery requirements.
Government facilities command the largest installed base, though correctional institutions are expanding most quickly as state infrastructure ages.
End User:
Buyer sophistication determines specification authority, with defense agencies retaining in-house ballistic engineering capabilities while educational institutions rely on DHS grant administrators for technical guidance.
- Defense Agencies:Department of Homeland Security and Department of Justice procurement officers specify transparent armor for federal protective service details and border inspection facilities. These buyers mandate full NIJ 0108.01 test documentation and supply chain origin verification.
- Security Contractors:Turnkey physical security providers bundle transparent armor with access control and surveillance systems for corporate and high-net-worth residential clients. These integrators prioritize single-source accountability and installation speed.
- Financial Institutions:Retail banking chains specify lower threat-level barriers for teller lines and ATM enclosures, often through national facilities management contracts.
- Educational Institutions:K-12 districts and university systems access DHS school hardening grants that restrict vendor selection to pre-approved product lists.
Defense agencies anchor procurement volume, with security contractors gaining share fastest as bundled service contracts displace direct material purchasing.
Distribution Channel:
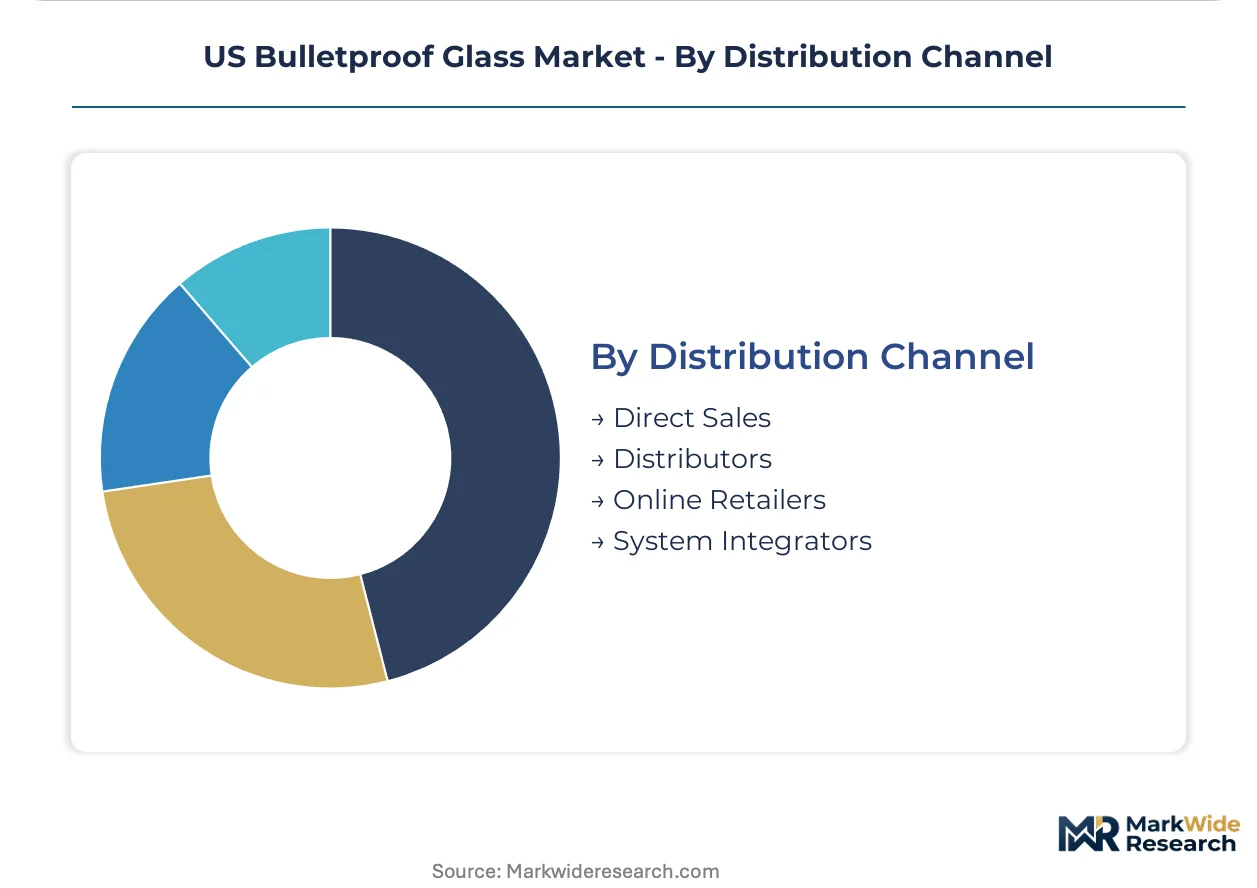
Channel selection correlates with project scale and technical complexity, with direct relationships dominating federal contracts while system integrators capture fragmented commercial demand.
- Direct Sales:Major fabricators maintain in-house specification engineering teams that interface directly with federal procurement officers and general contractors on courthouse and embassy projects. These relationships lock in multi-year supply agreements.
- System Integrators:Physical security contractors aggregate transparent armor with ballistic doors, access control, and surveillance into unified threat mitigation packages for corporate and institutional buyers.
- Distributors:Regional building material wholesalers stock standard threat-level panels for commercial retrofit and retail banking applications.
- Online Retailers:E-commerce channels serve small-scale residential and small business buyers with standardized panel sizes and DIY installation kits.
Direct sales channels capture the highest volume concentration, with system integrators expanding their share fastest as buyers demand single-source project accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transparent armor fabrication in the United States traces its industrial lineage to Cold War-era defense contracting clusters established around federal research facilities and automotive manufacturing belts.
Southwest
Texas school districts coordinate ballistic-resistant glazing procurement through shared service agreements that aggregate demand across multiple counties. The Department of Homeland Security school hardening grants flow through state education agencies to qualifying districts. Houston and Dallas-Fort Worth host specification engineering teams that interface directly with district facilities managers on modular vestibule installations.
Southeast
Florida districts mirror Texas consolidation patterns while adding hurricane-resistant glazing requirements that complicate ballistic specification selection. State procurement offices maintain pre-approved vendor lists that restrict contractor eligibility. Miami and Tampa fabrication shops specialize in hybrid assemblies that address both wind-borne debris and ballistic threat ratings.
Midwest
Michigan and Ohio armored vehicle upfitters drive polycarbonate configuration demand for cash-in-transit fleet modernization programs. The National Institute of Justice certification requirements determine product eligibility for federal protective service vehicle contracts. Detroit-area engineering firms coordinate specification workflows between automotive chassis modifiers and transparent armor fabricators.
West Coast
California correctional institutions generate replacement demand for aging visitor booth and control room glazing across state prison systems. OSHA workplace safety guidelines tighten installation protocol requirements for commercial retrofit projects in Los Angeles and San Francisco. Sacramento-based procurement offices coordinate multi-facility replacement schedules through consolidated state contracts.
Northeast
Federal courthouse modernization programs in New York and Washington compress specification timelines to ninety-day windows for transparent armor assemblies. The Administrative Office of the US Courts coordinates multi-site procurement through pre-qualified vendor pools. Philadelphia and Baltimore fabricators maintain direct sales relationships with federal procurement officers on embassy and courthouse security upgrades.
US Bulletproof Glass Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and specification complexity. The vendor base stratifies between NIJ-certified federal contractors and regional fabricators serving commercial retrofit demand. Three archetypes dominate: integrated engineering-to-installation providers, specialized ballistic frame manufacturers, and diversified materials conglomerates with transparent armor divisions. Consolidation pressure is accelerating through multi-district school procurement contracts and federal courthouse vendor pool qualification requirements.
Among integrated specification-to-installation providers, Total Security Solutions exemplifies the engineering-controlled workflow archetype through in-house project delivery capabilities. Armortex occupies a position within specialized frame manufacturing, pairing fiberglass-reinforced structural components with transparent armor assemblies. PPG Industries represents the diversified materials conglomerate tier, competing on optical clarity standards for high-threat architectural specifications. These three anchors illustrate the competitive segmentation between project-integrated specialists, component-focused manufacturers, and scale-driven materials platforms.
| Leading Market Players |
|---|
| Total Security Solutions |
| Armortex |
| American Glass Products |
| Bullet Guard Corporation |
| Insulgard |
| Gaffco Ballistics |
| Precision Glass Bulletproofing |
| Apogee Enterprises |
| PPG Industries |
| Others |
Pricing and Supply Chain Analysis
Polycarbonate configuration adoption in retrofit transportation applications simultaneously compresses per-unit fabrication costs and concentrates procurement leverage among certified suppliers. This technology transition rewards fabricators with captive resin supply relationships while squeezing margin pools for assembly-only operators dependent on spot-market polycarbonate sourcing.
Pricing Analysis
Three-tier pricing structure across NIJ-certified premium, UL-listed standard, and uncertified economy levels governs transparent armor transactions. Price differentiation centers on ballistic certification grade and installation complexity, with VIP security applications commanding substantial premiums over standardized government contracts. Cost compression in the economy tier is intensifying because acrylic substitution for glass-polycarbonate laminates accelerates in retail banking applications. Educational institutions accessing DHS school hardening grants exhibit highest price sensitivity, while federal courthouse procurement officers prioritize threat rating over unit cost.
Supply Chain Analysis
Refurbishment flows for aging correctional institution glazing create secondary material recovery channels that partially offset virgin polycarbonate demand. Raw material sourcing concentrates on Saudi Arabia and South Korea for specialty optical-grade resin, with US domestic production anchoring polyurethane interlayer supply. The fabrication tier rests on chemical feedstock volatility and single-source vulnerability in polycarbonate resin supply. Distribution runs through direct sales relationships for federal contracts, system integrators for commercial bundled security packages, and regional distributors for standardized commercial retrofit panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US bulletproof glass hinges on polycarbonate configuration standardization reducing per-unit labor intensity, while federal courthouse vendor pool consolidation shifts pricing power toward pre-qualified fabricators.
For Market Incumbents: Anchor federal courthouse vendor pool positions through accelerated NIJ 0108.01 recertification investments before specification windows narrow. Deepen backward integration into polyurethane interlayer production to offset chemical feedstock volatility eroding transparent armor margins. Threatened by regional fabricators capturing multi-district school procurement contracts through shared service agreements, incumbents must control specification-to-installation workflows to defend margin position. For New Entrants and Emerging Players: Capture correctional institution retrofit demand across California, Texas, and Florida state prison systems where aging infrastructure drives replacement cycles independent of new construction. The most penetrable white-space sits in modular vestibule kit fabrication for secondary metropolitan school districts lacking in-house specification engineering. A go-to-market angle through DHS grant administrator relationships offers faster qualification than direct federal courthouse vendor pool entry. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with established NIJ certification but limited installation capabilities, presenting rollup opportunities for integrated engineering-to-installation platforms. Long-term viability over the next decade favors suppliers with captive optical-grade polycarbonate sourcing and direct federal procurement relationships. The signal to watch is Texas and Florida school district procurement consolidation velocity, which determines whether regional players achieve scale sufficient to challenge national fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| NIJ Certification Investment | Secures eligibility for federal courthouse modernization programs and DHS school hardening grants. |
| Backward Integration into Resin | Captures optical-grade polycarbonate margin pools currently concentrated among limited suppliers. |
| Modular Vestibule Kit Development | Expands addressable building stock by enabling entryway upgrades without full facade reconstruction. |
| Multi-District Procurement Capture | Locks multi-year supply agreements through Texas and Florida shared service agreements. |
| Transparent Ceramic Composite R&D | Positions fabricators for federal courthouse judge chamber specifications requiring multi-hit resistance. |
Research Methodology
Bottom-up government facility and correctional institution modeling reconciled against top-down polycarbonate resin supply tracking forms the analytical core of this study. Primary interviews with ballistic glazing fabricators, DHS grant administrators, federal procurement officers, and state prison facilities managers combined with secondary validation against NIJ certification databases, UL 752 test records, and Department of Homeland Security grant disbursement reports. This approach triangulates demand-side project pipelines with supply-side capacity and certification constraints.
Historical trendline analysis of transparent armor procurement volumes across government, correctional, commercial, transportation, and VIP security segments established baseline growth patterns. The projection framework models product type, application, end user, and distribution channel dimensions across the analysis window, with CAGRs derived from threat-level specification migration rates and DHS funding authorization trajectories. Forecast inputs include NIJ standard revision implementation timelines and state-level procurement consolidation patterns.
Polyurethane feedstock price volatility, NIJ recertification delays, and school district funding authorization uncertainty are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding continued federal courthouse modernization program prioritization and sustained DHS school hardening grant flows. Practitioners should monitor UL 752 revision cycles and state procurement office vendor list updates for early signals of specification migration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
National Security
Global Non Lethal Weapons Market
National Security
Service Handgun Market
National Security
North America Non Lethal Weapons Market
National Security
Homeland Security Market
National Security
Saudi Arabia Manned Security Market
National Security
Radiological and Nuclear Security Market
National Security
Asia-Pacific Border Security Market
National Security
Global Security Assessment Market
National Security
Chemical, Biological, Radiological and Nuclear (CBRN) Security Market
National Security
Asia-Pacific Non-Lethal Weapons Market
National Security
Europe Non-Lethal Weapons Market
National Security
Research Department Explosive (RDX) Market