
 North America Non Lethal Weapons Market | 2026-2036
North America Non Lethal Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
North America Non Lethal Weapons Market Analytics
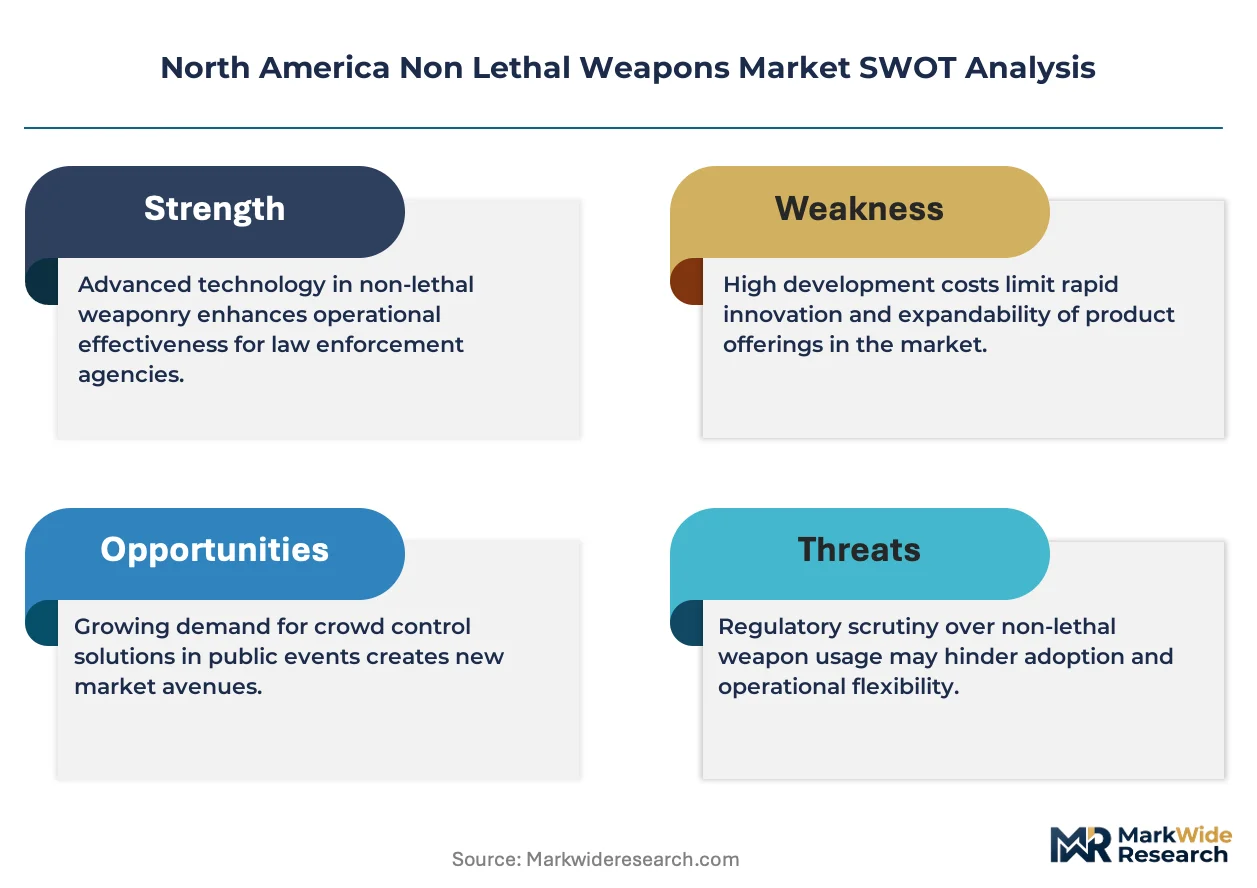
The capability gap between vertically integrated defense conglomerates and specialized less-lethal innovators is unwinding competitive dynamics in the sector. Axon Enterprise leverages its dominant channel position in conducted electrical weapons to sustain premium placement across U.S. law enforcement agencies. Combined Systems anchors its market presence through chemical agent manufacturing scale and established military contracts. Byrna Technologies competes in the civilian segment with compact chemical irritant launchers, differentiating through direct-to-consumer distribution.
Non lethal weapons encompass devices engineered to incapacitate, repel, or disorient targets without causing fatal injury, typically operating at kinetic energy levels below lethal thresholds or employing directed energy, chemical, or acoustic mechanisms. These systems serve primarily to expand force-option continuums for law enforcement and military operators while reducing fatality risks in crowd management and individual engagement scenarios. The product type dimension shows stun guns and electric shock devices capturing dominant share through recurring Taser deployments, while tear gas formulations face margin pressure from environmental litigation. The technology segment reveals kinetic energy weapons maturing in rubber projectile systems as active denial systems attract R&D investment for perimeter security applications.
Federal oversight from the National Institute of Justice shapes minimum performance standards for less-lethal devices, while state-level statutes in California and New York govern civilian possession and law enforcement deployment protocols. The Department of Defense's Non-Lethal Weapons Program coordinates inter-agency requirements, directly influencing procurement specifications for military end users. Stakeholders must monitor evolving use-of-force litigation trends and NIJ certification updates to anticipate product liability exposure and compliance-driven replacement cycles.
Market Dynamics
The National Institute of Justice certification requirements are compressing product development cycles and forcing manufacturers to redesign conducted electrical weapons around updated electrical output standards before legacy inventory expires.
Growth Catalysts
- NIJ Standard-0112.03:Federal testing protocols for conducted electrical weapons are mandating third-party validation, creating replacement demand across municipal police departments as agencies retire uncertified devices.
- Border security operations:U.S. Customs and Border Protection procurement of kinetic energy projectiles for crowd management scenarios is expanding volume requirements for less-lethal munitions.
- Directed energy systems:Active denial technology development for perimeter security applications is attracting defense R&D funding and accelerating technology maturation timelines.
Market Restraints
- Lithium battery supply concentration:Dependence on Asian cell manufacturers for Taser power systems creates input cost volatility and geopolitical exposure for domestic assemblers.
- Environmental litigation:California state courts are adjudicating tear gas discharge claims that threaten chemical irritant formulations with usage restrictions or liability exposure.
- Technical limitation:Effective range constraints on conducted electrical weapons—typically under 35 feet—limit officer safety margins in open-terrain engagements.
Strategic Opportunities
- Canadian municipal expansion:Royal Canadian Mounted Police and provincial police services are formalizing less-lethal deployment protocols, opening procurement channels for U.S. manufacturers with Health Canada device approvals.
- Civilian direct-to-consumer channels:Compact chemical irritant launchers are bypassing traditional law enforcement distributors through e-commerce platforms targeting private security and personal defense buyers.
- Technology convergence:Integration of body-worn camera systems with conducted electrical weapon activation logging is creating bundled procurement specifications that favor vertically integrated suppliers.
Industry Challenges
- NIJ certification timeline compression:Revised electrical output standards require complete product redesign and 18-month validation cycles, straining R&D budgets for mid-tier manufacturers.
- Biomechanical testing expertise shortage:Specialized engineers capable of modeling less-lethal projectile impact trauma are concentrated in defense contractors, creating hiring competition.
- Interoperability complexity:New conducted electrical weapons must integrate with existing evidence management software and officer-worn sensor networks, extending deployment validation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Non Lethal Weapons Market |
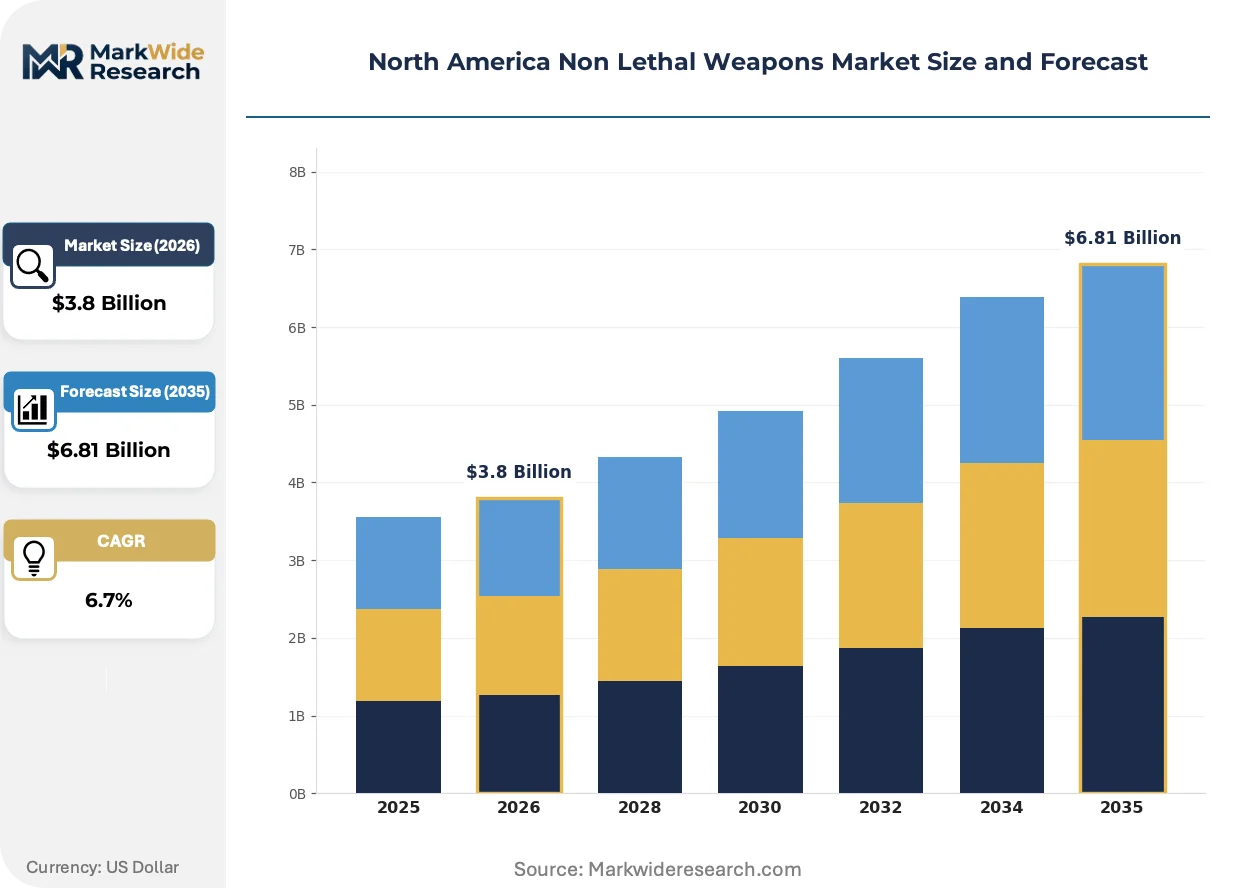
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stun Guns, Tear Gas, Electric Shock Devices, Rubber Bullets End User: Law Enforcement, Military, Private Security, Civilian Technology: Active Denial System, Chemical Agents, Kinetic Energy Weapons, Sound Cannons Application: Crowd Control, Self-Defense, Tactical Operations, Training |
| Companies Covered | Axon Enterprise, Inc., Combined Systems, Inc., Safariland, LLC, Raytheon Technologies Corporation, BAE Systems Plc, General Dynamics Corporation, Byrna Technologies Inc., Pepperball Technologies, Inc., Lamperd Less Lethal, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Non Lethal Weapons Market Evolving Landscape
Product evolution is centering on portability and concealability as law enforcement agencies demand force options that integrate with standard duty gear without encumbering officer mobility.
Conducted electrical weapon cartridge design is miniaturizing through solid-state pulse generation circuits that eliminate bulky capacitors while maintaining neuro-muscular incapacitation thresholds. Texas Department of Public Safety and California Highway Patrol are field-testing compact single-shot units for motorcycle officers. This form-factor reduction is compressing the addressable market for traditional stun guns by collapsing the distinction between primary and backup less-lethal options.
Revised NIJ Standard-0112.03 is mandating waveform documentation and output consistency testing that disqualifies legacy conducted electrical weapon architectures. Manufacturers must submit devices for independent laboratory validation against cardiac safety protocols before federal procurement eligibility. Smaller suppliers lacking in-house compliance teams are outsourcing certification preparation, extending their product refresh cycles relative to established competitors with captive testing facilities.
Law enforcement procurement departments are consolidating vendor relationships through multi-year sole-source agreements that bundle devices, cartridges, and cloud-based evidence management. This concentration is displacing fragmented purchasing across individual precincts and forcing smaller manufacturers to partner with systems integrators for market access. The shift is most pronounced in California and Texas, where state-level cooperative purchasing agreements aggregate demand from hundreds of municipal agencies.
North America Non Lethal Weapons Market Segmentation
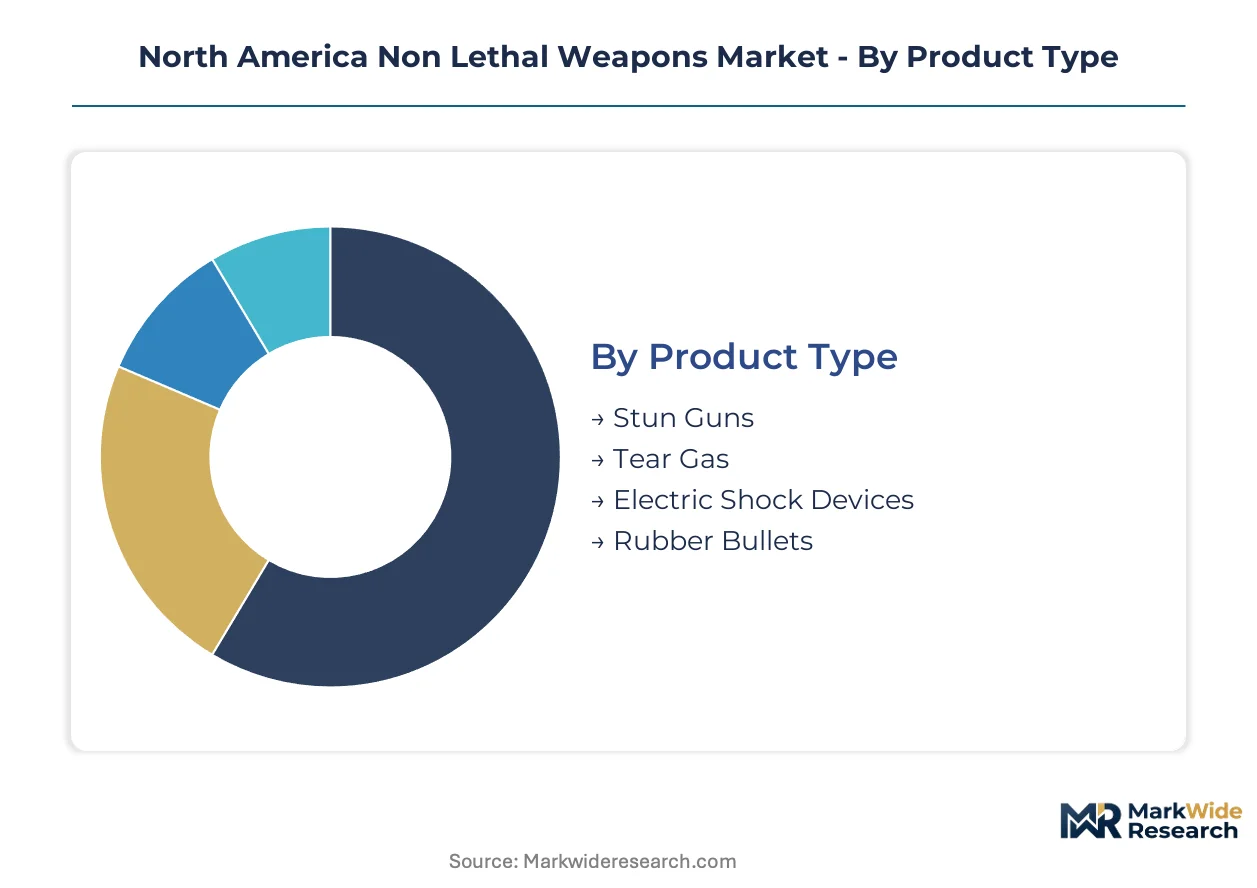
Segmentation in the North America non lethal weapons market reveals how procurement specifications diverge across federal, state, and municipal jurisdictions. Each dimension—product type, end user, technology, and application—carries distinct certification requirements and liability exposure profiles that reshape vendor competitive positioning.
Product Type:
Federal NIJ certification tiers separate segments into procurement-eligible and restricted categories, with electrical output standards and chemical formulation approvals creating divergent compliance pathways.
- Stun Guns:Compact contact-distance devices delivering localized electrical disruption through direct electrode contact. Texas and Florida municipal agencies favor these for correctional facility deployment where projectile launch is prohibited by facility protocols. Battery cell supply constraints from Asian manufacturers compress margins for domestic assemblers.
- Tear Gas:Aerosolized chemical irritant formulations—primarily CS and OC compounds—deployed for area denial and crowd dispersal. California state courts are adjudicating environmental discharge claims that threaten usage permissions in coastal municipalities. Litigation exposure is accelerating demand for decontamination service bundling.
- Electric Shock Devices:Projectile-based conducted electrical weapons operating at 35-foot effective ranges. California Highway Patrol and Texas Department of Public Safety procurement concentrates here for patrol officer primary carry.
- Rubber Bullets:Kinetic impact munitions fired from standard firearms or dedicated launchers. U.S. Customs and Border Protection operations along the southwest border drive volume for crowd management scenarios.
Electric shock devices handle the majority of throughput; tear gas is gaining share fastest amid border security procurement expansion.
End User:
Procurement scale and contract duration vary dramatically across end-user categories, with federal cooperative purchasing agreements aggregating demand differently than fragmented municipal buying.
- Law Enforcement:Municipal police departments and highway patrol agencies constitute the dominant procurement channel. California and Texas state-level cooperative purchasing agreements aggregate demand from hundreds of agencies, favoring vendors with NIJ-certified device portfolios and cloud-based evidence management integration.
- Military:Department of Defense Non-Lethal Weapons Program coordinates inter-agency requirements for base security and expeditionary operations. Specifications emphasize interoperability with existing command-and-control systems and extended operational temperature ranges.
- Private Security:Corporate campus and critical infrastructure protection teams operate under less stringent certification requirements than public agencies. Direct-to-consumer distribution channels are expanding addressable reach for compact chemical irritant systems.
- Civilian:Personal defense buyers purchasing through e-commerce platforms. State-level possession statutes in California and New York create geographic restrictions that fragment market development.
Law enforcement commands the dominant procurement volume; civilian channels are expanding most quickly as direct-to-consumer distribution bypasses traditional law enforcement distributors.
Technology:
R&D investment intensity and patent protection durability separate technologies into mature commodity segments and emerging proprietary systems with defense funding backing.
- Active Denial System:Millimeter-wave directed energy technology producing intolerable heating sensation at standoff distances. Department of Defense perimeter security applications are accelerating technology maturation timelines beyond law enforcement affordability thresholds.
- Chemical Agents:Irritant formulations and malodorant compounds with established manufacturing scale. Environmental litigation in California is pressuring legacy CS formulations toward replacement with OC-based alternatives.
- Kinetic Energy Weapons:Rubber and foam projectile systems with mature biomechanical trauma modeling. U.S. Customs and Border Protection procurement for southwest border operations sustains volume demand.
- Sound Cannons:Long-range acoustic devices producing directional sound pressure for crowd dispersal. Deployment restrictions in urban centers with noise ordinances limit addressable geography.
Kinetic energy weapons carry the established volume base; active denial systems are climbing the fastest on defense R&D allocation.
Application:
Operational environment constraints—urban density, rules of engagement, and training infrastructure availability—segment demand across use cases with divergent product specification requirements.
- Crowd Control:Area denial and dispersal operations in urban environments. California municipalities and U.S. border security operations concentrate demand for chemical agents and kinetic projectiles with de-escalation protocols.
- Self-Defense:Individual protection scenarios favoring compact, concealable form factors. Civilian direct-to-consumer channels in Texas and Florida bypass traditional law enforcement distribution.
- Tactical Operations:High-risk warrant service and barricade scenarios requiring immediate incapacitation capability. NIJ certification for conducted electrical weapons is mandatory for federal tactical team procurement.
- Training:Simulation systems and inert cartridges for officer certification. State-level training mandates in California and Texas create recurring replacement demand.
Crowd control absorbs the dominant application volume; self-defense is expanding share fastest through civilian channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement patterns diverge sharply across North American jurisdictions, with U.S. agencies prioritizing conducted electrical weapons for patrol officers while Canadian forces emphasize kinetic projectile systems for riot control protocols.
United States
California Highway Patrol and Texas Department of Public Safety drive volume for NIJ-certified conducted electrical weapons through state-level cooperative purchasing agreements. The National Institute of Justice Standard-0112.03 mandates third-party electrical output validation, forcing municipal departments in Los Angeles and Houston to retire legacy devices. Southern California and the Texas-Mexico border corridor concentrate demand for border security applications.
Canada
Royal Canadian Mounted Police procurement formalizes less-lethal deployment standards across provincial police services, opening federal procurement channels for U.S. manufacturers. Health Canada device approval requirements create a dual-certification burden that filters supplier participation. Toronto and Vancouver municipal police departments pilot compact chemical irritant systems for urban crowd management scenarios.
Mexico
Federal Police and National Guard units expand less-lethal inventories amid constitutional policing reforms and international human rights monitoring. The Secretariat of National Defense coordinates military procurement specifications with U.S. border security interoperability requirements. Mexico City and Tijuana concentrate operational deployment for protest response and detention facility security.
North America Non Lethal Weapons Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with defense conglomerates and dedicated less-lethal innovators competing through divergent capability stacks. The upper tier commands federal procurement relationships and captive certification infrastructure, while mid-tier players outsource compliance preparation and partner with systems integrators for market access. Two strategic archetypes dominate: vertically integrated defense contractors leveraging military contract scale, and focused less-lethal specialists exploiting direct-to-consumer distribution channels. Competitive moves center on sole-source agreement consolidation and bundled evidence management integration.
Within the integrated defense tier, Raytheon Technologies Corporation and BAE Systems Plc occupy positions anchored by military R&D funding and expeditionary security contracts. Among specialized less-lethal developers, Axon Enterprise, Inc. exemplifies channel dominance through law enforcement agency relationships, while Byrna Technologies Inc. represents the civilian-facing archetype with compact chemical irritant distribution. These three companies illustrate how scale concentration and niche specialization coexist as viable competitive positions.
| Leading Market Players |
|---|
| Axon Enterprise, Inc. |
| Combined Systems, Inc. |
| Safariland, LLC |
| Raytheon Technologies Corporation |
| BAE Systems Plc |
| General Dynamics Corporation |
| Byrna Technologies Inc. |
| Pepperball Technologies, Inc. |
| Lamperd Less Lethal, Inc. |
| Others |
Value Network & Pricing Analysis
Multi-year sole-source agreements with bundled evidence management lock in procurement channels and price visibility across California and Texas municipal agencies. These contract structures tether unit pricing to cartridge replenishment schedules and cloud service tiers, compressing margin negotiation windows for manufacturers lacking integrated software stacks.
Pricing Analysis
Long-term offtake contracts dominate municipal procurement, with California Highway Patrol and Texas Department of Public Safety aggregating volume through state cooperative purchasing agreements. Price differentiation hinges on NIJ certification tier and evidence management integration depth, with certified-device premiums widening as legacy inventory expires. Cost compression in chemical irritant formulations intensifies due to California environmental litigation exposure. Private security buyers exhibit highest price sensitivity, while federal tactical teams prioritize certification compliance over unit cost.
Supply Chain Analysis
China, South Korea, and Japan anchor lithium-ion cell production for conducted electrical weapon power systems. Domestic assemblers draw from Asian battery manufacturers and specialized polymer suppliers for cartridge housings. Single-source vulnerability concentrates in solid-state pulse generation circuits, where defense-contractor captive production limits merchant market access. Distribution runs through law enforcement equipment distributors and direct-to-consumer e-commerce platforms for civilian segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Body-worn camera integration with conducted electrical weapon activation logging is consolidating procurement around platform ecosystems, rewarding vendors with bundled hardware-software stacks.
For Market Incumbents: Fortify channel control through exclusive evidence management contracts that embed replacement cartridge commitments. Deepen backward integration into solid-state pulse generation to offset Asian battery supply concentration. Counter emerging compact chemical irritant specialists by accelerating Health Canada certification for Canadian municipal expansion. For New Entrants and Emerging Players: Health Canada fast-track approval opens procurement channels with Royal Canadian Mounted Police and provincial services underserved by incumbent distributors. Target civilian direct-to-consumer segments in Texas and Florida where possession statutes permit compact launcher sales. Bypass traditional law enforcement distributors through e-commerce platforms with subscription-based cartridge replenishment. For Investors and Strategic Acquirers: Specialized biomechanical testing firms with NIJ validation relationships represent priority acquisition targets as certification timeline compression strains mid-tier manufacturers. Long-term viability favors platform-integrated suppliers over pure-hardware vendors. Watch for Health Canada approval announcements as inflection signals for Canadian market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| NIJ Certification Fast-Track | Health Canada parallel submissions open Royal Canadian Mounted Police procurement channels for U.S. manufacturers. |
| Evidence Management Integration | Cloud-based activation logging bundled with device sales locks in cartridge replenishment revenue streams. |
| Direct-to-Consumer Channel Buildout | E-commerce platforms targeting Texas and Florida civilian buyers bypass traditional law enforcement distributor markups. |
| Solid-State Pulse Generation Investment | In-house circuit design eliminates capacitor bulk and extends patent protection durability against Asian competitors. |
| Environmental Litigation Defense Bundling | Decontamination service contracts attached to tear gas sales mitigate California municipal liability exposure. |
Research Methodology
Initial hypotheses were tested against primary input from law enforcement procurement officers, NIJ certification specialists, and defense program managers and refined through secondary validation. Stakeholder interviews encompassed municipal police department equipment coordinators, U.S. Customs and Border Protection contracting officers, and private security firm operations directors. Secondary sources included NIJ standard documentation, Department of Defense Non-Lethal Weapons Program budget justifications, and Health Canada medical device approval records. Bottom-up unit shipment estimates triangulated against top-down procurement budget allocations.
Variance decomposition separated volume drivers across product type, end user, and technology segments throughout the forecast period. Segmentation modeling captured law enforcement, military, private security, and civilian demand archetypes alongside kinetic, chemical, electrical, and directed energy technology pathways. CAGRs derived from procurement cycle analysis and replacement demand curves tied to NIJ Standard-0112.03 compliance deadlines. Industry-specific inputs included state-level cooperative purchasing agreement aggregation patterns and border security operations tempo.
Decision-makers should treat outputs as directional under assumptions of continued NIJ certification enforcement and stable lithium battery trade flows; material deviation would warrant model refresh. Forecasts reflect procurement budget continuity and litigation exposure thresholds for chemical irritant formulations. Recalibration cycles align with NIJ standard revision announcements and Health Canada approval determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
National Security
Europe Non-Lethal Weapons Market
National Security
Global Security Assessment Market
National Security
Homeland Security Market
National Security
Research Department Explosive (RDX) Market
National Security
Chemical, Biological, Radiological and Nuclear (CBRN) Security Market
National Security
Asia-Pacific Non-Lethal Weapons Market
National Security
Saudi Arabia Manned Security Market
National Security
US Bulletproof Glass Market
National Security
Radiological and Nuclear Security Market
National Security
Global Non Lethal Weapons Market
National Security
Service Handgun Market
National Security
Asia-Pacific Border Security Market