
 Radiological and Nuclear Security Market | 2026-2036
Radiological and Nuclear Security Market Size, Share, and Industry Trends Forecast 2026-2036
Radiological and Nuclear Security Market Analytics
Project finance for large-scale border detection networks is narrowing the competitive field to firms with balance-sheet capacity for multi-year deployment contracts. Thermo Fisher Scientific leverages its analytical instrumentation heritage to anchor government laboratory relationships. Mirion Technologies sustains its position through captive manufacturing of dosimetry and detection components. Kromek Group specializes in cadmium zinc telluride semiconductor detectors for portable nuclear identification.
Radiological and nuclear security encompasses systems that detect, identify, and interdict illicit radioactive materials through gamma-ray spectroscopy, neutron detection, and portal monitoring at throughput rates exceeding 2,000 vehicles per hour. These technologies serve counter-proliferation, emergency response, and critical infrastructure protection missions across civilian and defense contexts. Detection Equipment dominates procurement budgets due to sensor replacement cycles and sensitivity upgrade mandates, while Nuclear Forensics represents the fastest-expanding technology segment as attribution capabilities gain priority. Military end users command premium pricing for hardened, deployable systems, whereas Healthcare Facilities drive steady demand for staff dosimetry and waste monitoring.
The IAEA Nuclear Security Series shapes national detection architecture standards, while the U.S. Department of Homeland Security's Domestic Nuclear Detection Office sets procurement specifications for American ports and crossings. The EU CBRN Action Plan coordinates member-state investments in cross-border detection networks and response interoperability. Stakeholders must monitor how regulatory divergence between American and European sensitivity thresholds affects product certification costs and market access.
Market Dynamics
Compliance mandates from the IAEA Nuclear Security Series and the EU CBRN Action Plan are compressing detection sensitivity thresholds, forcing sensor replacement cycles and accelerating procurement of next-generation portal systems across NATO member states.
Growth Catalysts
- IAEA Nuclear Security Series:Updated detection architecture standards mandate gamma-ray spectroscopy upgrades at civilian nuclear facilities, expanding replacement demand for legacy scintillator systems.
- Healthcare Facilities:Staff dosimetry monitoring and radioactive waste tracking requirements sustain recurring revenue streams for personal radiation detection devices.
- Cadmium zinc telluride semiconductors:These detectors enable portable nuclear identification with superior energy resolution, opening deployment at remote border crossings and emergency response units.
Market Restraints
- Helium-3 supply constraints:Neutron detection systems face input cost volatility as nuclear non-proliferation agreements restrict access to this critical isotope for proportional counters.
- Single-source sensor dependencies:High-purity germanium crystal production concentrates in limited manufacturing facilities, creating supply concentration risk for laboratory-grade spectrometers.
- Cross-border certification friction:Divergent sensitivity thresholds between American and European regulatory regimes inflate product validation timelines and duplicate testing expenditures.
Strategic Opportunities
- India:The country's nuclear power expansion and BIS standards alignment create underpenetrated demand for domestic radiation monitoring networks at ports and industrial zones.
- Machine learning convergence:Artificial intelligence is hybridizing with gamma-ray spectroscopy to reduce false alarm rates and enable autonomous threat classification in high-throughput screening environments.
- EU CBRN Action Plan:Coordinated member-state investments in cross-border detection interoperability generate multi-year framework contracts for integrated response systems.
Industry Challenges
- Certification timeline compression:NRC and EPA approval pathways for new detection algorithms extend 18-24 months, delaying revenue recognition for upgraded firmware releases.
- Legacy system integration:DHS Domestic Nuclear Detection Office procurement specifications require backward compatibility with decade-old portal architectures, constraining architectural innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiological and Nuclear Security Market |
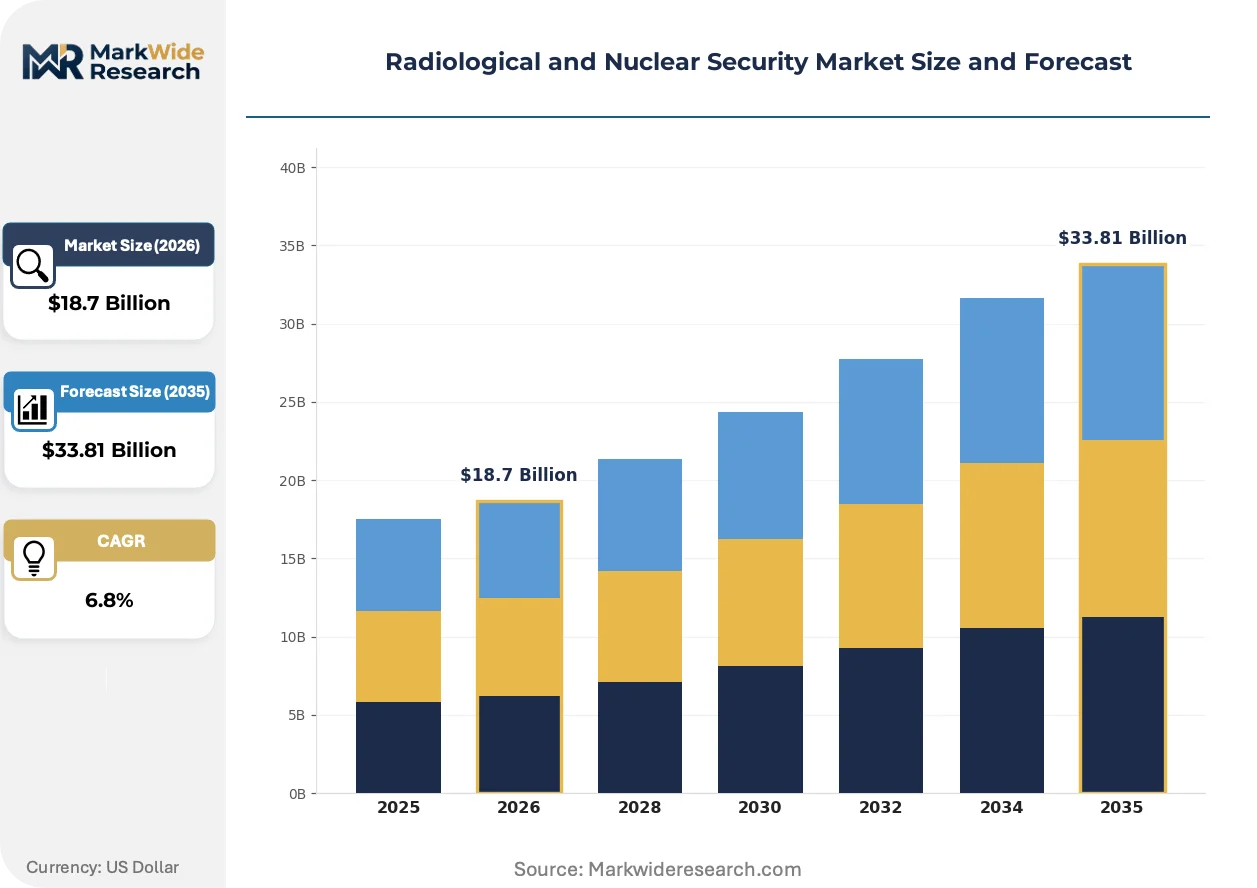
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detection Equipment, Surveillance Systems, Response Tools, Personal Protection End User: Government Agencies, Military, Healthcare Facilities, Private Security Technology: Radiation Detection, Nuclear Forensics, Emergency Response, Monitoring Systems Application: Homeland Security, Border Protection, Public Safety, Asset Protection |
| Companies Covered | Mirion Technologies, Thermo Fisher Scientific, Fortive, AMETEK, Fuji Electric, Ludlum Measurements, Teledyne FLIR, Kromek Group, Arktis Radiation Detectors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiological and Nuclear Security Market Evolving Landscape
Detection architectures are converging around artificial intelligence-enabled spectroscopy and modular hardware platforms that reduce deployment footprints. These shifts are compressing development cycles and redefining competitive differentiation.
Cadmium zinc telluride semiconductor arrays are hybridizing with traditional sodium iodide scintillators to deliver portable nuclear identification without liquid nitrogen cooling. Military end users are field-testing these hybrid systems for rapid deployable screening. The technology is hybridizing laboratory-grade resolution with field-ruggedized packaging, collapsing the performance gap between fixed-site and mobile detection platforms.
The EU CBRN Action Plan mandates cross-border detection network interoperability by 2027, compelling vendors to adopt standardized data protocols. This regulatory pressure is consolidating procurement around open-architecture platforms that interface with national emergency response systems. Border security agencies in Germany, France, and Poland are prioritizing certification for systems meeting these interoperability specifications.
Service unbundling is fragmenting traditional detection equipment contracts. Government buyers are separating hardware procurement from algorithm maintenance and threat library updates, creating recurring revenue pools for software-centric vendors. This pattern is most visible in United States port security deployments, where DHS contracts now specify distinct performance milestones for detection sensitivity versus system uptime guarantees.
Radiological and Nuclear Security Market Segmentation
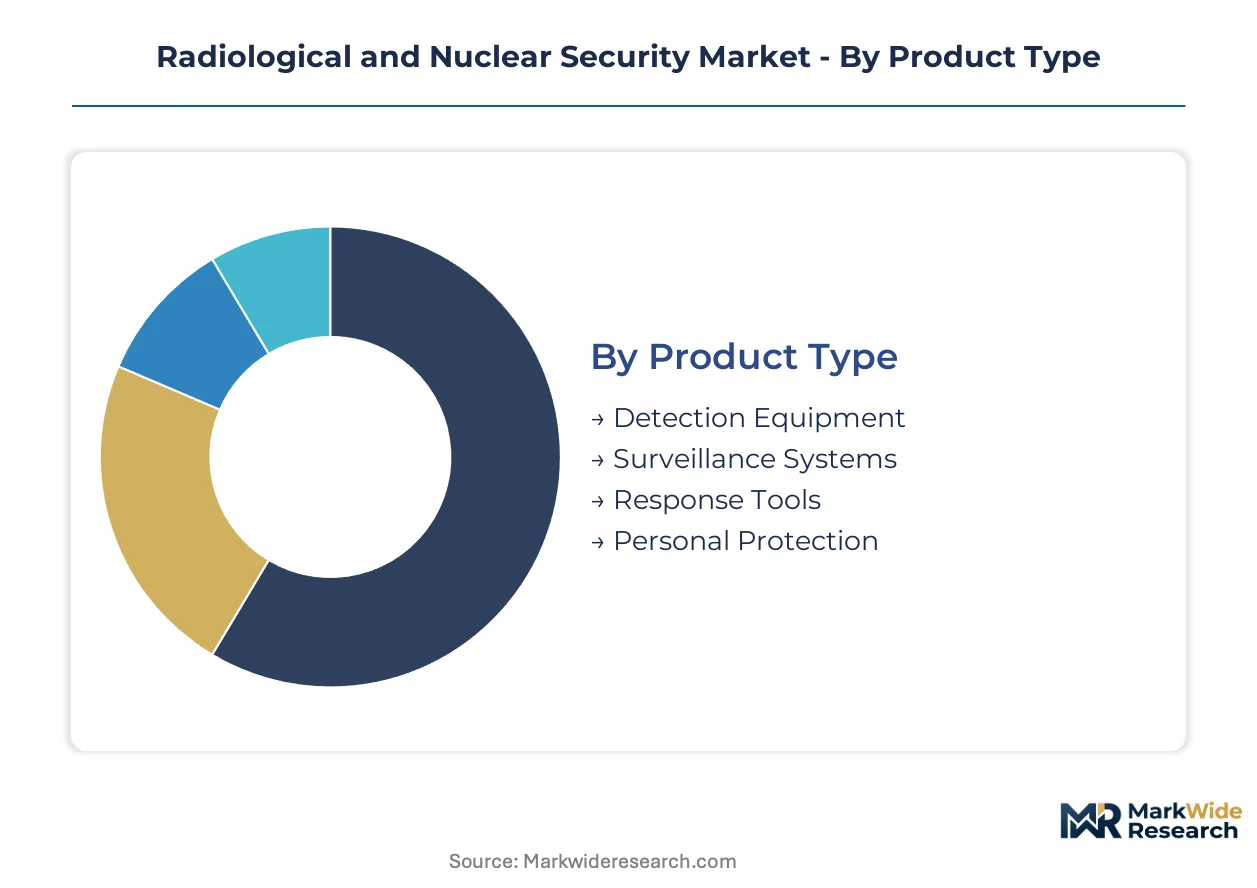
Radiological and nuclear security procurement splits across four distinct dimensions, each with divergent replacement cycles and margin profiles. Detection hardware operates on 7-10 year refresh timelines, while software and service layers turn over faster as threat signatures evolve.
Product Type:
Detection Equipment commands the shortest replacement cycles due to sensor degradation and sensitivity upgrade mandates, while Personal Protection turns slowest with 15-year certification windows.
- Detection Equipment:Gamma-ray spectroscopy, neutron detection arrays, and portal monitors at throughput rates exceeding 2,000 vehicles per hour. NATO member states at critical infrastructure entry points drive procurement as IAEA standards tighten compliance thresholds.
- Surveillance Systems:Integrated sensor networks with real-time data fusion for distributed monitoring architectures. Germany and Poland prioritize cross-border interoperability under EU CBRN Action Plan specifications.
- Response Tools:Deployable containment and interdiction equipment for emergency scenarios.
- Personal Protection:Dosimetry badges, protective garments, and individual monitoring devices.
Detection Equipment dominates installed base. Surveillance Systems is where expansion concentrates.
End User:
Government Agencies anchor volume procurement through multi-year framework contracts, while Military end users extract premium pricing for hardened specifications.
- Government Agencies:National laboratories, customs authorities, and domestic security departments operating fixed-site screening networks. The U.S. Department of Homeland Security prioritizes port and crossing deployments with distinct performance milestones for sensitivity versus uptime.
- Military:Deployable, ruggedized systems for expeditionary screening and forward operating base protection. Field-testing of cadmium zinc telluride hybrid arrays is accelerating procurement for rapid response units.
- Healthcare Facilities:Staff dosimetry monitoring and radioactive waste tracking for hospitals and medical centers.
- Private Security:Corporate and critical infrastructure operators supplementing government screening layers.
Government Agencies capture the largest contract value. Military applications are climbing the fastest as attribution capabilities gain priority.
Technology:
Radiation Detection absorbs the majority of R&D expenditure, while Nuclear Forensics attracts venture-stage investment for algorithm development.
- Radiation Detection:Scintillator-based and semiconductor sensor platforms for gamma and neutron signature identification. Sodium iodide systems face replacement pressure from cadmium zinc telluride arrays offering superior energy resolution without liquid nitrogen cooling.
- Nuclear Forensics:Attribution analytics, isotopic fingerprinting, and origin determination protocols. The EU CBRN Action Plan and updated IAEA standards are accelerating demand as member states build response interoperability.
- Emergency Response:Rapid deployment protocols and consequence management systems.
- Monitoring Systems:Continuous environmental and facility-wide surveillance networks.
Radiation Detection holds the deepest installed base. Nuclear Forensics shows the steepest expansion trajectory.
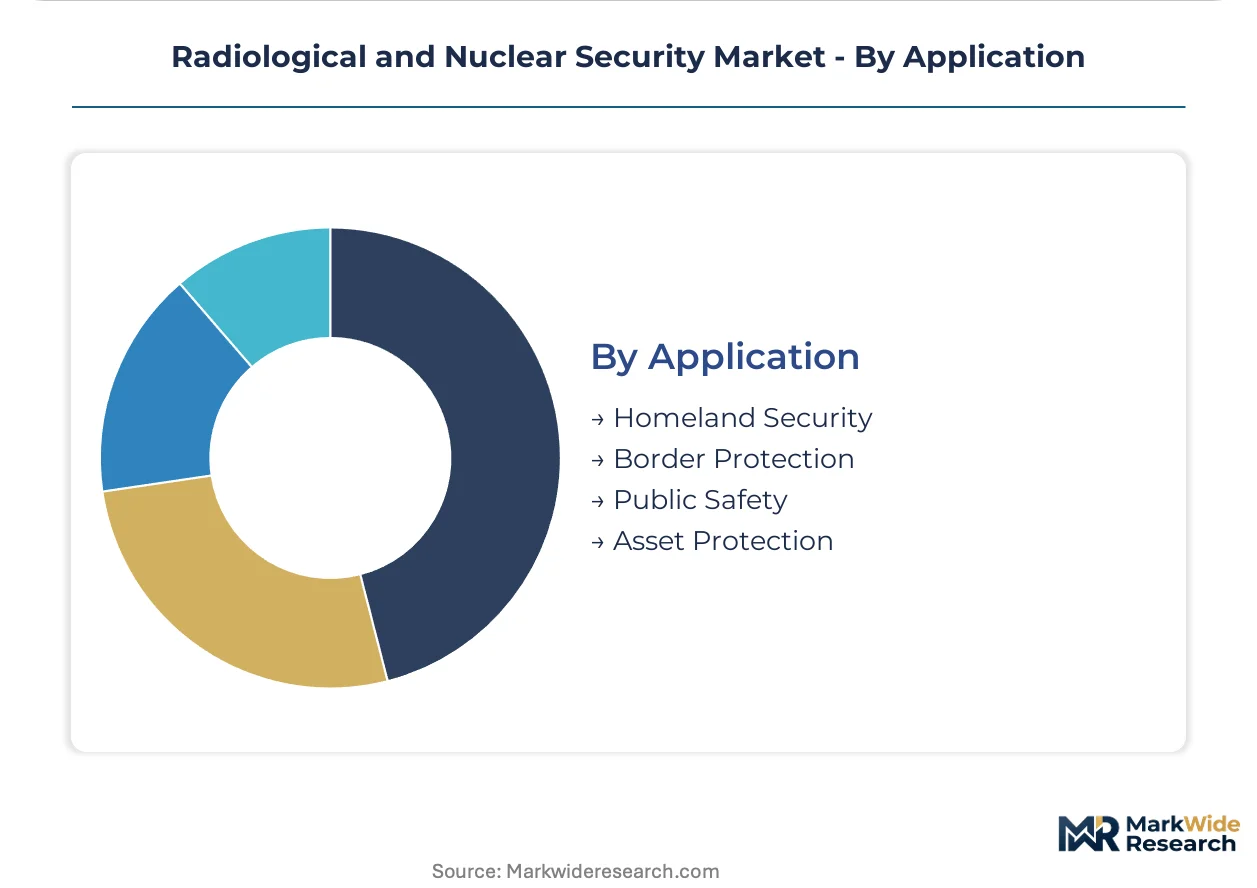
Application:
Homeland Security and Border Protection split procurement between fixed infrastructure and mobile screening requirements.
- Homeland Security:Domestic screening networks at airports, seaports, and critical infrastructure nodes. The U.S. Domestic Nuclear Detection Office sets procurement specifications requiring backward compatibility with legacy portal architectures.
- Border Protection:Cross-boundary detection corridors with standardized data protocols for interoperability. France and Germany are prioritizing certification for systems meeting EU-mandated interoperability specifications.
- Public Safety:Urban area monitoring and event security for mass gatherings.
- Asset Protection:Facility-specific guarding of nuclear materials and industrial radiological sources.
Homeland Security anchors existing deployment value. Border Protection is gaining share fastest as cross-network integration mandates take effect.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IAEA Nuclear Security Series compliance mandates are reshaping procurement patterns across national detection architectures. Government agencies in NATO member states are accelerating sensor replacement cycles. The EU CBRN Action Plan coordinates cross-border interoperability investments.
United States
The Department of Homeland Security prioritizes domestic radiological screening networks at ports and crossings. The Domestic Nuclear Detection Office sets procurement specifications requiring backward compatibility with legacy portal architectures. Deployment concentrates along the Southwest border corridor and major seaport clusters.
Germany
Federal police and customs authorities are expanding radiation detection portals at critical infrastructure entry points. The EU CBRN Action Plan drives certification for systems meeting interoperability specifications by 2027. Industrial demand clusters in Bavaria and North Rhine-Westphalia around nuclear research facilities.
France
The country's national nuclear security regulator enforces tightened detection sensitivity thresholds at civilian facilities. Cross-border detection network mandates prioritize standardized data protocols for emergency response interoperability. Procurement activity concentrates at Channel ports and the Île-de-France research corridor.
India
Nuclear power expansion and BIS standards alignment create demand for domestic radiation monitoring networks. The central government's port modernization programs mandate detection equipment at major maritime terminals. Industrial zones in Gujarat and Maharashtra are prioritizing facility-wide surveillance installations.
Japan
METI coordinates post-Fukushima detection architecture upgrades at nuclear facilities and emergency response units. National standards for gamma-ray spectroscopy are displacing legacy scintillator systems in prefectural monitoring networks. Deployment focuses on the Tōkai region and metropolitan Tokyo screening infrastructure.
Radiological and Nuclear Security Market Competitive Landscape
On the supply side, the industry is consolidating around firms with balance-sheet capacity for multi-year government deployment contracts. Analytical instrumentation heritage and captive manufacturing of detection components define two strategic archetypes. Competitive moves concentrate on technology licensing partnerships and geographic expansion into underpenetrated Asian markets.
Among established detection specialists, Mirion Technologies and Kromek Group exemplify the component-captive archetype, while Thermo Fisher Scientific anchors the diversified analytical instrumentation tier. These firms occupy positions across the technology spectrum from semiconductor detector arrays to laboratory-grade spectrometers. Their market presence reflects sustained government laboratory relationships and multi-year framework contract execution capability.
| Leading Market Players |
|---|
| Mirion Technologies |
| Thermo Fisher Scientific |
| Fortive |
| AMETEK |
| Fuji Electric |
| Ludlum Measurements |
| Teledyne FLIR |
| Kromek Group |
| Arktis Radiation Detectors |
| Others |
Value Network & Pricing Analysis
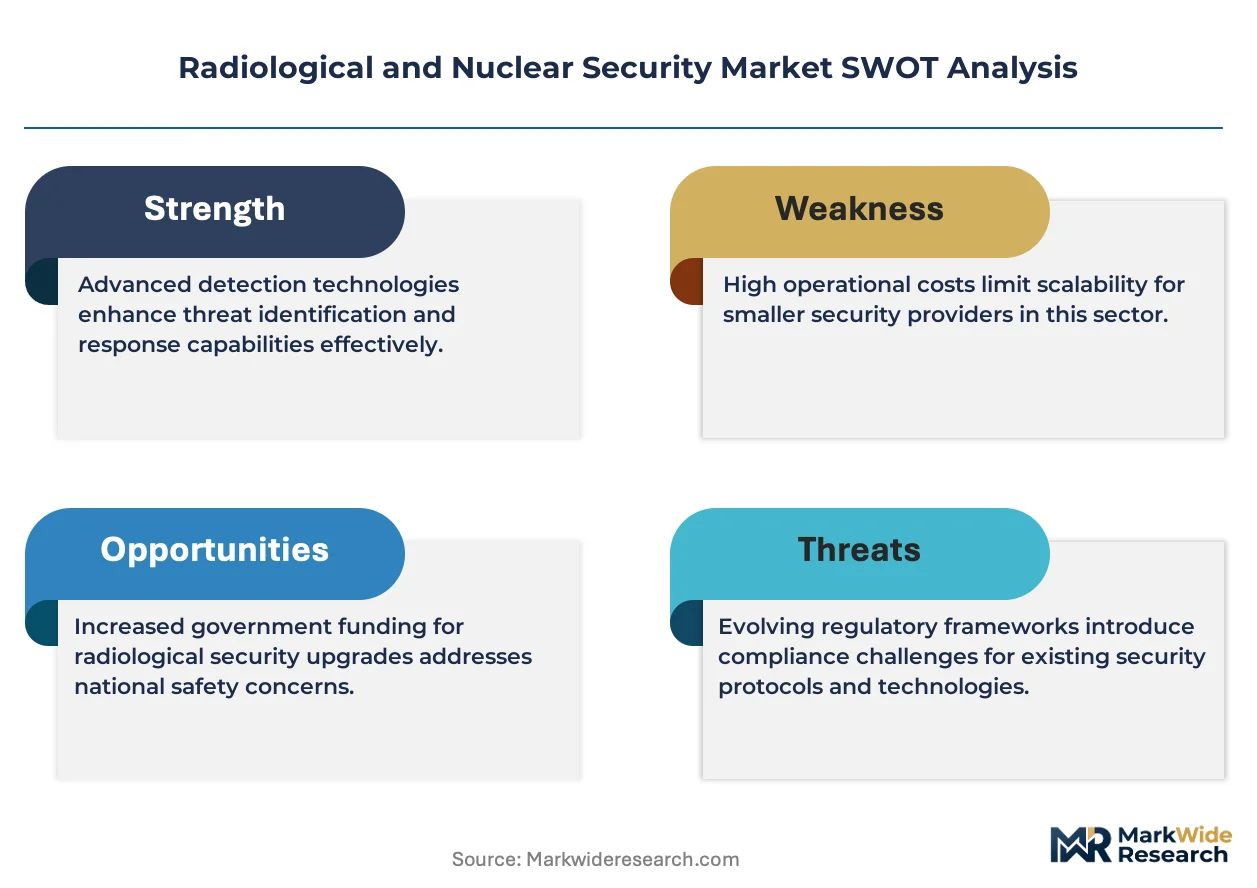
Helium-3 supply constraints determine both tiered pricing spreads and supply chain configuration across neutron detection system manufacturers. Procurement officers at national laboratories face compressed margins as single-source dependencies for high-purity germanium crystals force premium pricing on laboratory-grade spectrometers while project-based contracts for portal systems stratify by certification grade.
Pricing Analysis
Certification level (IAEA-compliant versus national-standard grade) creates the primary spread between premium and standard tiers. Three-tier pricing structure across IAEA-certified, NATO-interoperable, and national-standard levels dominates procurement, with sensitivity thresholds and backward-compatibility requirements driving differentiation. Cost compression in standard-tier scintillator systems is intensifying because cadmium zinc telluride semiconductors displace legacy sodium iodide arrays. Government agencies exhibit lowest price sensitivity due to multi-year framework contract structures, while private security operators show highest elasticity.
Supply Chain Analysis
Extended payment terms from prime contractors to component suppliers characterize working capital dynamics across the tier. High-purity germanium crystal production concentrates in the United States, Japan, and Germany, while helium-3 extraction for neutron proportional counters draws from legacy nuclear stockpiles in the United States and Russia. Single-source vulnerability for cadmium zinc telluride semiconductor substrates rests on limited crystal growth facilities. Distribution runs through government procurement frameworks and authorized defense contractors rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through consolidated national procurement frameworks that aggregate demand across multiple agency budgets. This consolidation fragments competitive access for vendors lacking established government laboratory relationships.
For Market Incumbents:Insulate installed base positions through captive manufacturing of dosimetry components and backward integration into semiconductor detector crystal growth. Certification investment in EU CBRN Action Plan interoperability specifications anchors channel control against emerging entrants lacking framework contract execution history.
For New Entrants and Emerging Players:Pursue white-space deployment at India's port modernization programs and Japan's prefectural monitoring network upgrades where incumbent presence remains underdeveloped. Machine learning-enabled spectroscopy algorithm licensing offers the most penetrable entry angle for software-centric vendors seeking recurring revenue streams separate from hardware procurement.
For Investors and Strategic Acquirers:The market sits at a standards-convergence phase that favors component-captive specialists with IAEA certification pedigree. Long-term viability across the projection horizon rests on algorithmic differentiation rather than sensor hardware alone. Watch cadmium zinc telluride cost curves as the inflection signal for semiconductor displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| IAEA Certification Investment | Unlocks NATO member state procurement frameworks and laboratory system integration contracts. |
| Algorithm Licensing Partnership | Captures recurring revenue from threat library updates separate from hardware replacement cycles. |
| Cadmium Zinc Telluride Scale-Up | Displaces liquid nitrogen-cooled scintillator systems with portable semiconductor resolution. |
| EU Interoperability Compliance | Positions vendors for 2027 cross-border detection network consolidation mandates. |
| India Port System Partnership | Secures early-mover advantage in BIS standards-aligned radiation monitoring expansion. |
Research Methodology
A spread of perspectives from government procurement officers, radiation detection system engineers, national laboratory program managers, and defense contractor business development leads converged on the working assumptions. Primary field engagement combined with secondary validation from IAEA Nuclear Security Series documentation, EU CBRN Action Plan implementation reports, DHS Domestic Nuclear Detection Office procurement specifications, and national regulatory filings. Bottom-up equipment shipment analysis and top-down government budget appropriation triangulation anchored volume estimates.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework. Segmentation modeling covered product type, end-user archetype, technology platform, and application mission with regional regulatory cluster overlays. CAGRs derived from replacement cycle analysis and sensitivity upgrade mandates. Industry-specific inputs included helium-3 stockpile depletion curves and cadmium zinc telluride manufacturing yield improvements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by semiconductor detector specialists or algorithm-centric software vendors would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
National Security
Research Department Explosive (RDX) Market
National Security
US Bulletproof Glass Market
National Security
Homeland Security Market
National Security
North America Non Lethal Weapons Market
National Security
Global Non Lethal Weapons Market
National Security
Asia-Pacific Non-Lethal Weapons Market
National Security
Saudi Arabia Manned Security Market
National Security
Asia-Pacific Border Security Market
National Security
Service Handgun Market
National Security
Global Security Assessment Market
National Security
Chemical, Biological, Radiological and Nuclear (CBRN) Security Market
National Security
Europe Non-Lethal Weapons Market