
 Service Handgun Market | 2026-2036
Service Handgun Market Size, Share, and Industry Trends Forecast 2026-2036
Service Handgun Market Analysis
US Army Modular Handgun System requirements is expanding the cost-of-entry calculus for service handgun manufacturers, forcing competitors to invest in modular architecture platforms. SIG SAUER leverages its MHS contract win to sustain production scale across military and law enforcement channels. GLOCK Ges.m.b.H. anchors the global law enforcement segment through its dominant presence in police department procurement worldwide. Smith & Wesson Brands competes aggressively in the private security and federal agency tiers with polymer-frame striker-fired designs.
A service handgun constitutes a portable, shoulder-fired firearm designed for one-handed or two-handed operation, typically chambered in calibers ranging from 9mm to .45 ACP, with barrel lengths between 3 and 5 inches and magazine capacities of 10 to 17 rounds, manufactured through precision CNC machining of steel or polymer frames to deliver reliable stopping power in close-quarters engagements. The semi-automatic product category leads procurement volumes due to superior capacity and faster reload cycles, while striker-fired technology dominates new platform development because of its simplified trigger mechanism and enhanced reliability under field conditions. The law enforcement application segment commands the largest margin pool, though personal protection channels show accelerated growth as concealed-carry permit frameworks expand across multiple jurisdictions.
The US Bureau of Alcohol, Tobacco, Firearms and Explosives, the National Institute of Justice, and Germany's KBA collectively shape service handgun compliance through ballistic testing protocols, import restrictions, and safety certification requirements that directly determine market access. European REACH regulations and the EU Firearms Directive impose additional material and traceability standards that manufacturers must satisfy for cross-border sales. Stakeholders must monitor evolving modular platform requirements and ammunition standardization debates across NATO procurement frameworks to anticipate shifts in specification-driven demand.
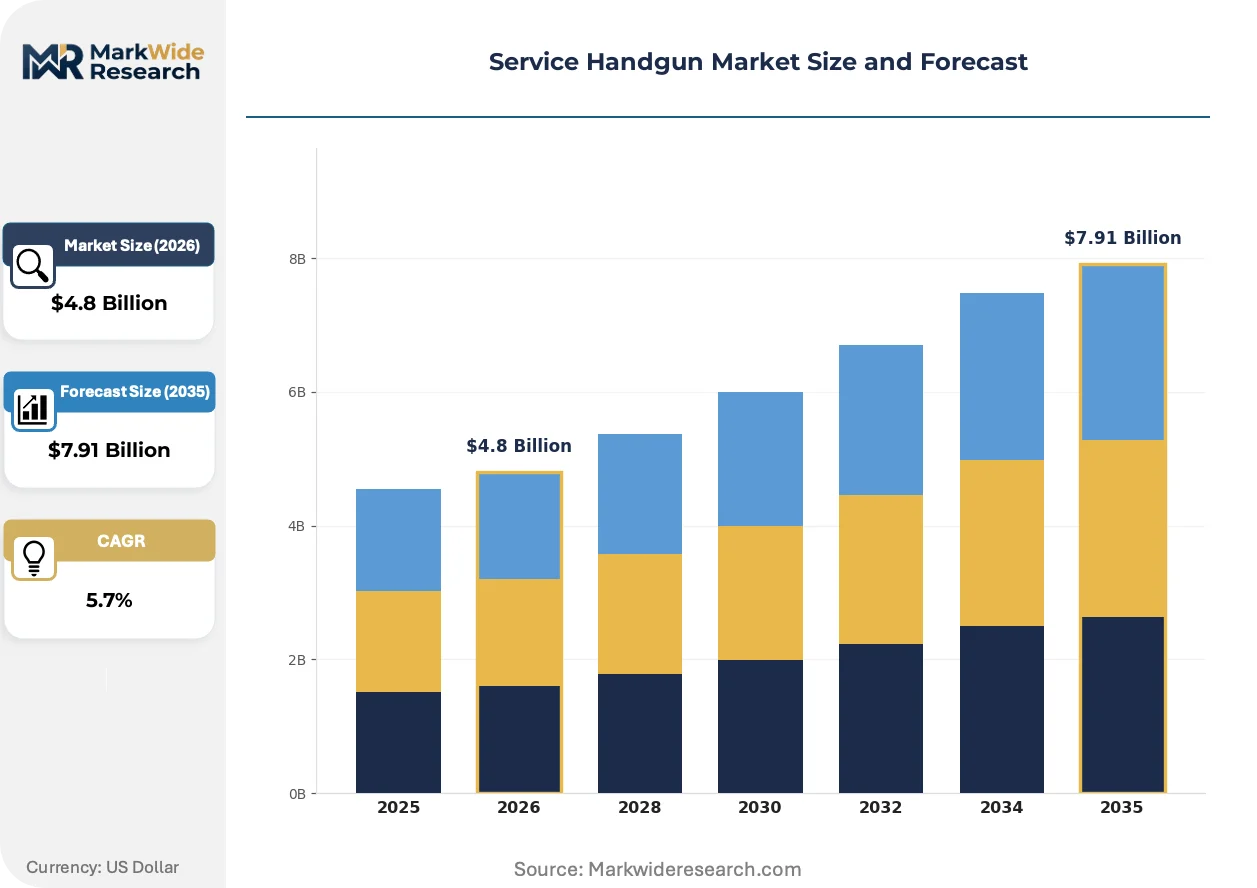
Market Dynamics
The US Army Modular Handgun System program is restructuring manufacturer design priorities by mandating modular architecture platforms, forcing competitors to absorb elevated R&D costs while SIG SAUER leverages its contract position to dominate military and adjacent law enforcement procurement channels.
Growth Catalysts
- NIJ Ballistic Testing Protocols:Standardized performance certification under US National Institute of Justice guidelines creates procurement clarity for federal and municipal law enforcement agencies, accelerating replacement cycles for legacy sidearm inventories.
- Polymer-Frame Manufacturing Scale:CNC machining advances and polymer injection molding maturity are compressing unit production costs while maintaining precision tolerances, enabling broader agency adoption across budget-constrained departments.
- Czech Republic Defense Modernization:NATO interoperability requirements and domestic security force upgrades are driving sustained procurement of striker-fired 9mm platforms compatible with standardized ammunition supply chains.
Market Restraints
- Steel and Polymer Input Volatility:Specialized firearm-grade steel alloys and high-impact polymer feedstock prices fluctuate with energy and petrochemical markets, squeezing margin structures for precision-machined components.
- German KBA Certification Friction:Germany's Federal Motor Transport Authority equivalent for firearms imposes extended safety validation timelines and traceability mandates that delay market entry for non-EU manufacturers.
- Modular Platform R&D Concentration:Development cost barriers concentrate advanced platform innovation among three manufacturers with captive military contracts, limiting competitive diversity in next-generation system architecture.
Strategic Opportunities
- Concealed-Carry Permit Expansion:Jurisdictional frameworks enabling civilian concealed-carry licensing are opening personal protection channels with higher margin profiles than institutional procurement, particularly in US states with shall-issue statutes.
- Optics-Ready Slide Convergence:Integration of miniature red-dot sight mounting interfaces with striker-fired platforms creates premium tier differentiation and aftermarket attachment revenue streams.
- EU Firearms Directive Harmonization:Streamlined cross-border traceability and safety certification standards reduce regulatory fragmentation for manufacturers achieving KBA and BKA dual compliance, easing Central European market penetration.
Industry Challenges
- Modular Interoperability Testing:Validation of trigger group, slide, and frame component interchangeability across environmental conditions extends product development timelines and strains quality assurance resources.
- Legacy Ammunition Inventory Integration:Law enforcement agencies with substantial .40 S&W stockpiles face transition friction to 9mm NATO standardization, complicating procurement decisions and training protocols.
- Skilled CNC Machinist Scarcity:Precision firearm manufacturing requires specialized metalworking expertise concentrated in traditional manufacturing regions, constraining production scaling for emerging market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Handgun Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pistol, Revolver, Semi-Automatic, Compact, Subcompact Technology: Striker-Fired, Double Action, Single Action, Double Action Only, Polymer Frame Application: Law Enforcement, Military Operations, Personal Protection, Security Services, Tactical Training End User: Federal Agencies, Defense Forces, Private Security Firms, Police Departments |
| Companies Covered | SIG SAUER, GLOCK Ges.m.b.H., Smith & Wesson Brands, Heckler & Koch GmbH, Fabbrica d'Armi Pietro Beretta S.p.A., Colt’s Manufacturing Company, Sturm, Ruger & Co., FN HERSTAL, Ceska zbrojovka uhersky brod, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Handgun Market Emerging Trajectories
Striker-fired mechanism standardization is compressing technical differentiation among manufacturers while red-dot optic integration and ammunition caliber rationalization reshape product roadmaps across military, law enforcement, and civilian segments.
Striker-fired ignition architecture is consolidating as the dominant technical platform across new service handgun development. Law enforcement agencies and military procurement offices specify simplified internal mechanisms with fewer moving parts to reduce field maintenance requirements and enhance reliability under adverse conditions. This technical convergence is consolidating competitive differentiation around modular frame ergonomics and accessory rail standardization rather than fundamental operating systems.
REACH regulations governing polymer frame material composition and long-term chemical stability are reshaping European manufacturing compliance burdens. ECHA substance restrictions on specific plasticizers and flame retardants force reformulation of frame polymers and extended migration testing protocols. German and Czech manufacturers with integrated material science capabilities are responding fastest, while importers face delayed market access pending certification renewal.
Agency fleet standardization mandates are compressing procurement decision timelines and consolidating vendor relationships. Large municipal police departments and federal agencies increasingly award sole-source or dual-source contracts covering multi-thousand unit deployments with integrated armorer training and parts availability guarantees. US state-level highway patrol and corrections departments demonstrate this pattern most visibly, with California, Texas, and Florida agencies completing system-wide transitions to single-platform standardization.
Service Handgun Market Segmentation
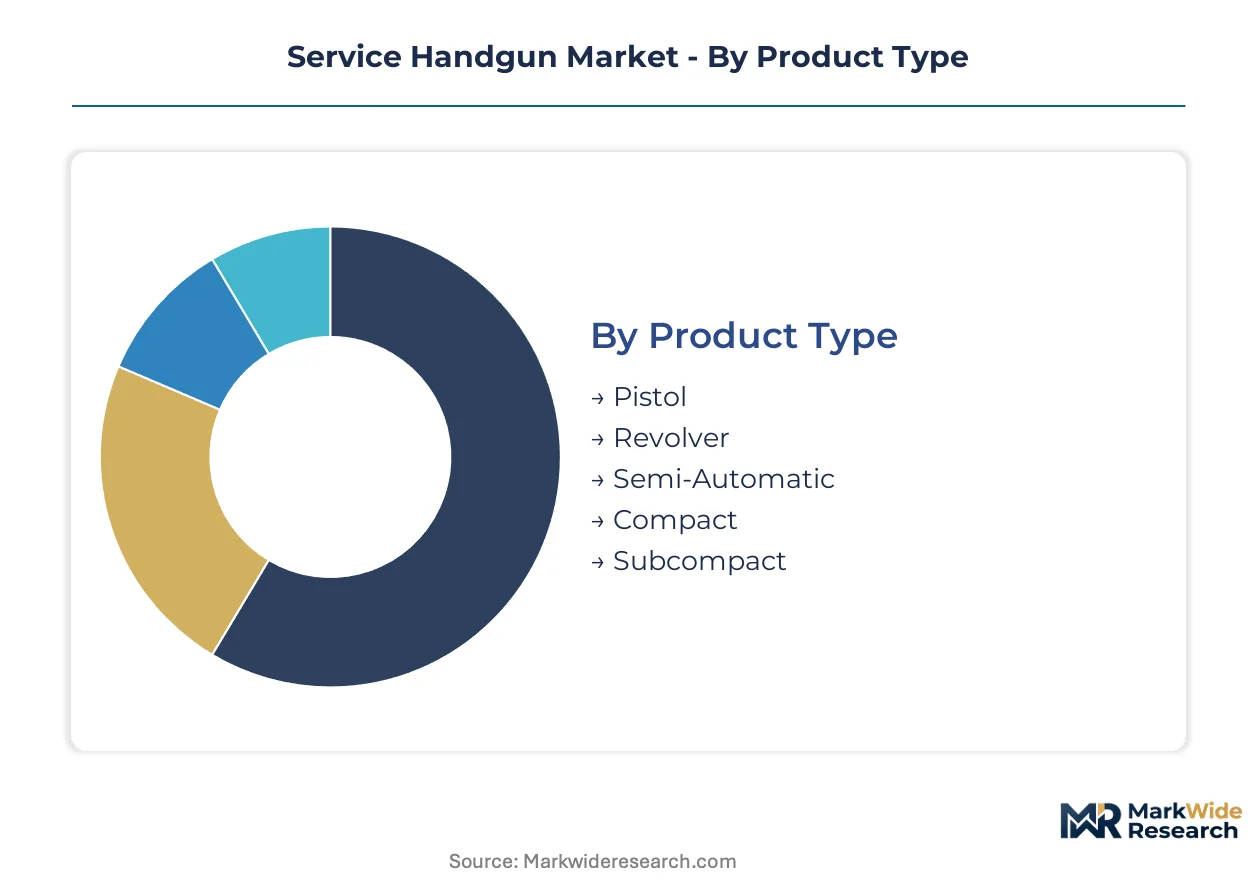
Service handgun procurement patterns diverge sharply across technical specifications, operational contexts, and institutional buyer types. Specification-driven segmentation reveals where manufacturer R&D investments concentrate and which compliance frameworks govern market access.
Product Type:
Barrel length and ammunition capacity specifications determine operational suitability across duty assignments and concealment requirements.
- Pistol:Magazine-fed handguns with detachable ammunition storage dominate institutional procurement volumes. US police departments and federal agencies specify full-size and compact variants for uniformed patrol and plainclothes operations.
- Semi-Automatic:Self-loading mechanisms with slide-cycling operation deliver superior capacity and faster reload cycles than competing architectures. Military and law enforcement procurement offices in the Czech Republic and Germany mandate this platform for NATO ammunition standardization.
- Revolver:Cylinder-rotating manual operation persists in limited backup and specialized duty roles. Some US municipal agencies maintain revolver qualifications for officers preferring simplified manual-of-arms.
- Compact:Reduced barrel length and grip dimensions balance concealability with shootability. Plainclothes law enforcement and private security details in urban environments drive specification requirements.
- Subcompact:Minimal dimensions for deep concealment sacrifice capacity and sight radius. Personal protection permit holders and executive protection specialists generate demand concentration.
Mature deployment sits with Pistol. Newer deployment is concentrated in Subcompact.
Technology:
Ignition mechanisms and frame material specifications reshape reliability testing protocols and manufacturing cost structures.
- Striker-Fired:Spring-tensioned firing pin systems eliminate external hammers and reduce component count. US Army Modular Handgun System requirements and subsequent law enforcement adoptions cement this architecture as the procurement default.
- Polymer Frame:High-impact synthetic construction reduces weight and corrosion susceptibility versus steel alternatives. CNC machining advances and injection molding scale economies enable cost compression across budget-constrained agencies.
- Double Action:Trigger-cock and hammer-drop cycling permits immediate firing without manual preparation. Traditionalist procurement officers in some European defense forces maintain preference for this mechanical redundancy.
- Single Action:Hammer-prepped discharge delivers crisp trigger characteristics valued in precision applications. Competitive shooting and specialized tactical training programs sustain limited demand.
- Double Action Only:Consistent trigger pull weight across all shots simplifies training protocols. Certain US federal agency qualification standards specify this uniformity for liability reduction.
Striker-Fired platforms command the steepest expansion trajectory as NATO standardization and law enforcement fleet modernization accelerate replacement cycles.
Application:
Operational intensity and threat environment specifications determine durability requirements and ammunition selection.
- Law Enforcement:Daily carry and intermittent engagement scenarios demand corrosion resistance and maintenance simplicity. NIJ ballistic testing protocols and armorer training availability drive vendor selection.
- Military Operations:Environmental extremes and suppressed firing requirements impose modular suppressor compatibility and finish durability. US Army and allied defense forces concentrate procurement volume here.
- Personal Protection:Civilian concealed-carry frameworks expand addressable demand beyond institutional channels. Shall-issue permit statutes in multiple US jurisdictions accelerate growth.
- Security Services:Private sector guarding operations balance cost constraints with liability exposure. Armed transport and facility protection contracts generate recurring replacement demand.
- Tactical Training:High-round-count instruction programs prioritize parts availability and armorer support infrastructure. Federal training academies and regional qualification centers sustain this segment.
Law Enforcement absorbs the most mature procurement patterns. Personal Protection is climbing the fastest as civilian licensing frameworks proliferate.
End User:
Budget authority and procurement scale differentiate institutional buyer segments and their specification influence.
- Federal Agencies:Department-wide standardization mandates and integrated logistics support requirements favor sole-source contracting. FBI, DHS, and Treasury bureaus issue multi-thousand unit solicitations with training and parts guarantees.
- Police Departments:Municipal budget cycles and union negotiation timelines compress decision windows. Large agencies in California, Texas, and Florida demonstrate fleet consolidation toward single-platform deployments.
- Defense Forces:NATO interoperability requirements and ammunition supply chain integration dominate specification development. German and Czech military modernization programs illustrate this pattern.
- Private Security Firms:Liability insurance requirements and client contract terms drive certification and training investment. Corporate executive protection and cash-in-transit operations concentrate demand.
Federal Agencies anchor established procurement relationships. Private Security Firms represent the most dynamic expansion channel as outsourced guarding contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in the Czech Republic and tax-advantaged manufacturing corridors in Germany concentrate European production capacity for precision-machined firearm components. These designated zones attract specialized CNC machining investments and polymer compounding facilities serving NATO procurement frameworks.
United States
Federal agency standardization mandates and state-level police department fleet consolidation drive procurement concentration. The Bureau of Alcohol, Tobacco, Firearms and Explosives enforces import restrictions and safety certification requirements that determine market access. Manufacturing clusters in New Hampshire and Arizona host precision machining operations supplying military and law enforcement contracts.
Germany
KBA certification requirements and extended safety validation timelines shape competitive entry for domestic and foreign manufacturers. The Federal Motor Transport Authority equivalent for firearms imposes traceability mandates that favor integrated material science capabilities. Industrial concentrations in Baden-Württemberg and Bavaria maintain specialized polymer formulation and precision steel forging operations.
Czech Republic
NATO interoperability requirements and domestic security force modernization programs sustain demand for striker-fired 9mm platforms. Defense procurement offices specify ammunition supply chain integration compatible with standardized NATO logistics. Manufacturing facilities in Uherský Brod anchor regional production of modular handgun systems for export markets.
Italy
Historical firearm manufacturing heritage and EU Firearms Directive compliance capabilities support specialized production for military and law enforcement export markets. ANSM traceability standards align with broader European harmonization efforts. The Gardone Val Trompia industrial district maintains centuries-old metalworking expertise applied to modern precision manufacturing.
Switzerland
Swissmedic certification alignment with EU standards facilitates cross-border market access for precision-engineered firearm components. Federal procurement requirements emphasize modular platform specifications and environmental durability testing. Manufacturing operations in the Swiss plateau leverage precision engineering traditions for specialized military and security applications.
Service Handgun Market Vendor Landscape
German and Austrian producers anchor one tier; American specialists hold contract-dependent positions in military and federal agency procurement. The vendor structure concentrates around manufacturers with captive military contracts and integrated polymer machining capabilities. Three strategic archetypes dominate: modular platform specialists, polymer-frame scale producers, and precision steel legacy manufacturers. Competitive moves center on sole-source contract awards and armorer training infrastructure deployment.
Within the modular platform tier, SIG SAUER and Heckler & Koch GmbH exemplify manufacturers positioned around military specification requirements. GLOCK Ges.m.b.H. occupies a scale-driven position across global law enforcement procurement. These entities represent archetypes of contract-anchored production and polymer manufacturing specialization respectively.
| Leading Market Players |
|---|
| SIG SAUER |
| GLOCK Ges.m.b.H. |
| Smith & Wesson Brands |
| Heckler & Koch GmbH |
| Fabbrica d'Armi Pietro Beretta S.p.A. |
| Colt's Manufacturing Company |
| Sturm, Ruger & Co. |
| FN HERSTAL |
| Ceska zbrojovka uhersky brod |
| Others |
Supply Flow & Price Mechanics
Striker-fired mechanism standardization is compressing manufacturing cost differentials while concentrating production scale among polymer-frame specialists with captive military contracts. This technical convergence simultaneously elevates R&D amortization burdens for modular platforms and tightens supplier concentration around precision-machining clusters in New Hampshire, Arizona, and Baden-Württemberg.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with federal agencies paying elevated unit costs for rapid fleet replacement cycles while municipal departments absorb longer delivery windows for budget relief. Pricing stratifies across premium, standard, and economy tiers based on NIJ certification level and integrated optics-ready slide configurations. Cost compression in the standard tier is intensifying because polymer injection molding scale economies are diffusing across second-tier manufacturers. Municipal police departments demonstrate the highest price sensitivity due to annual budget appropriation constraints, whereas federal agencies prioritize sole-source reliability guarantees over per-unit expenditure.
Supply Chain Analysis
Freight cost volatility from specialized firearm-grade steel suppliers in Germany and the Czech Republic is elevating landed costs for US-based frame manufacturers without integrated forging capabilities. Component sourcing draws from Austria for striker assemblies, Italy for precision barrels, and domestic US facilities for polymer compounding. Single-source vulnerability concentrates in CNC-machined slide forgings from Baden-Württemberg operations. Distribution runs through federally licensed firearms distributors serving law enforcement procurement offices and military supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled CNC machinist scarcity is constraining production scaling across precision firearm manufacturing, propping pricing power for incumbents with established workforce pipelines in traditional metalworking regions.
For Market Incumbents: Anchor defensive positioning through backward integration into polymer compounding and captive supply of specialized steel alloys. SIG SAUER and GLOCK Ges.m.b.H. should deepen armorer training infrastructure deployment to lock in sole-source contract renewals. Modular platform R&D concentration among three manufacturers with military contracts limits competitive diversity and protects margin structures. For New Entrants and Emerging Players: Private security firms represent the most penetrable channel, with outsourced guarding contracts proliferating faster than institutional procurement cycles. Target concealed-carry permit expansion in shall-issue US states where personal protection margins exceed law enforcement tiers. Pursue distributor partnerships with federally licensed firearms wholesalers serving municipal departments outside major metropolitan consolidation zones. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by defense contractors seeking modular handgun system capabilities for adjacent military vehicle or personal protective equipment platforms. Long-term viability hinges on NATO ammunition standardization alignment and sustained Czech Republic and German defense modernization funding. Watch KBA certification timeline compression as an inflection indicator for non-EU manufacturer market access.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform R&D Investment | US Army MHS requirements force competitors to absorb elevated development costs for interchangeable component architecture. |
| Optics-Ready Slide Integration | Miniature red-dot sight mounting interfaces create premium tier differentiation and aftermarket attachment revenue streams. |
| Armorer Training Infrastructure | Federal agencies award sole-source contracts covering multi-thousand unit deployments with integrated maintenance support guarantees. |
| Polymer Compounding Backward Integration | REACH compliance and ECHA substance restrictions favor manufacturers with in-house material science capabilities. |
| Concealed-Carry Channel Development | Shall-issue permit statutes in multiple US jurisdictions accelerate personal protection segment growth with higher margin profiles. |
Methodological Framework
Independent corroboration across procurement officers at federal law enforcement agencies, state-level police department armorers, and defense ministry acquisition officials underwrites the qualitative findings. Secondary validation draws from NIJ ballistic testing protocol documentation, ATF import restriction filings, and NATO standardization agreement repositories. The analysis combines bottom-up unit shipment estimates from manufacturer production disclosures with top-down budget appropriation analysis across US federal agencies and European defense ministries.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. The analytical framework models segmentation dimensions including product type, ignition mechanism technology, application context, and end-user procurement tier. CAGRs derive from fitted growth curves applied to disclosed contract values and replacement cycle timing. Industry-specific forecast inputs incorporate ammunition standardization debates across NATO frameworks and concealed-carry permit issuance rates by US state jurisdiction.
Caveats apply where modular platform requirement revisions or KBA certification timeline shifts could materially shift the outlook. Forecasts reflect assumptions regarding sustained defense modernization funding in the Czech Republic and Germany, polymer feedstock price stability, and continued striker-fired mechanism standardization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
National Security
US Bulletproof Glass Market
National Security
Asia-Pacific Border Security Market
National Security
Europe Non-Lethal Weapons Market
National Security
Homeland Security Market
National Security
Asia-Pacific Non-Lethal Weapons Market
National Security
Saudi Arabia Manned Security Market
National Security
Research Department Explosive (RDX) Market
National Security
Radiological and Nuclear Security Market
National Security
Global Non Lethal Weapons Market
National Security
Global Security Assessment Market
National Security
Chemical, Biological, Radiological and Nuclear (CBRN) Security Market
National Security
North America Non Lethal Weapons Market