
 Research Department Explosive (RDX) Market | 2026-2036
Research Department Explosive (RDX) Market Size, Share, and Industry Trends Forecast 2026-2036
Research Department Explosive (RDX) Market Analytics
Specialized chemist and energetic materials engineer shortages across Western defense industrial bases is redrawing competitive boundaries in RDX manufacturing. BAE Systems leverages its integrated UK-Australia supply chain to sustain long-term military contracts. Eurenco anchors European production capacity through its nitrocellulose and nitramine expertise. Dyno Nobel competes across commercial mining channels with packaged emulsion systems that extend its civilian revenue base.
Research Department Explosive is a nitramine high explosive with chemical designation cyclotrimethylenetrinitramine, synthesized through the Bachmann process using hexamine, nitric acid, and acetic anhydride, yielding a detonation velocity exceeding 8,750 m/s for military and industrial blasting applications. RDX Powder dominates military formulations where precise particle size distribution governs burn rates and shaped-charge performance. RDX Emulsions represent the fastest-growing product category as mining contractors adopt water-gel blends for safer bulk handling and reduced environmental residue. Government end users command the largest value pool through multi-year ordnance procurement frameworks that lock in volume commitments.
EPA oversight of nitramine wastewater discharge and REACH registration of explosive precursors constrain plant siting and raw material sourcing across US and European facilities. The US Department of Defense mandates domestic source qualification under Berry Amendment provisions, limiting foreign RDX access for critical munitions programs. Stakeholders must monitor evolving EPA effluent guidelines and EU REACH authorization timelines to anticipate capacity relocation and compliance cost pass-through.
Market Dynamics
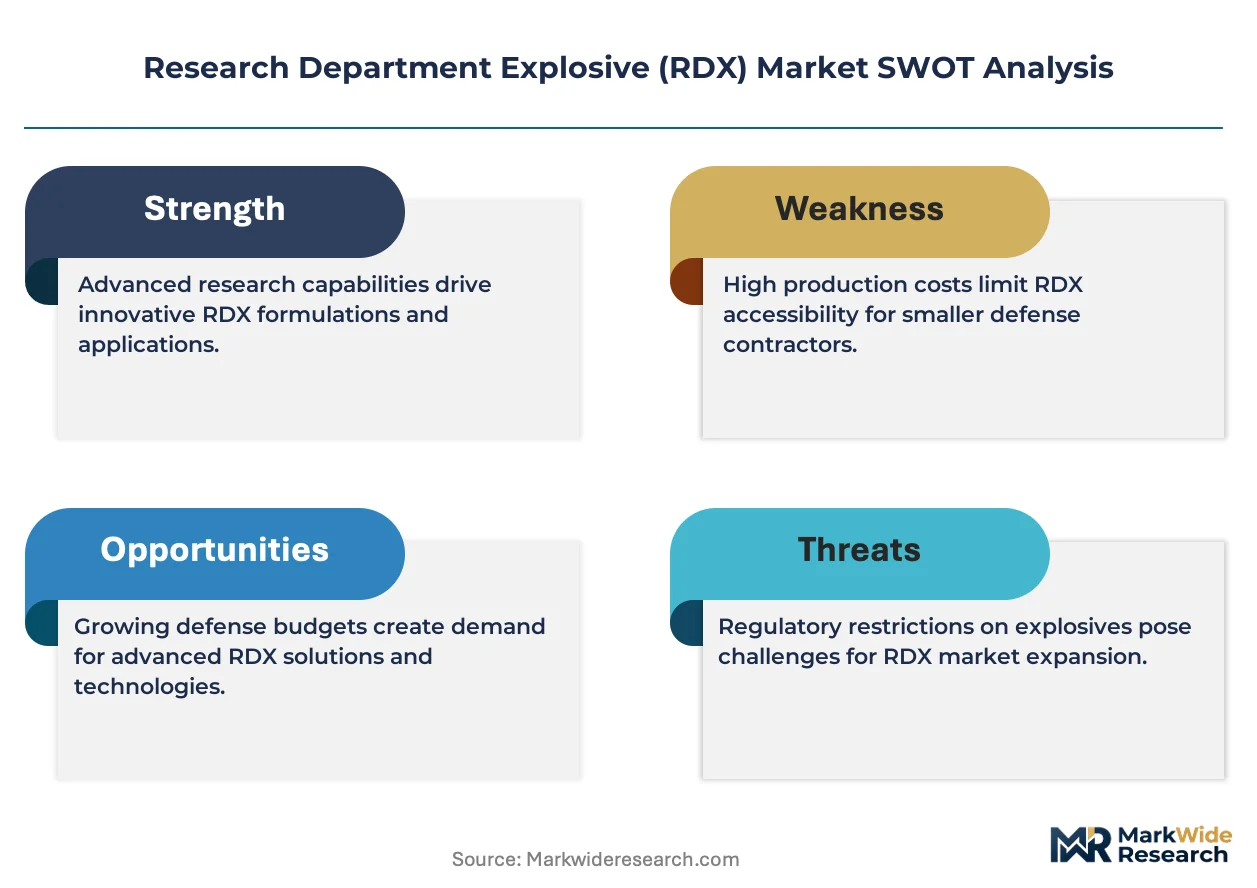
Defense procurement centralization around domestic supply mandates is compressing RDX manufacturing geography, forcing capacity consolidation toward qualified military contractors with integrated synthesis and formulation capabilities.
Growth Catalysts
- NATO Munitions Modernization:Multi-year ordnance frameworks across alliance members are locking in volume commitments for shaped-charge warheads and demolition explosives, sustaining baseline demand for nitramine feedstocks.
- REACH Precursor Registration:European authorization timelines for hexamine and nitric acid derivatives are filtering out non-compliant suppliers, tightening supply-side concentration around certified producers with ECHA-tracked substance dossiers.
- Water-Gel Formulation Advances:Mining contractors are adopting bulk emulsion systems with reduced environmental residue profiles, expanding RDX utilization beyond traditional cast-pressed military applications into commercial blasting channels.
Market Restraints
- Acetic Anhydride Price Volatility:Bachmann process economics hinge on petrochemical-derived acetic anhydride pricing, exposing margin compression during upstream feedstock squeezes.
- Single-Source Hexamine Dependency:Western RDX synthesis relies on concentrated hexamine supply from Asian chemical manufacturers, creating geopolitical exposure in precursor availability.
- EPA Effluent Limitations:Nitramine wastewater discharge restrictions under evolving EPA guidelines are constraining plant siting near water bodies and elevating tertiary treatment capital requirements.
Strategic Opportunities
- Australian Defense Industrial Expansion:AUKUS-related munitions self-sufficiency mandates are opening qualified supplier slots for RDX synthesis and formulation facilities with sovereign capability certification.
- Berry Amendment Compliance Services:US defense contractors require domestic-source qualification documentation, creating advisory and certification revenue streams for testing laboratories and regulatory consultants.
- Continuous Flow Synthesis Integration:Microreactor technology convergence with nitramine chemistry promises safer, scalable production with reduced batch-to-batch variability for precision-matched military specifications.
Industry Challenges
- Energetic Materials Chemist Scarcity:University programs in propellant and explosive chemistry have contracted across NATO defense industrial bases, constraining R&D and plant operations staffing.
- Dual-Use Export Control Complexity:ITAR and EU dual-use regulation classification disputes create licensing delays for RDX-containing components in international munitions sales.
- Legacy Facility Remediation Burden:Decommissioned TNT and RDX production sites carry soil and groundwater contamination liabilities that divert capital from active manufacturing investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Research Department Explosive (RDX) Market |
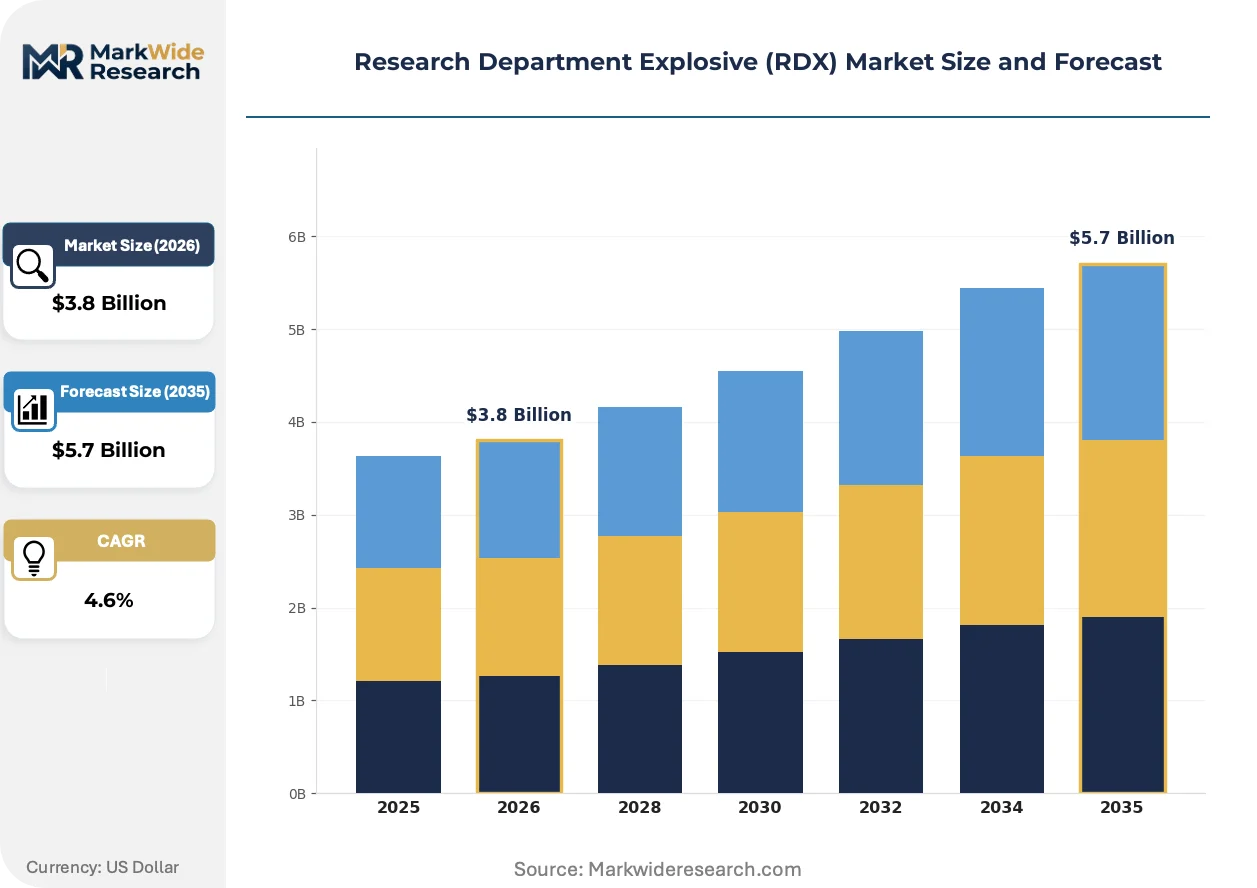
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RDX Powder, RDX Granules, RDX Solutions, RDX Emulsions Application: Military, Commercial, Mining, Demolition End User: Government, Contractors, Mining Companies, Demolition Services Packaging Type: Bulk Containers, Bagged, Canisters, Sachets |
| Companies Covered | BAE Systems, Dyno Nobel, Eurenco, Austin Powder Company, Rheinmetall AG, Chemring Nobel, Nitro Chem S.A., General Dynamics Ordnance & Tactical Systems, Prva Iskra- Namenska a.d., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Research Department Explosive (RDX) Market Evolving Landscape
Process intensification and regulatory stringency are jointly transforming how RDX is synthesized, formulated, and qualified for defense and commercial end uses, with implications for plant economics and competitive positioning.
Micronized RDX with controlled particle size distribution below 5 microns is displacing conventional granular grades in precision-initiation systems and miniaturized warhead designs. US prime contractors are qualifying these ultrafine nitramines for next-generation anti-armor munitions where burn rate predictability governs terminal effectiveness. This particle engineering focus is compressing the addressable market for standard-mesh RDX while elevating technical barriers to qualified supply.
EPA's forthcoming nitramine effluent guidelines under the Clean Water Act are mandating zero-discharge manufacturing or advanced biological treatment for wastewater streams containing cyclotrimethylenetrinitramine residues. Facilities without tertiary treatment infrastructure face capital-intensive upgrades or operational shutdowns. European REACH authorization requirements for explosive precursors are synchronizing with this US regulatory trajectory, creating transatlantic compliance convergence.
Defense procurement offices are consolidating multi-year ordnance awards under single-source or dual-source frameworks with embedded option years, compressing supplier rosters and extending contract tenures. This buyer concentration is displacing spot-market and short-cycle purchasing that historically sustained smaller RDX blenders. The shift is most visible in US Army and Marine Corps munitions programs, where five-year indefinite-delivery contracts now dominate volume allocation.
Research Department Explosive (RDX) Market Segmentation
RDX procurement channels diverge sharply between military ordnance programs and commercial blasting operations. Product form, application setting, and packaging configuration each dictate distinct supply chain economics and qualification requirements.
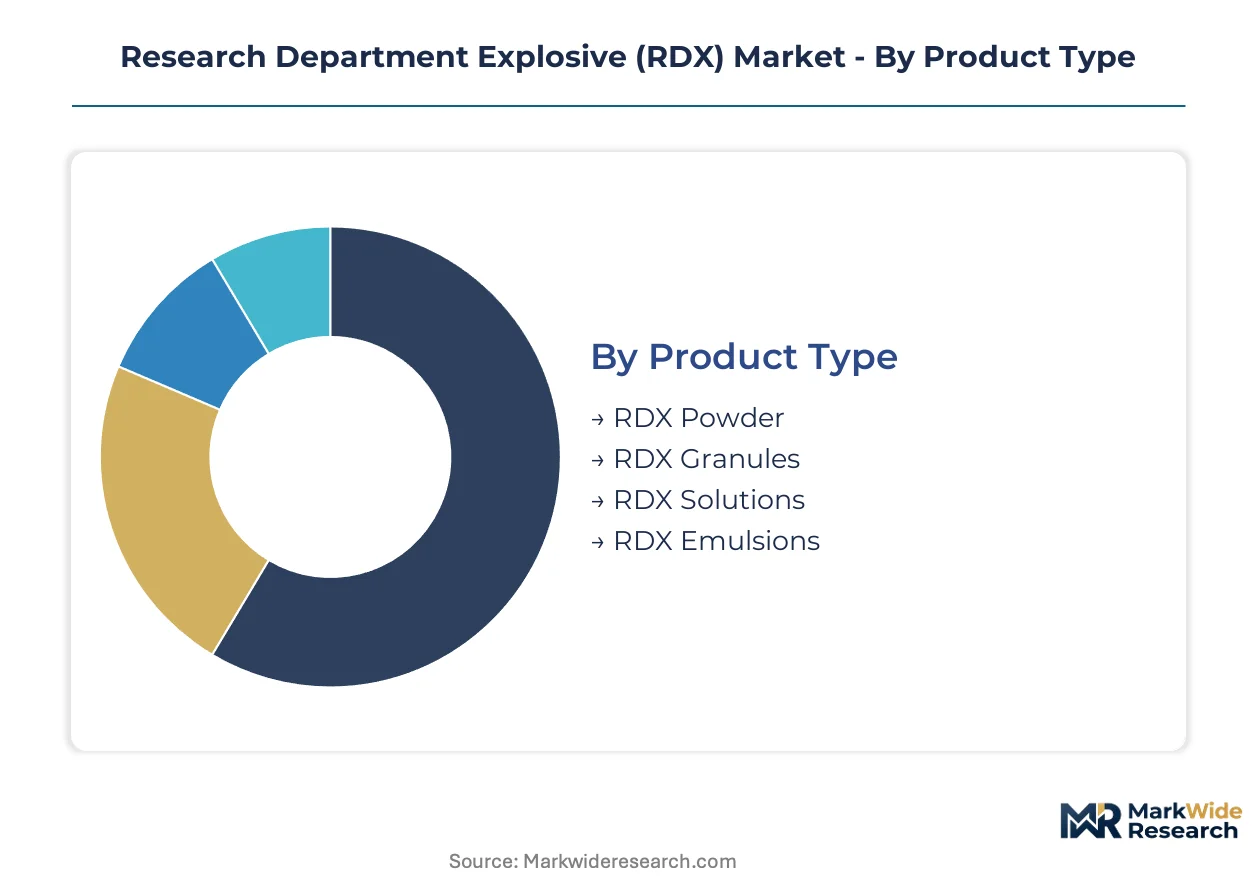
Product Type:
Military contractors source through qualified synthesis-to-formulation pipelines, while mining distributors push bulk emulsion systems through regional blasting supply houses.
- RDX Powder:Micronized nitramine with particle size distribution below 5 microns governs burn rate predictability in shaped-charge warheads. US Army munitions programs concentrate procurement through domestic-qualified synthesis facilities under Berry Amendment compliance.
- RDX Emulsions:Water-gel blends with reduced environmental residue profiles enable safer bulk handling at mine sites. Australian surface coal operations are adopting these formulations fastest as contractors phase out conventional ANFO systems.
- RDX Granules:Standard-mesh crystalline grades serve legacy cast-pressed munitions and demolition charges with established performance specifications.
- RDX Solutions:Solvent-based preparations facilitate precision coating of polymer-bonded explosive substrates for specialized warhead applications.
By volume, RDX Powder leads military procurement. By growth pace, RDX Emulsions are climbing the fastest as mining contractors switch to water-gel systems.
Application:
Defense budgets anchor baseline consumption while commercial end uses expand through formulation innovation and regulatory acceptance.
- Military:Anti-armor munitions, demolition charges, and missile warheads require nitramine purity levels above 99 percent with full batch traceability. NATO procurement centralization around multi-year ordnance frameworks locks in volume commitments.
- Mining:Bulk emulsion systems with RDX sensitizers replace conventional explosives in hard-rock excavation. Surface operations in Australia and Canada are qualifying these blends for seismic consistency and reduced nitrate leaching.
- Commercial:Specialized industrial applications include oil well perforating charges and seismic exploration detonators with precise initiation timing requirements.
- Demolition:Controlled structural implosion and rock breaking utilize cast-pressed charges with predictable fragmentation patterns.
Military applications command premium pricing through qualification overhead. Mining applications are gaining share fastest as emulsion technology matures.
End User:
Procurement authority separates sovereign defense programs from contractor-led commercial blasting operations with diverging compliance burdens.
- Government:National arsenals and defense ministries mandate domestic-source qualification with embedded multi-year option contracts. US Department of Defense programs require Berry Amendment certification for critical munitions.
- Mining Companies:Large diversified miners negotiate direct supply agreements for bulk emulsion systems with integrated technical support and blast design services.
- Contractors:Regional blasting services and specialty demolition firms purchase through authorized distributors with just-in-time delivery requirements.
- Demolition Services:Urban implosion specialists require small-batch precision charges with rapid deployment logistics and strict transport security protocols.
Government end users dominate value capture through long-cycle procurement. Mining companies are expanding volume fastest as bulk emulsion adoption accelerates.
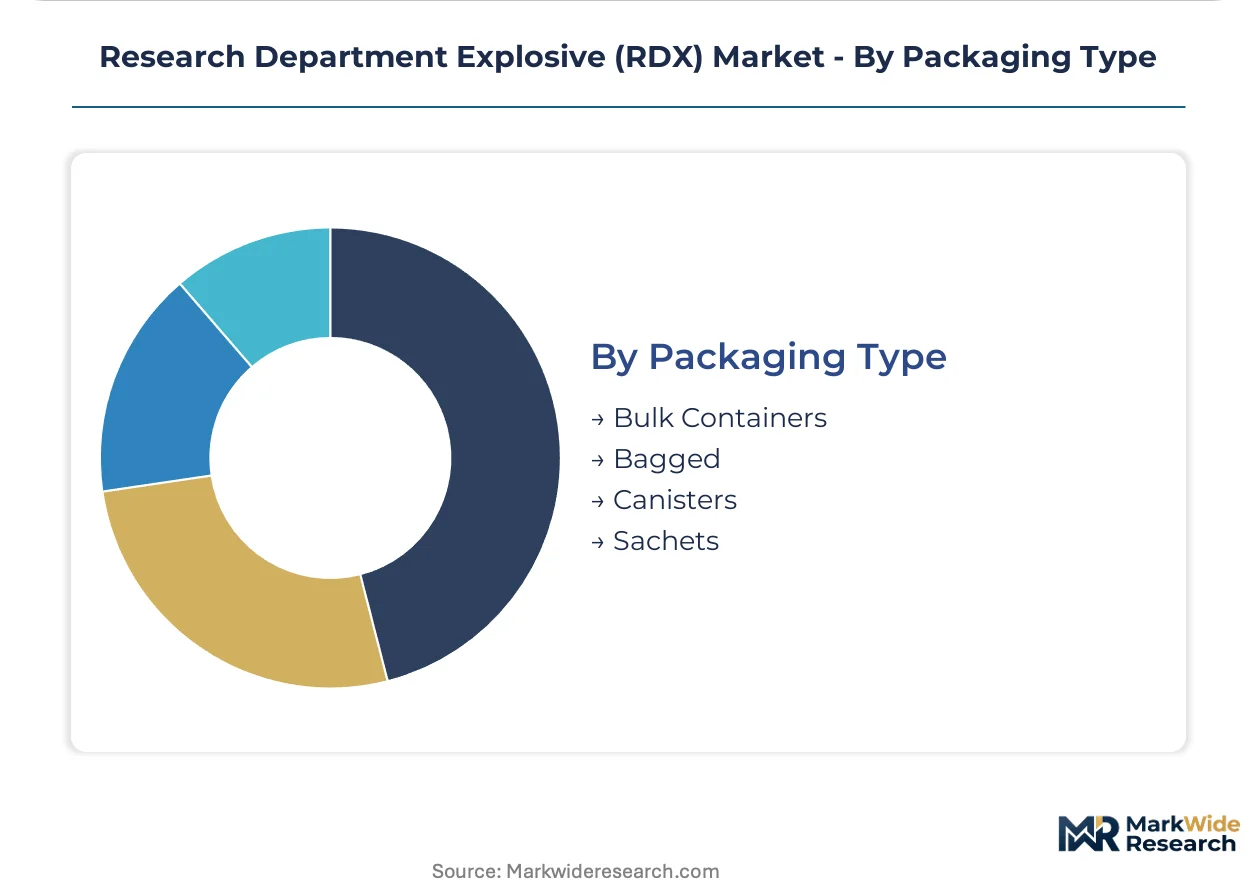
Packaging Type:
Security classification and handling automation requirements shape container selection across defense and commercial channels.
- Bulk Containers:ISO tank systems and intermediate bulk containers serve high-volume mining operations with automated pumping equipment and minimal residual waste.
- Bagged:Multi-wall paper or polymer bags with anti-static liners package granular grades for military logistics and remote site distribution.
- Canisters:Sealed metal containers preserve powder stability during extended storage in arsenals and forward deployment facilities.
- Sachets:Unit-dose flexible packaging supports precision demolition charges and specialized oilfield perforating applications with exact quantity control.
Bulk Containers lead mining procurement by volume. Sachets are expanding fastest through oilfield services adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes RDX predominantly through military procurement channels, while Australia and Canada drive commercial adoption through mining-sector emulsion systems. European markets split between defense arsenals and REACH-regulated industrial applications.
United States
Defense modernization programs and Berry Amendment domestic-source mandates concentrate RDX demand within Pentagon ordnance frameworks. EPA effluent guidelines under the Clean Water Act constrain plant siting near water bodies, forcing tertiary treatment investments. Tennessee and Virginia host qualified synthesis facilities serving Army and Marine Corps munitions programs.
Australia
AUKUS-related munitions self-sufficiency initiatives are expanding sovereign RDX production capacity for allied defense supply chains. The country's national environmental regulator imposes strict nitramine discharge standards on manufacturing facilities. Queensland surface coal operations are adopting bulk emulsion systems fastest, displacing conventional ANFO blasting agents.
Germany
Eurenco anchors European nitramine production through integrated nitrocellulose and RDX synthesis capabilities serving NATO arsenals. ECHA REACH authorization requirements for hexamine and nitric acid derivatives filter supplier compliance. The Rhineland-Palatinate chemical corridor maintains formulation expertise for shaped-charge warheads and demolition explosives.
United Kingdom
BAE Systems leverages integrated UK-Australia supply chains to sustain long-term military contracts across Commonwealth defense programs. The Health and Safety Executive regulates explosive precursor handling through COMAH-tiered controls. Scotland's energetic materials research clusters support precision particle engineering for next-generation anti-armor munitions.
Canada
Hard-rock mining operations in Ontario and British Columbia are qualifying RDX-sensitized emulsion blends for seismic consistency and reduced nitrate leaching. Health Canada's PMRA oversees commercial explosive registration and transport security protocols. The Prairie Provinces host bulk emulsion distribution networks serving potash and metallurgical coal extraction.
Research Department Explosive (RDX) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with defense primes controlling qualified synthesis-to-formulation pipelines while regional blenders serve commercial mining channels. The upper tier consolidates around multi-year ordnance frameworks with embedded option years, compressing supplier rosters. Three archetypes dominate: sovereign defense contractors with captive RDX production, European nitramine specialists with REACH-certified precursor access, and mining explosives distributors with bulk emulsion technical services. Capacity expansion and regulatory compliance certification represent the dominant competitive moves.
Among UK-based defense primes, BAE Systems exemplifies the integrated military contractor archetype through transnational supply chain architecture. Eurenco occupies a position within the European specialist tier, representing REACH-compliant nitramine manufacturing expertise. Dyno Nobel anchors the commercial mining channel, exemplifying packaged emulsion system distribution with integrated blast design services. These three entities represent distinct strategic positions without overlapping competitive territory.
| Leading Market Players |
|---|
| BAE Systems |
| Dyno Nobel |
| Eurenco |
| Austin Powder Company |
| Rheinmetall AG |
| Chemring Nobel |
| Nitro Chem S.A. |
| General Dynamics Ordnance & Tactical Systems |
| Prva Iskra- Namenska a.d. |
| Others |
Value Network & Pricing Analysis
Multi-year indefinite-delivery contracts with embedded option years lock in supply access and price visibility for defense primes, compressing spot-market participation while elevating qualification overhead as a barrier to entry for non-certified blenders.
Pricing Analysis
Long-term offtake agreements dominate defense procurement, with Berry Amendment compliance tiers commanding premium positioning over commercial mining grades. Price differentiation rests on purity certification and domestic-source documentation, with EPA tertiary treatment requirements intensifying cost compression in legacy synthesis facilities. Mining contractors exhibit highest price sensitivity due to emulsion commoditization, while government arsenals prioritize supply security over unit economics.
Supply Chain Analysis
Inventory buffers for hexamine and acetic anhydride extend lead times across Western facilities, with just-in-time precursor management proving untenable given REACH authorization delays and Asian supplier concentration. Synthesis capacity clusters in the United States, Germany, and Australia, with Bachmann process chemistry drawing from petrochemical feedstocks and concentrated nitric acid supply. Single-source hexamine dependency from Asian manufacturers creates geopolitical exposure, while distribution runs through qualified military logistics channels and regional mining explosives distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized energetic materials chemist shortages across NATO defense industrial bases constrain R&D throughput and plant operations, consolidating competitive advantage around incumbent primes with captive training pipelines and apprenticeship architectures.
For Market Incumbents: Secure backward integration into hexamine precursor synthesis or qualified alternative feedstock pathways to mitigate Asian supply concentration risk. Deepen Berry Amendment compliance documentation services to capture advisory revenue from downstream contractors facing domestic-source verification mandates. Capacity expansion in Australia aligns with AUKUS sovereign capability requirements. For New Entrants and Emerging Players: REACH fast-track authorization for nitramine manufacturing offers the most penetrable entry vector for European market access. Target Australian bulk emulsion formulation for mining contractors phasing out ANFO systems, leveraging water-gel technical services as the primary go-to-market wedge. Continuous flow microreactor qualification differentiates against batch-process incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward REACH-certified nitramine specialists with ECHA-tracked substance dossiers and embedded NATO arsenal relationships. Long-term viability hinges on regulatory compliance moats rather than commodity volume exposure. Monitor EPA effluent guideline finalization as the inflection signal for tertiary treatment capex cycles and capacity relocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captive hexamine supply mitigates Asian concentration risk under REACH authorization timelines. |
| Continuous Flow Microreactor Deployment | Microreactor technology reduces batch variability for precision-matched military specifications. |
| Berry Amendment Compliance Certification | Domestic-source documentation services capture advisory revenue from defense subcontractors. |
| Australian Sovereign Capacity Expansion | AUKUS munitions self-sufficiency mandates open qualified supplier slots for allied defense programs. |
| Tertiary Wastewater Treatment Infrastructure | Zero-discharge manufacturing capability satisfies EPA Clean Water Act effluent guidelines. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with energetic materials engineers, defense procurement officers, mining explosives distributors, and EPA compliance consultants; and secondary validation through customs trade records, SEC 10-K filings of defense primes, ECHA substance dossier databases, and Army ordnance program budget justifications. Bottom-up volume triangulation across product grades and end-use applications was cross-checked against top-down defense budget allocation analysis.
Across the projection horizon, the analytical framework modeled segmentation across product form, application setting, end-user procurement authority, and regional regulatory cluster. CAGRs were derived from trend extrapolation of multi-year ordnance contract volumes and mining emulsion adoption curves, with inputs including NATO munitions modernization schedules and EPA effluent guideline implementation timelines.
Underlying assumptions cover sustained defense budget authorization and REACH authorization pathway stability, with deviation risk concentrated in hexamine supply disruptions and acetyl anhydride feedstock price volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
National Security
Europe Non-Lethal Weapons Market
National Security
Chemical, Biological, Radiological and Nuclear (CBRN) Security Market
National Security
Global Security Assessment Market
National Security
Homeland Security Market
National Security
Asia-Pacific Non-Lethal Weapons Market
National Security
Global Non Lethal Weapons Market
National Security
Saudi Arabia Manned Security Market
National Security
North America Non Lethal Weapons Market
National Security
Service Handgun Market
National Security
Asia-Pacific Border Security Market
National Security
US Bulletproof Glass Market
National Security
Radiological and Nuclear Security Market