
 Saudi Arabia Manned Security Market | 2026-2036
Saudi Arabia Manned Security Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Manned Security Market Insights
Corporate buyers are collapsing the historical dominance of government clients in Saudi Arabia's manned security procurement. Allied Universal G4S leverages its international training protocols to compete for banking and hospitality contracts. Arabian Protective Services Group anchors its position through deep relationships with Saudi Aramco and petrochemical complexes. Securitas AB differentiates by integrating Swedish-developed digital reporting tools with on-site guard services.
Manned security encompasses trained personnel providing physical protection through surveillance patrols, access verification, and incident response at client premises, typically operating under 12-hour rotating shifts with real-time communication to central command centers. Static guarding dominates service revenue as oil facilities, government buildings, and luxury retail require fixed-post presence with armed or unarmed personnel. Event security represents the fastest-growing segment as NEOM, Qiddiya, and Red Sea Project developments multiply large-scale entertainment and sporting occasions requiring temporary workforce surge capacity.
The General Authority for Military Industries mandates security clearances for contractors serving defense-adjacent sites, while the Saudi Standards, Metrology and Quality Organization enforces guard licensing and training hour minimums. The National Cybersecurity Authority increasingly requires hybrid physical-digital competency certifications for integrated solutions providers. Stakeholders must monitor how forthcoming localization quotas under the Ministry of Human Resources and Social Development reshape workforce composition and cost structures.
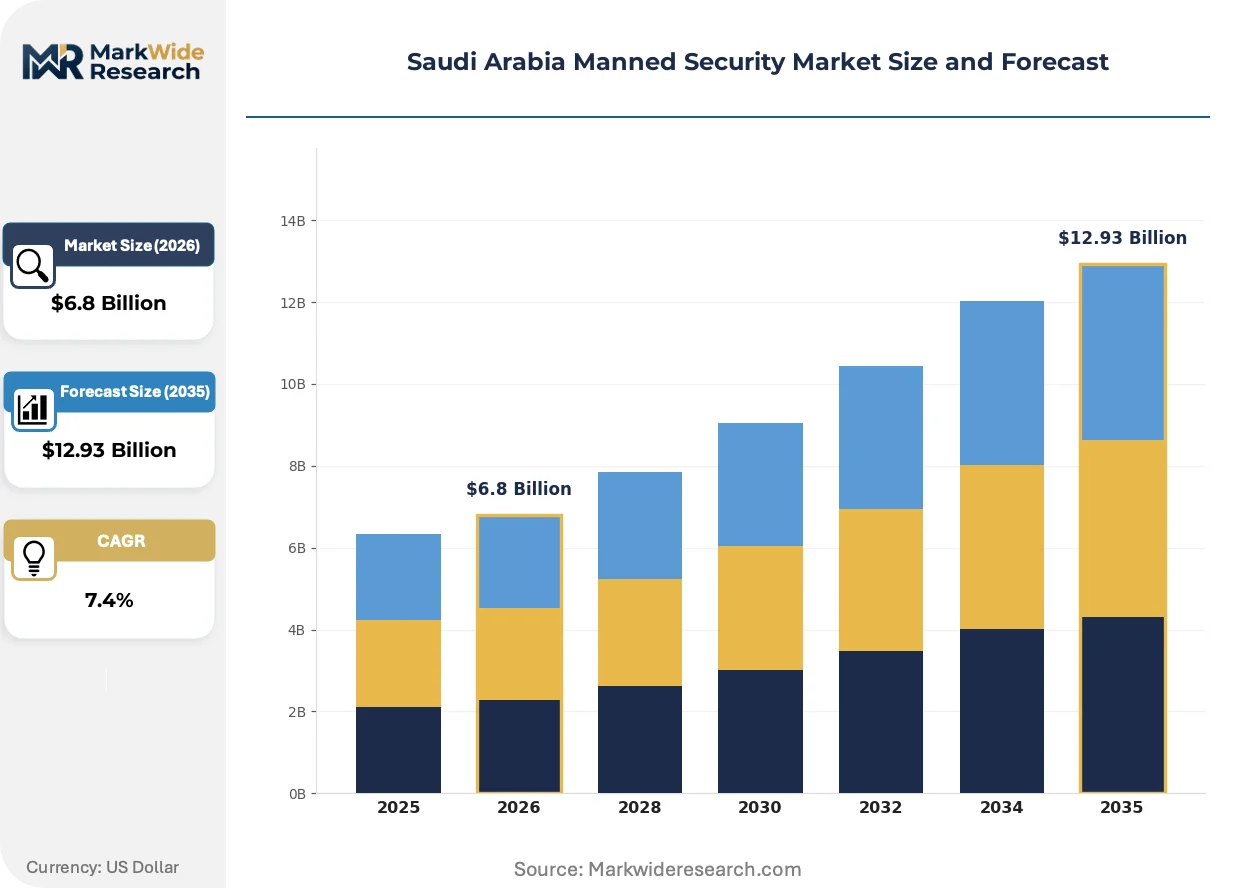
Market Dynamics
Localization mandates under Saudi Vision 2030 are compressing contractor margins while elevating firms with established Saudi workforce pipelines. The Ministry of Human Resources and Social Development's Saudization quotas now require 70% citizen composition in security roles, fundamentally restructuring labor economics.
Growth Catalysts
- Vision 2030 Infrastructure Pipeline:NEOM, Qiddiya, and Red Sea Project developments are generating sustained demand for static guarding and event security services across multi-year construction and operational phases.
- SFDA Facility Security Mandates:Pharmaceutical manufacturing sites and medical device facilities now require armed perimeter protection, creating specialized contract opportunities for cleared contractors.
- Banking Sector Deregulation:Expanded branch licensing for digital banks and fintech entrants is multiplying physical security requirements for cash handling and customer data protection zones.
Market Restraints
- Training Cost Inflation:SAMA certification requirements and firearms licensing for executive protection specialists have raised per-guard onboarding costs substantially.
- Equipment Import Dependency:Surveillance hardware, body armor, and communication systems remain concentrated in US and European supply chains, exposing contractors to currency fluctuation and shipping delays.
- Substitution by AI Surveillance:Facial recognition and behavioral analytics systems are displacing low-skill monitoring posts in retail and logistics facilities.
Strategic Opportunities
- Eastern Province Petrochemical Corridor:Jubail and Ras Tanura industrial cities lack sufficient cleared contractors for critical infrastructure protection, presenting first-mover expansion potential.
- Hybrid Physical-Cyber Certifications:NCA competency requirements are enabling premium pricing for guards trained in access control system administration and incident digital forensics.
- Religious Tourism Security:Umrah and Hajj visitor volume expansion is driving demand for multilingual crowd management specialists at Makkah and Madinah sites.
Industry Challenges
- Retention of Trained Saudi Nationals:Competing public sector employment absorbs qualified graduates from security training academies, forcing repetitive recruitment cycles.
- Integration with Legacy Command Centers:Government ministries and Aramco facilities operate proprietary dispatch protocols that resist standardization with commercial guard management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Manned Security Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Static Guarding, Mobile Patrols, Event Security, Access Control Client Type: Government, Corporate, Residential, Industrial Sector: Hospitality, Retail, Transportation, Healthcare Deployment Model: On-site Services, Remote Monitoring, Temporary Staffing, Integrated Solutions |
| Companies Covered | Allied Universal G4S, Arabian Protective Services Group, Securitas AB, The Arab Security and Safety Services Company (AMNCO), ETH Security Solutions Company LLC, Sharaf Din Security Services, Al Fareeq Security Services, First Security Group, Nesma Security, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Manned Security Market Trends and Innovations
Digital credentialing and real-time workforce verification systems are displacing paper-based guard qualification tracking. This shift is compressing contractor onboarding timelines while elevating compliance transparency expectations among procurement officers at major developments.
Biometric access control is bifurcating the manned security value chain. High-assurance environments including defense-adjacent sites and sovereign wealth fund headquarters are deploying fingerprint and iris recognition at guard posts. Lower-tier commercial real estate is retaining traditional badge-and-escort protocols. This divergence is forcing contractors to maintain dual competency streams or surrender premium segments to specialized rivals.
SAMA's updated Anti-Money Laundering guidelines now mandate physical security audits for all Category 1 and 2 financial institutions. Banks must demonstrate controlled access to server rooms and cash vaults with documented guard patrol logs. Riyadh-based headquarters of national banks are accelerating procurement of integrated guarding and electronic surveillance packages to satisfy examination requirements.
Facility managers at mega-developments are unbundling security from bundled facilities management contracts. NEOM and Red Sea Project procurement teams now issue standalone security RFPs with explicit KPIs for incident response times and guard retention rates. This disintermediation is visible across giga-project developments where direct contractor relationships replace master developer intermediaries.
Saudi Arabia Manned Security Market Segmentation
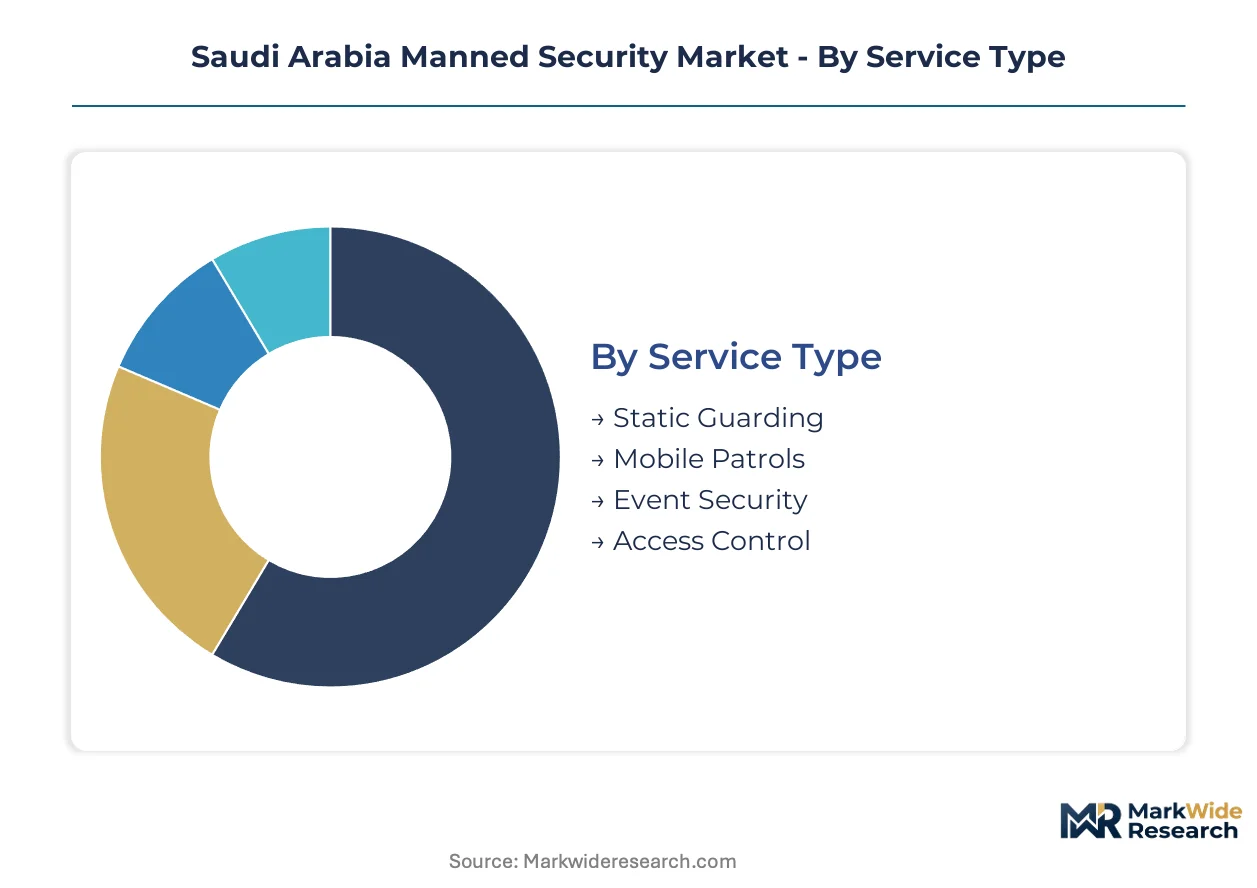
Segmentation in Saudi Arabia's manned security market reveals how procurement patterns diverge across client sophistication levels and threat environments. Understanding these divides enables contractors to align workforce training, equipment investment, and pricing architectures with specific buyer requirements rather than deploying undifferentiated service packages.
Service Type:
Margin pools concentrate in specialized service lines where certification barriers and liability exposure limit competitive entry. Static guarding commands premium pricing at defense-adjacent sites and sovereign wealth fund headquarters where armed clearance requirements apply.
- Static Guarding:Fixed-post personnel maintain continuous physical presence at entry points, perimeters, and critical infrastructure nodes. Oil facilities across the Eastern Province and government ministries in Riyadh anchor demand for armed and unarmed static posts with 12-hour rotating shifts.
- Event Security:Temporary workforce surge capacity supports large-scale entertainment and sporting occasions at NEOM, Qiddiya, and Red Sea Project developments. Crowd management specialists with multilingual capabilities command wage premiums during Umrah and Hajj peak seasons in Makkah and Madinah.
- Mobile Patrols:Vehicle-based guards conduct randomized perimeter checks and alarm response across distributed commercial and industrial campuses.
- Access Control:Personnel verify credentials and manage visitor flow at high-assurance environments including pharmaceutical manufacturing sites subject to SFDA facility security mandates.
Static guarding holds installed capacity. Event security is rotating up the share rankings.
Client Type:
Volume concentration tilts toward institutional buyers with multi-year contract horizons and centralized procurement authority. Corporate clients are expanding contract values faster than historical government dominance would suggest.
- Government:Ministries, military installations, and critical infrastructure operators require security clearances from the General Authority for Military Industries. Procurement standardization is accelerating as the National Cybersecurity Authority mandates hybrid physical-digital competency certifications.
- Corporate:Banking headquarters in Riyadh and hospitality groups in Jeddah are disaggregating security from bundled facilities management contracts. SAMA's updated Anti-Money Laundering guidelines now mandate documented guard patrol logs for server room and cash vault access.
- Residential:Gated communities and luxury developments in urbanizing corridors demand concierge-security hybrid roles.
- Industrial:Petrochemical complexes in Jubail and Ras Tanura require cleared contractors for critical infrastructure protection with specialized hazard response training.
Government contracts anchor revenue stability. Corporate procurement is climbing the fastest.
Sector:
Application-specific compliance requirements are fragmenting service specifications across verticals. Healthcare and transportation are emerging as distinct demand centers with non-overlapping vendor qualification criteria.
- Hospitality:Luxury hotels and entertainment venues at giga-projects require front-of-house guards with customer service orientation and crisis de-escalation training.
- Retail:Shopping malls and luxury brand flagships deploy loss prevention specialists alongside traditional guarding functions.
- Transportation:Airport and logistics facility operators are integrating biometric access control at guard posts with real-time workforce verification systems.
- Healthcare:Hospitals and medical device facilities now require armed perimeter protection under expanded SFDA security mandates for pharmaceutical manufacturing sites.
Hospitality maintains established contract flow. Healthcare is ascending the priority ladder.
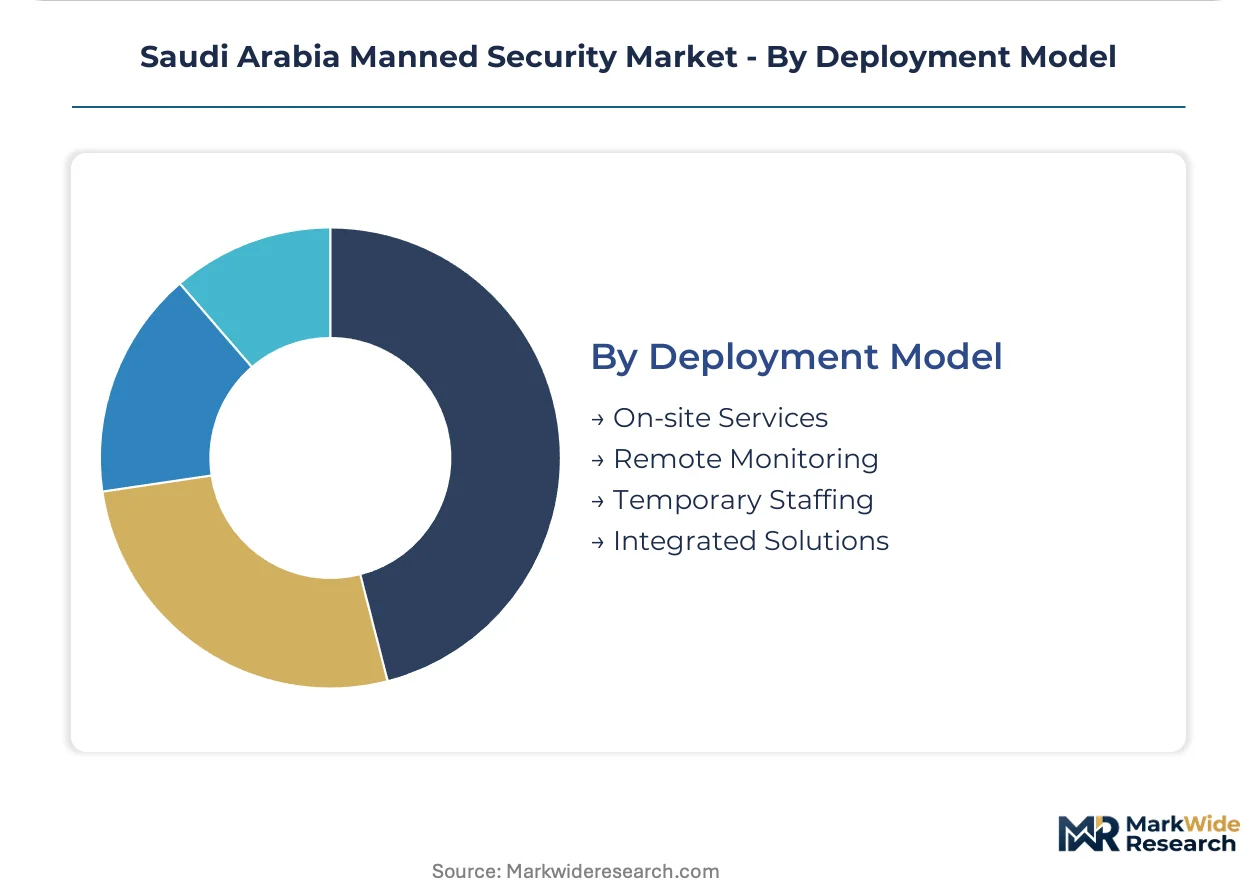
Deployment Model:
Customer type and contract scale dictate deployment architecture preferences. Mega-developments are driving unbundling of security from master facilities management agreements toward direct contractor relationships.
- On-site Services:Dedicated personnel embedded at client premises with real-time communication to proprietary or commercial command centers.
- Remote Monitoring:Centralized surveillance oversight supplements physical presence at lower-threat commercial real estate where AI surveillance is displacing low-skill monitoring posts.
- Temporary Staffing:Surge capacity for construction phases and seasonal events with rapid onboarding enabled by digital credentialing systems.
- Integrated Solutions:Combined guarding and electronic surveillance packages with explicit KPIs for incident response times and guard retention rates at NEOM and Red Sea Project procurements.
On-site services retain contract volume leadership. Integrated solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate buyers in Riyadh and Jeddah now command larger contract values than traditional government procurement channels. Urbanization across the Kingdom is redistributing security demand toward commercial real estate and mega-development corridors.
Riyadh
Banking headquarters and sovereign wealth fund offices concentrate demand for armed clearance-qualified static guarding. SAMA's Anti-Money Laundering guidelines mandate documented patrol logs for server room access. The King Abdullah Financial District anchors premium contract awards for integrated guarding and electronic surveillance packages.
Eastern Province
Petrochemical complexes in Jubail and Ras Tanura generate specialized demand for cleared contractors with hazard response training. The General Authority for Military Industries mandates security clearances for defense-adjacent site access. Ras Tanura industrial city lacks sufficient qualified providers for critical infrastructure protection contracts.
Western Region
Religious tourism expansion at Makkah and Madinah drives seasonal demand for multilingual crowd management specialists. The Ministry of Hajj and Umrah coordinates visitor volume increases requiring temporary workforce surge capacity. Jeddah's hospitality sector disaggregates security from bundled facilities management agreements.
NEOM Northwest
Giga-project developments generate sustained demand for event security and construction-phase temporary staffing. The National Cybersecurity Authority requires hybrid physical-digital competency certifications for integrated solutions providers. The Line and Oxagon zones issue standalone security RFPs with explicit incident response KPIs.
Saudi Arabia Manned Security Market Competitive Landscape
Player mix skews toward Saudi-established operators with Aramco relationships and international specialists with cross-border training protocols. Market structure exhibits tiered consolidation where premium segments favor cleared contractors while commercial real estate tolerates broader participation. Three archetypes dominate: petrochemical-anchored local champions, banking-sector international specialists, and giga-project hybrid integrators. Competitive moves concentrate on workforce Saudization pipeline development and unbundling from master facilities management contracts.
Within the petrochemical-anchored tier, Arabian Protective Services Group occupies a position exemplifying deep industrial relationships. Allied Universal G4S and Securitas AB represent the international specialist archetype, with the former leveraging cross-border banking protocols and the latter integrating digital reporting tools with on-site services. These three companies illustrate how certification depth and client segment focus determine tier placement rather than scale alone.
| Leading Market Players |
|---|
| Allied Universal G4S |
| Arabian Protective Services Group |
| Securitas AB |
| The Arab Security and Safety Services Company (AMNCO) |
| ETH Security Solutions Company LLC |
| Sharaf Din Security Services |
| Al Fareeq Security Services |
| First Security Group |
| Nesma Security |
| Others |
Pricing and Supply Chain Analysis
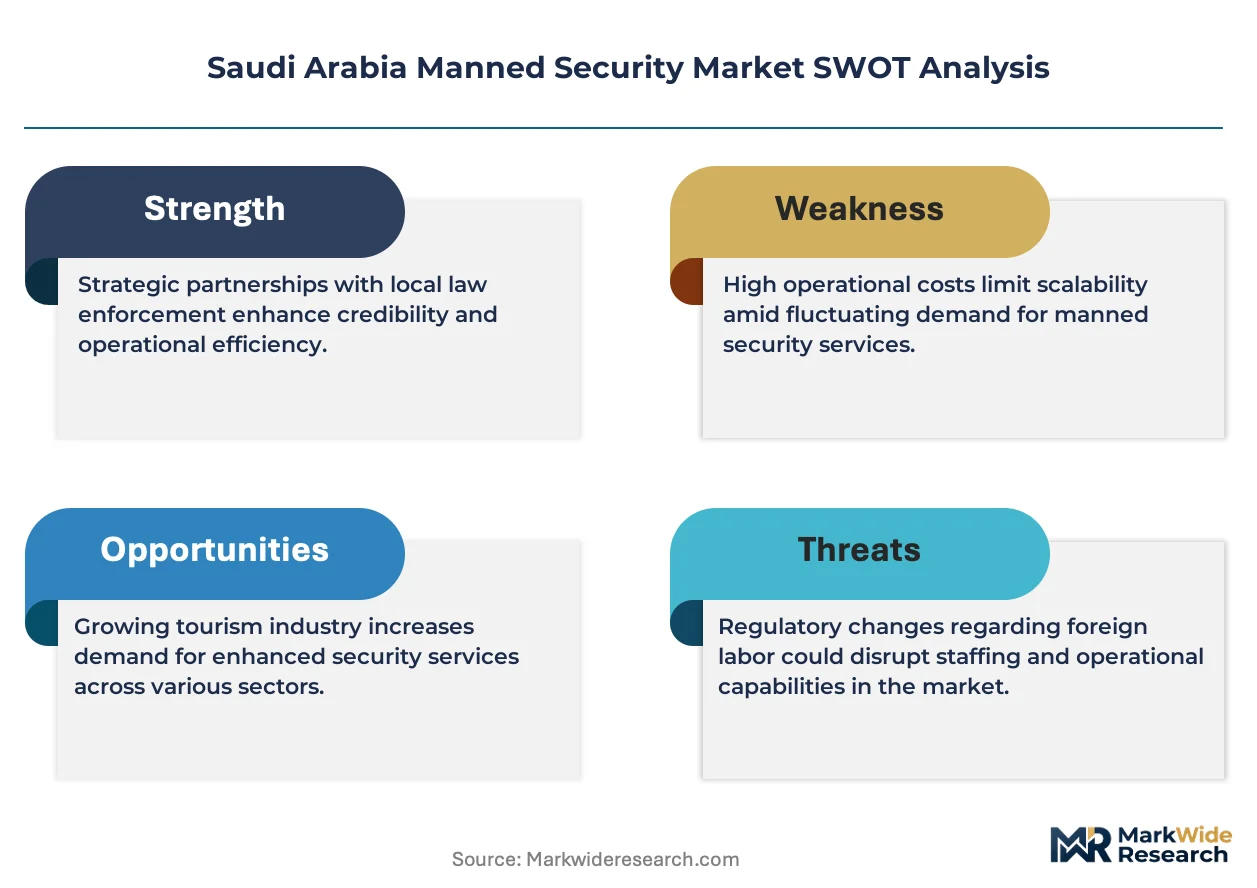
Sixty-to-ninety-day lead times for US- and European-sourced surveillance hardware and body armor compress contractor margins while elevating pricing power for domestic inventory holders. This inventory asymmetry shapes bid competitiveness across Riyadh banking headquarters and Eastern Province petrochemical sites.
Pricing Analysis
Current-gen biometric access control systems command substantial premiums over badge-and-escort protocols, while next-gen AI-integrated surveillance pricing remains aspirational. Three-tier pricing structure across premium, standard, and economy levels separates armed clearance-qualified static guarding from unarmed commercial posts and temporary event staffing. Cost compression in mid-tier commercial real estate is intensifying because SAMA certification requirements and firearms licensing have raised per-guard onboarding costs substantially. Corporate banking clients exhibit lowest price sensitivity due to AML compliance mandates, while retail and logistics facilities demonstrate highest sensitivity as AI surveillance displaces low-skill monitoring posts.
Supply Chain Analysis
The United States and European Union anchor production of advanced surveillance hardware, body armor, and encrypted communication systems. Saudi contractors draw from these concentrated supply bases for critical equipment, with secondary inputs including patrol vehicles and uniform textiles sourced from regional manufacturing. Single-source vulnerability runs through proprietary dispatch protocol integrations required by Aramco facilities and government ministries. Distribution runs through approved vendor lists maintained by the General Authority for Military Industries and National Cybersecurity Authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's manned security market is approaching a platform-economics inflection as digital credentialing systems and real-time workforce verification create interoperability standards between contractor management platforms and client command centers.
For Market Incumbents: Shield premium contract positions by deepening backward integration into Saudi workforce training pipelines to satisfy Ministry of Human Resources and Social Development localization mandates. Prioritize certification investment in hybrid physical-cyber competencies to meet National Cybersecurity Authority requirements for integrated solutions providers, creating barriers against international specialists lacking cleared personnel depth.
For New Entrants and Emerging Players: Differentiate on Eastern Province petrochemical corridor penetration where Jubail and Ras Tanura industrial cities lack sufficient cleared contractors for critical infrastructure protection. Target temporary staffing and event security segments at NEOM and Red Sea Project developments where standalone security RFPs disintermediate master facilities management relationships. Deploy rapid digital credentialing capabilities to compress onboarding timelines for surge capacity contracts.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because Saudization quotas and security clearance requirements create structural moats around established workforce pipelines. Acquisition targets should display deep Aramco or ministry relationships with transferable personnel rosters. Monitor Ministry of Human Resources and Social Development localization quota announcements as inflection indicators for margin compression or expansion across contractor tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Saudization Pipeline Development | Direct workforce localization investments satisfy Ministry of Human Resources and Social Development mandates ahead of quota escalations. |
| Hybrid Certification Acquisition | NCA physical-digital competency certifications enable premium pricing for integrated guarding and electronic surveillance packages. |
| Petrochemical Corridor Expansion | Eastern Province presence captures underserved critical infrastructure contracts requiring General Authority for Military Industries clearances. |
| Digital Credentialing Platform Deployment | Real-time workforce verification systems compress onboarding timelines for NEOM and Red Sea Project temporary staffing RFPs. |
| Banking Sector AML Integration | SAMA-mandated physical security audits create recurring revenue streams through documented guard patrol log services. |
Research Methodology
Initial hypotheses were tested against primary input from security operations directors at banking headquarters, procurement leads at petrochemical complexes, ministry contracting officers, and training academy administrators and refined through secondary validation against General Authority for Military Industries procurement guidelines, National Cybersecurity Authority competency frameworks, SAMA Anti-Money Laundering circulars, and Ministry of Human Resources and Social Development Saudization policy documents. Bottom-up guard deployment estimates across Riyadh, Jeddah, and Eastern Province facilities were triangulated against top-down market sizing derived from contract award tracking at mega-developments.
Variance decomposition across the projection horizon isolates volume drivers from pricing effects within service type, client type, sector, and deployment model segments. CAGRs were derived from regression analysis of historical contract award values against Vision 2030 infrastructure spend trajectories and localization policy implementation schedules. Forecast inputs incorporate Saudization quota phase-ins, SFDA facility security mandate expansion timelines, and giga-project development completion schedules.
Forecasts assume regulatory continuity in Ministry of Human Resources and Social Development workforce policies, National Cybersecurity Authority certification requirements, and SAMA financial institution security mandates; material policy shifts would require re-modeling. Specific risks include accelerated AI surveillance substitution, public sector recruitment competition for trained Saudi nationals, and import restriction escalations affecting surveillance hardware availability. Recalibration cycles align with material shifts in localization enforcement intensity and giga-project procurement award announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
National Security
Global Non Lethal Weapons Market
National Security
Asia-Pacific Border Security Market
National Security
Research Department Explosive (RDX) Market
National Security
Radiological and Nuclear Security Market
National Security
Chemical, Biological, Radiological and Nuclear (CBRN) Security Market
National Security
Service Handgun Market
National Security
Asia-Pacific Non-Lethal Weapons Market
National Security
Homeland Security Market
National Security
Europe Non-Lethal Weapons Market
National Security
North America Non Lethal Weapons Market
National Security
Global Security Assessment Market
National Security
US Bulletproof Glass Market