
 Asia-Pacific Non-Lethal Weapons Market | 2026-2036
Asia-Pacific Non-Lethal Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Non-Lethal Weapons Market Outlook
Directed-energy miniaturization is reconfiguring how non-lethal payloads integrate with standard-issue platforms across Asia-Pacific defense forces. Axon Enterprise leverages its body-worn ecosystem to anchor police procurement channels in Australia and Southeast Asia. Rheinmetall AG competes through its modular less-lethal systems designed for tropical operational environments. Combined Systems Inc. specializes in chemical agent formulations that meet varying national toxicity thresholds.
Non-lethal weapons encompass devices engineered to incapacitate personnel or materiel while minimizing permanent injury, typically operating through kinetic impact below penetration thresholds, chemical irritant dispersion, or electrical neuromuscular disruption at controlled amperage. These systems serve primarily to project force in asymmetric security scenarios where lethal engagement carries political, legal, or collateral costs. Stun guns and electric shock devices represent the fastest-expanding product category as battery energy density improves and unit costs decline. Chemical agents maintain the largest installed base across riot control applications, though margin pools are shifting toward laser systems as semiconductor laser diodes achieve military-grade reliability.
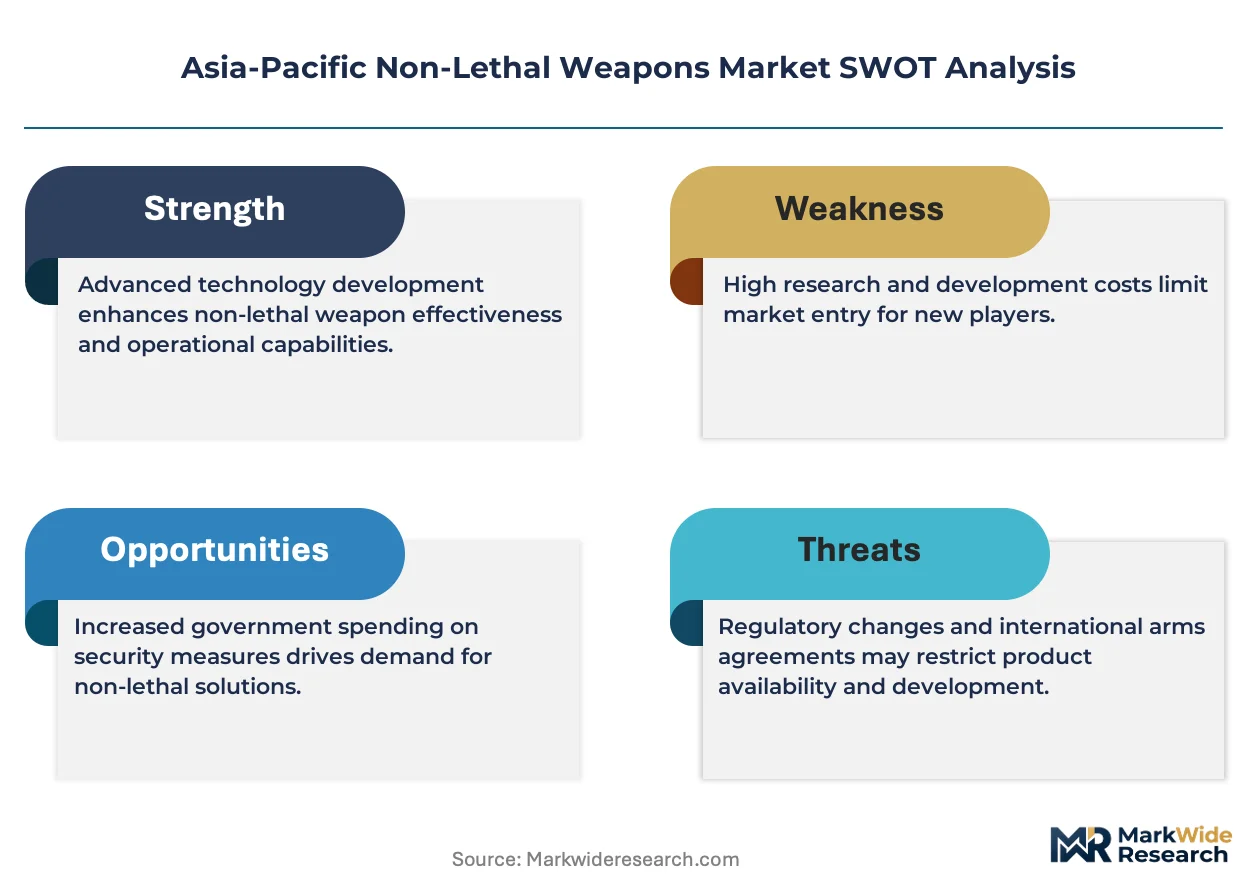
Japan's METI sets industrial standards for electromagnetic pulse devices that constrain import pathways for non-certified suppliers. Australia's TGA and South Korea's MFDS regulate chemical agent formulations through distinct toxicity classification regimes that fragment product homologation requirements. India's BIS certification mandates for security equipment create additional market access filters. Stakeholders must monitor how divergent national standards for temporary incapacitation thresholds reshape product development roadmaps and partnership structures.
Market Dynamics
Directed-energy miniaturization is compressing payload integration cycles across Asia-Pacific defense procurement channels, forcing suppliers to reconfigure product architectures around semiconductor laser diodes and solid-state power electronics rather than legacy chemical-delivery mechanisms.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for domestic defense manufacturing are accelerating local assembly capacity for directed-energy systems and reducing import dependency for law enforcement agencies.
- Urban security modernization:China's municipal police forces are expanding procurement of acoustic and optical deterrent systems for crowd management in megacity deployments.
- Battery energy density improvements:Lithium-polymer cell advances are extending operational duration of portable electric shock devices while shrinking form factors below 300 grams.
Market Restraints
- Input cost volatility:Rare earth element prices for neodymium magnets in acoustic weapons fluctuate with Chinese export quota adjustments, squeezing margin predictability for system integrators.
- Technical limitation:Atmospheric humidity above 80% degrades effective range of 445-nanometer laser dazzlers below operational thresholds in tropical Southeast Asian climates.
- Regulatory friction:Australia's TGA toxicity classification regime for oleoresin capsicum formulations creates 18-24 month homologation timelines that block rapid product refresh cycles.
Strategic Opportunities
- Vietnam's underpenetrated procurement:Ministry of Public Security modernization programs lack established supplier relationships, creating first-mover positioning for modular less-lethal system vendors.
- Technology convergence:Integration of millimeter-wave active denial systems with AI-enabled targeting sensors enables precision engagement at 500-meter standoff distances.
- Regulatory tailwind:Japan's METI electromagnetic pulse device standards are creating certified supplier lists that advantage pre-qualified component manufacturers.
Industry Challenges
- Skill gap in directed-energy engineering:Asia-Pacific defense industrial bases lack sufficient quantum optics specialists to support field repair networks for solid-state laser platforms.
- Certification timeline compression:India's BIS security equipment mandates require parallel testing protocols that extend product launch windows by 8-12 months versus unregulated markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Non-Lethal Weapons Market |
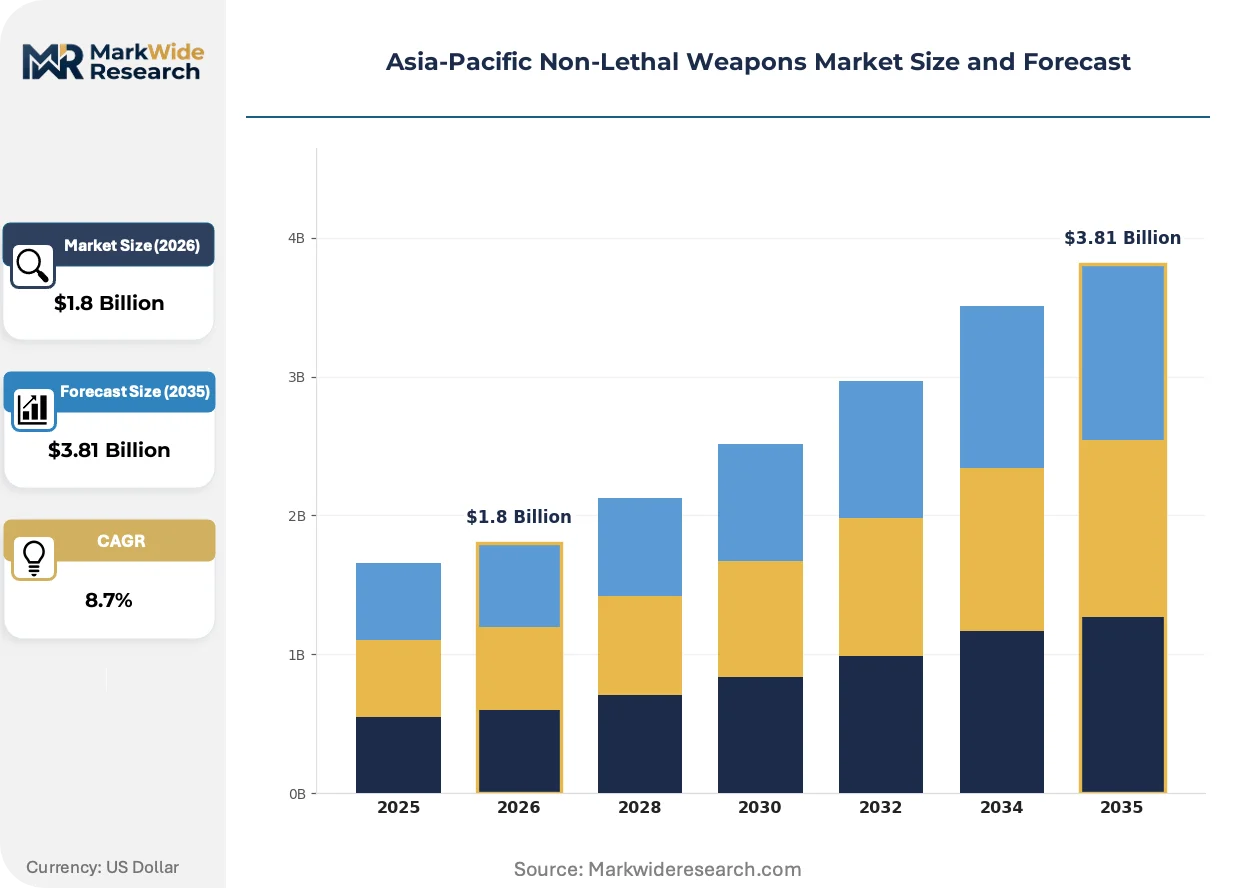
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Bullets, Tear Gas, Stun Guns, Electric Shocks Application: Law Enforcement, Riot Control, Military Training, Crowd Management End User: Government Agencies, Security Firms, Military Organizations, Private Security Technology: Laser Systems, Chemical Agents, Kinetic Energy, Electromagnetic Pulses |
| Companies Covered | Axon Enterprise, Combined Systems Inc., Condor Non-Lethal Technologies, RUAG Group, Safariland LLC, Rheinmetall AG, BAE Systems, Raytheon Technologies, General Dynamics Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Non-Lethal Weapons Market Strategic Shifts
Weapon system architectures are converging around software-defined payload management, enabling single platforms to switch between kinetic, optical, and electrical deterrent modes through firmware updates rather than hardware swaps.
Millimeter-wave active denial technology is digitizing engagement protocols for area denial scenarios. Singapore's police services are piloting vehicle-mounted systems with real-time thermal feedback loops. This capability is digitizing command-and-control hierarchies by enabling remote authorization chains that bypass traditional escalation procedures.
South Korea's MFDS revised chemical agent toxicity thresholds are compressing permissible concentration bands for CS gas formulations by 40%. Domestic manufacturers are reformulating irritant payloads around synthetic capsaicin analogs. Riot control equipment suppliers in Thailand and Indonesia face compliance recertification costs that favor larger formulation houses with in-house toxicology laboratories.
Police procurement departments are consolidating vendor relationships around integrated platform ecosystems rather than point-product acquisitions. Australian state police forces now require API-compatible body-worn cameras, less-lethal launchers, and evidence management software from single-source contracts. This behavioral shift is most visible in Victoria and Queensland, where multi-year framework agreements have displaced annual competitive tenders for crowd control equipment.
Asia-Pacific Non-Lethal Weapons Market Segmentation
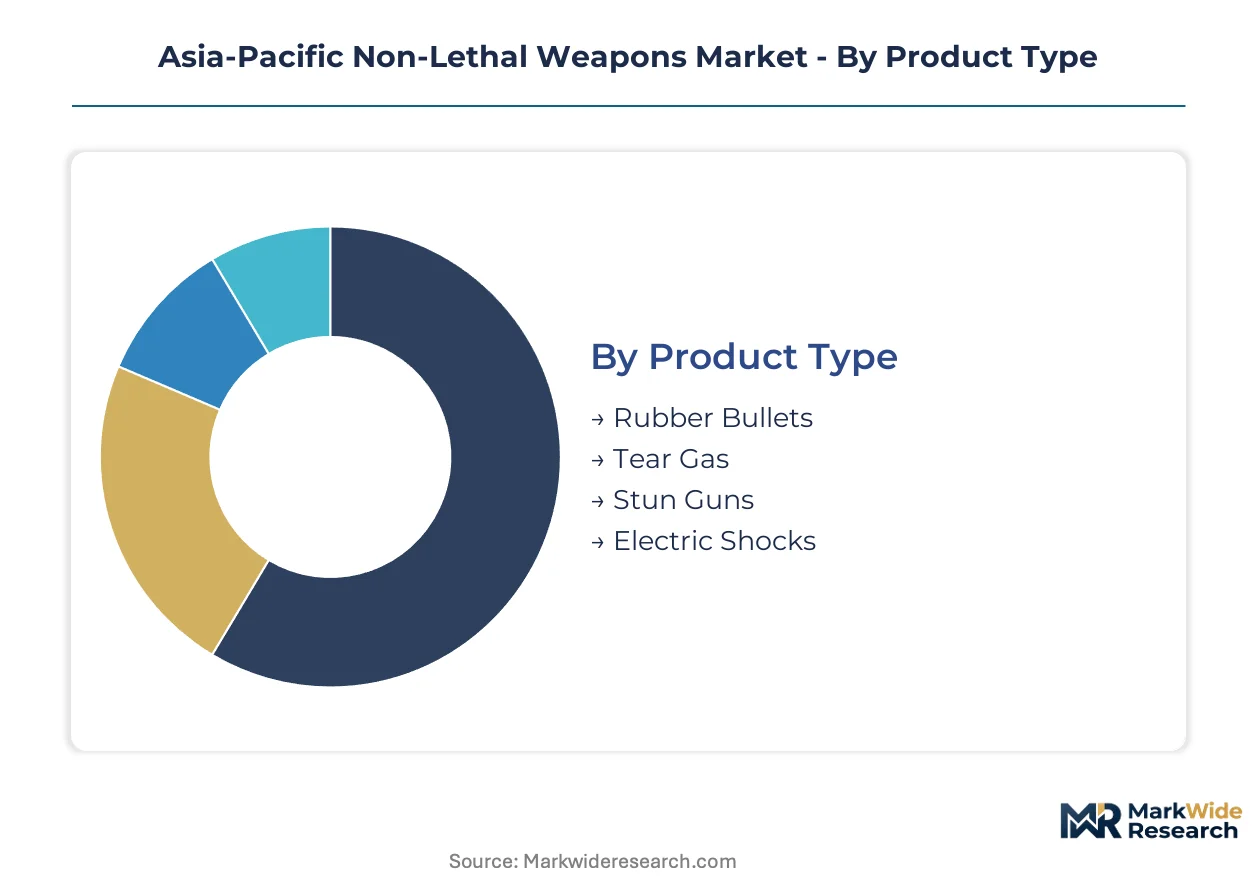
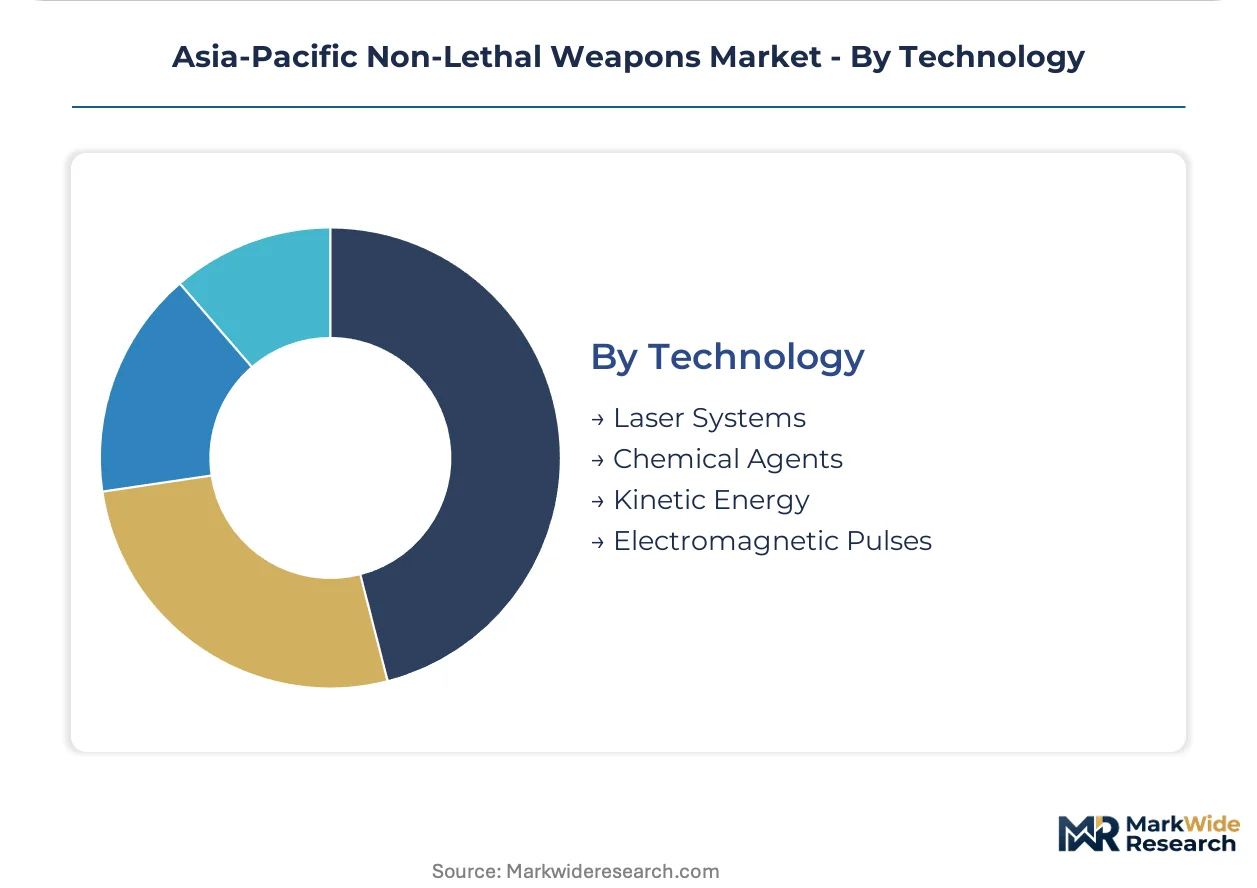
Non-lethal weapons procurement across Asia-Pacific fragments sharply across operational contexts, with riot control protocols demanding chemical saturation capabilities while urban policing prioritizes precision electric systems. Technology selection varies by humidity exposure, regulatory toxicity thresholds, and platform integration requirements.
Product Type:
Use-case spectrum spans kinetic crowd dispersion, chemical area denial, and targeted neuromuscular incapacitation with divergent platform footprints.
- Stun Guns:Portable electric shock devices deliver neuromuscular disruption through barbed probe deployment or direct contact electrodes. China's municipal police forces are standardizing compact units under 300 grams for bicycle patrol units as lithium-polymer energy density improves.
- Tear Gas:Aerosolized irritant formulations—primarily CS (ortho-chlorobenzylidene malononitrile) and OC (oleoresin capsicum)—create temporary respiratory and ocular incapacitation. South Korea's MFDS toxicity threshold revisions are compressing permissible concentration bands by 40%, forcing reformulation toward synthetic capsaicin analogs.
- Rubber Bullets:Kinetic impact munitions fired from standard rifle platforms at reduced velocities below penetration thresholds. Indian paramilitary units deploy 12-gauge variants for stone-pelting scenarios in Kashmir Valley operations.
- Electric Shocks:Conducted electrical weapons with tethered dart systems enabling 5-15 meter standoff engagement. Australian state police procurement requires API-compatible integration with body-worn camera ecosystems.
Established volume favors tear gas; emerging adoption favors stun guns.
Application:
Cost tier stratification separates budget-constrained training programs from premium-specification crowd management systems with real-time command integration.
- Law Enforcement:Routine patrol and arrest scenarios requiring graduated force escalation with minimal collateral injury risk. Japan's National Police Agency specifies METI-certified electromagnetic pulse devices for specialized arrest teams.
- Crowd Management:Megacity deployments of acoustic and optical deterrent systems for unauthorized assembly dispersal. Singapore's police services pilot vehicle-mounted millimeter-wave active denial with thermal feedback loops.
- Riot Control:Sustained area denial against organized civil unrest requiring persistent irritant saturation or kinetic barrier projection. Thailand's Royal Thai Police maintain stockpiles for Bangkok metropolitan corridor contingencies.
- Military Training:Force-on-force simulation and rules-of-engagement rehearsal with non-lethal munitions. Australian Defence Force urban warfare exercises incorporate dye-marking kinetic rounds for after-action assessment.
Margin concentration sits with crowd management; volume scale concentrates in law enforcement.
End User:
Customer type determines procurement channel access, with government tenders demanding BIS certification in India and framework agreements dominating Australian state-level acquisition.
- Government Agencies:National and subnational police forces with centralized procurement authority and multi-year equipment refresh cycles. India's Ministry of Home Affairs channels PLI scheme incentives toward domestic assembly of directed-energy systems.
- Military Organizations:Armed forces requiring non-lethal options for peacekeeping, checkpoint security, and detention facility operations. Vietnam's Ministry of Public Security modernization programs lack established supplier relationships, creating first-mover positioning opportunities.
- Security Firms:Private sector guarding services with fragmented purchasing power and price-sensitive specification requirements. Indonesian mining sector contracts drive regional demand for perimeter denial capabilities.
- Private Security:Corporate and residential protection services with limited training infrastructure favoring simple-operational systems. Philippine shopping mall operators deploy acoustic deterrents for parking facility management.
Procurement sophistication peaks with government agencies; growth velocity runs through military organizations.
Technology:
Maturity gradient separates field-proven chemical delivery mechanisms from solid-state laser platforms constrained by atmospheric humidity degradation.
- Chemical Agents:Irritant and incapacitating compound formulations delivered through grenade, spray, or aerosol dispersion. Australia's TGA toxicity classification regime imposes 18-24 month homologation timelines that block rapid product refresh.
- Laser Systems:Semiconductor diode platforms emitting 445-nanometer visible light for temporary visual impairment. Atmospheric humidity above 80% degrades effective range below operational thresholds in tropical Southeast Asian climates.
- Kinetic Energy:Impact munitions utilizing rubber, foam, or beanbag projectiles fired at sub-lethal velocities. Rare earth element price volatility for neodymium magnets in acoustic weapons squeezes margin predictability.
- Electromagnetic Pulses:Directed-energy systems inducing temporary sensory or motor dysfunction through radiofrequency or microwave exposure. Japan's METI industrial standards constrain import pathways for non-certified suppliers.
Technology convergence favors laser systems; operational reliability favors chemical agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Law enforcement agencies across Asia-Pacific concentrate procurement authority at national ministries, creating distinct buyer archetypes that favor either domestic assembly partnerships or established foreign supplier relationships depending on local industrial policy.
China
Municipal police forces in megacities drive acoustic and optical deterrent procurement for crowd management in unauthorized assembly scenarios. The country's GB standards for security equipment establish technical baselines that foreign suppliers must meet through joint ventures. Manufacturing clusters in the Yangtze River Delta produce laser diode components for directed-energy platforms serving urban security modernization programs.
India
Paramilitary units deploy kinetic impact munitions for stone-pelting containment in sensitive border regions. The Ministry of Home Affairs channels PLI scheme incentives toward domestic assembly of directed-energy systems, reducing import dependency. Industrial corridors in Gujarat and Tamil Nadu host emerging security equipment fabrication facilities.
Japan
The National Police Agency specifies METI-certified electromagnetic pulse devices for specialized arrest teams requiring graduated force options. METI industrial standards constrain import pathways for non-certified suppliers, creating certified supplier lists. Precision manufacturing clusters in the Kanto region supply solid-state power electronics for directed-energy platforms.
Australia
State police forces in Victoria and Queensland consolidate procurement around integrated platform ecosystems requiring API-compatible body-worn cameras and less-lethal launchers. The TGA toxicity classification regime imposes extended homologation timelines for chemical agent formulations. Urban centers along the eastern seaboard pilot vehicle-mounted millimeter-wave systems with thermal feedback loops.
Vietnam
Ministry of Public Security modernization programs lack established supplier relationships, creating positioning opportunities for modular less-lethal system vendors. The country's national defense regulator maintains evolving technical standards for security equipment imports. Industrial zones near Hanoi and Ho Chi Minh City attract component assembly investments for regional security equipment supply.
Asia-Pacific Non-Lethal Weapons Market Competitive Environment
Channel-controlling players compete with product-specialist players across Asia-Pacific procurement channels, yielding a tiered structure where integrated platform vendors capture multi-year framework agreements while point-product suppliers fight for annual tenders. Consolidation pressures concentrate around police procurement departments demanding single-source contracts spanning cameras, launchers, and evidence management software. Three archetypes dominate: body-worn ecosystem integrators, tropical-environment modular system designers, and chemical formulation houses with in-house toxicology capabilities. M&A activity targets API-compatible software assets, while capacity expansion focuses on lithium-polymer cell integration for portable electric platforms.
Within the integrated-platform tier, Axon Enterprise anchors police procurement channels in Australia and Southeast Asia through its body-worn ecosystem. Rheinmetall AG occupies a position among European-based defense contractors competing via modular less-lethal systems. Combined Systems Inc. exemplifies the chemical formulation specialist archetype, with its concentration on irritant payloads navigating varying national toxicity thresholds. These three represent distinct competitive vectors: ecosystem lock-in, environmental adaptation, and regulatory compliance specialization.
| Leading Market Players |
|---|
| Axon Enterprise |
| Combined Systems Inc. |
| Condor Non-Lethal Technologies |
| RUAG Group |
| Safariland LLC |
| Rheinmetall AG |
| BAE Systems |
| Raytheon Technologies |
| General Dynamics Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Yangtze River Delta laser diode fabrication clusters is compressing component pricing for directed-energy platforms while simultaneously eroding supplier willingness to honor long-term fixed-price contracts. This utilization dynamic forces procurement officers across Asia-Pacific law enforcement agencies to choose between spot-market volatility and cost-plus arrangements with indexation clauses tied to rare earth element benchmarks.
Pricing Analysis
Cost-plus contracts with rare earth element indexation dominate procurement agreements for acoustic and directed-energy systems across the region. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified electromagnetic pulse devices from uncertified imports and refurbished legacy stock. Pricing pressure stems from lithium-polymer cell cost compression as Chinese cylindrical cell manufacturers expand automotive-grade capacity. Government agencies exhibit lowest price sensitivity due to multi-year framework agreements, while private security firms in Indonesia and the Philippines drive hard bargaining on unit economics.
Supply Chain Analysis
Export control regimes limiting semiconductor laser diode flows from the United States and Japan are fragmenting supplier qualification pathways for non-certified system integrators. Manufacturing concentration centers on China, South Korea, and Japan for solid-state power electronics and lithium-polymer cells. Neodymium magnet supply draws from Chinese rare earth processing facilities, gallium arsenide substrates from Japanese precision manufacturers, and optical coatings from South Korean thin-film specialists. Single-source vulnerability around Japanese gallium arsenide wafer supply creates chokepoint exposure for 445-nanometer laser platform assembly. Distribution runs through national procurement authorities with BIS certification requirements in India and METI pre-qualification in Japan filtering channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as battery energy density improvements and semiconductor laser reliability cross threshold levels for mass law enforcement deployment. Directed-energy miniaturization is accelerating procurement refresh cycles beyond traditional chemical-agent replacement timelines.
For Market Incumbents: Harden ecosystem lock-in by embedding API-compatible firmware architectures that raise switching costs for Australian and Japanese police forces evaluating multi-year framework renewals. Acquire in-house lithium-polymer cell integration capabilities to reduce exposure to Chinese cylindrical cell pricing volatility. Certification investment in India's BIS security equipment mandates creates defensive moats against modular system competitors.
For New Entrants and Emerging Players: Vietnam's Ministry of Public Security modernization programs represent the most penetrable entry point given absent incumbent relationships and evolving technical standards for security equipment imports. Modular less-lethal systems designed for tropical operational environments address humidity-degradation limitations that constrain 445-nanometer laser dazzler effectiveness in Southeast Asian climates. Partnership with established regional distributors possessing existing police procurement channel access accelerates first-mover positioning.
For Investors and Strategic Acquirers: Capital is best deployed toward chemical formulation houses with in-house toxicology laboratories capable of navigating Australia's TGA and South Korea's MFDS toxicity classification recalibrations. Long-term viability hinges on regulatory compliance specialization rather than hardware commoditization. The signal to watch is BIS certification timeline compression in India, which would advantage pre-qualified domestic assembly partners over import-dependent competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Partnership | India's PLI scheme incentives reduce import dependency for directed-energy system procurement. |
| Certification Pre-Qualification | METI electromagnetic pulse device standards create certified supplier lists advantaging component manufacturers. |
| Tropical Environment Adaptation | Modular system designs addressing 80% humidity degradation expand addressable market in Southeast Asia. |
| API-Compatible Platform Integration | Body-worn ecosystem consolidation in Australian state police forces displaces annual competitive tenders. |
| Synthetic Capsaicin Reformulation | MFDS toxicity threshold compression forces irritant payload innovation toward compliant concentration bands. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with procurement directors at national police agencies, defense ministry acquisition officers, and laser platform engineering leads; alongside secondary validation through customs import records, BIS certification registries, and METI industrial standard filings. Primary fieldwork encompassed discussions with lithium-polymer cell manufacturers, rare earth element traders, and riot control equipment distributors across India, Australia, Japan, and Vietnam. Secondary sources included trade data from India's DGFT, Australian TGA toxicity classification determinations, and South Korean MFDS formulation guidelines. Bottom-up unit shipment estimates triangulated against top-down defense budget allocation analysis.
Forecast inputs considered technology adoption curves for directed-energy systems, regulatory timeline compression effects, and procurement cycle phasing across the analysis window. Segmentation dimensions modeled encompass product type, application context, end-user category, and technology maturity tier alongside regional regulatory cluster differentiation. CAGRs derived from logistic diffusion curves fitted to historical procurement data and projected replacement rates for legacy chemical-delivery systems. Industry-specific inputs incorporated lithium-polymer energy density improvement trajectories and semiconductor laser diode reliability maturation curves.
Stress conditions across rare earth element price volatility, BIS certification timeline extension, and tropical humidity degradation thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PLI scheme incentive continuity and METI standard stability. Material shifts in Chinese export quota administration or MFDS toxicity threshold recalibration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
National Security
Homeland Security Market
National Security
Radiological and Nuclear Security Market
National Security
US Bulletproof Glass Market
National Security
Service Handgun Market
National Security
Asia-Pacific Border Security Market
National Security
Research Department Explosive (RDX) Market
National Security
Global Security Assessment Market
National Security
Europe Non-Lethal Weapons Market
National Security
Chemical, Biological, Radiological and Nuclear (CBRN) Security Market
National Security
Saudi Arabia Manned Security Market
National Security
Global Non Lethal Weapons Market
National Security
North America Non Lethal Weapons Market