
 Asia-Pacific Border Security Market | 2026-2036
Asia-Pacific Border Security Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Border Security Market Outlook
Defense electronics manufacturing across South Korea and Japan is shifting toward sovereign production of thermal cores and encrypted datalinks. BAE Systems leverages its Adelaide-based integration facility to anchor naval surveillance programs across the AUKUS corridor. Tata Advanced Systems Limited competes through in-house production of unmanned aerial platforms configured for Himalayan border operations. Elbit Systems Ltd. differentiates via its Hermes drone family and persistent ground-surveillance radars deployed across Southeast Asian littorals.
Asia-Pacific border security encompasses integrated detection, identification, and response architectures that fuse electro-optical, radar, and biometric subsystems into unified command networks operating across maritime and terrestrial boundaries. These systems typically process multispectral sensor feeds through edge-computing nodes capable of sub-ten-second target classification, with primary purpose being sovereign territorial integrity against unauthorized cross-border movement, smuggling, and asymmetric threats. Surveillance Systems leads technology spending as coastal nations prioritize over-the-horizon radar and satellite-linked drone patrols, while Command & Control platforms capture expanding margin pools through software-defined integration mandates. Coastal Security and Land Border Protection dominate application demand, reflecting island-chain tensions and unresolved Himalayan delimitations that drive recurring sensor refresh cycles.
India's CEA and Australia's Defence Export Controls shape procurement through domestic content thresholds and technology-transfer requirements that restrict pure foreign supply. Japan's METI coordinates dual-use export licensing for infrared components, while China's GB standards and SAMR certification gates constrain non-indigenous system access. Stakeholders must monitor evolving AUKUS technology-sharing protocols and India's expanding negative-import list for defense electronics, as these frameworks will determine which suppliers retain market access across the region's largest procurement budgets.
Market Dynamics
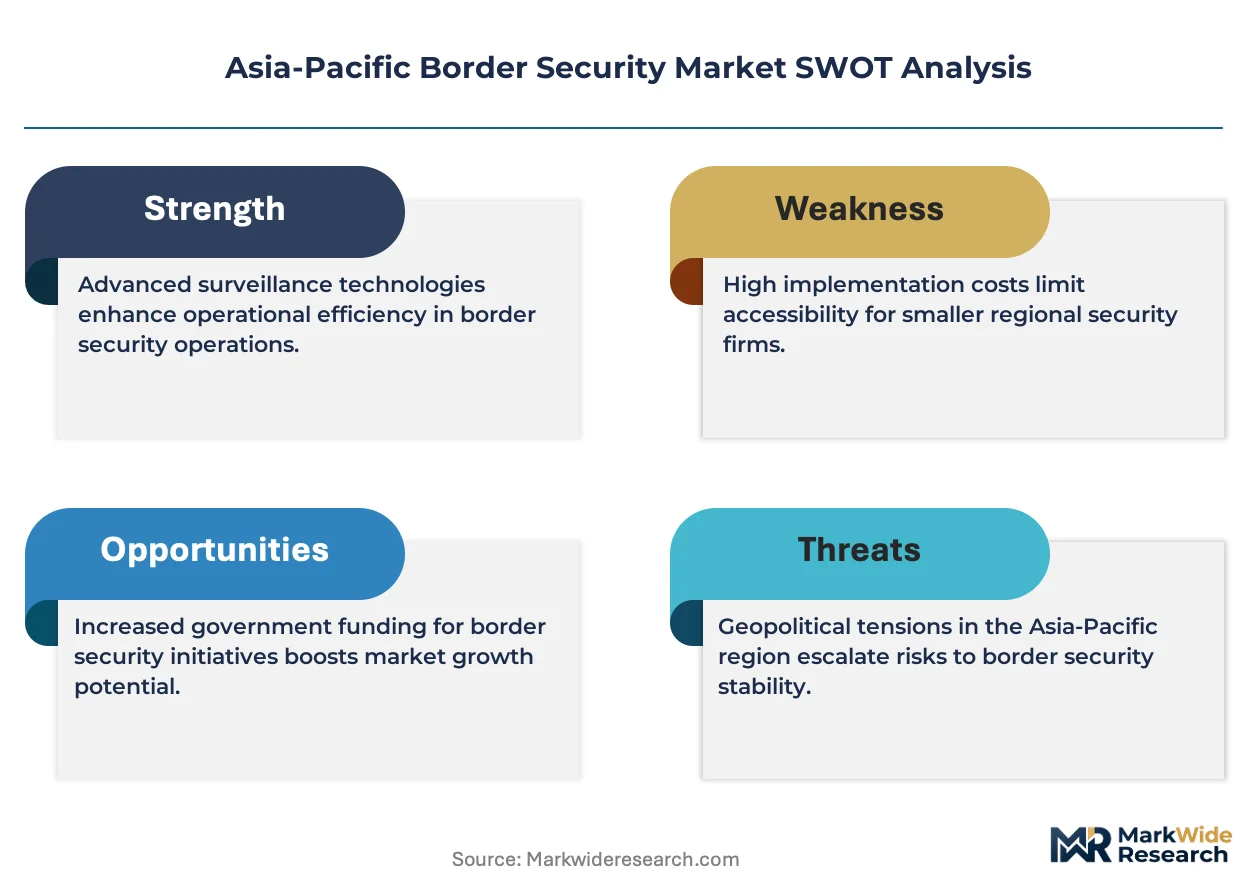
India's PLI scheme for defense electronics is forcing foreign suppliers to establish domestic manufacturing partnerships or surrender access to the region's largest procurement budget, fundamentally restructuring qualification requirements across the Asia-Pacific corridor.
Growth Catalysts
- Coastal Surveillance Modernization:Southeast Asian naval commands are accelerating integrated radar-optical platform procurement to monitor contested littoral zones against illegal fishing and smuggling networks.
- CEA Domestic Content Mandates:India's Central Electricity Authority thresholds require progressive local value-add in defense electronics, compelling joint ventures with Tata Advanced Systems and Bharat Electronics.
- AUKUS Technology Sharing:The trilateral security pact between Australia, the United Kingdom, and the United States is unlocking submarine-derived surveillance capabilities for surface and aerial border applications.
Market Restraints
- Germanium and Gallium Arsenide Concentration:Thermal imaging core production depends on refined rare earth processing concentrated in Chinese supply chains, exposing sensor manufacturers to export restriction vulnerability.
- METI Dual-Use Licensing Friction:Japan's Ministry of Economy, Trade and Industry imposes extended review timelines on infrared component exports, delaying Southeast Asian procurement cycles by 6-12 months.
- Encrypted Datalink Interoperability:Proprietary military communication protocols prevent seamless integration between national border security networks, fragmenting regional cooperative surveillance architectures.
Strategic Opportunities
- Indonesian Archipelago Coverage Gaps:The world's largest island nation maintains minimal radar coverage across eastern provinces, creating demand for satellite-linked drone patrol networks and mobile sensor stations.
- Biometric-Blockchain Convergence:Immutable identity verification for cross-border labor mobility is attracting pilot programs linking India's Aadhaar infrastructure with distributed ledger checkpoint systems.
- Australia's Defence Export Controls Reform:Streamlined technology transfer pathways for AUKUS partners are enabling faster qualification of integrated command platforms for regional resale.
Industry Challenges
- Edge-AI Engineering Talent Scarcity:Sub-ten-second target classification algorithms require specialized machine learning practitioners conversant with military-grade encryption standards, a skill set concentrated in Bangalore, Seoul, and Sydney.
- Legacy Radar Integration Complexity:Cold War-era coastal surveillance installations across the Philippines and Thailand resist seamless fusion with modern electro-optical feeds without complete signal processing replacement.
- GB Standards Certification Burden:China's State Administration for Market Regulation imposes mandatory testing protocols on foreign biometric equipment, extending market entry timelines by 18-24 months.
Report Scope
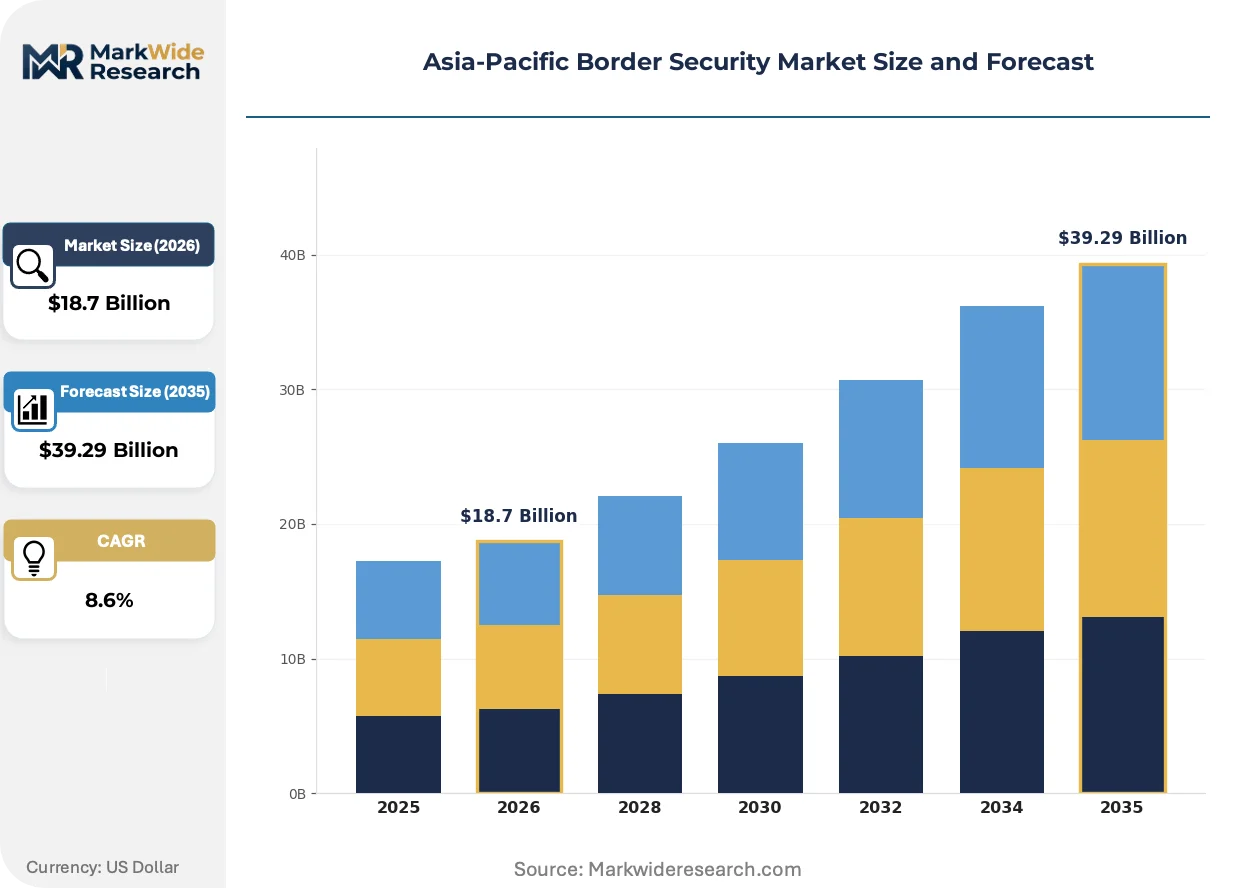
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Border Security Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surveillance Systems, Access Control, Intrusion Detection, Command & Control Application: Coastal Security, Land Border Protection, Airport Security, Critical Infrastructure End User: Government Agencies, Military, Customs & Border Protection, Private Security Firms Service Type: Consulting, System Integration, Maintenance, Training |
| Companies Covered | BAE Systems, Northrop Grumman Corporation, Lockheed Martin Corporation, Teledyne FLIR, Thales Group, Raytheon Technologies Corporation, Bharat Electronics Limited, Tata Advanced Systems Limited, Elbit Systems Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Border Security Market Strategic Shifts
Multispectral sensor fusion is compressing detection-to-response timelines across Himalayan and maritime boundaries, with edge-computing architectures displacing centralized processing for contested terrain operations.
Synthetic aperture radar combined with persistent infrared is rewriting coastal surveillance economics by enabling all-weather, day-night tracking without satellite dependency. Indonesian and Vietnamese maritime enforcement agencies are adopting these fused payloads for archipelago patrol, compressing the operational window for illegal vessel detection from hours to minutes.
India's negative-import list expansion for defense electronics is redirecting procurement toward domestic manufacturing consortia. The Defence Acquisition Procedure amendments require minimum 50% indigenous content for thermal imaging and biometric checkpoint systems, compelling Elbit Systems and Thales to transfer assembly lines to Hyderabad and Pune facilities.
Performance-based maintenance contracts are displacing traditional capital purchase models across Australian and Japanese border security programs. Canberra's Department of Home Affairs now procures coastal radar coverage as an operational availability metric rather than equipment ownership, shifting vendor risk onto system uptime guarantees and compressing supplier margins in exchange for decade-long revenue streams.
Asia-Pacific Border Security Market Segmentation
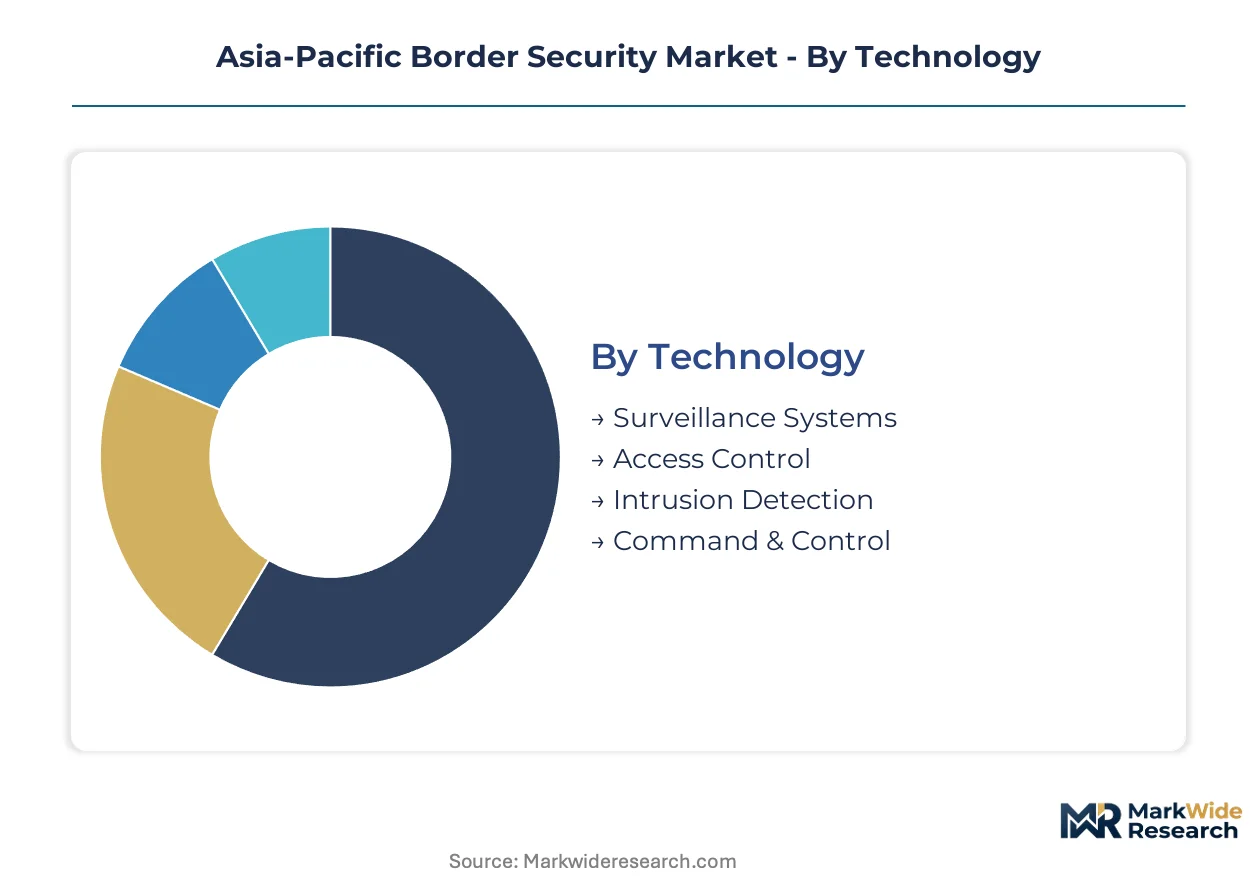
Border security procurement across Asia-Pacific fragments across technology maturity, operational domain, and institutional buyer type. Each segmentation axis reveals distinct qualification barriers and margin structures that determine vendor competitiveness.
Technology:
Electro-optical and radar subsystem integration defines performance tiering across Himalayan and maritime deployments.
- Surveillance Systems:Multispectral sensor platforms fuse thermal cores with synthetic aperture radar for all-weather detection. Indian land border modernization along Pakistan and China frontiers absorbs the largest capital allocation for these integrated perimeter arrays.
- Command & Control:Software-defined integration mandates are expanding margin pools through unified network architectures. Australia's AUKUS-linked capability investments prioritize these platforms for trilateral interoperability standards.
- Access Control:Biometric checkpoint systems process iris and fingerprint templates against centralized databases.
- Intrusion Detection:Seismic and magnetic sensor networks detect tunneling and sub-surface movement.
Mature deployment sits with Surveillance Systems. Newer deployment is concentrated in Command & Control.
Application:
Operational domain determines sensor payload specifications and environmental hardening requirements.
- Coastal Security:Over-the-horizon radar and satellite-linked drone patrols dominate Southeast Asian naval procurement. Indonesian and Vietnamese maritime enforcement agencies compress illegal vessel detection windows through persistent infrared tracking.
- Land Border Protection:Thermal imaging perimeters and biometric checkpoints secure unresolved Himalayan delimitations. India's CEA domestic content mandates reshape supplier qualification for these terrestrial installations.
- Airport Security:Passenger screening and baggage inspection systems integrate with national identity databases.
- Critical Infrastructure:Perimeter protection for energy and transport nodes employs layered detection architectures.
Established procurement patterns favor Coastal Security. Accelerating investment flows into Land Border Protection.
End User:
Institutional buyer type dictates funding authorization cycles and technical specification authority.
- Government Agencies:National interior ministries and home affairs departments control biometric infrastructure budgets. India's Aadhaar-linked checkpoint programs exemplify sovereign identity system deployment.
- Military:Defense forces operate integrated detection networks in contested terrain. Australia's Department of Defence procures coastal coverage through performance-based availability contracts rather than equipment ownership.
- Customs & Border Protection:Revenue collection agencies prioritize trade facilitation alongside security screening.
- Private Security Firms:Commercial operators protect extractive industry installations and logistics corridors.
Long-term contracts concentrate with Government Agencies. Flexible procurement terms expand fastest with Military.
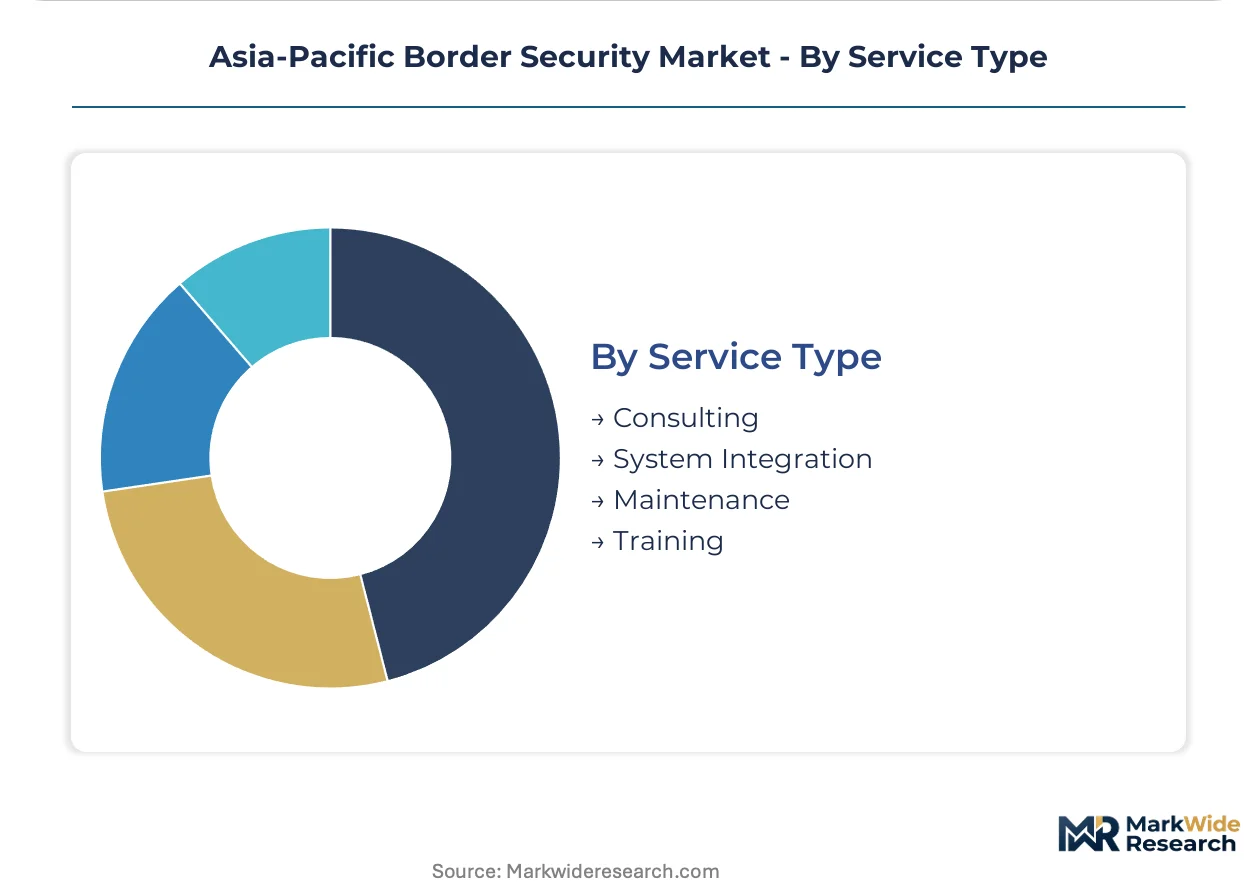
Service Type:
Lifecycle revenue models shift risk allocation between vendor and operator.
- System Integration:Vendor responsibility for fusing legacy radar with modern electro-optical feeds. Philippine and Thai coastal installations require complete signal processing replacement to achieve interoperability.
- Maintenance:Performance-based contracts guarantee operational availability metrics. Japanese border programs now procure uptime guarantees spanning decade-long revenue streams.
- Consulting:Threat assessment and architecture design services precede capital deployment.
- Training:Operator certification for edge-AI target classification systems addresses Bangalore and Seoul talent concentration.
Recurring revenue anchors in Maintenance. Expansion opportunity concentrates in System Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing clusters in Jiangxi and Inner Mongolia supply refined germanium and gallium arsenide that underpin thermal imaging core production across the Asia-Pacific corridor. This feedstock concentration shapes procurement vulnerability and sovereign production mandates from Seoul to Sydney.
India
Thermal imaging perimeters and biometric checkpoints absorb the largest capital allocation along Pakistan and China frontiers. The CEA domestic content mandates under the PLI scheme for defense electronics compel joint ventures with Bharat Electronics and Tata Advanced Systems. Hyderabad and Pune facilities now host transferred assembly lines from foreign suppliers seeking market access.
Australia
Coastal radar coverage procurement has shifted to performance-based availability contracts rather than equipment ownership. The Department of Home Affairs leverages AUKUS-linked capability investments for trilateral interoperability standards. Adelaide-based integration facilities anchor naval surveillance programs across the AUKUS corridor.
Japan
Dual-use export licensing for infrared components imposes extended review timelines that delay Southeast Asian procurement cycles. METI coordinates these controls while domestic manufacturers shift toward sovereign production of encrypted datalinks. Tokyo and Nagoya clusters concentrate edge-AI engineering talent for military-grade encryption standards.
South Korea
Defense electronics manufacturing is shifting toward in-house production of thermal cores and sovereign encrypted datalink capability. Seoul Capital Area firms address the regional scarcity of machine learning practitioners conversant with sub-ten-second target classification requirements. Government funding prioritizes integrated command platform development for Himalayan and maritime deployment.
Indonesia
Minimal radar coverage across eastern provinces creates demand for satellite-linked drone patrol networks and mobile sensor stations. Maritime enforcement agencies adopt synthetic aperture radar fused with persistent infrared for archipelago patrol. Jakarta and Surabaya procurement offices compress illegal vessel detection windows from hours to minutes.
Asia-Pacific Border Security Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue sovereign manufacturing partnerships to satisfy domestic content mandates. The vendor base stratifies across three tiers: integrated platform providers with naval surveillance credentials, component specialists in thermal and electro-optical subsystems, and domestic champions capturing procurement through joint venture structures. Competitive positioning hinges on technology transfer agreements, local assembly qualification, and performance-based maintenance contract execution. M&A activity concentrates on edge-AI software assets and rare earth processing capabilities.
Within the integrated platform tier, BAE Systems and Lockheed Martin Corporation exemplify vendors leveraging AUKUS corridor investments for regional market access. Among domestic champions, Bharat Electronics Limited and Tata Advanced Systems Limited occupy positions strengthened by India's negative-import list expansion and PLI scheme qualification requirements. Elbit Systems Ltd. represents the specialist archetype, with Hermes drone family credentials positioning it for Southeast Asian littoral programs.
| Leading Market Players |
|---|
| BAE Systems |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Teledyne FLIR |
| Thales Group |
| Raytheon Technologies Corporation |
| Bharat Electronics Limited |
| Tata Advanced Systems Limited |
| Elbit Systems Ltd. |
| Others |
Value Chain & Pricing Dynamics
India's CEA domestic content mandates are forcing foreign suppliers to transfer assembly lines to Hyderabad and Pune facilities, compressing margins through local partnership requirements while fragmenting procurement authority across state-level defense electronics consortia. This demand-side restructuring compels vendors to absorb technology transfer costs and recalibrate pricing models around indigenous value-add thresholds rather than pure equipment premiums.
Pricing Analysis
Performance-based maintenance contracts bundle decade-long operational availability guarantees with initial platform deployment, unbundling traditional capital purchase economics into subscription-like service structures. Three-tier pricing structure across premium, standard, and economy levels separates AUKUS-certified command platforms from modular sensor packages and basic perimeter arrays. Cost compression in standard-tier thermal imaging cores is intensifying because India's PLI scheme redirects procurement toward domestic manufacturing consortia. Military buyers exhibit lowest price sensitivity due to sovereignty requirements, while customs agencies prioritize trade facilitation over detection performance.
Supply Chain Analysis
Skilled machine learning practitioners conversant with military-grade encryption standards concentrate in Bangalore, Seoul, and Sydney, constraining edge-AI algorithm development capacity across the region. Rare earth processing clusters in Jiangxi and Inner Mongolia feed germanium and gallium arsenide refinement for thermal imaging cores, while Adelaide and Tokyo house naval surveillance integration facilities. Single-source vulnerability sits with Chinese feedstock concentration for infrared sensor substrates. Distribution runs through defense ministry procurement offices and state-owned electronics consortia rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors capable of satisfying domestic content mandates, with India's negative-import list expansion and Australia's performance-based contracting forcing pure foreign suppliers into joint venture structures or exit.
For Market Incumbents: Deepen sovereign manufacturing partnerships in Hyderabad and Pune to retain access to India's defense procurement budget, while securing AUKUS technology-sharing protocols for trilateral interoperability qualification. Transfer thermal core assembly lines to offset PLI scheme compliance costs. Invest in edge-AI engineering talent acquisition across Bangalore and Seoul clusters to defend algorithm development capabilities against emerging domestic champions. For New Entrants and Emerging Players: System integration specialists offer the most penetrable channel for Indonesian archipelago coverage gaps, where minimal eastern province radar coverage creates demand for satellite-linked drone patrol networks. Target maritime enforcement agencies in Vietnam and the Philippines with synthetic aperture radar-persistent infrared fused payloads. Partner with local defense electronics consortia for GB standards certification navigation and joint venture qualification. For Investors and Strategic Acquirers: The window for entry favors edge-AI software assets and rare earth processing capabilities before domestic content mandates fully mature. Long-term viability hinges on technology transfer agreements and local assembly qualification across the analysis window. Watch AUKUS protocol expansion into surface surveillance applications as the inflection signal for integrated platform provider valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Partnership | CEA mandates in India require joint ventures with Bharat Electronics for market access retention. |
| Edge-AI Talent Acquisition | Bangalore and Seoul engineering clusters enable sub-ten-second target classification algorithm development. |
| AUKUS Technology Transfer | Adelaide-based integration facilities anchor naval surveillance programs for trilateral interoperability. |
| Performance-Based Contracting | Australian Department of Home Affairs procures coastal radar coverage through operational availability metrics. |
| Rare Earth Processing Investment | Jiangxi and Inner Mongolia feedstock concentration creates vulnerability for thermal imaging core production. |
Study Parameters
Multi-period observation of procurement authorization cycles, technology transfer agreements, and domestic content mandate implementation anchored the trend analysis, supplemented by interviews with defense ministry procurement officers, naval surveillance program directors, border security system integrators, and rare earth processing facility managers. Secondary validation drew from customs trade data, CEA regulatory filings, AUKUS partnership disclosures, and METI dual-use licensing records. Bottom-up project pipeline assessment triangulated against top-down defense budget allocation analysis.
Input-output matrices mapped sensor platform deployment volumes to sovereign manufacturing capacity constraints across the projection horizon. Segmentation dimensions modeled include surveillance system type, operational domain, institutional buyer category, and service lifecycle structure. CAGRs were derived through exponential smoothing of authorized procurement trajectories, incorporating PLI scheme qualification timelines and negative-import list expansion schedules as scenario variables.
Caveats apply where AUKUS technology-sharing protocol scope revisions or Indian PLI scheme threshold adjustments could materially shift the outlook for foreign supplier market access. Material deviation in METI dual-use licensing timelines or Chinese rare earth export restriction enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
National Security
Research Department Explosive (RDX) Market
National Security
Service Handgun Market
National Security
Chemical, Biological, Radiological and Nuclear (CBRN) Security Market
National Security
Asia-Pacific Non-Lethal Weapons Market
National Security
Homeland Security Market
National Security
Europe Non-Lethal Weapons Market
National Security
US Bulletproof Glass Market
National Security
Global Security Assessment Market
National Security
Saudi Arabia Manned Security Market
National Security
Global Non Lethal Weapons Market
National Security
Radiological and Nuclear Security Market
National Security
North America Non Lethal Weapons Market