
 Industrial Personal Protective Equipment Market | 2026-2036
Industrial Personal Protective Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Personal Protective Equipment Market Insights
OSHA's updated permissible exposure limits is decoupling legacy product lines from compliant portfolios, forcing manufacturers to recertify entire ranges. 3M leverages its filtration science heritage to sustain dominance in respiratory protection. Honeywell International anchors its position through integrated software-hardware safety platforms. MSA Safety differentiates via connected gas detection systems that feed real-time analytics to plant control rooms.
Industrial personal protective equipment encompasses engineered garments, respiratory apparatus, head protection, and extremity guards designed to shield workers from mechanical, chemical, thermal, and biological hazards, typically constructed from aramid fibers, nitrile blends, polycarbonate, or thermoplastic elastomers meeting ANSI Z89.1 or EN 388 thresholds. Helmets and safety glasses constitute mature, high-volume categories where margin compression persists, while smart PPE with embedded biometric monitoring commands premium positioning. Gloves and footwear represent the fastest-expanding product segments as chemical handling protocols tighten across manufacturing and oil & gas applications. The construction and chemical end-use verticals generate disproportionate value owing to severity-rated product requirements and shorter replacement cycles.
OSHA, EU OSHA, and China's SAMR collectively enforce diverging certification regimes that fragment product development roadmaps and inflate compliance overhead. REACH chemical restrictions and the EU PPE Regulation reshape material sourcing decisions, compelling reformulation of coatings and elastomer compounds. Stakeholders must monitor regulatory harmonization negotiations between North American and European standard-setting bodies, as alignment or divergence will determine whether regional product variants proliferate or consolidate.
Market Dynamics
OSHA's tightening permissible exposure limits for respirable crystalline silica and chemical vapors are forcing wholesale portfolio recertification, compressing product lifecycles while elevating R&D burn rates across the protective equipment sector.
Growth Catalysts
- Respiratory Mandates:OSHA's updated silica exposure standard compels construction and foundry operators to upgrade from disposable to powered air-purifying respirators, expanding addressable hardware markets.
- Aramid Fiber Advances:Next-generation meta-aramid blends deliver 40% weight reduction in cut-resistant gloves without sacrificing EN 388 Level 5 ratings, penetrating chemical handling and glass manufacturing applications.
- German Industrial Liability:Germany's strict employer liability framework and Berufsgenossenschaft enforcement drive premium PPE replacement cycles shorter than European averages.
Market Restraints
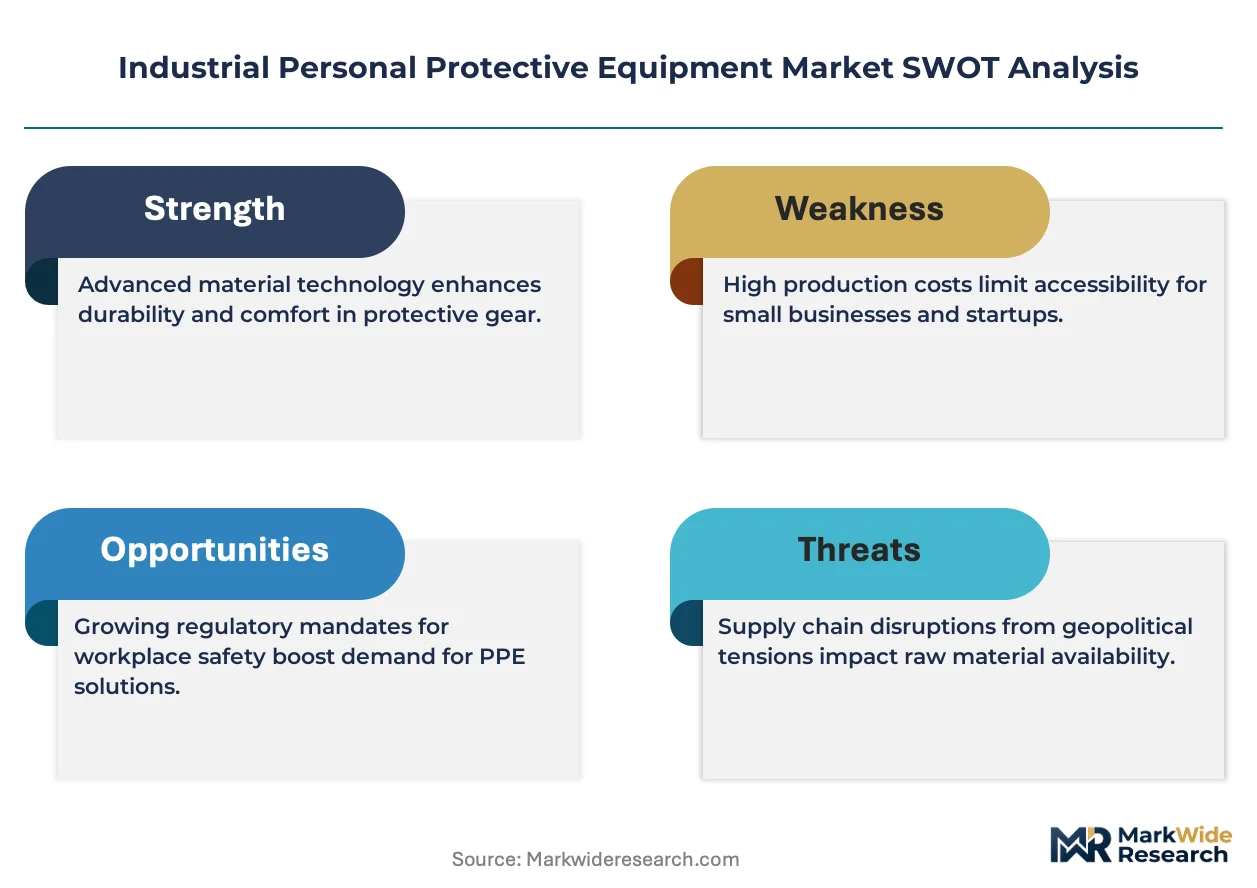
- Petrochemical Input Volatility:Nitrile butadiene rubber and polycarbonate resin prices fluctuate with crude oil indices, compressing margin predictability for glove and faceshield manufacturers.
- Filter Media Concentration:Electrospun nanofiber production concentrates in South Korea and Japan, creating single-source vulnerability for respiratory cartridge supply chains.
- REACH Chemical Restrictions:ECHA's expanding Substances of Very High Concern list forces reformulation of solvent-based glove coatings, extending product development timelines by 18-24 months.
Strategic Opportunities
- India Manufacturing Expansion:India's PLI scheme for technical textiles and BIS certification alignment with ISO standards position the country as an alternative production base for export-grade protective footwear.
- Wearable Convergence:Integration of biometric sensors with existing hard hat and vest form factors creates subscription revenue streams through fatigue monitoring and heat stress alerting.
- SAMR Accelerated Pathways:China's streamlined Class II PPE registration process for smart safety equipment reduces time-to-market for sensor-integrated products versus traditional mechanical categories.
Industry Challenges
- Certification Backlogs:EU Notified Body capacity constraints under the PPE Regulation delay CE marking for new respiratory products, freezing commercial launch schedules.
- Legacy System Integration:Connected gas detection systems require API compatibility with decades-old distributed control systems in petrochemical plants, complicating deployment.
- Specialized Field Service:Smart PPE maintenance demands technicians trained in both mechanical repair and IoT diagnostics, a skill combination scarce in industrial distributor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Personal Protective Equipment Market |
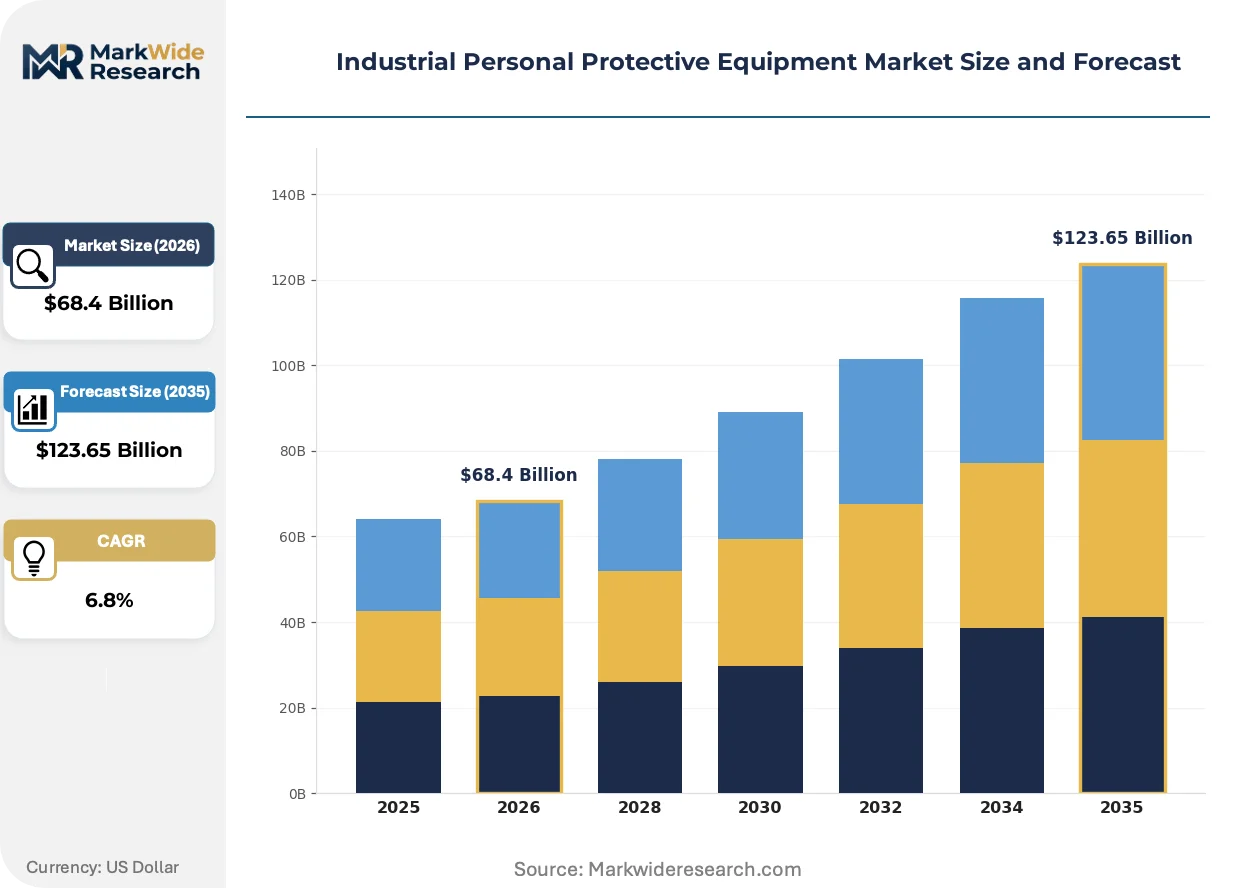
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmets, Gloves, Footwear, Safety Glasses Application: Construction, Manufacturing, Oil & Gas, Chemical End User: Corporations, Government, Contractors, Industrial Workers Distribution Channel: Online, Retail Stores, Direct Sales, Distributors |
| Companies Covered | 3M, Honeywell International, DuPont de Nemours, MSA Safety, Ansell, Lakeland Industries, Kimberly-Clark, Radians, Protective Industrial Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Personal Protective Equipment Market Trends and Innovations
Embedded sensor architectures and predictive safety analytics are redefining how industrial buyers evaluate protective equipment, shifting procurement criteria from passive compliance to active risk reduction capabilities.
Sensor-integrated respiratory protection is electrifying conventional product categories. These systems combine real-time fit testing, filter saturation monitoring, and location tracking into single mask assemblies. Oil & gas operators in the Permian Basin and North Sea installations are piloting deployments at scale. The technology is electrifying vendor-customer relationships by converting transactional hardware sales into ongoing data service contracts with annual recurring revenue structures.
REACH's restriction roadmap for per- and polyfluoroalkyl substances is eliminating durable water-repellent chemistries from protective fabric treatments. Manufacturers must reformulate outer shell coatings using silicone or hydrocarbon alternatives that meet EN 343 waterproofing standards. Outdoor utility workers and offshore wind technicians in Northern Europe face the most immediate gear replacement pressure as legacy inventory phases out.
Consolidated buying through integrated facility management providers is displacing traditional distributor relationships in Fortune 500 manufacturing accounts. These intermediaries bundle PPE procurement with uniform services, safety training, and compliance auditing under multi-year enterprise contracts. The pattern is most pronounced in United States automotive assembly and aerospace clusters where procurement centralization has advanced furthest.
Industrial Personal Protective Equipment Market Segmentation
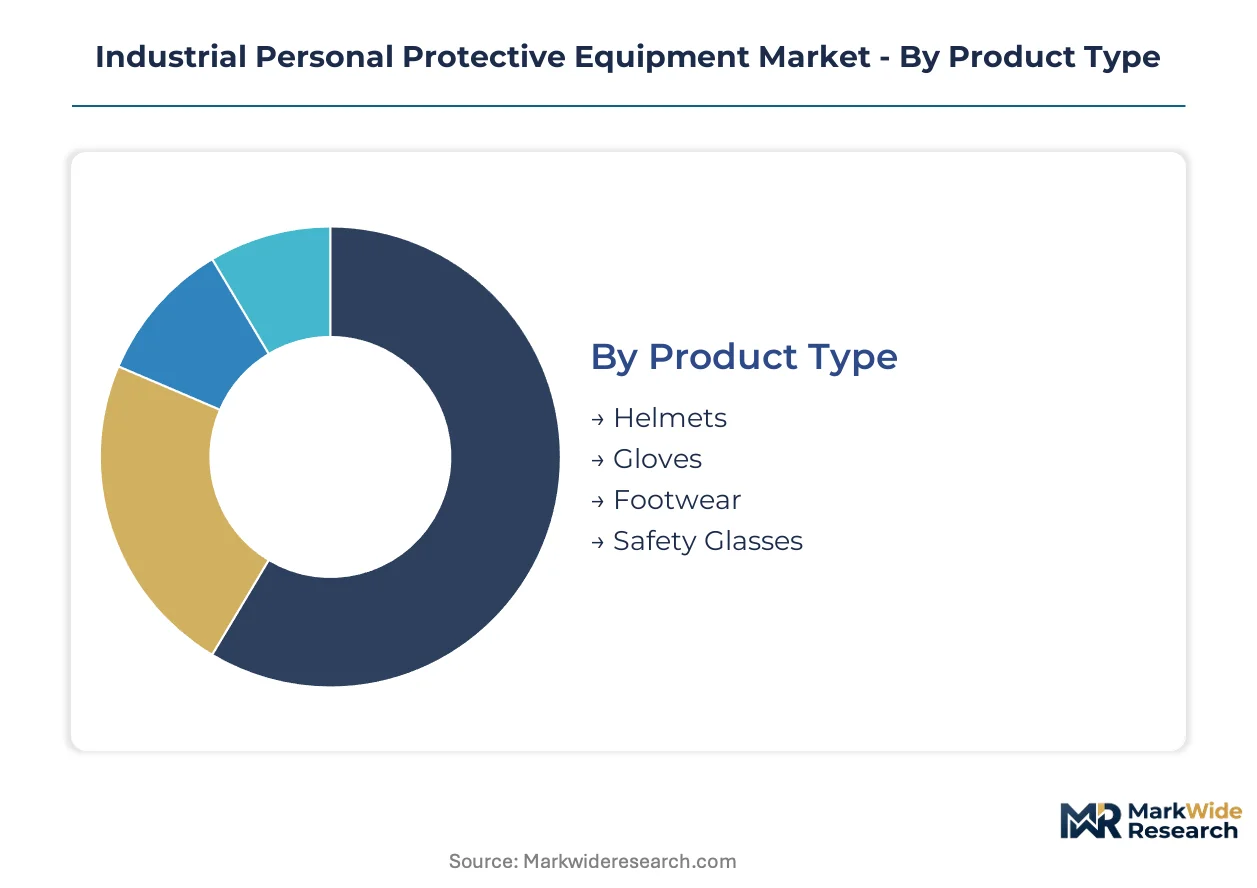
Segmentation in industrial PPE reveals how procurement patterns diverge between compliance-driven bulk purchasing and premium specification buying. Product architecture, end-use hazard severity, and channel economics each reshape margin structures and competitive positioning across distinct buyer clusters.
Product Type:
Standalone protective items dominate high-volume procurement, while integrated multi-hazard systems command specification engineering investment and longer sales cycles.
- Helmets:Injection-molded ABS or HDPE shells meeting ANSI Z89.1 Type I/II classifications form the baseline for head protection. Demand concentrates in United States construction where OSHA's updated fall protection enforcement drives replacement of legacy suspension systems. MSA Safety and Honeywell anchor this segment through distributor relationships with national builders.
- Gloves:Engineered from nitrile blends, aramid fibers, or leather composites with EN 388 or ANSI/ISEA 105 cut ratings. Chemical handling protocols in German manufacturing and United States oil refining are accelerating shift from cotton canvas to chemical-resistant nitrile and neoprene laminates.
- Footwear:Steel or composite toe caps with ASTM F2413 electrical hazard ratings. India's technical textile PLI scheme is drawing production investment for export-grade safety boots serving Middle East and Southeast Asian markets.
- Safety Glasses:Polycarbonate lenses with anti-fog and scratch-resistant coatings. Mature category with margin compression; differentiation shifts to prescription integration and blue-light filtering for indoor manufacturing environments.
Helmets lead volumes today; gloves are gaining share fastest through chemical handling mandate expansion.
Application:
Hazard severity and regulatory inspection frequency determine whether buyers prioritize cost minimization or performance premiumization across verticals.
- Construction:Fall protection and high-visibility apparel dominate procurement. United States residential and commercial building activity drives consistent demand for hard hats, harnesses, and steel-toe boots through integrated facility management contracts.
- Manufacturing:Cut-resistant gloves and respiratory protection anchor spend. German automotive assembly plants enforce shorter replacement cycles than European averages through Berufsgenossenschaft liability frameworks.
- Oil & Gas:Flame-resistant clothing and H2S detection-integrated respiratory systems command premium positioning. Permian Basin operators in Texas and North Sea installations pilot sensor-integrated PPE at scale.
- Chemical:Full-face respirators and chemical-resistant suits face REACH-driven material reformulation. ECHA's expanding SVHC list is forcing 18-24 month development timelines for solvent-based glove coating alternatives.
Construction generates highest absolute spend; oil & gas shows steepest expansion trajectory through connected safety platform adoption.
End User:
Procurement centralization and liability exposure create diverging buyer behaviors between consolidated enterprise accounts and fragmented contractor bases.
- Corporations:Fortune 500 manufacturers bundle PPE with uniform services and compliance auditing under multi-year enterprise contracts. United States automotive and aerospace clusters show most advanced procurement centralization.
- Government:Federal and state agencies mandate domestic sourcing preferences and certified small business participation. United States General Services Administration schedules drive standardized specification adoption.
- Contractors:Project-based purchasing with price sensitivity and rapid fulfillment requirements. Distributor branch networks compete on same-day availability for construction site delivery.
- Industrial Workers:Individual replacement purchases for worn or damaged items. Online channels capture growing share through subscription replenishment models for disposable respirators and gloves.
Corporations dominate contract value; contractors represent highest transaction velocity.
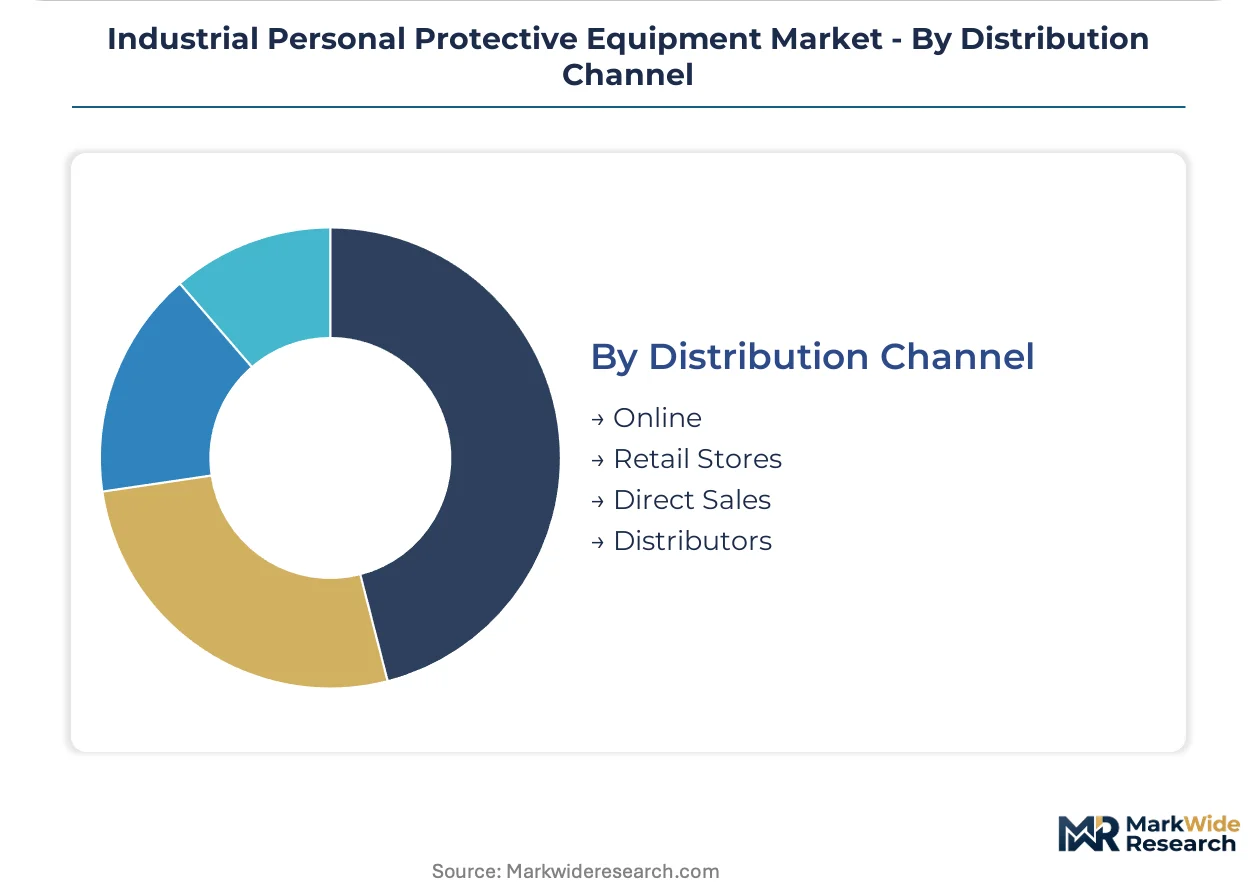
Distribution Channel:
Channel selection tracks buyer sophistication, with integrated service bundling displacing transactional product sales in mature markets.
- Online:E-commerce platforms capture individual worker and small contractor procurement through subscription models and rapid replenishment. Amazon Business and specialized safety distributors compete on search visibility and technical specification depth.
- Retail Stores:Big-box hardware chains serve residential construction and DIY segments with limited professional-grade assortment. United States Home Depot and Lowe's locations stock entry-level hard hats and safety glasses.
- Direct Sales:Manufacturer field forces engage large corporate accounts with specification engineering and custom fitting services. 3M and Honeywell deploy dedicated safety consultants to chemical and oil & gas majors.
- Distributors:W.W. Grainger and regional independents anchor commercial construction and manufacturing supply through local inventory and same-day delivery. Smart PPE maintenance demands are straining technician training capabilities in these networks.
Distributors retain largest volume share; direct sales is climbing the fastest through enterprise platform contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled industrial workforces in Germany, the United States, China, and India anchor regional demand patterns for protective equipment. Each geography shapes procurement through distinct liability frameworks and enforcement intensity.
United States
Construction and oil & gas operators drive respiratory and fall protection procurement. OSHA's updated silica exposure standard compels powered air-purifying respirator upgrades across foundries and demolition sites. The Permian Basin in Texas pilots sensor-integrated PPE deployments at scale for H2S monitoring.
Germany
Automotive assembly and chemical processing plants enforce premium replacement cycles. Berufsgenossenschaft liability frameworks and strict employer responsibility laws accelerate glove and footwear turnover. The Ruhr industrial corridor concentrates demand for cut-resistant aramid fiber products in steel and machinery operations.
China
Manufacturing scale and infrastructure investment sustain volume demand for baseline protective items. SAMR's streamlined Class II registration for smart safety equipment accelerates sensor-integrated product launches. The Yangtze River Delta industrial cluster leads adoption of connected gas detection systems in petrochemical plants.
India
Construction sector expansion and chemical manufacturing growth expand addressable markets for helmets and chemical-resistant gloves. The PLI scheme for technical textiles draws production investment for export-grade safety footwear. Gujarat's industrial zones emerge as alternative manufacturing bases serving Middle East procurement.
United Kingdom
Offshore wind and North Sea oil & gas operations command premium flame-resistant and thermal protection specifications. HSE enforcement of PPE at Work Regulations drives fit-testing compliance for respiratory programs. Aberdeen's energy sector cluster tests biometric-integrated hard hats for fatigue monitoring.
Industrial Personal Protective Equipment Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with filtration and safety platform capabilities. Market concentration remains moderate, with respiratory and head protection categories showing tighter oligopoly dynamics than gloves or footwear. Two strategic archetypes dominate: integrated safety platform providers leveraging software-hardware convergence, and specialized fabricators with deep vertical expertise in single hazard categories. Competitive moves center on sensor technology licensing partnerships and backward integration into aramid fiber and filter media production.
Among North American-based safety conglomerates, 3M and Honeywell International occupy positions spanning respiratory, head, and extremity protection through distributor and direct sales channels. MSA Safety exemplifies the connected safety archetype, anchoring real-time gas detection integration with plant control systems. DuPont de Nemours represents material science leverage, supplying aramid and advanced polymer inputs across competitor product lines.
| Leading Market Players |
|---|
| 3M |
| Honeywell International |
| DuPont de Nemours |
| MSA Safety |
| Ansell |
| Lakeland Industries |
| Kimberly-Clark |
| Radians |
| Protective Industrial Products |
| Others |
Pricing and Supply Chain Analysis
Crude oil index volatility cascades through nitrile butadiene rubber and polycarbonate resin costs, compressing margin buffers for glove and faceshield manufacturers while forcing tiered pricing adjustments across premium certified and economy-grade product lines.
Pricing Analysis
The bundled-versus-unbundled service split separates enterprise platform contracts from transactional hardware sales. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and sensor integration depth. Cost compression in economy-grade respiratory cartridges is intensifying because of petrochemical input fluctuations. Contractors exhibit highest price sensitivity through project-based purchasing, while oil & gas operators absorb premium positioning for H2S-integrated systems.
Supply Chain Analysis
Dual-sourcing requirements from Fortune 500 manufacturers mandate multi-supplier qualification for aramid fibers and filter media. Electrospun nanofiber production centers on South Korea and Japan, while nitrile rubber compounding concentrates in Malaysia and Thailand. Single-source vulnerability in respiratory cartridge supply chains rests on geographic concentration of specialty polymer extrusion. Distribution runs through W.W. Grainger and regional independents with local inventory for same-day construction site delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in industrial PPE hinges on sensor-integrated product shifts that convert transactional sales into recurring data service contracts, offsetting raw material volatility through software attach rates.
For Market Incumbents: Deploy backward integration into aramid fiber production to secure supply of cut-resistant glove materials against emerging Asian textile competitors. Anchor distributor relationships with smart PPE maintenance training programs to prevent technician skill scarcity from fragmenting channel control. Lock in multi-year enterprise platform contracts with integrated facility management providers before procurement centralization advances further.
For New Entrants and Emerging Players: Biometric-integrated hard hats for fatigue monitoring represent the most penetrable white-space target, with North Sea oil & gas and German automotive clusters showing pilot-scale adoption readiness. Target India's PLI scheme for technical textiles to establish export-grade safety footwear production serving Middle East procurement. Pursue direct sales to chemical manufacturers with REACH-compliant coating formulations that accelerate product qualification timelines.
For Investors and Strategic Acquirers: Asymmetric upside sits with connected safety platform specialists possessing API compatibility with legacy distributed control systems. Long-term viability favors acquisitions of sensor-embedded respiratory technology developers over commodity glove manufacturers facing margin compression. Watch for SAMR accelerated approval pathways for Class II smart PPE as signal of China market access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Platform Integration | Converts 3M and Honeywell hardware sales into recurring analytics subscriptions with plant control room feeds. |
| Backward Integration into Aramid | DuPont's captive meta-aramid supply secures 40% weight reduction in EN 388 Level 5 gloves without external dependency. |
| REACH-Compliant Coating Reformulation | ECHA's SVHC expansion forces 18-24 month development cycles that favor incumbents with R&D scale. |
| India PLI Manufacturing Footprint | BIS certification alignment with ISO standards positions Gujarat zones for Middle East safety boot export. |
| SAMR Accelerated Registration | Streamlined Class II PPE pathways in China reduce sensor-integrated product time-to-market versus mechanical categories. |
Research Methodology
Direct dialogue with plant safety managers, procurement leads at downstream chemical manufacturers, distributor branch operators, and technical R&D directors in filtration science grounded qualitative insights. Secondary validation drew from OSHA enforcement records, EU Notified Body CE marking databases, SAMR registration filings, and SEC 10-K disclosures from diversified industrial conglomerates. Bottom-up unit economics triangulated against top-down macro industrial production indices across the analysis window.
Segment-level outputs reflect product architecture, end-use hazard severity, and channel economics modeled across the projection horizon. The analytical framework incorporated deployment model, organization size, vertical application, and regional regulatory cluster as segmentation dimensions. CAGRs derived from historical replacement cycle analysis and regulatory mandate timing, with petrochemical input cost curves and certification backlog durations as industry-specific forecast inputs.
The model holds under stable OSHA and EU OSHA enforcement intensity; deviation in REACH restriction timelines or SAMR pathway alterations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Rodent Control Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Snowmobile Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Arc Flash Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Sports Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Hazard and Safety Indicator Control Modules Market