
 Europe Non-Lethal Weapons Market | 2026-2036
Europe Non-Lethal Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Non-Lethal Weapons Market Foresight
The gap between electromagnetic and chemical delivery systems is narrowing as capacitor and aerosol technologies converge on shared performance benchmarks. Rheinmetall AG leverages its defense electronics heritage to dominate pulse-energy subsystems for military end users. FN Herstal sustains its position through specialized launcher platforms that bridge law enforcement and correctional facility requirements. PepperBall Technologies differentiates via chemical payload innovation that extends range thresholds without crossing lethal-force thresholds.
Europe non-lethal weapons encompass devices engineered to incapacitate, repel, or disperse targets while minimizing risk of fatality or permanent injury, typically operating below 14 joules muzzle energy for kinetic projectiles or delivering electrical pulses under 3 milliamps for conducted energy weapons. Their primary commercial purpose centers on enabling controlled escalation in security operations where lethal force exceeds operational or legal authorization. The law enforcement end user segment anchors volume demand as municipal police forces standardize less-lethal options across patrol units, while electromagnetic technology leads R&D allocation due to reproducible output metrics that satisfy judicial review standards. Crowd control applications occupy the largest share of deployed inventory, though riot management procurement is accelerating fastest as urban policing doctrines shift toward area-denial over individual apprehension.
The EU AI Act and CE marking frameworks under the Machinery Directive shape product certification pathways, while national regulators such as Germany's KBA and France's ANSM impose supplementary testing protocols for chemical and electrical modalities. REACH compliance constrains formulation choices for chemical irritants, pushing manufacturers toward biodegradable or inert carrier agents. Stakeholders must monitor how the EU Green Deal's chemical restriction roadmap interacts with operational effectiveness requirements for aerosol and foam-based systems.
Market Dynamics
The European Convention on Human Rights is tightening use-of-force protocols across municipal police forces, forcing procurement officers to document every escalation threshold and pushing manufacturers toward reproducible output metrics that satisfy judicial review standards.
Growth Catalysts
- REACH compliance mandates:Chemical irritant formulators are accelerating biodegradable carrier agent development to preempt regulatory phase-outs of persistent organic compounds.
- Urban policing doctrine shifts:Area-denial strategies for riot management are displacing individual apprehension protocols, expanding inventory requirements for area-effect electromagnetic systems.
- CE marking under Machinery Directive:Standardized certification pathways reduce time-to-market for conducted electrical weapons, enabling faster police force modernization cycles.
Market Restraints
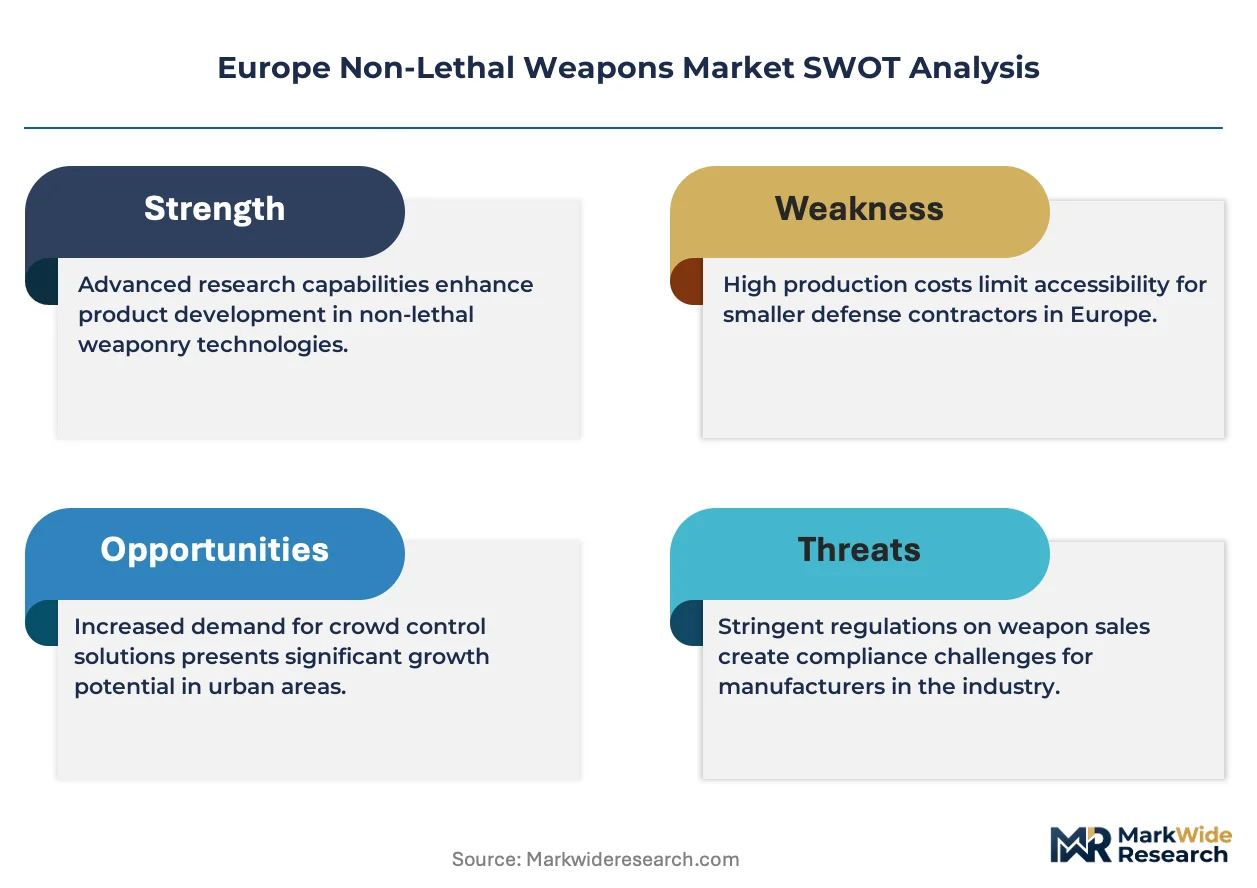
- Capacitor supply concentration:Pulse-energy subsystem manufacturing depends on specialized ceramic dielectric suppliers concentrated in East Asian production clusters.
- ECHA substance restriction timelines:The EU Green Deal's chemical restriction roadmap creates formulation uncertainty for aerosol and foam-based irritant systems.
- Judicial review liability exposure:Reproducible output requirements for electrical modalities expose manufacturers to litigation when field conditions deviate from laboratory benchmarks.
Strategic Opportunities
- Eastern European police modernization:Polish and Romanian municipal forces remain underpenetrated for conducted energy weapon standardization across patrol units.
- Correctional facility integration:Launcher platforms bridging law enforcement and prison security requirements offer specialized procurement channels with longer contract cycles.
- Biodegradable payload innovation:Inert carrier agents for chemical irritants align with France's ANSM supplementary testing protocols while differentiating against legacy formulations.
Industry Challenges
- Electrical engineer talent scarcity:Pulse-energy subsystem design requires specialized expertise in high-voltage capacitor topology that defense electronics firms monopolize.
- Multi-jurisdiction certification complexity:Germany's KBA imposes divergent electrical safety protocols from France's ANSM, fragmenting homologation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Non-Lethal Weapons Market |
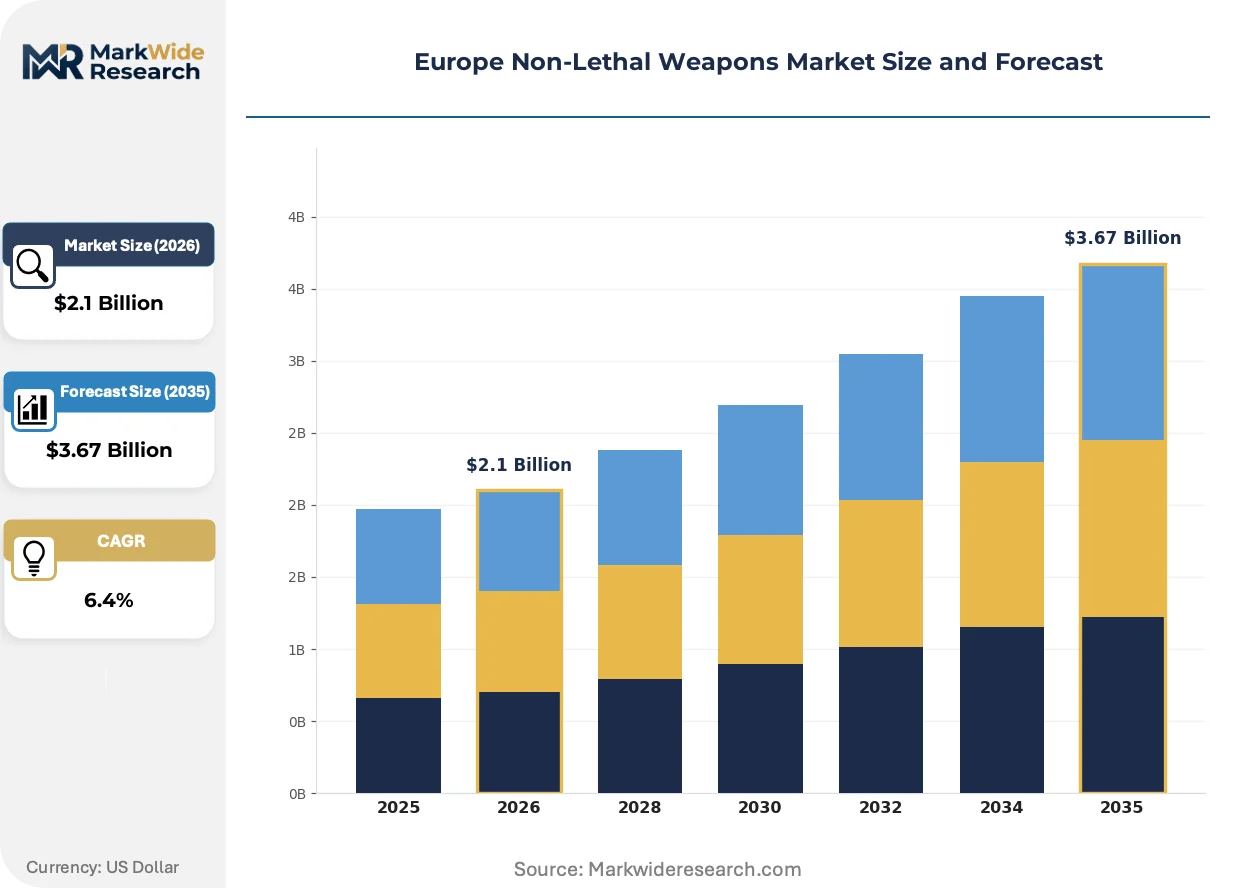
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
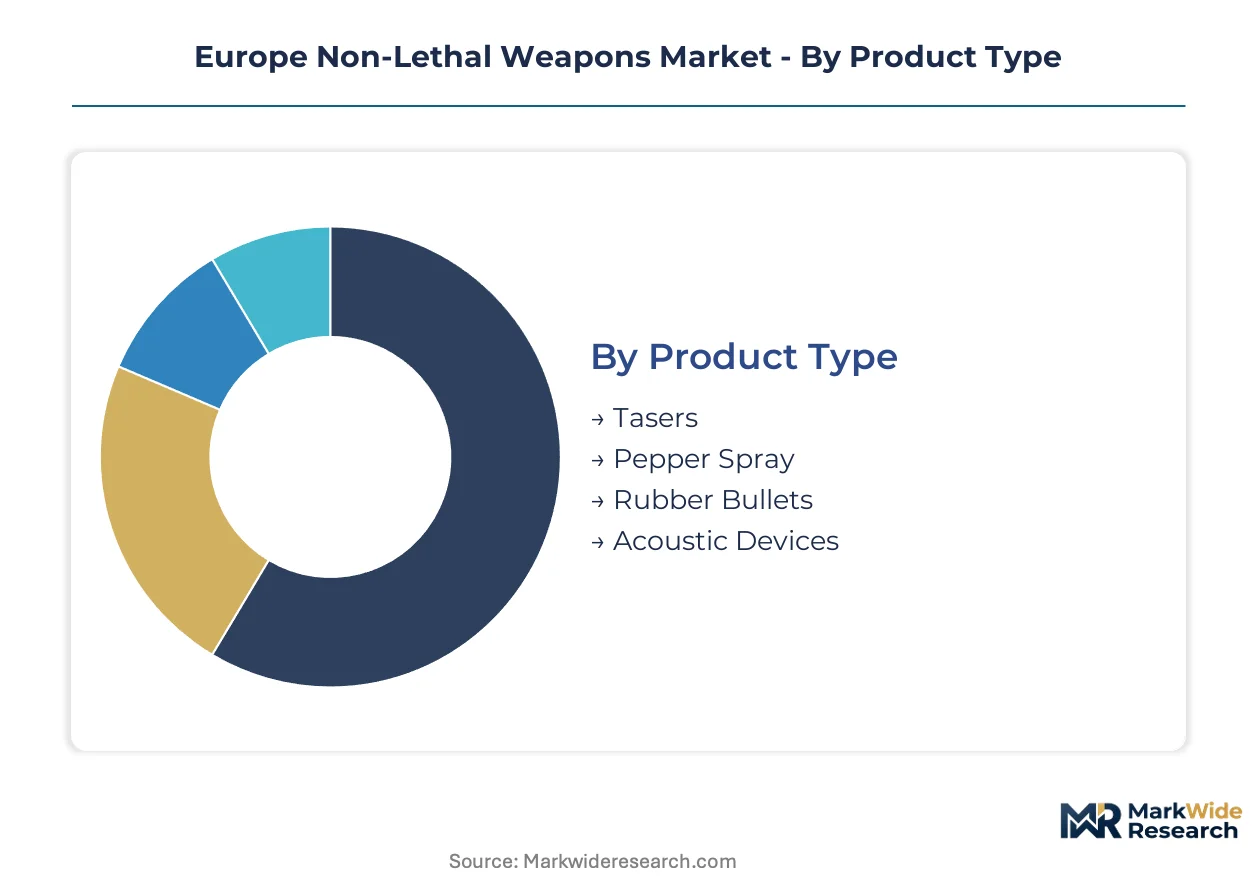
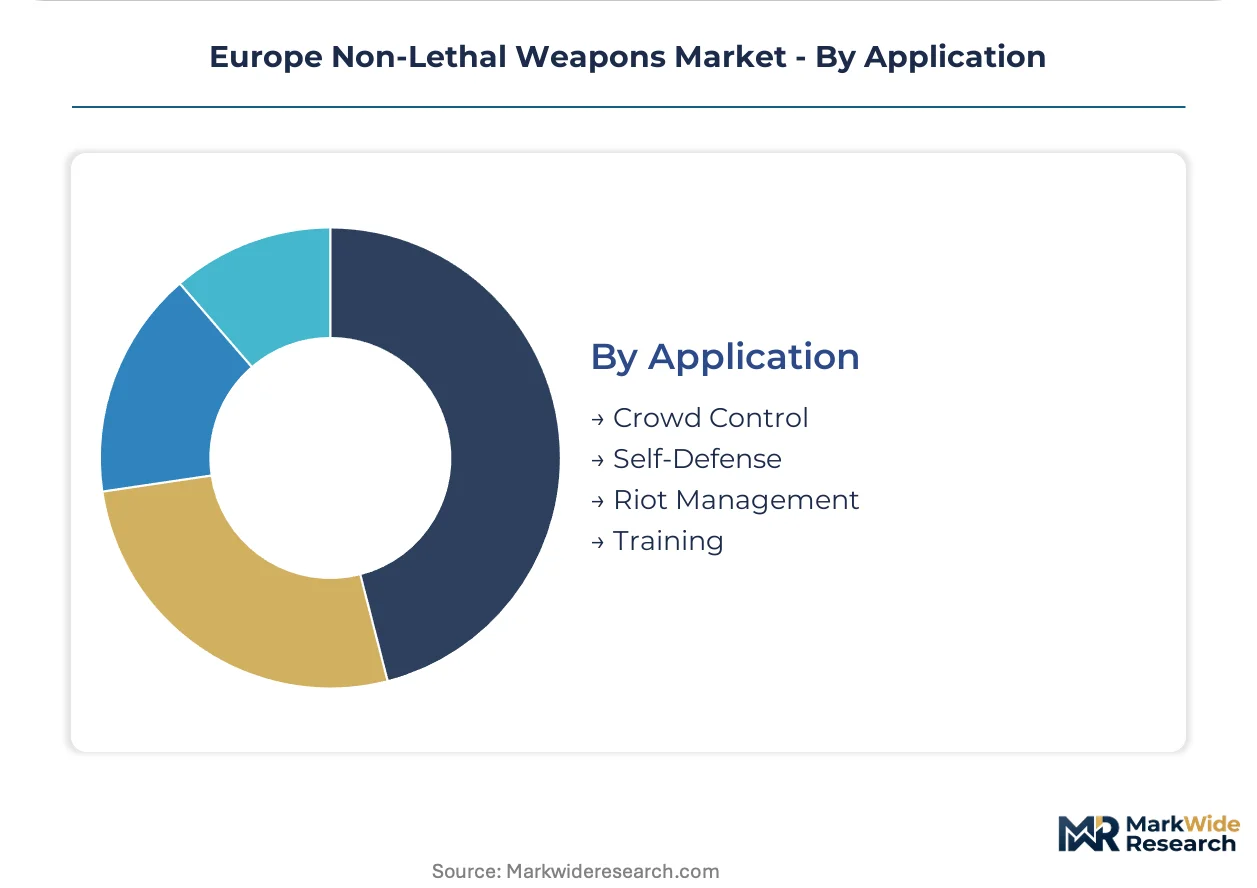
| Segmentation | Product Type: Tasers, Pepper Spray, Rubber Bullets, Acoustic Devices End User: Military, Law Enforcement, Private Security, Correctional Facilities Technology: Electromagnetic, Chemical, Mechanical, Sonic Application: Crowd Control, Self-Defense, Riot Management, Training |
| Companies Covered | Rheinmetall AG, FN Herstal, Combined Systems, Inc., Fiocchi Munizioni SpA, RUAG Group, PepperBall Technologies, Axon Enterprise, Inc., BAE Systems PLC, General Dynamics Ordnance and Tactical Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Non-Lethal Weapons Market Shifts & Advancements
Solid-state capacitor arrays are compressing the performance gap between electromagnetic and chemical delivery systems, while regulatory pressure on persistent irritants accelerates formulation turnover.
Variable-pulse waveform modulation is rendering obsolete fixed-output conducted energy weapons that cannot adapt discharge patterns to target impedance. German federal police procurement specifications now mandate adaptive output for new conducted electrical weapon acquisitions. The technology is rendering obsolete legacy stun-gun architectures that judicial review panels increasingly reject as indiscriminate force application.
REACH authorization requirements for synthetic pyrethroids are constraining irritant formulation choices to natural capsaicinoid derivatives or inert biodegradable carriers. Manufacturers face reformulation costs that compress margins on established aerosol product lines. French riot control procurement is responding fastest, with ANSM now requiring biodegradability documentation for chemical payload registration.
Police procurement officers are consolidating vendor relationships around integrated platform suppliers capable of delivering both electromagnetic and kinetic modalities under unified service contracts. Municipal forces in the United Kingdom are eliminating point-product purchases in favor of multi-modality framework agreements. This concentration is most visible in Metropolitan Police Service standardization programs, where single-source procurement now covers conducted energy, kinetic impact, and chemical irritant systems.
Europe Non-Lethal Weapons Market Segmentation
Segmentation in the Europe non-lethal weapons market reveals how procurement patterns diverge across institutional buyers with distinct operational doctrines and liability frameworks. Police modernization programs in Germany, France, and the United Kingdom concentrate volume in specific product configurations while regulatory pressure from REACH and the EU AI Act reshapes technology roadmaps.
Product Type:
After-sales service intensity varies dramatically across product categories, with conducted electrical weapons demanding firmware updates and calibration protocols that chemical modalities simply do not require.
- Tasers:These conducted electrical weapons deliver pulsed electrical charges through projectile electrodes or direct contact, with capacitor arrays requiring periodic recertification under CE marking frameworks. German federal police procurement now mandates adaptive pulse-waveform modulation, creating recurring service revenue streams for pulse-energy subsystem suppliers concentrated in defense electronics clusters.
- Pepper Spray:Aerosolized capsaicinoid formulations in pressurized canisters operate without electronic components, minimizing maintenance overhead. French ANSM registration requirements for biodegradability documentation are accelerating reformulation cycles among irritant manufacturers serving municipal riot control units.
- Rubber Bullets:Kinetic impact projectiles manufactured from synthetic polymers or rubber composites deliver blunt-force trauma below lethal-force thresholds.
- Acoustic Devices:Directional sound projection systems utilizing phased-array speaker technology for area denial or communication override.
By volume, rubber bullets lead deployed inventory across European police forces. By growth pace, tasers are expanding most quickly amid judicial review demands for reproducible output metrics.
End User:
Procurement authority fragmentation creates distinct commercial pathways, with military buyers prioritizing platform integration while municipal police forces emphasize officer safety liability.
- Military:Defense end users specify conducted energy weapons for checkpoint security and base perimeter defense, with Rheinmetall AG supplying pulse-energy subsystems that integrate with broader electronic warfare architectures. German Bundeswehr procurement emphasizes electromagnetic-kinetic multi-modality platforms.
- Law Enforcement:Municipal police forces anchor absolute volume demand, with Metropolitan Police Service framework agreements consolidating single-source procurement across conducted energy, kinetic impact, and chemical irritant systems.
- Private Security:Commercial guarding operations face stricter use-of-force authorization limits than public agencies, constraining permissible modalities.
- Correctional Facilities:Prison security requirements favor launcher platforms with reduced lethality risk in confined environments.
Law enforcement commands the largest installed base. Correctional facilities are climbing the fastest as incarceration facility modernization programs accelerate.
Technology:
Margin profiles diverge sharply between electromagnetic systems with specialized capacitor supply chains and chemical modalities facing REACH-driven formulation turnover.
- Electromagnetic:Pulse-energy subsystems utilizing solid-state capacitor arrays and waveform modulation circuits dominate R&D allocation due to judicial review compatibility. The technology is displacing fixed-output stun-gun architectures that European Court of Human Rights panels increasingly reject.
- Chemical:Aerosol and foam-based irritant systems face ECHA substance restriction timelines that compress margins on established product lines.
- Mechanical:Kinetic impact delivery through compressed air or spring mechanisms offers operational simplicity without electrical complexity.
- Sonic:Acoustic area-denial systems utilizing directional sound projection for crowd dispersal or communication disruption.
Electromagnetic technology leads R&D expenditure. Chemical delivery is gaining share fastest as biodegradable carrier agent innovation satisfies France's ANSM protocols.
Application:
Operational doctrine shifts from individual apprehension toward area-denial strategies are reallocating inventory requirements across application categories.
- Crowd Control:Area-effect systems for dispersal and denial occupy the largest share of deployed inventory, with urban policing doctrines in the United Kingdom and France emphasizing perimeter containment over direct engagement.
- Riot Management:Specialized procurement for sustained civil disorder response is accelerating fastest as area-denial protocols displace individual apprehension frameworks.
- Self-Defense:Personal carry authorization varies dramatically across European jurisdictions, with private purchase markets concentrated where civilian licensing permits chemical irritant possession.
- Training:Inert and reduced-power variants for officer certification programs create recurring replacement demand.
Crowd control dominates current inventory. Riot management shows the steepest expansion trajectory amid doctrine evolution toward area-denial over individual apprehension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal police procurement officers concentrate purchasing authority in Germany, France, and the United Kingdom, while Eastern European forces accelerate modernization programs. National regulators impose divergent testing protocols that fragment vendor certification timelines across jurisdictions.
Germany
Federal police modernization drives conducted energy weapon acquisitions with adaptive pulse-waveform specifications. The KBA imposes supplementary electrical safety protocols beyond baseline CE marking requirements. Defense electronics clusters in Bavaria and Baden-Württemberg host pulse-energy subsystem suppliers serving both law enforcement and Bundeswehr end users.
France
ANSM registration requirements for biodegradability documentation reshape chemical irritant procurement for municipal riot control units. The EU Green Deal's chemical restriction roadmap accelerates carrier agent reformulation cycles. Industrial capacity concentrates in the Île-de-France region, where specialized aerosol manufacturers serve national gendarmerie modernization programs.
United Kingdom
Metropolitan Police Service framework agreements consolidate single-source procurement across electromagnetic, kinetic, and chemical modalities. Judicial review standards under the European Convention on Human Rights mandate reproducible output metrics for electrical weapons. Manufacturing and testing facilities cluster in the Midlands, supporting integrated platform supply to municipal forces nationwide.
Poland
Municipal police forces remain underpenetrated for conducted energy weapon standardization across patrol units. EU accession-era equipment replacement cycles create procurement windows for less-lethal system vendors. Warsaw-based security equipment distributors increasingly serve as intermediaries between Western manufacturers and Eastern European institutional buyers.
Romania
Correctional facility modernization programs generate specialized demand for launcher platforms with reduced lethality risk in confined environments. National procurement regulations align with EU Machinery Directive frameworks while retaining ministry-level approval requirements. Bucharest-Ilfov industrial zones host assembly operations for imported subsystem components.
Europe Non-Lethal Weapons Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Municipal framework agreements favor integrated platform suppliers capable of multi-modality delivery under unified service contracts. Defense electronics heritage and specialized launcher manufacturing represent distinct strategic archetypes. Competitive moves center on capacitor supply chain security and biodegradable formulation differentiation.
Within the defense-electronics tier, Rheinmetall AG exemplifies pulse-energy subsystem integration, while FN Herstal occupies a position bridging law enforcement and correctional facility launcher requirements. Among chemical payload specialists, PepperBall Technologies anchors biodegradable carrier agent innovation. These three entities represent the dominant competitive archetypes: vertically integrated defense contractors, multi-modal platform integrators, and formulation-focused irritant specialists.
| Leading Market Players |
|---|
| Rheinmetall AG |
| FN Herstal |
| Combined Systems, Inc. |
| Fiocchi Munizioni SpA |
| RUAG Group |
| PepperBall Technologies |
| Axon Enterprise, Inc. |
| BAE Systems PLC |
| General Dynamics Ordnance and Tactical Systems |
| Others |
Supply & Pricing Matrix
Capacitor supply concentration in East Asian ceramic dielectric clusters determines both tiered pricing spreads across pulse-energy subsystems and the geographic shape of component sourcing networks serving European integrators. Procurement officers face simultaneous cost escalation from REACH-driven irritant reformulation and tariff exposure on specialized electrical components, compressing margins at standard-tier price points while premium adaptive-waveform systems command service-bundled premiums.
Pricing Analysis
Cost-plus contracts with ceramic dielectric indexation dominate pulse-energy subsystem procurement, locking municipal buyers into pass-through volatility from East Asian capacitor foundries. Price differentiation hinges on CE marking tier and firmware recertification bundling, with adaptive-waveform tasers carrying 40-60% service-contract premiums over fixed-output alternatives. Cost compression in chemical irritants intensifies as ANSM biodegradability documentation requirements accelerate carrier agent turnover. Private security contractors exhibit highest price sensitivity due to stricter use-of-force liability caps, while military end users prioritize platform integration over unit economics.
Supply Chain Analysis
Export-control restrictions on high-voltage capacitor topology limit technology flows from German defense electronics clusters to non-EU assembly operations. Ceramic dielectric supply draws from Japan, South Korea, and Taiwan, with biodegradable carrier agent sourcing anchored in French and Dutch chemical processing facilities. Single-source vulnerability concentrates in specialized pulse-energy engineering talent monopolized by Bavarian defense contractors. Distribution runs through national framework agreements in Germany, France, and the United Kingdom, with Polish distributors increasingly intermediating Eastern European procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive pulse-waveform modulation represents a regulatory-inflected disruption rendering fixed-output architectures obsolete under European Court of Human Rights scrutiny. This technological inflection compresses replacement cycles and consolidates procurement around integrated platform suppliers capable of multi-modality service delivery.
For Market Incumbents: Pre-empt judicial review liability exposure by accelerating firmware-update infrastructure for legacy installed bases before adaptive-waveform mandates spread beyond German federal specifications. Secure captive supply of solid-state capacitor arrays through backward integration into Bavarian defense electronics clusters or long-term offtake agreements with East Asian ceramic dielectric suppliers. Counter margin pressure from REACH reformulation costs by consolidating chemical irritant production around biodegradable carrier agents that satisfy France's ANSM protocols. For New Entrants and Emerging Players: Pursue Eastern European police modernization windows in Poland and Romania where conducted energy weapon penetration remains below Western European benchmarks. Target correctional facility launcher platforms bridging law enforcement and prison security requirements, as these specialized procurement channels offer longer contract cycles and reduced incumbent lock-in. Establish go-to-market positioning through Warsaw-based security equipment distributors serving as intermediaries to municipal forces undergoing EU accession-era equipment replacement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated platform suppliers with multi-modality certification breadth over point-product specialists. Long-term viability across the projection horizon hinges on adaptive-waveform R&D depth and REACH-compliant formulation pipelines. Acquisition targets should demonstrate pulse-energy subsystem design capability or biodegradable irritant carrier agent portfolios. The signal to watch is German KBA adoption of adaptive-output mandates, which would accelerate replacement demand across municipal forces continent-wide.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Waveform Firmware Development | CE marking compliance under Machinery Directive now requires judicial-review-compatible output metrics. |
| Biodegradable Carrier Agent Reformulation | ANSM registration protocols in France mandate documentation that REACH timelines will extend across the EU. |
| Capacitor Supply Security Investment | East Asian ceramic dielectric concentration creates procurement vulnerability for pulse-energy subsystem vendors. |
| Eastern European Distribution Partnership | Polish intermediaries unlock underpenetrated municipal police modernization budgets in Romania and adjacent markets. |
| Multi-Modality Framework Agreement Capture | Metropolitan Police Service procurement consolidation eliminates point-product vendors from UK municipal consideration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal police procurement officers, correctional facility security directors, defense electronics R&D leads, and chemical irritant formulation specialists. Secondary validation drew from CE marking documentation under the Machinery Directive, ECHA substance restriction timelines, ANSM registration protocols, and national procurement disclosures from Germany's KBA and France's interior ministry. Bottom-up unit shipment estimates across conducted energy, kinetic impact, and chemical irritant categories were triangulated against top-down defense and security expenditure allocations.
Calibration against historical procurement cycles and regulatory implementation lags shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, technology modality, and application scenario, with additional granularity on national regulatory cluster divergence. CAGRs were derived from replacement cycle compression tied to adaptive-waveform mandates and formulation turnover driven by REACH authorization requirements. Industry-specific inputs encompassed judicial review case volume trends and municipal police force headcount projections.
Sensitivities concentrate around ECHA substance restriction timeline acceleration and European Court of Human Rights rulings on fixed-output electrical weapons. Forecasts reflect assumptions on procurement authorization continuity and capacitor supply chain stability. Material shifts in EU Green Deal chemical restriction roadmaps or export-control tightening on high-voltage topology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
National Security
US Bulletproof Glass Market
National Security
Asia-Pacific Border Security Market
National Security
Saudi Arabia Manned Security Market
National Security
Global Non Lethal Weapons Market
National Security
North America Non Lethal Weapons Market
National Security
Radiological and Nuclear Security Market
National Security
Asia-Pacific Non-Lethal Weapons Market
National Security
Service Handgun Market
National Security
Research Department Explosive (RDX) Market
National Security
Homeland Security Market
National Security
Global Security Assessment Market
National Security
Chemical, Biological, Radiological and Nuclear (CBRN) Security Market