
 Bot Services Market | 2026-2036
Bot Services Market Size, Share, and Industry Trends Forecast 2026-2036
Bot Services Market Analysis
The pool of certified conversational AI engineers is collapsing, forcing enterprises to rely on platform vendors rather than in-house development. Microsoft Corporation leverages its Azure Bot Service ecosystem to anchor enterprise deployments across healthcare and finance verticals. Google LLC competes through deep NLP research integration into its Dialogflow platform, while Amazon Web Services dominates cloud-based bot infrastructure with Lex and Connect integration.
Bot services encompass software platforms and managed offerings that design, deploy, and operate automated conversational agents capable of natural language understanding, intent classification, and multi-turn dialogue management through API-based architectures. These systems process structured and unstructured inputs to execute tasks ranging from customer inquiry resolution to transactional workflow completion without human intervention. Cloud-based deployment models lead segment value due to elastic scaling and reduced infrastructure overhead, while NLP technology anchors functional differentiation as large language models reshape intent recognition accuracy. Healthcare and finance verticals represent the fastest-growing industry applications as regulated sectors pursue compliant automation of high-volume interactions.
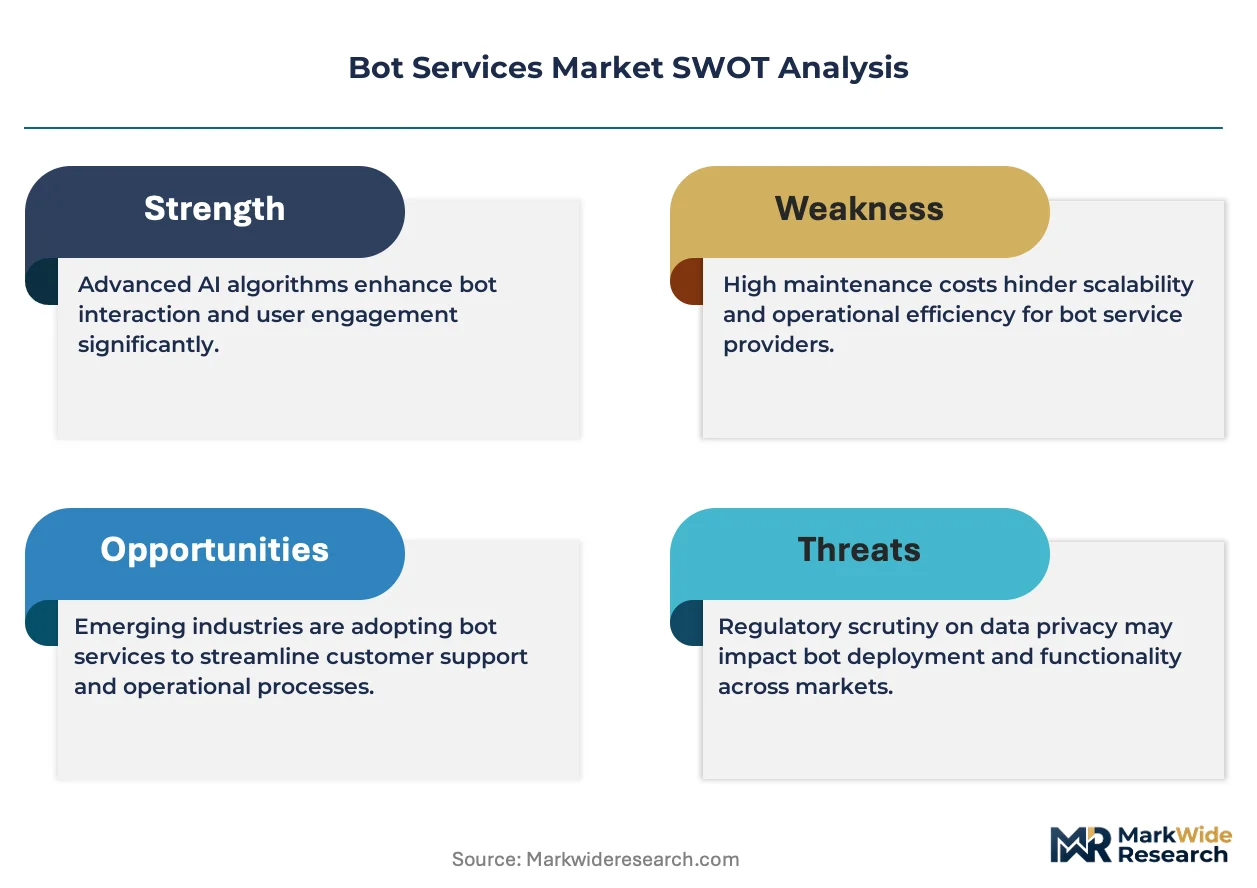
The EU AI Act imposes risk-tiered obligations on bot systems handling biometric inference or credit decisions, while the FDA scrutinizes clinical decision-support bots under software-as-medical-device pathways in the United States. HIPAA constraints shape healthcare bot architectures by mandating audit trails and encryption standards for protected health information exchanges. Stakeholders must monitor evolving algorithmic transparency mandates across jurisdictions to anticipate compliance costs that could reshape platform economics and vendor selection criteria.
Market Dynamics
The collapse of certified conversational AI engineering talent pools is forcing enterprises toward platform vendor dependency, fundamentally restructuring competitive advantage from in-house capability to vendor selection and integration architecture.
Growth Catalysts
- EU AI Act compliance mandates:Risk-tiered obligations for high-stakes bot applications are accelerating enterprise investment in auditable, enterprise-grade platforms over custom builds.
- Healthcare claims automation:HIPAA-compliant bot architectures are reducing administrative overhead in patient intake and prior authorization workflows across US hospital systems.
- Large language model integration:Transformer-based intent recognition is expanding bot accuracy thresholds into complex multi-turn dialogue scenarios previously requiring human handoff.
Market Restraints
- Compute cost volatility:GPU scarcity and cloud inference pricing spikes are compressing margins for high-volume bot deployments.
- Algorithmic audit requirements:The EU AI Act's documentation burdens and FDA software-as-medical-device pathways are extending deployment timelines.
- Human agent substitution limits:Emotional intelligence gaps in conversational AI are restricting deployment in high-empathy service contexts.
Strategic Opportunities
- India's BFSI modernization wave:RBI-mandated digital banking infrastructure is creating demand for vernacular-language bot deployments.
- Voice-to-text convergence:Integration of real-time speech recognition with dialogue management is opening automotive and smart home channels.
- Outcome-based pricing models:Vendors are capturing value through resolution-rate guarantees rather than seat-based subscriptions.
Industry Challenges
- Prompt engineering talent scarcity:The specialized skill set for LLM tuning and context window optimization commands premium compensation.
- Legacy contact center integration:Mainframe-era telephony infrastructure requires expensive middleware layers for bot connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bot Services Market |
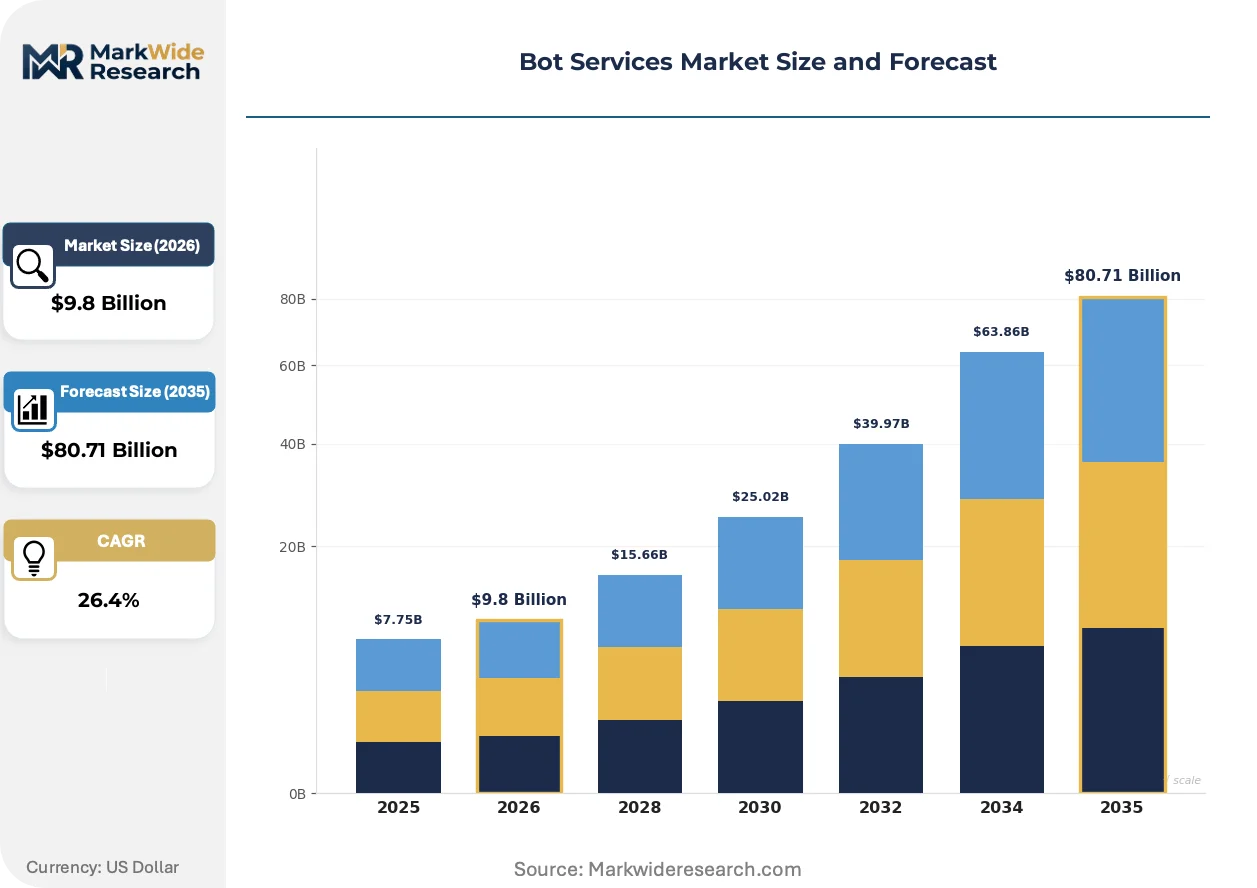
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $80.71 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chatbots, Voice Assistants, Service Bots, Transactional Bots Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS Industry Vertical: Retail, Healthcare, Finance, Telecommunications Technology: Machine Learning, NLP, AI, RPA |
| Companies Covered | Microsoft Corporation, Google LLC, Amazon Web Services, IBM Corporation, Oracle Corporation, SAP SE, Salesforce Inc., Kore.ai, Yellow.ai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bot Services Market Emerging Trajectories
Generative AI architectures are compressing development cycles and redefining performance benchmarks across the bot services value chain, with regulatory frameworks racing to catch up to deployment velocity.
Retrieval-augmented generation is displacing static knowledge bases in enterprise bot deployments. Banking and insurance IT departments are adopting RAG pipelines at accelerated procurement cycles. This architecture is displacing rule-based fallback systems that previously dominated high-stakes customer interactions.
The FDA's software-as-medical-device pathway is tightening oversight of clinical decision-support bots. Developers must now submit algorithmic change control protocols for model updates. Healthcare bot vendors are responding by partitioning diagnostic and administrative functions into separate, independently validated systems.
Enterprise buyers are consolidating vendor relationships around full-stack conversational AI platforms. Point solutions for intent classification or dialogue management are losing procurement cycles to integrated offerings. Fortune 500 technology modernization programs in the United States are driving this consolidation pattern.
Bot Services Market Segmentation
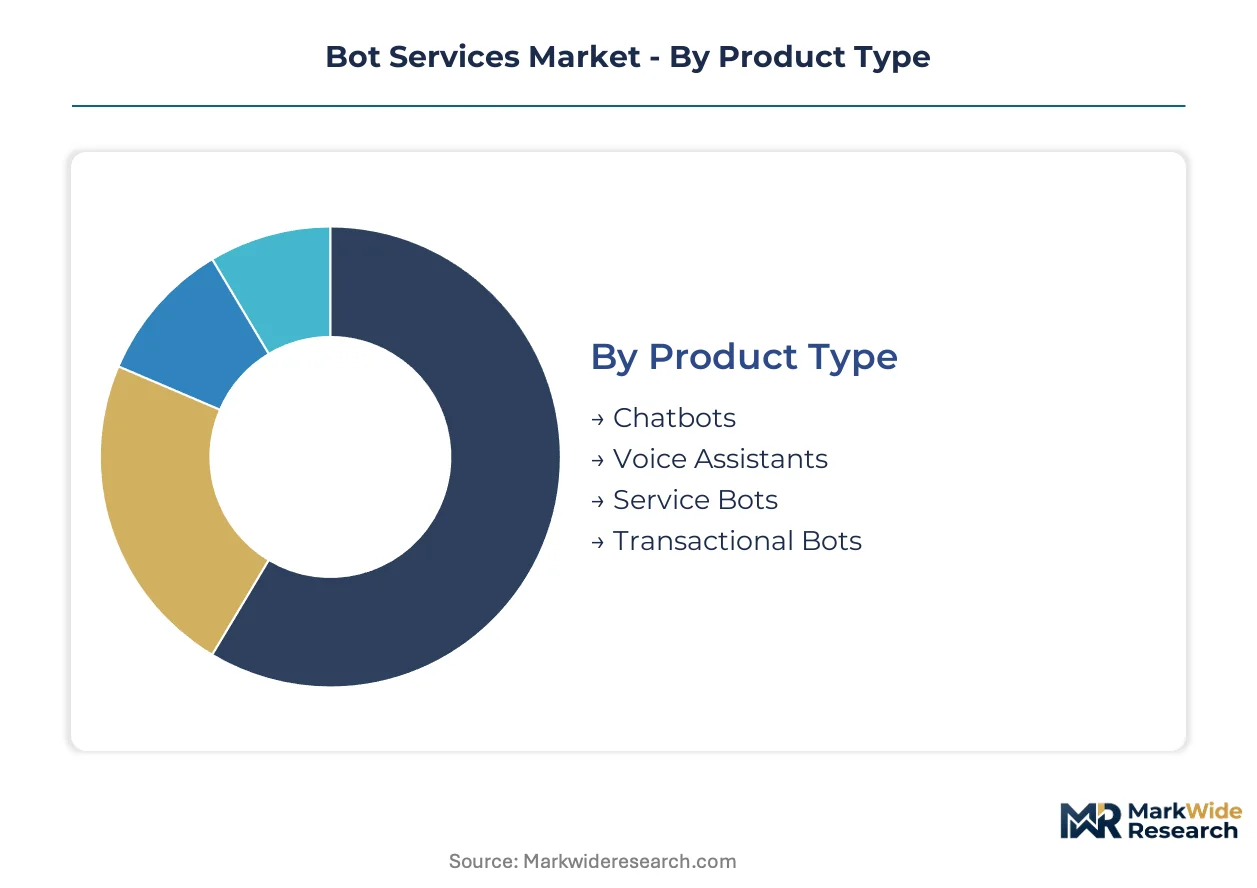
Bot services exhibit divergent growth patterns across deployment architectures and interaction modalities. Understanding segment boundaries clarifies where platform vendors capture margin versus where enterprise IT retains build-versus-buy discretion.
Product Type:
Chatbot deployments concentrate in domestic customer service operations, while voice assistant rollouts increasingly serve export-facing multilingual requirements.
- Chatbots:Text-based conversational interfaces process structured queries through rule-based or retrieval-augmented architectures. Banking IT departments in the United States deploy these for account servicing and password resets, constrained by EU AI Act documentation requirements for credit-adjacent interactions.
- Voice Assistants:Speech-enabled agents integrate acoustic models with dialogue management for hands-free operation. Automotive OEMs in Germany and smart home manufacturers in South Korea drive procurement, though emotional intelligence gaps restrict deployment in high-empathy healthcare contexts.
- Service Bots:Task-automation agents execute backend workflows through API orchestration.
- Transactional Bots:Payment-integrated systems complete purchase journeys without human handoff.
Chatbots command the established base. The steepest expansion runs through voice assistants.
Deployment Model:
Cost tier stratification separates elastic cloud consumption from capital-intensive on-premise installations requiring dedicated infrastructure teams.
- Cloud-Based:Elastic scaling architectures reduce infrastructure overhead through consumption-based pricing. Fortune 500 enterprises in the United States modernizing legacy contact centers favor this model, though GPU scarcity and inference pricing volatility compress margins at high volume.
- On-Premise:Self-managed deployments maintain data sovereignty through localized compute. German financial institutions and French healthcare systems select this architecture to satisfy GDPR and HIPAA-equivalent audit trail mandates.
- Hybrid:Split architectures process sensitive workloads locally while offloading burst demand to cloud.
- SaaS:Fully managed subscriptions abstract infrastructure complexity for mid-market buyers.
Cloud-based deployments command the established base. The steepest expansion runs through hybrid architectures.
Industry Vertical:
Application intensity varies by regulatory exposure and interaction volume, with regulated sectors pursuing compliant automation of high-frequency touchpoints.
- Healthcare:HIPAA-compliant bot architectures automate patient intake and prior authorization workflows. United States hospital systems reduce administrative overhead, while FDA software-as-medical-device pathways tighten oversight of clinical decision-support functions.
- Finance:Risk-tiered EU AI Act obligations accelerate investment in auditable platforms for credit decisions and claims processing. Enterprise IT departments in banking and insurance prioritize vendor selection over in-house development due to collapsing certified engineering talent pools.
- Retail:E-commerce and brick-and-mortar operators deploy for order tracking and returns processing.
- Telecommunications:Carriers automate billing inquiries and service troubleshooting at massive scale.
Finance commands the established base. Healthcare posts the fastest volume gains.
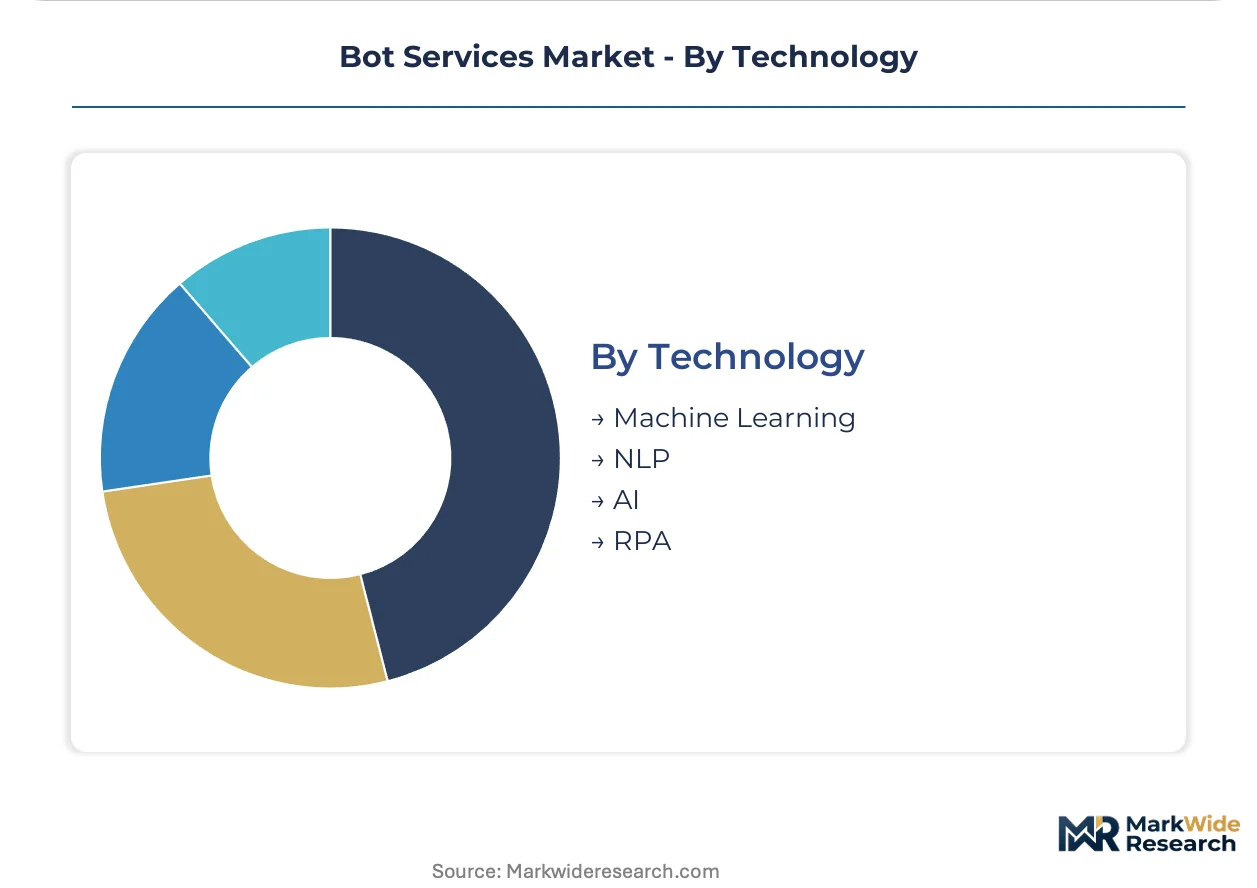
Technology:
Supply concentration clusters around large language model providers, with differentiation shifting from intent classification accuracy to context window optimization capabilities.
- NLP:Natural language processing anchors functional differentiation as transformer-based architectures reshape intent recognition. Banking and insurance procurement cycles favor platforms with deep research integration for complex multi-turn dialogue scenarios.
- Machine Learning:Supervised and reinforcement learning pipelines train intent classifiers on domain-specific corpora. Healthcare bot vendors partition diagnostic and administrative functions into separately validated systems to satisfy algorithmic change control protocols.
- AI:Broad artificial intelligence stacks encompass perception, reasoning, and generation layers.
- RPA:Robotic process automation handles structured backend workflows through UI-level interaction.
NLP commands the established base. Machine learning gains share fastest through retrieval-augmented generation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by jurisdiction. United States enterprises prioritize cloud-native contact center modernization, while European buyers emphasize GDPR-compliant on-premise architectures. Asian markets favor vernacular-language voice assistants for financial inclusion.
United States
Fortune 500 healthcare systems and banks drive demand for HIPAA-compliant patient intake bots and AI Act-ready credit decision platforms. FDA software-as-medical-device pathways tighten oversight of clinical decision-support systems. Hospital clusters in Texas and California deploy prior authorization automation at scale.
Germany
Automotive OEMs and financial institutions procure voice-enabled agents for hands-free manufacturing and GDPR-auditable customer service. The EU AI Act imposes risk-tiered documentation obligations on biometric inference systems. Munich and Frankfurt banking hubs prioritize on-premise deployments for data sovereignty.
India
RBI-mandated digital banking infrastructure fuels vernacular-language bot deployments across tier-2 and tier-3 cities. The central bank's regulatory sandbox enables testing of conversational AI for financial inclusion. Mumbai and Bengaluru fintech clusters modernize legacy core banking with API-orchestrated service bots.
United Kingdom
Insurance carriers and NHS trusts adopt retrieval-augmented generation for claims processing and patient triage. The Information Commissioner's Office enforces algorithmic transparency for automated decision systems. London's financial district concentrates procurement of auditable enterprise-grade platforms.
South Korea
Smart home manufacturers and telecom carriers integrate real-time speech recognition for IoT command interfaces. The Ministry of Science and ICT promotes AI sovereignty through domestic large language model development. Seoul's consumer electronics cluster leads voice-to-text convergence for automotive applications.
Bot Services Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Cloud hyperscalers anchor the upper tier with full-stack conversational AI platforms spanning NLP, dialogue management, and API orchestration. Beneath them, vertical specialists concentrate on HIPAA-compliant healthcare deployments or BFSI-specific vernacular language capabilities. Competitive moves center on enterprise partnership ecosystems and retrieval-augmented generation integration to displace rule-based fallback systems.
Within the integrated platform tier, Microsoft Corporation and Google LLC exemplify the full-stack archetype through Azure Bot Service and Dialogflow ecosystems. Amazon Web Services occupies a distinct position anchoring cloud-native infrastructure with Lex and Connect integration. These three hyperscalers represent the consolidation pattern as Fortune 500 buyers reduce vendor counts and prioritize auditable, enterprise-grade platforms over custom builds.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Amazon Web Services |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| Salesforce Inc. |
| Kore.ai |
| Yellow.ai |
| Others |
Supply Flow & Price Mechanics
Retrieval-augmented generation architectures displacing static knowledge bases simultaneously shift compute demand toward GPU-rich cloud regions and compress pricing premiums previously commanded by rule-based enterprise systems. This substitution dynamic concentrates procurement leverage among hyperscalers while eroding margins for middleware specialists tethered to legacy integration stacks.
Pricing Analysis
Long-term enterprise licensing contracts dominate Fortune 500 deployments, though outcome-based resolution guarantees are displacing seat-based subscriptions in competitive healthcare and finance tenders. Price differentiation hinges on EU AI Act audit-readiness certification and HIPAA-compliant encryption tiers, with cloud-native platforms commanding premiums over on-premise alternatives. Pricing pressure stems from GPU scarcity inflating inference costs at scale, squeezing high-volume deployments. Mid-market buyers exhibit acute price sensitivity, while regulated enterprises prioritize compliance-grade platforms despite cost premiums.
Supply Chain Analysis
The United States anchors large language model development through hyperscaler R&D clusters, while Taiwan and South Korea concentrate advanced semiconductor fabrication for training and inference hardware. Bot service providers draw from NVIDIA GPU allocations, specialized NLP research talent pools, and API-orchestrated cloud infrastructure. Single-source vulnerability in GPU supply chains exposes deployment timelines to foundry capacity constraints. Distribution runs through direct enterprise sales teams and cloud marketplace channels, with systems integrators handling legacy contact center retrofitting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified conversational AI engineers have become the constraining asset, forcing competitive advantage to migrate from in-house development velocity toward vendor selection acumen and integration architecture sophistication.
For Market Incumbents: Fortify platform stickiness through retrieval-augmented generation integration that displaces rule-based fallback systems in banking and insurance deployments. Deepen HIPAA-compliant healthcare certifications and EU AI Act audit-ready documentation to defend against emerging vertical specialists. Prioritize outcome-based pricing pilots with Fortune 500 hospital systems to lock in long-term enterprise relationships before GPU cost volatility stabilizes. For New Entrants and Emerging Players: Lead with vernacular-language voice assistant capabilities targeting India's RBI-mandated digital banking infrastructure across tier-2 and tier-3 cities. The BFSI modernization wave offers the most penetrable entry point, with regulatory sandbox environments enabling validated proof-of-concept deployments. Partner with domestic system integrators possessing established relationships with legacy core banking providers to bypass direct hyperscaler competition. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors full-stack conversational AI platforms with proven FDA software-as-medical-device pathway navigation. Long-term viability centers on vendors capable of partitioning diagnostic and administrative functions into independently validated systems. Watch for inflection signals in EU AI Act enforcement severity, which would accelerate procurement toward auditable enterprise-grade platforms and compress valuation multiples for point-solution specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Retrieval-Augmented Generation Integration | Displaces static knowledge bases in banking claims processing and prior authorization workflows. |
| HIPAA-Compliant Architecture Certification | Unlocks United States hospital system procurement cycles with mandated audit trail capabilities. |
| EU AI Act Audit-Ready Platform Investment | Captures risk-tiered compliance demand from German financial institutions and French healthcare systems. |
| Vernacular Language Voice Assistant Development | Addresses RBI-mandated digital banking infrastructure requirements across India's tier-2 cities. |
| Outcome-Based Pricing Model Pilot | Shifts revenue capture from seat subscriptions to resolution-rate guarantees in Fortune 500 tenders. |
Methodological Framework
A spread of perspectives from enterprise IT procurement officers, conversational AI platform engineers, healthcare compliance directors, and systems integration specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from hyperscaler cloud divisions, FDA software-as-medical-device pathway documentation, and EU AI Act regulatory impact assessments. Bottom-up deployment sizing across chatbot, voice assistant, and service bot categories triangulated with top-down market aggregation from cloud infrastructure spend disclosures.
Segmentation dimensions modeled encompass deployment architecture, interaction modality, industry vertical, and regulatory compliance tier across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves incorporating EU AI Act implementation timelines and RBI digital banking mandates. Forecast inputs include GPU availability constraints, certified engineering talent pool trajectories, and Fortune 500 contact center modernization cycle data.
The analysis sits within stated boundaries; outcomes outside sustained hyperscaler R&D investment levels or accelerated EU AI Act enforcement would require recalibration. Forecasts reflect documented assumptions regarding LLM accuracy improvement rates and healthcare regulatory pathway stability. Recalibration cycles align with material shifts in GPU supply availability and algorithmic transparency mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
South America AUV Market
Robotics and Automation
Europe AUV Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
Case and Box Handling Robots Market
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
Smart Lawn Robot Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Telepresence Robotics Market