
 Global Maternity Innerwear Market | 2026-2036
Global Maternity Innerwear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Maternity Innerwear Market Foresight
E-commerce distribution for maternity innerwear is fragmenting as direct-to-consumer platforms, marketplace aggregators, and specialty maternity apps compete for transaction volume. Seraphine leverages its British heritage and celebrity endorsements to sustain premium positioning across digital channels. Triumph Holding AG anchors European market presence through specialized retail partnerships and technical bra engineering. Wacoal competes in Asia with manufacturing scale and localized sizing expertise for trimester-specific fits.
Maternity innerwear encompasses engineered garments designed to accommodate physiological changes during pregnancy and lactation, typically incorporating stretch recovery fabrics with 15-25% elastane content and wireless support structures to accommodate fluctuating breast tissue volume. The primary commercial purpose is to provide ergonomic support, skin breathability, and convenient nursing access while minimizing pressure on sensitive abdominal and mammary areas. Nursing bras command significant margin pools due to extended wear duration and technical closure mechanisms, while bamboo fiber and modal blends represent the fastest-growing material segment driven by moisture-wicking and hypoallergenic performance. Online stores are displacing department stores as the dominant distribution channel, particularly for repeat purchases where sizing familiarity reduces return rates.
FDA regulates skin-contact textile claims in the United States, while REACH and OEKO-TEX Standard 100 govern chemical residue limits across European supply chains, collectively elevating compliance costs for synthetic dye processes and antimicrobial finishes. China's GB 18401 national textile safety standard and evolving SAMR labeling requirements create additional certification layers for brands sourcing from or selling into that market. Stakeholders must monitor how tightening chemical disclosure rules and emerging extended producer responsibility frameworks for textile waste reshape supplier qualification criteria and regional sourcing decisions.
Market Dynamics
Direct-to-consumer channel expansion is fragmenting traditional maternity innerwear distribution, as specialized apps and marketplace aggregators capture transaction volume previously held by department stores and specialty retailers. This structural shift compresses wholesale margins while elevating brand control over customer data and repeat purchase cycles.
Growth Catalysts
- REACH chemical compliance:Tightening residue limits for skin-contact textiles in Europe are accelerating supplier consolidation toward certified dye houses and finishers, favoring scaled manufacturers with in-house testing laboratories.
- Bamboo fiber adoption:Moisture-wicking and hypoallergenic performance attributes are pulling expectant mothers toward modal-blend nursing bras, extending average wear duration and supporting premium price realization.
- Millennial and Gen Z demand:These cohorts expect functional maternity apparel with wireless support structures and convenient nursing access, driving product refresh cycles and expanding addressable spend per pregnancy.
Market Restraints
- Elastane cost volatility:Synthetic fiber input prices fluctuate with petrochemical feedstock markets, compressing gross margins for stretch recovery fabrics with 15-25% elastane content.
- Chinese supply concentration:GB 18401 certification requirements and SAMR labeling rules create compliance friction for brands dependent on concentrated cut-and-sew capacity in coastal provinces.
- Wireless support limitations:Technical bra engineering for fluctuating breast tissue volume faces performance ceilings versus underwire alternatives, constraining category expansion among high-support seekers.
Strategic Opportunities
- India market penetration:BIS textile safety standards and rising disposable incomes create whitespace for premium maternity lingerie brands establishing localized sizing expertise.
- Nursing bra application extension:Technical closure mechanisms and extended wear duration position this segment for postpartum athletic and sleepwear crossover.
- Specialty maternity app channels:Trimester-specific fit algorithms and subscription replenishment models are capturing repeat purchases with reduced return rates.
Industry Challenges
- OEKO-TEX certification timelines:Standard 100 testing protocols for chemical residue limits extend product development cycles, delaying seasonal assortment launches.
- Technical talent scarcity:Pattern engineers with expertise in trimester-specific fit grading command premium compensation, constraining mid-tier brand R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Maternity Innerwear Market |
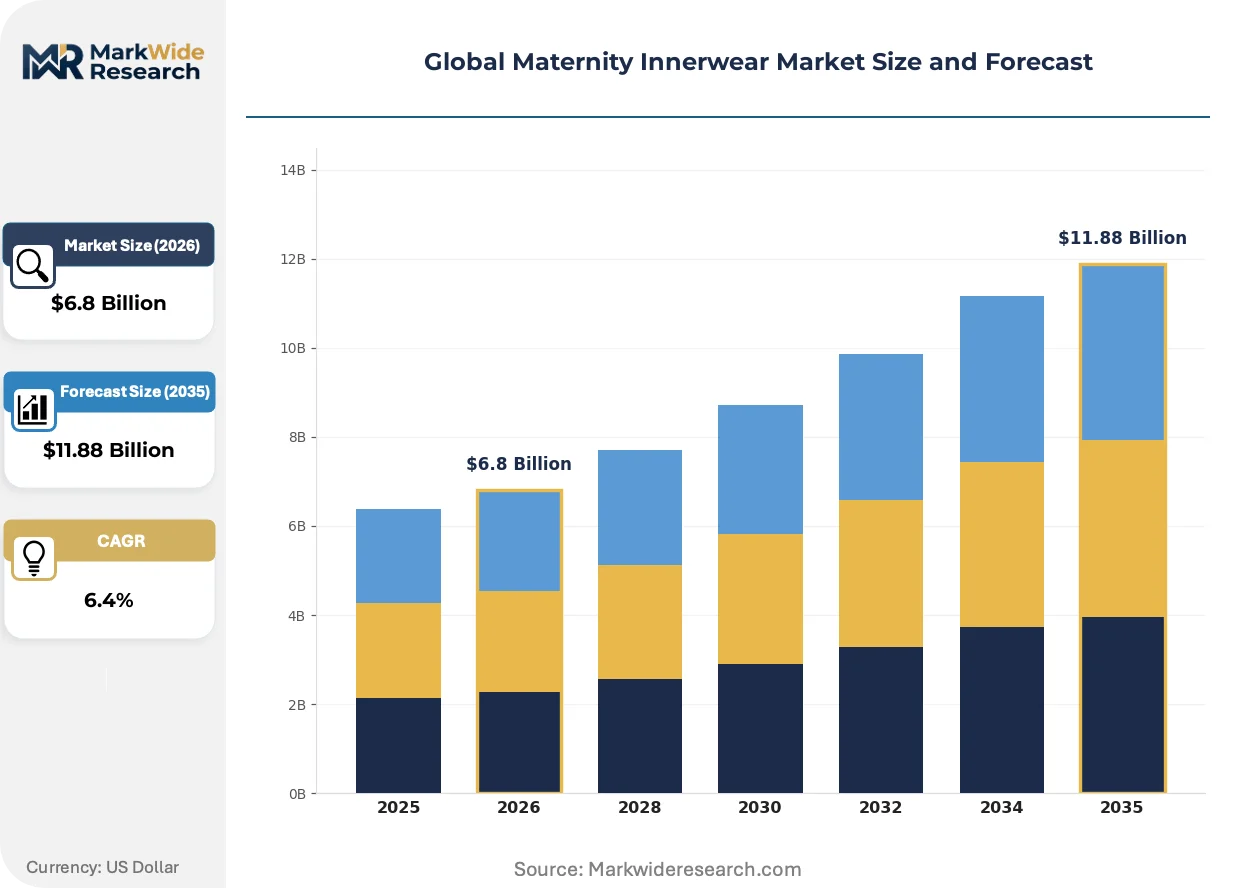
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maternity Bras, Nursing Bras, Maternity Panties, Support Bands, Camisoles Material: Cotton, Modal, Spandex, Nylon, Bamboo Fiber, Microfiber Distribution Channel: Online Stores, Specialty Boutiques, Department Stores, Pharmacies, Supermarkets End User: Pregnant Women, Nursing Mothers, Postpartum Mothers, Mothers-to-be |
| Companies Covered | Seraphine, Triumph Holding AG, Wacoal, H & M Hennes & Mauritz AB, Hatch Collection LLC, Hotmilk Lingerie, Bravado Designs, Cake Maternity, Kindred Bravely, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Maternity Innerwear Market Shifts & Advancements
Material science advances and regulatory disclosure requirements are converging to reshape maternity innerwear specifications, with performance attributes and chemical transparency now co-equal purchase criteria for educated expectant mothers.
Adaptive stretch fabrics with shape-memory polymers are migrating from athletic wear into maternity bra engineering, enabling single-garment accommodation of breast tissue volume changes across trimesters. Premium lingerie specialists in Germany and the United States are piloting these materials for nursing bra lines. This migration is compressing the traditional multi-size purchase pattern into fewer, higher-margin transactions per customer.
REACH authorization requirements for skin-contact textiles are tightening chemical disclosure obligations across European supply chains, forcing dye process reformulation and supplier requalification. Synthetic antimicrobial finishes face particular scrutiny under evolving ECHA guidance. Nursing bra categories with extended skin contact duration are experiencing the most intensive compliance investment.
Subscription replenishment models for maternity innerwear are displacing one-time retail purchases among second-time mothers with established sizing familiarity. Direct-to-consumer platforms in the United States and China are capturing this behavioral shift through trimester-timed delivery algorithms. This pattern is most visible among millennial cohorts prioritizing convenience over in-store fitting experiences.
Global Maternity Innerwear Market Segmentation
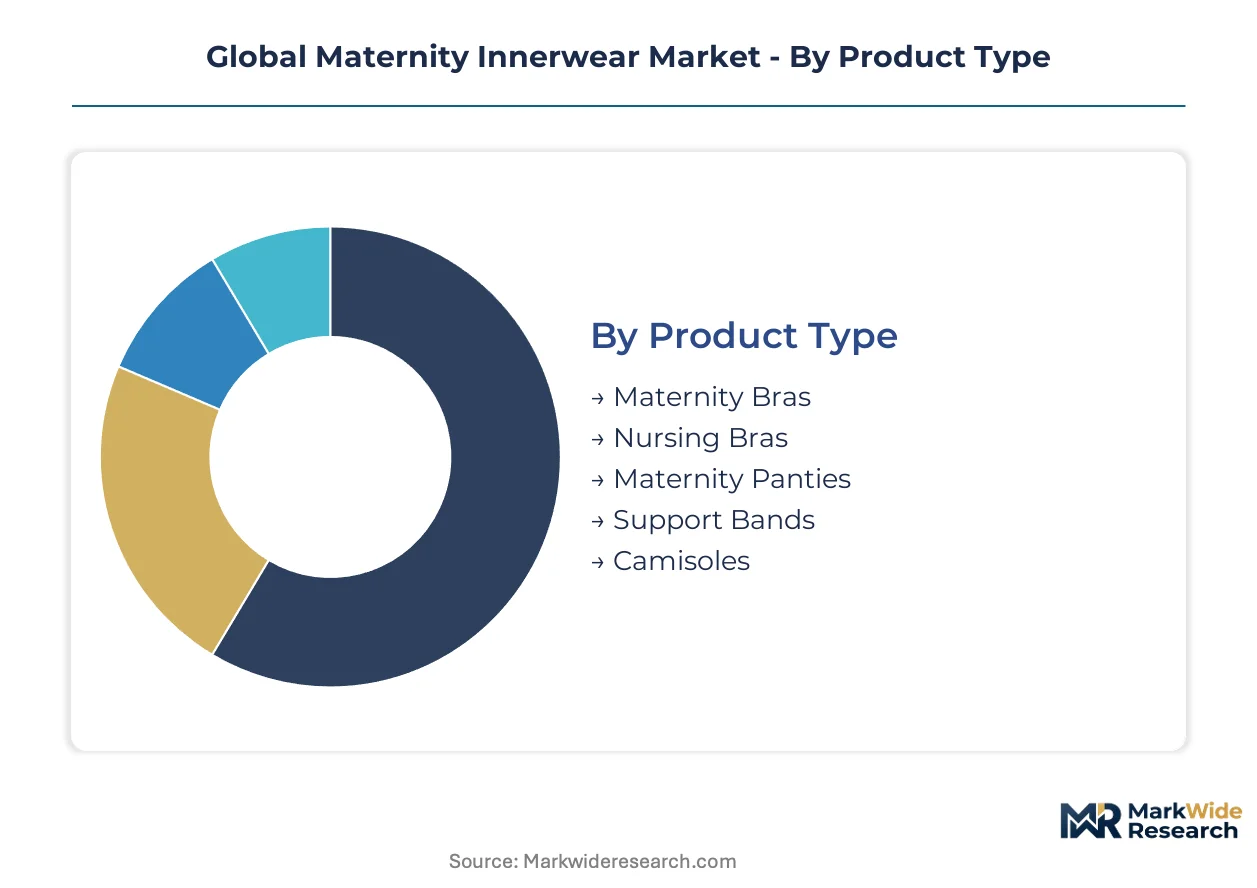
Maternity innerwear segmentation reflects divergent technical requirements across pregnancy stages and lactation periods. Product architecture, material selection, and channel strategy must align with trimester-specific physiological changes and repeat purchase behaviors.
Product Type:
Application-specific engineering separates functional maternity garments from conventional lingerie categories, with wireless support structures and nursing access mechanisms defining commercial value.
- Maternity Bras:Engineered with 15-25% elastane content for stretch recovery during trimester transitions, these garments accommodate fluctuating breast tissue volume without underwire pressure. Demand concentrates in Germany and the United States, where premium lingerie brands emphasize technical fit grading for second-trimester expansion.
- Nursing Bras:Technical closure mechanisms—drop-down cups, magnetic fasteners, and front-open designs—extend wear duration into postpartum periods. Mothers in China and the United States drive volume, prioritizing convenience for frequent feeding schedules and workplace pumping compatibility.
- Maternity Panties:Low-rise and over-bump silhouettes address abdominal sensitivity with seamless construction and breathable gusset linings.
- Support Bands:Compression fabrics redistribute lumbar load during third-trimester weight gain, with obstetrician recommendations driving pharmacy channel placement.
- Camisoles:Built-in shelf bras and nursing panel integration serve sleepwear and layering functions for hospital bag preparation.
Nursing bras command margin premiums through extended wear cycles. Maternity panties deliver volume throughput via lower price points and higher replacement frequency.
Material:
Skin-contact chemistry and moisture management properties determine material selection, with regulatory compliance costs varying sharply across fiber categories.
- Cotton:Natural fiber dominance persists in mass-market segments, though conventional cultivation pesticide residues trigger OEKO-TEX Standard 100 testing protocols for European import clearance.
- Modal:Cellulosic fiber derived from beechwood pulp delivers silk-like drape and superior moisture absorption versus cotton. German and Austrian specialty producers supply premium maternity lingerie brands targeting REACH-compliant supply chains.
- Bamboo Fiber:Fastest-expanding category driven by hypoallergenic claims and antimicrobial performance without synthetic chemical finishes. Chinese viscose producers dominate raw supply, with European brands absorbing certification costs for ECHA-aligned dye processes.
- Spandex:Essential for 15-25% elastane blends enabling stretch recovery; petrochemical feedstock volatility compresses gross margins.
- Nylon:Microfiber constructions support seamless knitting for invisible undergarment lines.
- Microfiber:Ultra-fine denier synthetic blends enable lightweight, quick-dry performance for tropical climates and athletic crossover applications.
Modal and bamboo fiber blends gain share fastest among millennial cohorts prioritizing chemical transparency. Cotton retains the established volume base through price accessibility and retail familiarity.
Distribution Channel:
Channel economics fragment as direct-to-consumer platforms capture customer data and repeat purchase cycles previously held by physical retail.
- Online Stores:Trimester-timed algorithms and subscription replenishment models reduce return rates among second-time mothers with established sizing familiarity. United States and Chinese platforms lead algorithmic personalization investment.
- Specialty Boutiques:Professional fitting services and curated brand assortments sustain premium price realization in urban centers. German midwife network referrals concentrate demand in Munich, Hamburg, and Berlin clusters.
- Department Stores:Foot traffic erosion accelerates space reduction for maternity lingerie, with remaining fixtures consolidating toward entry-level cotton basics.
- Pharmacies:Clinical credibility supports support band and postpartum compression garment placement, particularly in European markets with pharmacist consultation norms.
- Supermarkets:Impulse accessibility and price-driven positioning capture emergency replacement purchases and trial-size introductions.
Online stores capture the steepest expansion trajectory through convenience positioning. Specialty boutiques defend margin pools via service differentiation.
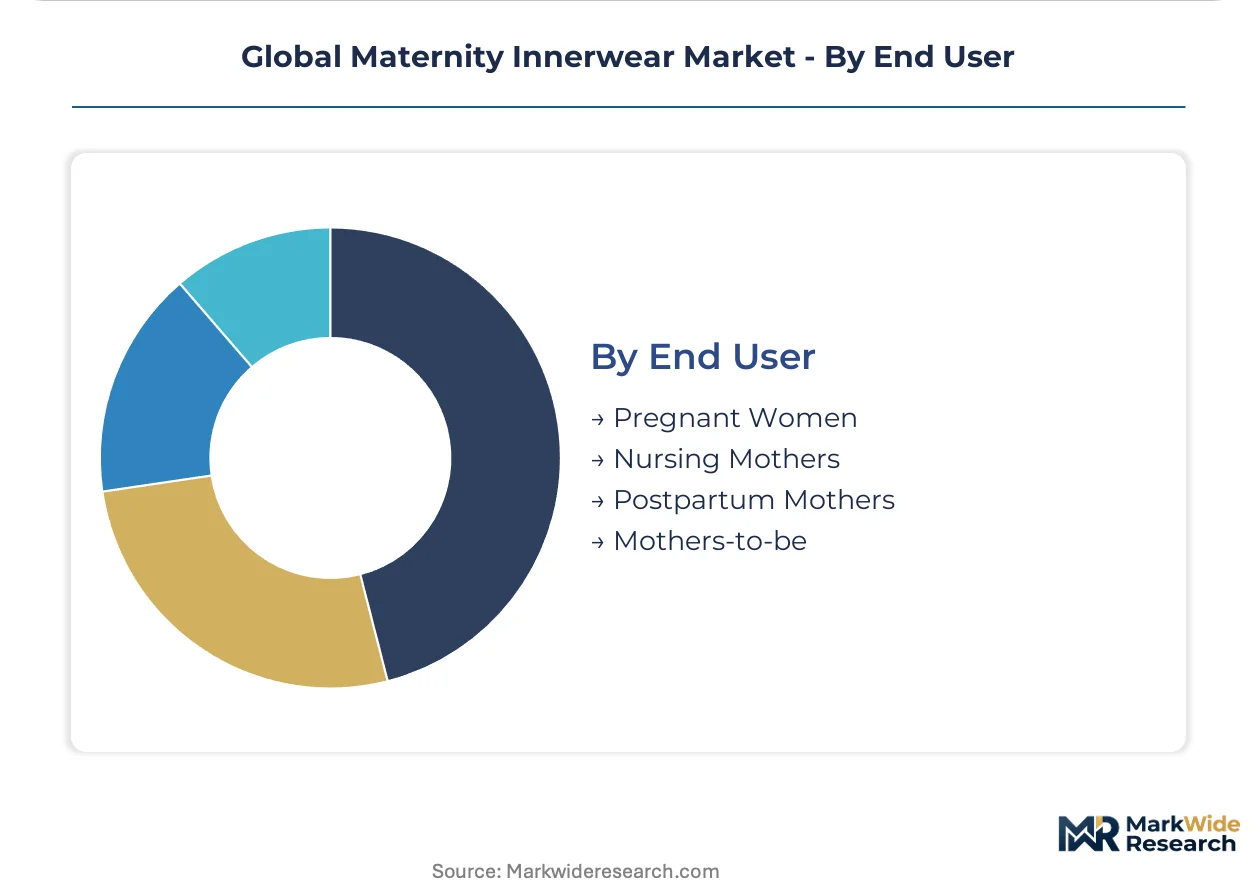
End User:
Customer lifecycle stage dictates functional priorities, with physiological transition timelines creating distinct purchasing windows and product specifications.
- Pregnant Women:First-trimester nausea sensitivity and third-trimester skin stretching demand seamless, tag-free construction with adjustable sizing architectures.
- Nursing Mothers:Milk supply fluctuations and leakage management require moisture-wicking linings and absorbent pad pockets; workplace pumping compatibility drives United States demand for discreet access designs.
- Postpartum Mothers:Abdominal muscle recovery and breast engorgement resolution create compression garment and transitional sizing requirements distinct from pregnancy-period offerings.
- Mothers-to-be:Pre-conception and early pregnancy preparation purchases concentrate in gift-giving occasions and hospital bag assembly, favoring coordinated sets over individual garment selection.
Nursing mothers generate the highest per-customer lifetime value through extended wear duration. Mothers-to-be represent the fastest-growing addressable segment as prenatal preparation rituals expand across developed Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's textile logistics corridor underwrites European distribution efficiency for maternity innerwear brands sourcing modal and bamboo fiber blends from Austrian and Chinese viscose producers.
United States
Millennial expectant mothers drive direct-to-consumer channel adoption through trimester-timed subscription algorithms. FDA regulates skin-contact textile claims for nursing bras with extended wear duration. Los Angeles and New York City clusters host premium lingerie brand headquarters and influencer marketing ecosystems.
Germany
REACH chemical compliance requirements accelerate supplier consolidation toward certified dye houses with in-house testing laboratories. ECHA authorization protocols for antimicrobial finishes reshape nursing bra product development cycles. Munich, Hamburg, and Berlin midwife referral networks concentrate specialty boutique demand for technical fit grading services.
China
GB 18401 national textile safety standards and SAMR labeling rules create certification layers for brands sourcing from coastal cut-and-sew provinces. NMPA oversight extends to postpartum compression garment claims in pharmacy channels. Yangtze River Delta manufacturing clusters dominate bamboo viscose raw supply for export-oriented premium brands.
India
Rising disposable incomes among urban expectant mothers create whitespace for premium maternity lingerie establishing localized sizing expertise. BIS textile safety standards govern import clearance for modal-blend nursing bras. Maharashtra and Karnataka sub-regions concentrate e-commerce platform development for trimester-specific fit algorithms.
Japan
METI industrial policy supports technical textile innovation in shape-memory polymers for adaptive stretch fabrics. PMDA consultation frameworks influence postpartum compression garment channel placement in pharmacy and hospital retail. Tokyo-Osaka corridor hosts specialized pattern engineering talent for trimester-specific fit grading.
Global Maternity Innerwear Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fabric innovation and technical closure mechanisms. The maternity innerwear market exhibits tiered concentration with premium lingerie houses, mass-market apparel conglomerates, and specialized maternity pure-plays occupying distinct margin pools. Three strategic archetypes dominate: heritage European engineering specialists, Asian manufacturing scale leaders, and direct-to-consumer digital natives. Competitive moves center on backward integration into certified fiber supply and algorithmic personalization investments for repeat purchase retention.
Among heritage-positioned specialists, Seraphine leverages British provenance and celebrity endorsement architectures, while Triumph Holding AG anchors European technical bra engineering through specialized retail partnerships. Wacoal exemplifies Asian manufacturing scale advantages with localized sizing expertise for trimester-specific fit architectures. These three occupy positions across the premium-to-mass spectrum without overlapping core channel strategies.
| Leading Market Players |
|---|
| Seraphine |
| Triumph Holding AG |
| Wacoal |
| H & M Hennes & Mauritz AB |
| Hatch Collection LLC |
| Hotmilk Lingerie |
| Bravado Designs |
| Cake Maternity |
| Kindred Bravely |
| Others |
Supply & Pricing Matrix
Coastal China cut-and-sew underutilization is pressuring contract manufacturers to absorb dye certification costs while brands consolidate purchase volumes to defend margin pools. This utilization dynamic concentrates pricing power with scaled OEKO-TEX certified suppliers and forces mid-tier labels toward private-label exit.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Seraphine-tier celebrity-endorsed nursing bras from Triumph's technical engineering tier and mass-market cotton basics. Price differentiation hinges on OEKO-TEX Standard 100 certification grade and elastane blend ratio. Pricing pressure stems from petrochemical feedstock volatility in spandex inputs. First-time mothers in Germany show lowest price sensitivity; repeat purchasers in United States supermarkets exhibit highest elasticity.
Supply Chain Analysis
Yangtze River Delta contract manufacturers hold dominant cut-and-sew capacity for bamboo viscose nursing bras, with secondary concentration in Bangladesh for cotton basics and Vietnam for seamless microfiber panties. Raw material dependencies center on Austrian modal pulp, Chinese bamboo viscose, and Korean spandex fiber. Single-source vulnerability concentrates in ECHA-aligned dye house certification. Distribution runs through direct-to-consumer platforms and specialty maternity apps capturing repeat purchase cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as millennial and Gen Z prenatal preparation rituals extend addressable spend per pregnancy beyond traditional single-trimester purchasing windows.
For Market Incumbents: Build certification moats by captive investment in REACH-compliant dye houses with in-house testing laboratories. Consolidate supplier relationships toward OEKO-TEX Standard 100 certified finishers to outpace mid-tier compliance costs. Defend against direct-to-consumer digital natives by locking specialty boutique channel exclusivity in German midwife referral networks.
For New Entrants and Emerging Players: Build out trimester-specific fit algorithm capabilities for subscription replenishment models targeting second-time mothers. White-space concentrates in India's Maharashtra and Karnataka e-commerce corridors where BIS certification barriers remain penetrable. Go-to-market angle: localized sizing expertise for South Asian body grading standards absent from incumbent portfolios.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across bamboo fiber processing as Chinese viscose producers achieve scale efficiencies. Long-term viability favors brands with backward integration into certified fiber supply and algorithmic personalization infrastructure. Acquisition target archetype: specialty maternity apps with established repeat purchase retention data. Signal to watch: OEKO-TEX certification timeline compression as competitive moat indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Fiber Supply | Captive OEKO-TEX aligned dye capacity insulates margin pools from ECHA regulatory tightening. |
| Direct-to-Consumer Platform Launch | Trimester-timed algorithms reduce return rates among repeat purchasers in United States and China. |
| Subscription Replenishment Model | Second-mother convenience positioning captures lifetime value erosion from department store channel exit. |
| Specialty Maternity App Partnership | Algorithmic fit personalization defends against mass-market aggregator commoditization. |
| Sustainability Repositioning | Bamboo fiber certification investment aligns with millennial chemical transparency purchase criteria. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, OEKO-TEX certification databases, and SEC apparel sector filings. Interviews with maternity lingerie brand managers, specialty boutique buyers, contract manufacturing procurement leads, and midwife network coordinators were triangulated with Nielsen retail audit data and GB 18401 compliance documentation. Bottom-up sizing estimates from distribution channel volumes were validated against top-down consumer expenditure surveys.
Forecast inputs span product type segmentation across nursing bras, maternity bras, and support bands; material tiers from cotton through modal and bamboo fiber; and distribution channel evolution from department stores toward online stores and specialty apps. CAGRs were derived from elasticity-adjusted adoption curves across the projection horizon. Industry-specific inputs include elastane cost volatility scenarios and REACH authorization timeline assumptions for antimicrobial finish reformulation.
Stress conditions across petrochemical feedstock price bands, ECHA enforcement intensity, and Chinese export certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding millennial cohort size stability and prenatal preparation ritual penetration rates. Quarterly review of OEKO-TEX certification backlog indicators and modal pulp futures pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Rolle Market
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
Thailand Garment Industry Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
Bridal Gowns Market
Apparel Textiles
Rain Apparel Market
Apparel Textiles
Cosplay Clothing Market
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Stockings Market
Apparel Textiles
Denim Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Flame Retardant Apparel Market