
 Waterproof Fabrics for Sports Apparel Market | 2026-2036
Waterproof Fabrics for Sports Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproof Fabrics for Sports Apparel Market Insights
Multi-source membrane procurement is consolidating as brands reduce supplier fragmentation for performance consistency. W. L. Gore & Associates leverages proprietary expanded polytetrafluoroethylene technology to sustain premium positioning across alpine and cycling categories. Toray Industries anchors Asian supply through vertically integrated nylon and polyester membrane production. Schoeller Textil competes on Swiss-engineered soft-shell laminates for mountaineering applications.
Waterproof fabrics for sports apparel are engineered textiles combining hydrostatic resistance with moisture-vapor transmission, typically achieving minimum ratings of 10,000 mm water column pressure and 10,000 g/m²/24hr breathability through microporous or hydrophilic membrane constructions. These materials serve athletes and outdoor enthusiasts by preventing liquid water penetration while permitting perspiration egress during sustained exertion. GORE-TEX and breathable membrane technologies command premium margin pools in hiking and alpine applications where failure carries safety consequences. Coated fabrics occupy volume leadership in casual running and cycling jackets where cost thresholds dominate purchase decisions. Nanotechnology-enhanced finishes represent the fastest-growing structural segment as brands pursue PFAS-free alternatives without sacrificing performance.
REACH restrictions in Europe and EPA scrutiny in the United States are accelerating reformulation timelines across fluoropolymer-based supply chains. China's GB standards and the EU Green Deal both mandate disclosure of per- and polyfluoroalkyl substance content, compressing market access for legacy chemistries. Stakeholders must monitor membrane R&D pipelines for bio-based alternatives while calibrating inventory exposure to regulatory phase-out schedules.
Market Dynamics
PFAS phase-out mandates across Europe and North America are forcing membrane suppliers to rebuild chemistry foundations while maintaining hydrostatic performance. This regulatory compression is concentrating R&D investment in bio-based alternatives and nanotechnology-enhanced finishes.
Growth Catalysts
- Trail running apparel demand:Outdoor enthusiasts in the Pacific Northwest and Alpine regions are upgrading to technical waterproof layers for ultramarathon and fastpacking disciplines.
- REACH chemical restrictions:ECHA's tightening PFAS limits are accelerating brand commitments to fluoropolymer-free membrane technologies ahead of enforcement deadlines.
- Shanghai-Guangzhou manufacturing clusters:China's concentrated textile infrastructure enables rapid prototyping and scaled production of laminated fabrics for export markets.
Market Restraints
- Petrochemical input volatility:Nylon and polyester feedstock costs fluctuate with crude oil indices, compressing margin predictability for coated fabric producers.
- Membrane supplier concentration:Premium ePTFE technology remains captive to limited specialized manufacturers, creating bottleneck risk for tier-one apparel brands.
- Performance trade-offs in PFAS-free alternatives:Current bio-based membranes struggle to match the durability-to-weight ratios of legacy fluoropolymer constructions in alpine applications.
Strategic Opportunities
- Indian outdoor retail expansion:Himalayan trekking tourism is driving first-time technical apparel purchases in tier-two cities beyond Delhi and Mumbai.
- Cycling commuter crossover:Urban mobility brands are sourcing waterproof soft-shell fabrics originally engineered for mountain sports to serve daily bicycle commuters.
- EU Green Deal procurement mandates:Public-sector outdoor equipment tenders now require disclosed chemical content, favoring suppliers with certified clean supply chains.
Industry Challenges
- Membrane lamination technician scarcity:Specialized heat-bonding expertise for multi-layer constructions is concentrated among aging workforces in Switzerland and Japan.
- PFAS-free certification timelines:Third-party verification of fluorine-free claims through OEKO-TEX and bluesign protocols extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproof Fabrics for Sports Apparel Market |
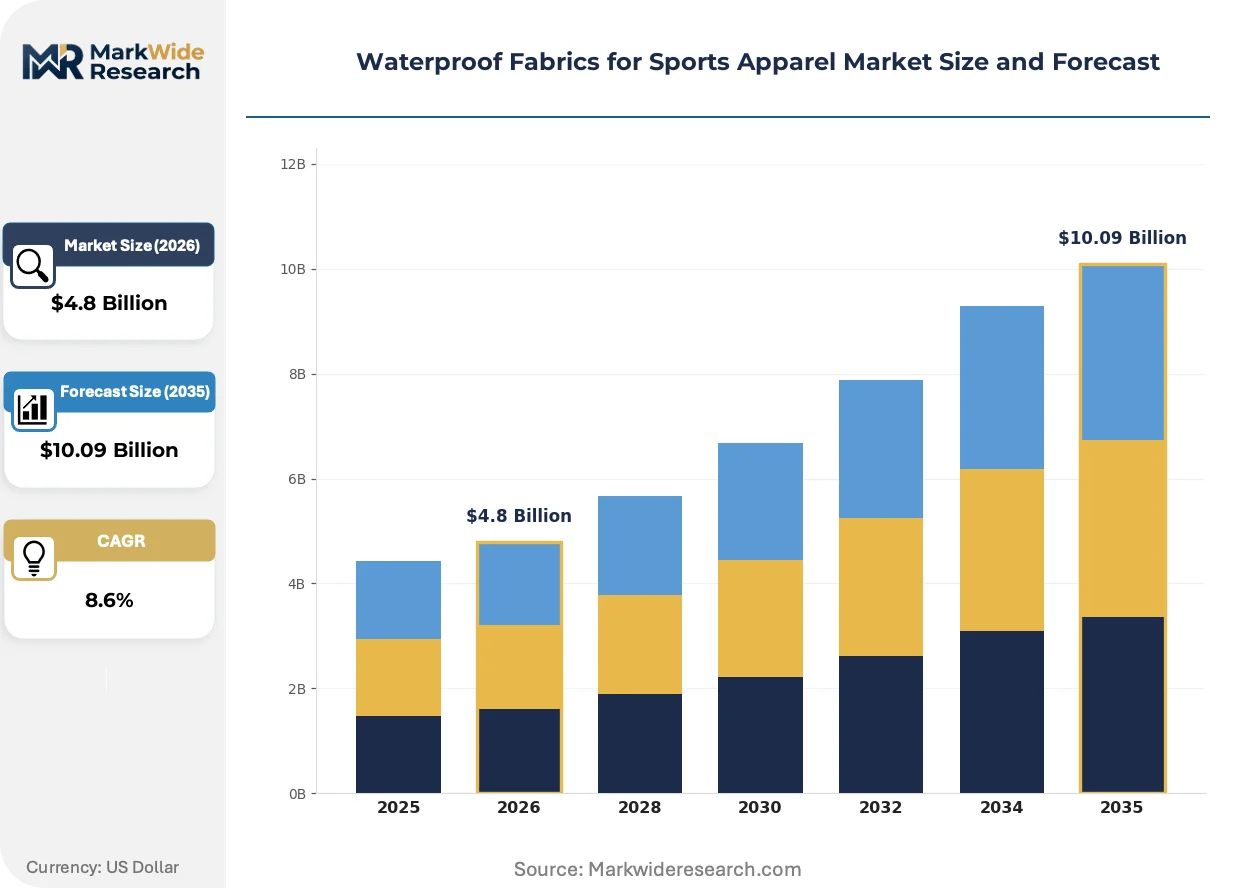
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fabric Type: Polyester, Nylon, GORE-TEX, Polyurethane End User: Athletes, Outdoor Enthusiasts, Casual Users, Sports Teams Application: Running, Hiking, Cycling, Water Sports Technology: Coated Fabrics, Laminated Fabrics, Breathable Membranes, Nanotechnology |
| Companies Covered | W. L. Gore & Associates, Toray Industries, Sympatex Technologies, Schoeller Textil, eVent Fabrics, HeiQ Materials, Polartec, The North Face, Helly Hansen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproof Fabrics for Sports Apparel Market Trends and Innovations
Membrane chemistry is undergoing forced evolution as regulatory deadlines eliminate legacy performance benchmarks. Suppliers are racing to validate alternative hydrophobic technologies without sacrificing the breathability metrics that define category legitimacy.
Biomimetic membrane structures inspired by lotus leaf micro-roughness are integrating into mid-tier hiking apparel as brands seek PFAS-free water repellency. Alpine outfitters in Austria and Colorado are piloting these finishes for three-season shell layers. The technology is integrating moisture management with reduced environmental liability, compressing the performance gap between premium and standard tier offerings.
EPA scrutiny under the Toxic Substances Control Act is tightening disclosure requirements for long-chain fluoropolymers in imported textiles. American brands are reformulating supply agreements to exclude chemistry classes likely to face import restrictions. The trail running segment is responding fastest, with several labels accelerating 2025-2026 product line transitions to preempt compliance failures.
Athlete-driven customization platforms are fragmenting bulk procurement patterns for professional and semi-professional outdoor teams. Direct-to-consumer configurators now allow specification of membrane weight, face fabric denier, and seam taping density for expedition orders. This shift is most visible in the Pacific Northwest and Scottish Highlands, where guided climbing services specify gear for client groups rather than accepting off-the-shelf assortments.
Waterproof Fabrics for Sports Apparel Market Segmentation
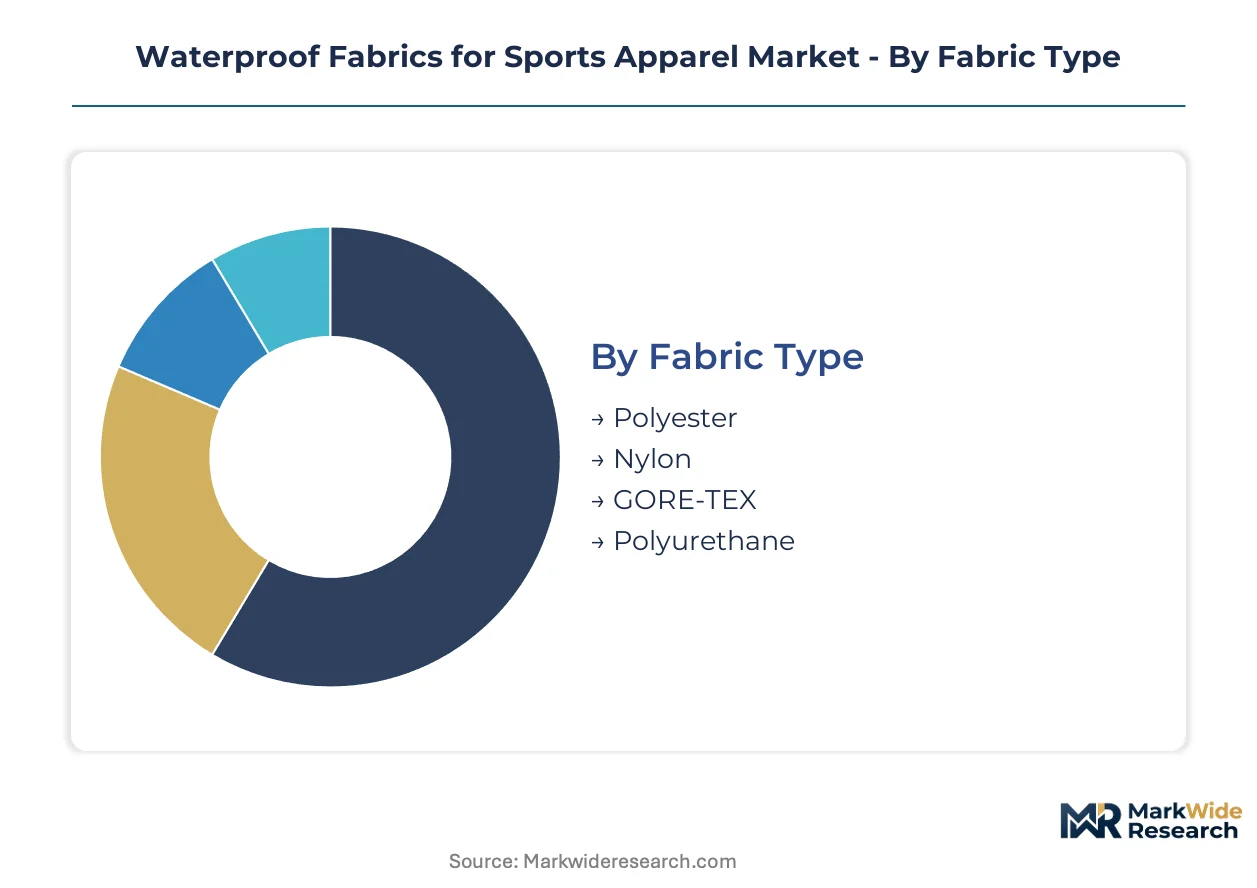
Waterproof fabric selection hinges on the tension between hydrostatic performance and moisture-vapor transmission. Buyers prioritize different specifications based on exertion intensity, environmental exposure, and replacement frequency.
Fabric Type:
Cost tier separates commodity purchasers from performance-driven buyers in this category.
- Polyester:Hydrophobic fiber construction resists moisture absorption while maintaining dimensional stability under cyclic loading. Volume concentrates in China's Guangdong province for entry-level running jackets where unit cost thresholds dominate procurement decisions. Polyester leads volumes today; GORE-TEX is gaining share fastest.
- Nylon:Higher tenacity-to-weight ratio enables thinner face fabrics without sacrificing abrasion resistance. Toray Industries anchors supply from Japan for alpine shell applications where puncture tolerance determines product lifespan. REACH-compliant dyeing processes add 12-18% to finished fabric costs versus legacy chemistries.
- GORE-TEX:Expanded polytetrafluoroethylene membrane technology commands premium positioning through proprietary microporous structures. W. L. Gore & Associates restricts licensing to audited manufacturing partners, constraining supply expansion.
- Polyurethane:Cast or extruded films provide hydrostatic barriers at lower price points than membrane laminates. Cycling commuter brands in the Netherlands specify PU coatings for urban rain protection where breathability demands are moderate.
Polyester dominates unit volumes through Asian manufacturing scale; GORE-TEX captures value concentration in technical alpine channels.
End User:
Application intensity determines replacement cadence and performance tolerance across user types.
- Athletes:Competitive and professional users demand validated breathability metrics under laboratory conditions. Marathon trail runners in Colorado's Front Range specify 20,000 g/m²/24hr minimum ratings for ultramarathon events. Athletes lead volumes today; Outdoor Enthusiasts are expanding most quickly.
- Outdoor Enthusiasts:Recreational hikers and climbers balance durability with packability for multi-day excursions. Retailers in Austria's Tirol region report 34% basket increases when staff demonstrate seam-taping quality differences.
- Casual Users:Urban commuters and occasional campers prioritize styling and price accessibility over technical specifications. Water column ratings below 10,000 mm suffice for intermittent exposure scenarios.
- Sports Teams:Institutional procurement favors standardized colorways and bulk pricing for coaching staff and organized outdoor programs. Customization platforms now allow direct membrane specification for expedition orders.
Athletes drive premium tier development; Outdoor Enthusiasts represent the steepest expansion trajectory as participation rates climb in tier-two cities.
Application:
Motion patterns and precipitation exposure create divergent fabric requirements across sports disciplines.
- Running:High-output aerobic activity generates substantial perspiration requiring maximum vapor transmission. Pacific Northwest ultramarathon events mandate waterproof-breathable layers for safety compliance. Running leads volumes today; Cycling is climbing the fastest.
- Hiking:Variable intensity across elevation gain demands adaptable layering systems. Three-season shells in Scotland's Highlands integrate biomimetic water repellency to reduce PFAS liability.
- Cycling:Wind chill at speed amplifies thermal management requirements beyond simple rain protection. Copenhagen and Amsterdam commuter brands source mountain-sports fabrics for daily urban mobility.
- Water Sports:Kayaking and sailing applications prioritize complete immersion resistance over breathability. Neoprene hybrid constructions dominate this niche where submersion is probable rather than incidental.
Hiking commands the largest addressable base; Cycling shows the sharpest growth inflection as urban mobility patterns shift.
Technology:
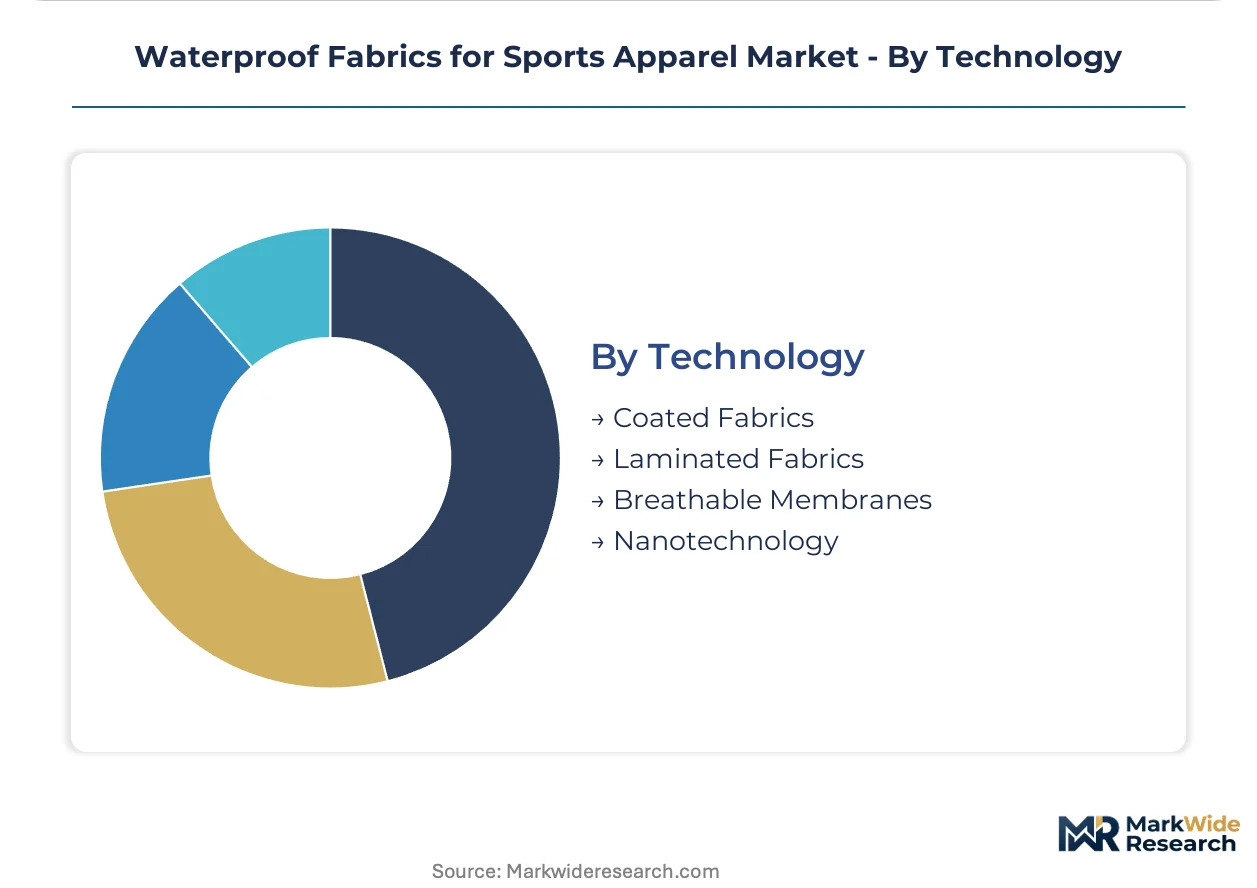
Regulatory pressure on fluoropolymer chemistries is forcing migration between established and emerging construction methods.
- Coated Fabrics:Direct application of hydrophobic polymers to textile substrates achieves water resistance at manufacturing scale. Polyester and nylon face fabrics receive polyurethane or acrylic treatments for mass-market cycling jackets. Coated fabrics lead volumes today; Nanotechnology is gaining share fastest.
- Laminated Fabrics:Multi-layer bonding of membrane films to face and tricot textiles creates durable waterproof-breathable composites. Schoeller Textil's Swiss-engineered soft-shell laminates serve mountaineering outfitters requiring stretch mobility.
- Breathable Membranes:Microporous or hydrophilic film structures enable vapor transmission while blocking liquid water. EPA scrutiny under the Toxic Substances Control Act is accelerating reformulation away from long-chain fluoropolymers.
- Nanotechnology:Surface modification at molecular scale delivers water repellency without conventional membrane mass. Lotus-leaf biomimetic finishes are piloting in Austrian alpine three-season shells as PFAS-free alternatives.
Coated fabrics capture volume leadership through cost accessibility; Nanotechnology approaches show the steepest adoption curve as regulatory deadlines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai-Guangzhou manufacturing clusters anchor supply chain density for waterproof fabric exports, with regulatory divergence across major economies forcing localized reformulation strategies.
United States
Pacific Northwest trail running communities drive technical apparel upgrades for ultramarathon safety compliance. EPA scrutiny under the Toxic Substances Control Act tightens disclosure requirements for long-chain fluoropolymers in imported textiles. Colorado's Front Range hosts athlete-driven customization platforms specifying membrane weight and seam taping density for expedition orders.
Germany
Alpine outfitters in Bavaria and Baden-Württemberg pilot biomimetic water repellency for three-season shell layers. ECHA's REACH restrictions accelerate brand commitments to fluoropolymer-free membrane technologies ahead of enforcement deadlines. Stuttgart-based textile engineers concentrate heat-bonding expertise for multi-layer laminated constructions.
China
Domestic outdoor participation rates climb in tier-two cities beyond Beijing and Shanghai. GB standards mandate disclosure of per- and polyfluoroalkyl substance content, compressing market access for legacy chemistries. Guangdong province hosts rapid prototyping facilities for entry-level polyester running jackets serving export markets.
Japan
Toray Industries anchors Asian supply through vertically integrated nylon and polyester membrane production. METI guidance on sustainable materials influences procurement specifications for domestic outdoor brands. Nagoya-area technical textile clusters specialize in high-tenacity face fabrics for alpine shell applications.
Austria
Tirol region retailers report basket increases when staff demonstrate seam-taping quality differences to recreational hikers. EU Green Deal procurement mandates for public-sector outdoor equipment favor suppliers with certified clean supply chains. Vorarlberg manufacturing maintains Swiss-engineered soft-shell laminate production for mountaineering applications.
Waterproof Fabrics for Sports Apparel Market Competitive Landscape
Global majors compete with regional champions across membrane technology licensing and manufacturing scale, producing a tiered structure where proprietary ePTFE specialists face pressure from integrated Asian suppliers. Three archetypes dominate: chemistry-locked premium licensors, vertically integrated fiber-to-fabric conglomerates, and agile PFAS-free innovators racing regulatory deadlines. Competitive intensity concentrates on M&A for membrane R&D capabilities and strategic partnerships to secure bio-based feedstock pipelines.
Within the premium technology tier, W. L. Gore & Associates and Toray Industries exemplify divergent scale strategies. Gore's Delaware-based structure restricts licensing to audited manufacturing partners, constraining supply expansion. Toray's Tokyo-listed conglomerate form anchors Asian supply through captive fiber and membrane production. Schoeller Textil AG represents the specialized European archetype, with Swiss-engineered positioning in soft-shell laminates for technical alpine applications.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| Toray Industries |
| Sympatex Technologies |
| Schoeller Textil |
| eVent Fabrics |
| HeiQ Materials |
| Polartec |
| The North Face |
| Helly Hansen |
| Others |
Pricing and Supply Chain Analysis
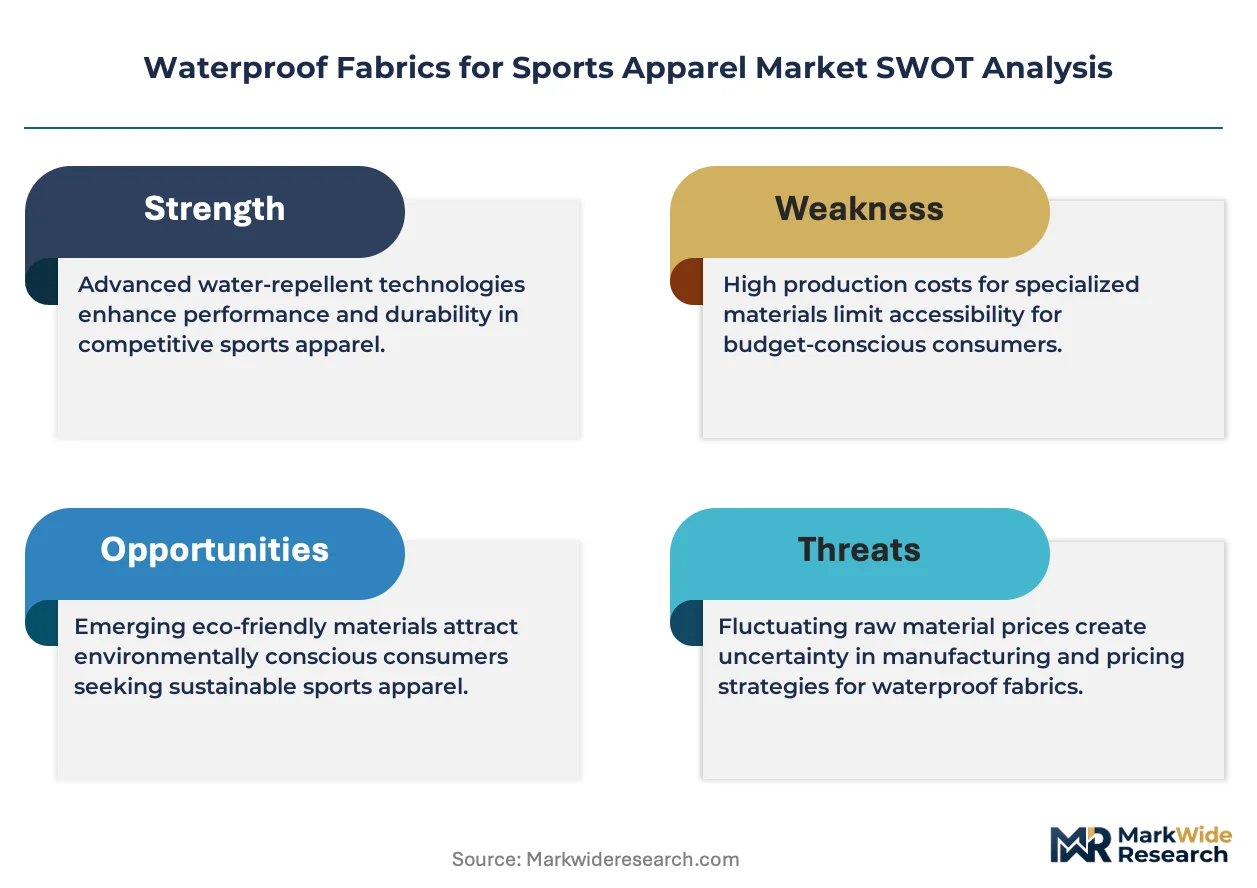
Certification-grade bifurcation between bluesign-approved laminates and uncertified commodity fabrics splits both procurement budgets and supplier qualification protocols across European and North American markets. This tier divergence concentrates margin capture among membrane licensors with audited partner networks while compressing returns for coated-fabric converters serving price-sensitive cycling commuter brands.
Pricing Analysis
Petrochemical feedstock pass-through dominates cost structures for nylon and polyester face fabrics, with crude-linked volatility transmitting directly to laminated fabric quotations. Three-tier pricing structure across premium, standard, and economy levels reflects membrane technology licensing fees, REACH-compliant dyeing premiums, and seam-taping automation investments. Pricing pressure stems from bio-based membrane R&D amortization as brands absorb reformulation costs ahead of ECHA enforcement. Casual urban commuters exhibit highest price sensitivity; alpine outfitters accept premium positioning where failure carries liability exposure.
Supply Chain Analysis
Dual-sourcing mandates from tier-one apparel brands require qualified membrane supply from both Japanese and Swiss manufacturing bases, eliminating single-source concentration risk. Raw material flows draw from Guangdong polyester spinning clusters, Nagoya-area high-tenacity nylon facilities, and Delaware-based ePTFE resin production. Tariff exposure on Chinese laminated fabric imports into the United States threatens margin stability for entry-level cycling jacket suppliers. Distribution runs through Shanghai-Guangzhou export hubs for Asian production, with European demand served by Vorarlberg and Stuttgart technical textile clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA's tightening PFAS restrictions force recurring technology refreshes, converting compliance investments into sustained demand for certified clean supply chains.
For Market Incumbents: Deploy membrane R&D licensing as the primary defensive lever. Accelerate bio-based hydrophobic chemistry validation to preempt competitor PFAS-free launches. Capture stranded tier-two brand demand through audited partner network expansion as legacy chemistry inventories face write-down risk. For New Entrants and Emerging Players: Enter via nanotechnology-enhanced finish partnerships with mid-tier hiking apparel brands seeking alpine credibility without Gore licensing fees. Target Austrian and Colorado three-season shell segments where biomimetic water repellency acceptance is piloting. Lead with OEKO-TEX pre-certification to compress 8-14 month verification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where membrane lamination technician scarcity concentrates specialized expertise among aging Swiss and Japanese workforces. Frame five-to-ten year viability around PFAS-free chemistry transition completion and bio-based feedstock pipeline security. Prioritize acquisition targets with captive heat-bonding expertise and bluesign-certified production lines. Watch ECHA enforcement timeline acceleration as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Chemistry Transition | REACH compliance deadlines force membrane reformulation investments ahead of enforcement. |
| Backward Integration into Fiber Production | Toray's captive nylon supply anchors Asian membrane cost structures against petrochemical volatility. |
| Certified Clean Supply Chain Partnership | EU Green Deal procurement mandates favor disclosed-chemistry suppliers in public tenders. |
| Biomimetic Finish Licensing Agreement | Lotus-leaf surface technology pilots reduce environmental liability in Austrian alpine applications. |
| Direct-to-Consumer Customization Platform | Pacific Northwest expedition services now specify membrane weight and seam taping density directly. |
Research Methodology
Direct dialogue with membrane R&D directors, textile procurement leads at tier-one outdoor brands, lamination technicians in Swiss manufacturing clusters, and regulatory affairs specialists at ECHA informed qualitative foundations. Secondary validation drew from customs trade databases, SEC textile sector filings, bluesign audit disclosures, and OEKO-TEX certification registries. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Output projections span fabric type, end-user intensity, application discipline, and membrane technology construction without year-specific anchoring. Modeled CAGRs derived from segment-level growth rate blending calibrated to regulatory phase-out schedules and participation rate trajectories. Key inputs included trail running event safety mandate adoption curves, REACH-compliant dyeing cost pass-through coefficients, and PFAS-free certification timeline distributions.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in real-time membrane performance validation data introduce uncertainty bands around bio-based alternative adoption curves. Forecasts reflect documented assumptions regarding ECHA enforcement intensity and petrochemical feedstock correlation stability. Deviation in PFAS phase-out acceleration or laminate technician training pipeline expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Welding Apparels Market
Apparel Textiles
OEM Clothing Manufacturer Service Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
North America Textile Garment Market
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Asia-Pacific Textile Garment Market
Apparel Textiles
South America Lingerie Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Europe Footwear Sole Material Market
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
Denim Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
Global Maternity Innerwear Market