
 Global Log Management Software Market | 2026-2036
Global Log Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Log Management Software Market Foresight
Enterprise-grade security analytics with sub-second query latency is redrawing competitive boundaries in log management software. Splunk leverages its proprietary data processing engine to dominate high-complexity security operations centers. IBM anchors its position through deep integration with hybrid cloud infrastructure and governance tooling. Datadog competes by extending observability into log streams alongside its metrics and tracing stack.
Log management software collects, indexes, and analyzes machine-generated event data from servers, applications, and network devices, typically processing terabyte-scale daily ingest with structured and unstructured query support. Its primary purpose is enabling real-time threat detection, forensic investigation, and compliance attestation across distributed IT estates. Cloud-based deployment now captures the fastest expansion as organizations retire capital-intensive on-premise log repositories. Security analytics commands the deepest margin pools among solution types, driven by managed security service providers bundling advanced detection logic. Banking and finance end users generate the most intensive demand, fueled by transaction audit mandates and fraud investigation workloads.
FDA 21 CFR Part 11, EU GDPR, and India's IT Act collectively shape product roadmaps by mandating immutable audit trails, data residency controls, and breach notification automation. HIPAA in the United States and PCI-DSS globally enforce encryption standards and access logging that directly determine feature certification requirements. Stakeholders must weigh sovereign cloud deployments against vendor consolidation as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Cloud-native observability pipelines are compressing deployment cycles and collapsing the traditional distinction between log management, metrics, and tracing infrastructure. Elastic consumption models now dominate procurement conversations as enterprises retire fixed-capacity on-premise repositories.
Growth Catalysts
- GDPR audit mandates:EU data protection rules require immutable retention of access logs for breach investigations. Financial institutions in Germany and France are expanding platform deployments to satisfy supervisory authority examinations.
- Serverless architecture proliferation:Ephemeral compute functions generate exponentially more discrete events than virtual machines. Engineering teams require automated log aggregation to maintain visibility across distributed microservices.
- India's digital infrastructure investment:Data localization requirements under the IT Act are accelerating sovereign cloud procurement. Domestic banks and payment processors are building captive log repositories to satisfy RBI compliance timelines.
Market Restraints
- Storage cost volatility:Hot-tier cloud object storage pricing fluctuates with hyperscaler capacity investments. Enterprises face unpredictable egress charges when querying historical terabyte-scale datasets.
- Hyperscaler concentration:Three cloud providers control the majority of managed log infrastructure. Regional outages or pricing harmonization create systemic dependency risks for downstream buyers.
- Query latency limitations:Sub-second analytical response requires specialized indexing engines. Standard open-source alternatives fail to meet security operations center performance thresholds without significant engineering investment.
Strategic Opportunities
- Brazilian financial modernization:PIX instant payment system expansion generates massive transaction audit trails. Local banks lack indigenous platforms capable of real-time fraud correlation at national scale.
- AI-assisted anomaly detection:Large language models are converging with structured log schemas. Early deployments demonstrate automated root-cause identification without predefined correlation rules.
- Edge computing telemetry:Manufacturing and energy facilities are deploying lightweight log forwarders. These distributed collectors bypass centralized ingestion bottlenecks while preserving compliance attestation.
Industry Challenges
- Observability engineering talent scarcity:Organizations struggle to hire specialists fluent in OpenTelemetry instrumentation, query optimization, and cost governance. Compensation premiums for these hybrid skill sets are compressing project margins.
- Legacy SIEM integration complexity:Decades-old correlation engines persist in regulated industries. Migration to modern pipelines requires maintaining dual-write architectures during extended transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Log Management Software Market |
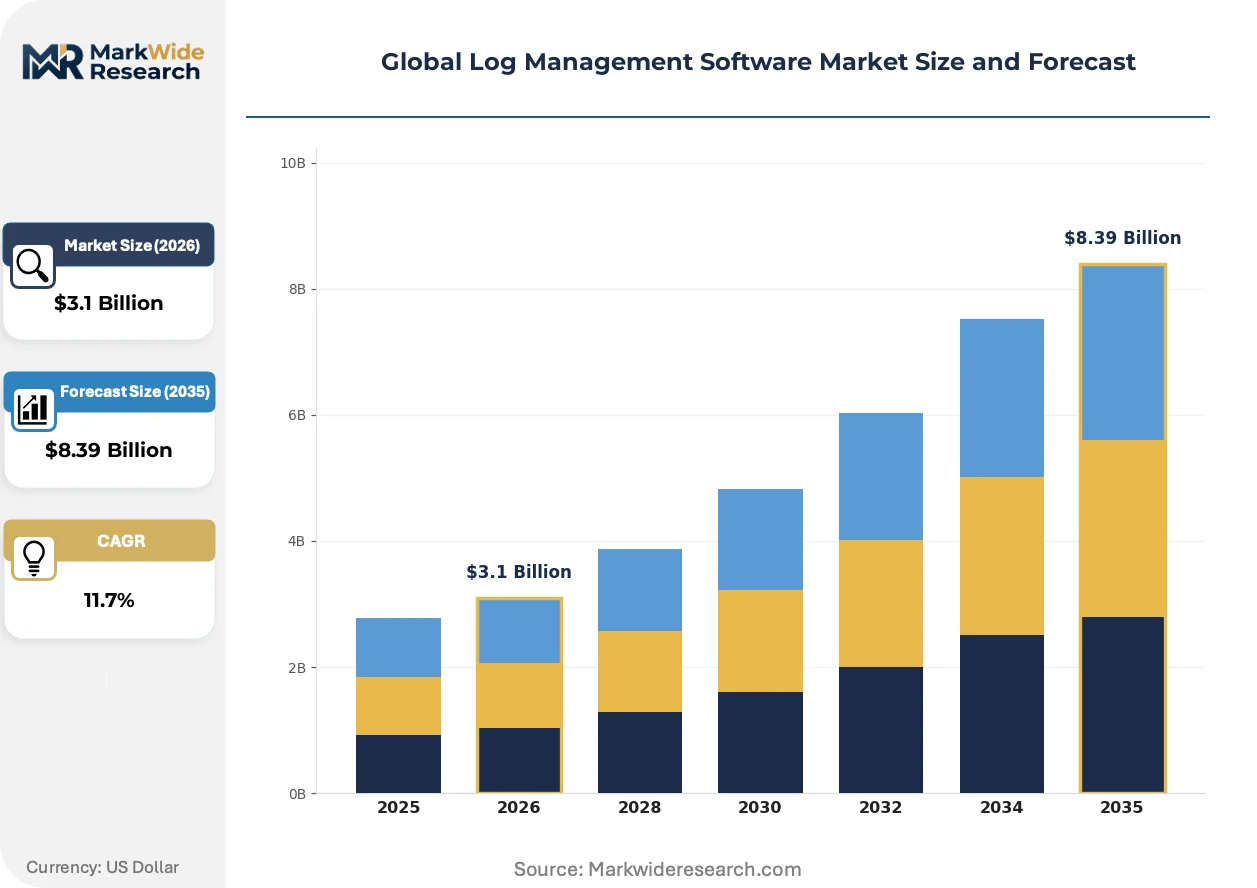
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Solution Type: Log Analysis, Real-Time Monitoring, Event Correlation, Compliance Management, Security Analytics Use Case: Threat Detection, Performance Optimization, Operational Troubleshooting, Audit & Compliance, Capacity Planning End User Industry: Telecommunications, Banking & Finance, Manufacturing, Government, Media & Entertainment |
| Companies Covered | Splunk, IBM, Datadog, SolarWinds, LogRhythm, Sumo Logic, Elastic, Micro Focus, Alert Logic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Log Management Software Market Shifts & Advancements
Stream-native processing architectures are eliminating batch-oriented indexing delays. Vendors are racing to embed machine learning inference directly at the collection layer before data reaches persistent storage.
OpenTelemetry is supplanting proprietary agent ecosystems as the dominant instrumentation standard. Cloud-native enterprises in the United States are mandating OTLP-compliant telemetry pipelines for all new service deployments. This standardization is compressing vendor lock-in and enabling portable observability stacks across hybrid environments.
EU AI Act risk classification rules are reshaping log retention policies for automated decision systems. Financial services algorithms classified as high-risk must maintain complete audit trails for model training, inference, and override events. German automotive lenders and Dutch credit scorers are reconfiguring data pipelines to satisfy conformity assessment body documentation requirements.
Consumption-based pricing is displacing perpetual license models across enterprise procurement. Security operations teams in India and Singapore are negotiating commit-based contracts with burst capacity allowances. This flexibility accommodates unpredictable incident response volumes without permanent infrastructure overprovisioning.
Global Log Management Software Market Segmentation
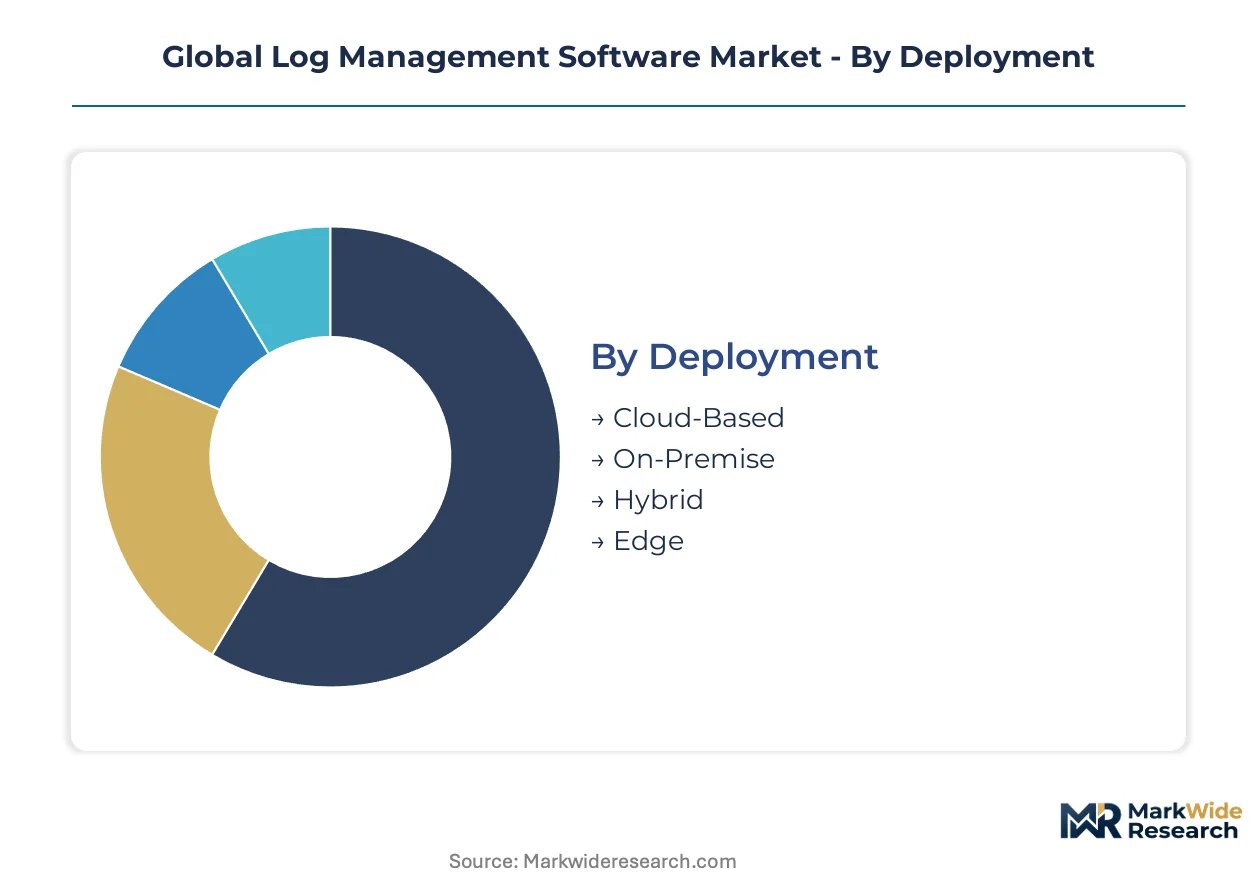
Log management software segmentation reveals how deployment economics, solution complexity, and regulatory pressure fragment purchasing decisions across enterprise buyers. Understanding these divisions exposes where vendors command pricing power and where procurement commoditizes.
Deployment:
Margin pools concentrate in consumption-based cloud arrangements where vendor-managed infrastructure eliminates capital expenditure approval cycles.
- Cloud-Based:Fully managed SaaS platforms handle ingestion, indexing, and query processing through hyperscaler infrastructure. German automotive manufacturers and Indian payment processors are migrating legacy on-premise repositories to satisfy data localization mandates without building captive data centers.
- On-Premise:Self-hosted deployments retain dedicated hardware for air-gapped environments or stringent data residency requirements. United States defense contractors and classified government facilities maintain these installations despite higher total cost of ownership.
- Hybrid:Split architectures route sensitive logs to private infrastructure while pushing operational telemetry to cloud tiers. Financial services firms in Singapore use this model to balance RBI compliance timelines with elastic burst capacity.
- Edge:Lightweight collectors forward filtered telemetry from distributed manufacturing floors, energy substations, and retail locations. These deployments bypass centralized ingestion bottlenecks while preserving immutable audit trails for FDA-regulated production environments.
The dominant share belongs to Cloud-Based, while Edge is closing the gap fastest.
Solution Type:
Commercial intensity varies by analytical sophistication, with predictive capabilities commanding premium pricing over passive storage.
- Security Analytics:Machine learning inference engines detect anomalous access patterns and lateral movement across distributed estates. Managed security service providers bundle these capabilities for mid-market buyers lacking in-house threat hunting expertise.
- Log Analysis:Structured query interfaces enable forensic investigation across historical datasets with full-text search and field extraction. This foundational capability supports GDPR breach investigations and PCI-DSS audit responses.
- Real-Time Monitoring:Sub-second alerting pipelines trigger automated responses to infrastructure failures or security incidents. DevOps teams in telecommunications deploy these for service-level agreement enforcement.
- Event Correlation:Rule engines and statistical models link discrete log entries into multi-stage attack narratives or system degradation chains.
- Compliance Management:Pre-built reporting templates map log retention policies to HIPAA, FDA 21 CFR Part 11, and EU AI Act documentation requirements.
Security Analytics holds the revenue concentration, though Compliance Management is expanding most quickly under regulatory fragmentation.
Use Case:
Procurement authority shifts between security operations, platform engineering, and governance functions depending on primary use case.
- Threat Detection:Continuous monitoring identifies indicators of compromise across endpoints, networks, and cloud workloads. Security operations centers in United States healthcare systems prioritize these investments following HHS breach notification enforcement.
- Audit & Compliance:Immutable log chains demonstrate control effectiveness to supervisory authorities and external auditors. German banks under BaFin supervision maintain these capabilities for transaction reconstruction mandates.
- Performance Optimization:Latency analysis and resource utilization trending guide capacity planning decisions.
- Operational Troubleshooting:Root-cause identification across microservices dependencies accelerates incident resolution.
- Capacity Planning:Historical ingestion rates forecast storage scaling requirements and license renewal negotiations.
Threat Detection commands the largest committed spend, while Audit & Compliance shows the steepest expansion trajectory.
End User Industry:
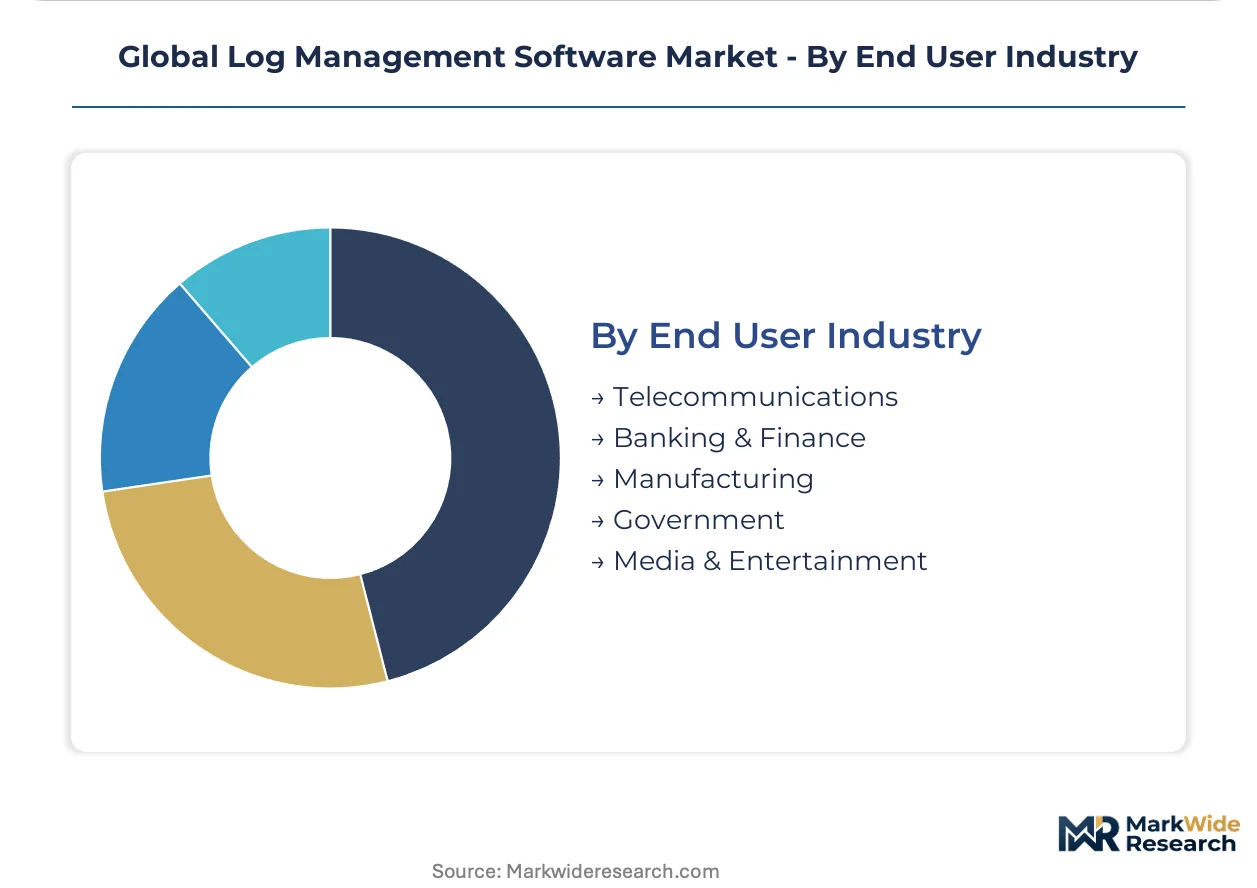
Data sovereignty rules and transaction volume intensity create divergent procurement patterns across verticals.
- Banking & Finance:Real-time fraud correlation and transaction audit trails dominate procurement specifications. India's PIX instant payment system expansion drives sovereign cloud repository investments at domestic banks.
- Government:Classified and unclassified networks require separate logging architectures with distinct clearance handling procedures. United States federal agencies align deployments to FedRAMP authorization boundaries.
- Telecommunications:Subscriber metadata retention and lawful intercept compliance shape technical requirements.
- Manufacturing:Industrial control system telemetry and FDA-validated batch records drive specialized edge collector deployments.
- Media & Entertainment:Content delivery network performance monitoring and digital rights management audit trails define use cases.
Banking & Finance retains the deepest wallet share, with Government procurement cycles accelerating fastest under cyber-hardening mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler infrastructure investments concentrate in the United States, Germany, and India, where data sovereignty enforcement and financial sector digitization are compressing procurement timelines. Regulatory fragmentation across jurisdictions is forcing vendors to architect region-specific deployment templates rather than uniform global stacks.
United States
Federal cyber-hardening mandates and healthcare breach notification enforcement drive security analytics procurement. HHS and SEC audit requirements compel financial institutions and hospital systems to maintain immutable log chains. Silicon Valley cloud-native enterprises and New York financial services firms anchor domestic demand for sub-second query latency platforms.
Germany
BaFin transaction reconstruction mandates and EU AI Act high-risk algorithm documentation rules reshape data pipeline architectures. Automotive lenders in Stuttgart and credit scorers in Frankfurt reconfigure retention policies to satisfy conformity assessment body requirements. Bavarian manufacturing clusters deploy edge collectors for FDA-validated batch record compliance.
India
Data localization under the IT Act and RBI compliance timelines accelerate sovereign cloud repository construction. Domestic banks building captive log infrastructure to support PIX instant payment system audit trails concentrate procurement in Mumbai and Bangalore. Payment processors in Hyderabad invest in elastic burst capacity for unpredictable fraud investigation volumes.
United Kingdom
FCA operational resilience requirements and post-Brexit data adequacy negotiations drive hybrid deployment decisions. London financial services firms split sensitive transaction logs to private infrastructure while pushing operational telemetry to cloud tiers. Edinburgh fintech clusters and Manchester insurance operations prioritize GDPR-aligned breach notification automation.
Japan
METI digital infrastructure subsidies and Financial Services Agency cybersecurity guidelines expand managed security service provider adoption. Tokyo banking consortia and Osaka manufacturing networks invest in OpenTelemetry-compliant pipelines for legacy SIEM migration. Nagoya automotive electronics suppliers embed lightweight log forwarders for supply chain visibility.
Global Log Management Software Market Competitive Landscape
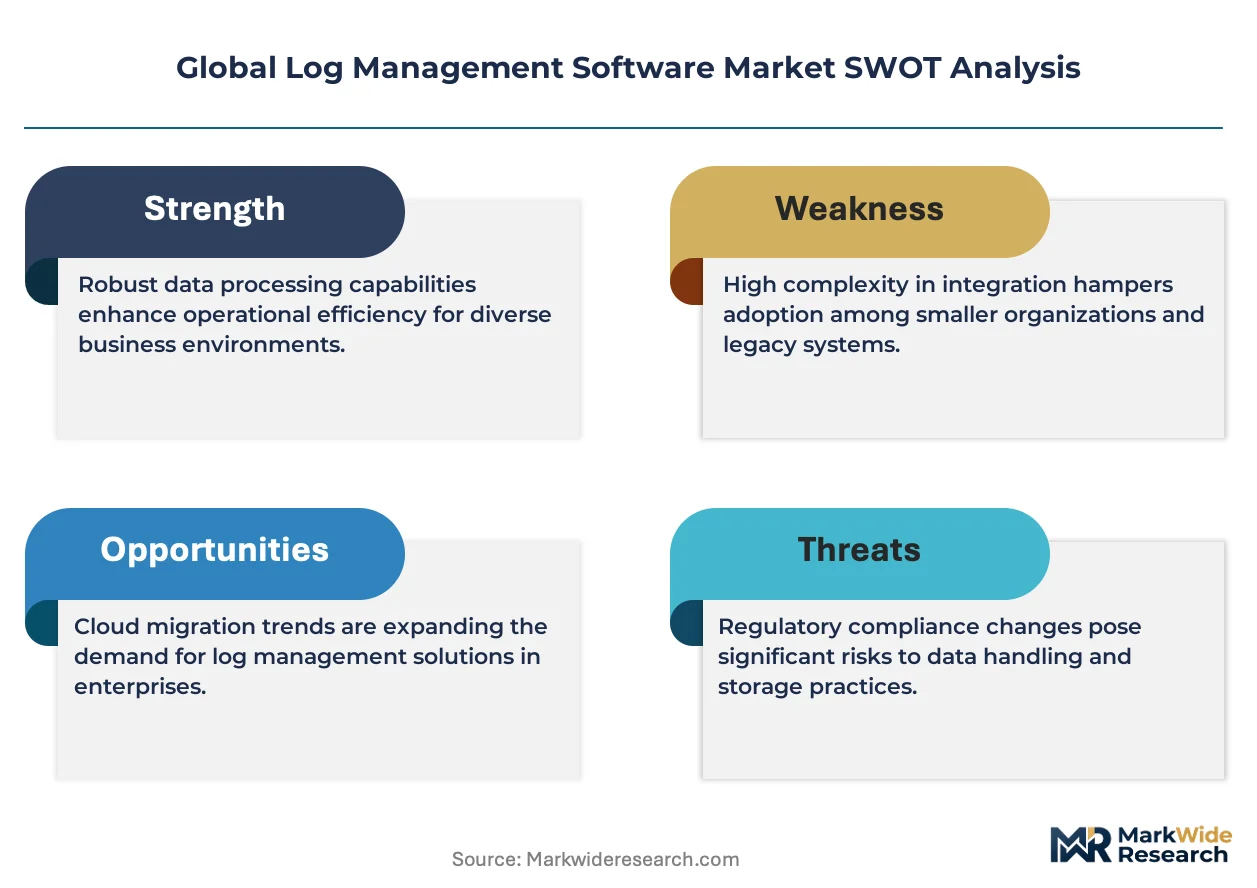
Concentration sits with full-stack observability platforms and specialized security analytics vendors competing for enterprise wallet share. The vendor landscape fragments across three tiers: hyperscaler-native services, independent software vendors with proprietary indexing engines, and open-source-backed commercial distributions. Dominant competitive moves include strategic partnerships with managed security service providers and geographic expansion through sovereign cloud certifications.
Within the full-stack observability tier, Splunk, Datadog, and Elastic represent contrasting architectural philosophies. Splunk anchors high-complexity security operations center deployments through its proprietary data processing heritage. Datadog exemplifies metrics-tracing-logs convergence for cloud-native engineering teams. Elastic occupies a position as the open-source-backed alternative with portable deployment patterns across hybrid environments.
| Leading Market Players |
|---|
| Splunk |
| IBM |
| Datadog |
| SolarWinds |
| LogRhythm |
| Sumo Logic |
| Elastic |
| Micro Focus |
| Alert Logic |
| Others |
Supply & Pricing Matrix
Ninety-day implementation cycles for cloud-native deployments concentrate pricing power with vendors possessing FedRAMP and sovereign cloud certifications, while hyperscaler storage cost volatility feeds back into buyer procurement preferences for commit-based contracts with burst allowances. This interdependence between deployment velocity and infrastructure sourcing shapes margin structures across the competitive landscape.
Pricing Analysis
GDPR and PCI-DSS dictate the pricing tier structure across the market, with three-tier pricing stratifying across premium security analytics, standard log analysis, and economy-grade retention tiers. Certification grade and query latency performance anchor price differentiation, with sub-second analytical engines commanding substantial premiums over open-source alternatives. Cost compression in economy retention tiers is intensifying because hyperscaler storage pricing harmonization erodes vendor margin buffers. Mid-market financial services firms exhibit the highest price sensitivity, while United States defense contractors and German automotive manufacturers under BaFin supervision demonstrate the lowest.
Supply Chain Analysis
Just-in-time provisioning dominates cloud-native deployments, though strategic stockpiling of reserved compute capacity secures preferential pricing for high-volume Indian payment processors and German banking consortia. Infrastructure supply concentrates in the United States, Germany, and India, where hyperscaler regions and sovereign cloud certifications anchor vendor operations. The supply chain draws from specialized indexing engine development, GPU inference clusters, and OpenTelemetry instrumentation libraries. Single-source vulnerability around hyperscaler concentration creates systemic dependency risks. Distribution runs through direct enterprise sales, managed security service provider bundling, and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OpenTelemetry standardization is collapsing proprietary agent ecosystems into platform-commodity layers, creating a platform-economics inflection where interoperability investments determine long-term competitive viability. This shift rewards vendors embedding inference capabilities at the collection layer before persistent storage.
For Market Incumbents: Secure sovereign cloud certifications in India and Germany to defend against regional challengers exploiting data localization mandates under the IT Act and EU AI Act. Deepen backward integration into GPU inference infrastructure to reduce dependency on hyperscaler pricing harmonization. Prioritize OpenTelemetry-native pipeline development to neutralize vendor lock-in threats from cloud-native entrants. For New Entrants and Emerging Players: Anchor in Brazilian financial modernization, where PIX instant payment system expansion has outpaced indigenous platform capabilities for real-time fraud correlation. Target mid-market managed security service providers in Singapore and Hyderabad lacking in-house threat hunting expertise. Pursue consumption-based pricing with burst capacity allowances to differentiate from incumbent perpetual license incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a data-sovereignty infrastructure play because regulatory fragmentation across GDPR, EU AI Act, and India's IT Act is fragmenting global deployments into region-specific stacks. Acquisition candidates should demonstrate FedRAMP or RBI compliance timelines and OpenTelemetry-native architectures. Watch hyperscaler capex disclosure trends as the signal indicating whether cloud-native compression accelerates or reverses.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | OpenTelemetry compliance enables portable observability stacks across hybrid environments for German automotive manufacturers. |
| Sovereign Cloud Certification | FedRAMP and RBI authorizations unlock United States federal and Indian banking procurement cycles. |
| Acquisition of Specialist Firm | Edge collector capabilities address FDA-validated batch record requirements for Bavarian manufacturing clusters. |
| Strategic Partnership | Managed security service provider bundling extends reach to mid-market buyers lacking threat hunting expertise. |
| Geographic Expansion | Brazilian PIX payment system expansion creates demand for real-time fraud correlation at national scale. |
Research Methodology
Operator-level perspectives from security operations center directors, platform engineering leads, compliance officers at financial institutions, and managed security service provider executives anchored the qualitative base. These primary insights combined with secondary validation from SEC filings, hyperscaler capex disclosures, FedRAMP authorization databases, and RBI circulars. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates.
Sensitivity analysis tested forecast robustness across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs derived from segment-level growth rate reconciliation against macro infrastructure investment indicators. Inputs included serverless architecture proliferation rates, data localization enforcement intensity, and OpenTelemetry adoption curves across the analysis window.
Decision-makers should treat outputs as directional under assumptions of continued hyperscaler infrastructure investment and regulatory fragmentation; material deviation would warrant model refresh. Revision becomes warranted when hyperscaler concentration risk or sovereign cloud procurement acceleration crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Language Translation Software Market
Software & Services
Full Screen Website Screenshot Software Market
Software & Services
Anti-Plagiarism Software Market
Software & Services
Video Editing Software Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Communication Software Market
Software & Services
Airline Route Profitability Software Market
Software & Services
Machine Translation Software Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Data Integration Software Market
Software & Services
Employee Engagement Solutions Market
Software & Services
Global Cloud Enterprise Resource Planning Market
Software & Services
Global Affiliate Software Market
Software & Services
Global Offshore Software Development Market
Software & Services
Testing As a Service (Taas) Market
Software & Services
Global Appointment Reminder Software Market