
 Encryption Software Market | 2026-2036
Encryption Software Market Size, Share, and Industry Trends Forecast 2026-2036
Encryption Software Market Intelligence
North American cybersecurity vendor capacity is restructuring around post-quantum cryptography readiness and federal compliance requirements. Proofpoint leverages cloud-native delivery to sustain enterprise email encryption dominance. Virtru anchors healthcare and government workflows with client-side encryption architectures. Arqit competes through quantum-safe key distribution technology for satellite and defense channels.
Encryption software applies mathematical algorithms to render data unintelligible without authorized decryption keys, typically using AES-256 or RSA-4096 standards for symmetric and asymmetric operations. Its primary purpose is to enforce confidentiality, integrity, and non-repudiation across data at rest, in transit, and in use. Cloud-based deployment is capturing the fastest expansion as enterprises abandon capital-intensive on-premises key management. File encryption solutions lead absolute revenue within the solution category due to remote workforce proliferation and endpoint data sprawl. Large enterprises remain the deepest customer type segment, though SMEs are narrowing the gap through managed encryption services.
FDA mandates for healthcare data protection, FCC requirements for telecommunications subscriber privacy, and SEC cybersecurity disclosure rules are collectively elevating encryption from optional safeguard to audit-critical infrastructure. The EU AI Act and GDPR impose algorithmic transparency and cross-border data transfer constraints that vendors must architect around. Stakeholders should monitor NIST post-quantum standard finalization timelines and corresponding procurement clause revisions across federal and enterprise buyers.
Market Dynamics
Post-quantum cryptographic migration is restructuring procurement priorities across federal and enterprise buyers, compressing replacement cycles for legacy asymmetric infrastructure and elevating NIST algorithm validation to contract-critical status.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for high-risk AI systems are forcing enterprises to encrypt training data and model weights, expanding addressable demand in member states.
- Financial services payment data protection:PCI-DSS 4.0 and open banking APIs are requiring end-to-end encryption for transaction flows, with card networks mandating hardware security module integration.
- Healthcare data breach penalties:HIPAA enforcement actions and state-level notification laws are converting encryption from recommended practice to liability-mitigation infrastructure for hospital systems.
Market Restraints
- Specialized cryptographic talent scarcity:Shortages of engineers with post-quantum mathematics and side-channel attack expertise are inflating implementation costs and extending deployment timelines.
- Key management infrastructure concentration:Cloud hardware security module services from three dominant providers create single-point-of-failure risks for enterprise key escrow operations.
- Legacy system interoperability friction:PKCS#11 and KMIP standard gaps between on-premises hardware and cloud-native services force expensive middleware development for hybrid environments.
Strategic Opportunities
- India BIS data localization mandates:Requirements for domestic encryption key storage are opening greenfield deployment opportunities for localized key management infrastructure.
- Confidential computing convergence:Integration of memory encryption with trusted execution environments is enabling new use cases in multi-tenant cloud analytics and federated machine learning.
- Japan METI critical infrastructure standards:Updated cybersecurity framework requirements for energy and transportation operators are mandating quantum-resistant key exchange protocols.
Industry Challenges
- FIPS 140-3 certification timelines:Laboratory backlogs and evolving post-quantum test requirements are delaying product launches by 18-24 months for hardware-dependent solutions.
- Homomorphic encryption performance constraints:Computational overhead of privacy-preserving computation remains prohibitive for real-time analytics workloads, limiting commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Encryption Software Market |
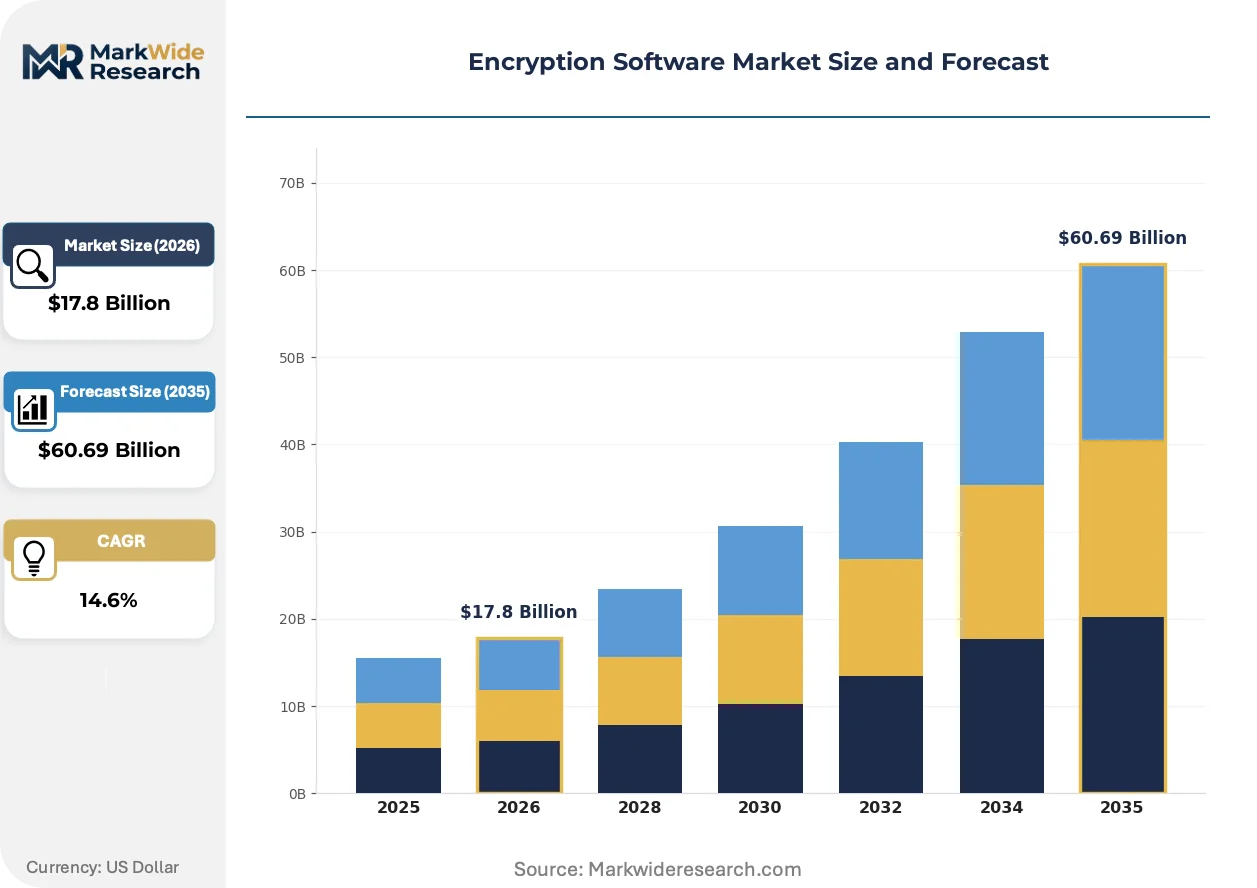
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $60.69 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, Managed Services Solution: End-to-end Encryption, Database Encryption, File Encryption, Disk Encryption Customer Type: SMEs, Large Enterprises, Government, Individual Users Industry Vertical: Financial Services, Healthcare, Retail, Telecommunications |
| Companies Covered | Virtru, Mimecast, Proton, AxCrypt, Barracuda, Arqit, Proofpoint, Sectigo, Egnyte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encryption Software Market Strategic Shifts & Innovations
Encryption architectures are fragmenting across deployment models, with cloud-native key services, confidential computing enclaves, and quantum-resistant algorithms competing for capital allocation and engineering priority.
Confidential computing is modularizing data protection by embedding encryption within processor-isolated execution environments. Financial institutions processing cross-border payments are adopting Intel SGX and AMD SEV technologies to minimize data exposure during transaction validation. This hardware-backed approach is compressing demand for traditional application-layer encryption in latency-sensitive workloads.
The EU AI Act and GDPR cross-border data transfer mechanisms are forcing architectural redesigns for machine learning pipelines. Organizations training models on EU citizen data must implement encryption with technical measures ensuring third-country access limitations. Healthcare AI developers in Germany and France are restructuring cloud contracts to satisfy Schrems II compliance requirements.
Consumption patterns in enterprise encryption are pivoting toward subscription-based key management services. Perpetual license models for on-premises hardware security modules are losing share to consumption-billed cloud alternatives. This shift is most pronounced among mid-market SaaS providers in the United States seeking to defer capital expenditure while scaling cryptographic operations.
Encryption Software Market Segmentation
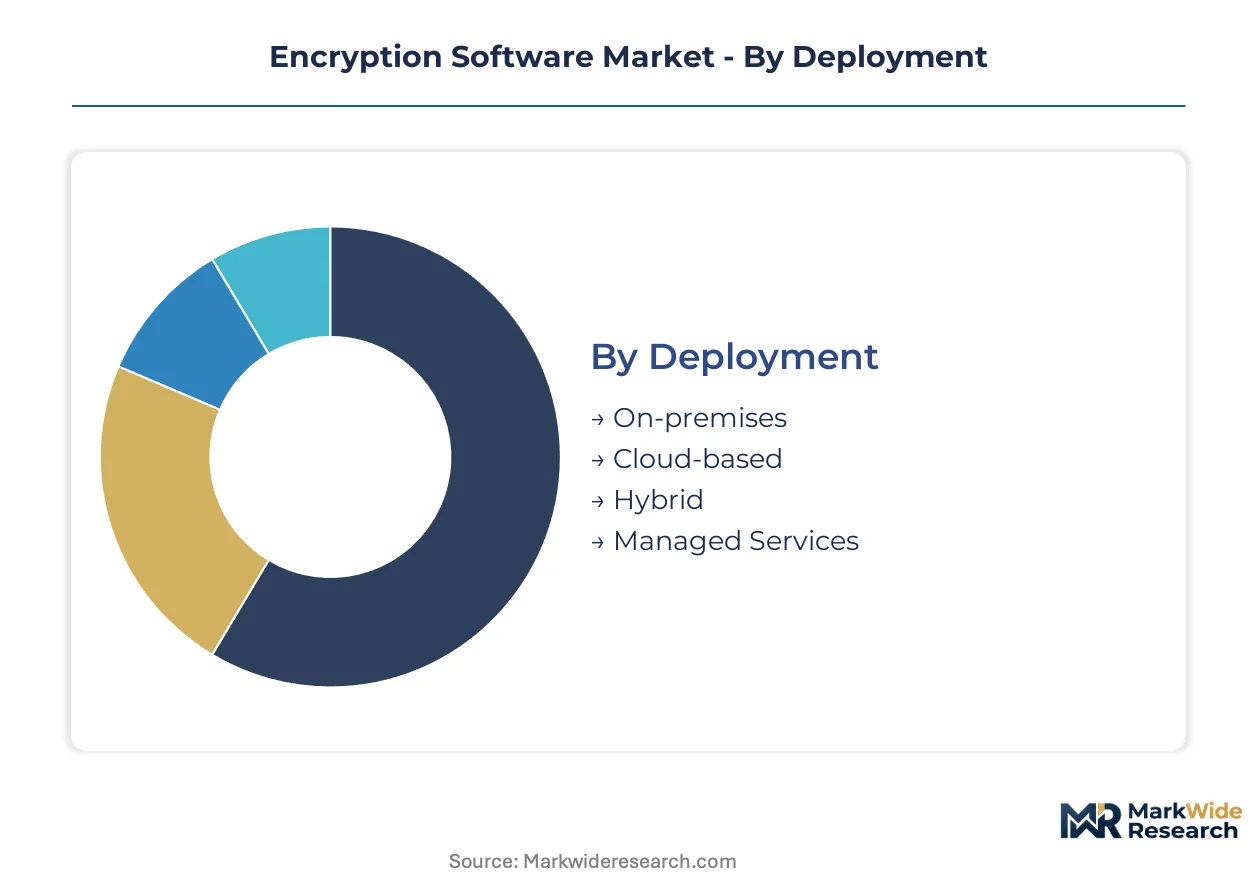
Encryption software segmentation reveals how deployment architectures, solution types, and customer profiles reshape procurement patterns. Vendors must align product roadmaps with the technical specifications and compliance requirements that dominate each category.
Deployment:
Architectural choices determine capital intensity, operational control, and regulatory auditability for encryption infrastructure.
- Cloud-based:Consumption-billed key management services eliminate hardware procurement cycles. Demand concentrates among mid-market SaaS providers in the United States seeking to defer capital expenditure while scaling cryptographic operations.
- On-premises:Hardware security modules and internal key escrow systems retain dominance where data sovereignty mandates apply. Financial institutions in Germany maintain on-premises infrastructure to satisfy BaFin supervisory requirements for payment data custody.
- Hybrid:Split architectures route sensitive workloads to on-premises HSMs while pushing bulk encryption to cloud services. Retail enterprises adopt hybrid models to isolate PCI-DSS cardholder data environments from cloud analytics pipelines.
- Managed Services:Outsourced key lifecycle operations reduce staffing burdens for organizations lacking cryptographic expertise. Healthcare systems deploy managed encryption to address HIPAA technical safeguard requirements without expanding security headcount.
Cloud-based deployment leads on scale; managed services leads on momentum.
Solution:
Functional scope defines which data states—at rest, in transit, or in use—receive cryptographic protection.
- File Encryption:Endpoint-focused solutions protect documents, spreadsheets, and media files against unauthorized access. Remote workforce proliferation and endpoint data sprawl drive revenue concentration in this segment across technology and professional services firms.
- End-to-end Encryption:Communication-layer cryptography ensures only sender and recipient possess decryption capabilities. Messaging platforms and email systems implement this standard to satisfy GDPR data protection requirements for EU citizen communications.
- Database Encryption:Transparent data encryption and column-level protection secure structured information repositories. Financial services firms deploy database encryption to meet PCI-DSS 4.0 mandates for stored payment card data.
- Disk Encryption:Full-volume cryptography protects data on laptops, servers, and removable media against physical theft. Government agencies mandate disk encryption for all mobile devices processing classified or controlled unclassified information.
File encryption leads on scale; end-to-end encryption leads on momentum.
Customer Type:
Organizational scale and sector affiliation dictate procurement sophistication and compliance exposure.
- Large Enterprises:Dedicated security teams negotiate custom encryption architectures with integrated key management. Multinational manufacturers in Japan deploy enterprise-wide encryption to satisfy METI critical infrastructure cybersecurity standards.
- SMEs:Subscription-based managed services narrow the capability gap with larger organizations. Regional healthcare clinics adopt SME-targeted encryption to address state-level breach notification laws without enterprise-scale budgets.
- Government:FIPS 140-3 certification and NIST algorithm compliance dominate procurement evaluation. Federal agencies require quantum-resistant key exchange protocols for systems processing sensitive but unclassified information.
- Individual Users:Consumer-grade encryption protects personal files, communications, and device backups. Privacy-conscious professionals adopt individual encryption tools following high-profile data breach disclosures.
Large enterprises lead on scale; SMEs lead on momentum.
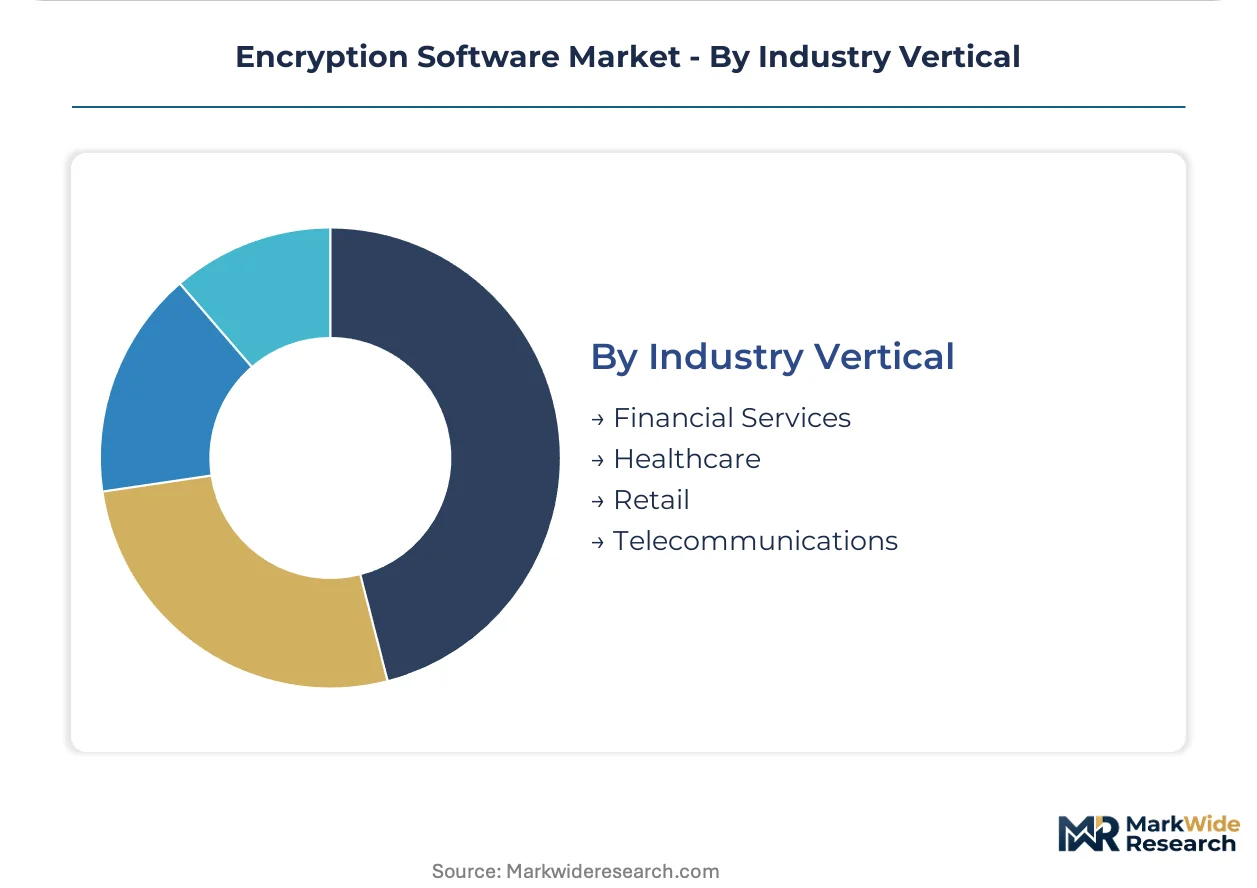
Industry Vertical:
Sector-specific regulatory frameworks and threat models shape encryption requirements and deployment urgency.
- Financial Services:Payment data protection mandates from card networks and banking regulators drive comprehensive encryption deployment. Open banking APIs require end-to-end encryption for transaction flows between institutions and third-party providers.
- Healthcare:HIPAA enforcement actions and FDA medical device cybersecurity guidance elevate encryption from recommended practice to liability-mitigation infrastructure. Hospital systems encrypt patient records, diagnostic images, and connected device communications.
- Telecommunications:FCC subscriber privacy rules and lawful intercept requirements create complex encryption obligations. Carriers implement lawful access mechanisms while protecting metadata and content against unauthorized surveillance.
- Retail:PCI-DSS compliance and e-commerce fraud prevention motivate point-to-point encryption for payment terminals. Merchants encrypt customer databases and loyalty program records to limit breach exposure.
Financial services leads on scale; healthcare leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping encryption software deployment as enterprises relocate data infrastructure to jurisdictions with clearer compliance cost structures. The EU AI Act and GDPR impose stringent cross-border transfer rules that inflate operational expenses for US-headquartered cloud providers. Germany, Japan, and India are capturing migration flows through localized key custody mandates and domestic certification pathways.
United States
Federal procurement rules and SEC cybersecurity disclosure requirements are accelerating post-quantum readiness investments. NIST algorithm standardization timelines dictate federal agency upgrade schedules. Silicon Valley cloud providers and Washington DC defense contractors dominate quantum-safe key distribution development.
Germany
BaFin supervisory requirements for payment data custody and EU AI Act algorithmic transparency mandates are compressing deployment timelines. Automotive manufacturers in Bavaria and industrial automation firms in Baden-Württemberg are upgrading cryptographic infrastructure for connected vehicle platforms.
Japan
METI critical infrastructure cybersecurity standards for energy and transportation operators mandate quantum-resistant protocols. Tokyo financial institutions and Osaka manufacturing clusters are integrating hardware security modules with cloud-native key services to satisfy cross-border data localization expectations.
India
BIS data localization requirements for domestic encryption key storage are opening greenfield deployment opportunities. Bengaluru SaaS providers and Mumbai financial services firms are restructuring cloud contracts to satisfy RBI payment data protection mandates while scaling managed encryption services.
United Kingdom
Post-Brexit divergence from EU GDPR enforcement patterns is creating compliance uncertainty for multinational enterprises. London financial services firms and Cambridge cybersecurity clusters are maintaining dual-certification strategies to preserve EU market access while adapting to UK-specific regulatory interpretations.
Encryption Software Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue quantum-safe specializations and confidential computing integration. The vendor base stratifies across three maturity tiers: legacy email encryption incumbents, cloud-native key management platforms, and post-quantum cryptography pioneers. Dominant competitive moves include strategic partnerships with hardware security module manufacturers and portfolio diversification into managed detection and response services.
Within the cloud-native tier, Proofpoint and Virtru exemplify divergent architectural approaches to enterprise data protection. Arqit occupies a distinct position among quantum-safe specialists targeting satellite and defense communication channels. These three entities represent the competitive spectrum from mass-market SaaS delivery to niche hardware-backed key distribution systems.
| Leading Market Players |
|---|
| Virtru |
| Mimecast |
| Proton |
| AxCrypt |
| Barracuda |
| Arqit |
| Proofpoint |
| Sectigo |
| Egnyte |
| Others |
Cost & Logistics Intelligence
FIPS 140-3 certification timelines gate qualified supply for encryption hardware vendors and anchor premium-tier pricing for validated modules. Federal procurement clauses and healthcare compliance mandates restrict vendor eligibility to certified producers, compressing competitive supply while sustaining price premiums for audit-ready solutions.
Pricing Analysis
Direct-to-enterprise discounts dominate cloud-native key management services, displacing traditional distributor-mediated hardware sales. Three-tier pricing structure across premium, standard, and economy levels separates FIPS-validated HSMs from managed services and open-source alternatives. Price differentiation hinges on certification grade and after-sales support bundling. Cost compression in standard-tier SaaS subscriptions is intensifying because hyperscaler economies of scale depress per-key costs. SMEs exhibit highest price sensitivity; defense contractors and regulated financial institutions show lowest.
Supply Chain Analysis
Reverse-logistics flows for hardware security module refurbishment concentrate in Taiwan, Germany, and the United States, extending equipment lifecycles for cost-conscious enterprises. Semiconductor fabrication for cryptographic processors draws from Taiwan, South Korea, and Israel. Raw material dependencies include silicon wafers, rare-earth magnets for tamper-evident enclosures, and specialized ASIC designs. Single-source vulnerability in TSMC's advanced node production creates supply chain risk for quantum-resistant chipsets. Distribution runs through value-added resellers with compliance consulting capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encryption software margins expand through cloud-native delivery economics and post-quantum premium-tier migrations. Subscription billing models convert capital expenditure into recurring revenue while NIST algorithm validation sustains pricing power.
For Market Incumbents: Cement cloud-native key management dominance by acquiring regional managed service providers with healthcare and government certifications. Deepen post-quantum cryptography R&D to preempt emerging entrant specialization in quantum-safe algorithms. Channel control through exclusive HSM manufacturer partnerships protects against margin erosion from commodity key services.
For New Entrants and Emerging Players: Begin with confidential computing integration for multi-tenant analytics workloads, the most penetrable segment where Intel SGX and AMD SEV adoption outpaces incumbent platform coverage. Target mid-market SaaS providers in India seeking BIS-compliant localized key custody without enterprise-scale infrastructure investment. Go-to-market through hyperscaler marketplace listings with consumption-based trial tiers.
For Investors and Strategic Acquirers: Roll-up economics work for regional managed encryption services because regulatory fragmentation across EU member states, India, and Japan prevents single-vendor global scale. Long-term viability centers on post-quantum migration services and confidential computing platform integration. Watch NIST post-quantum standard finalization timelines as the inflection signal for federal procurement clause revisions and corresponding enterprise replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Certification | FIPS 140-3 validation for NIST algorithms unlocks federal agency procurement pipelines. |
| Confidential Computing Platform Integration | Intel SGX and AMD SEV partnerships enable hardware-backed encryption for latency-sensitive financial workloads. |
| Geographic Key Localization Infrastructure | India BIS and EU GDPR data residency mandates require domestic HSM deployment for market access. |
| Managed Encryption Service Expansion | Healthcare systems outsource HIPAA technical safeguards without expanding security headcount. |
| Quantum-Safe Satellite Communication Development | Defense and aerospace channels demand quantum-resistant key distribution for orbital assets. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CISOs, cloud platform engineers, healthcare IT directors, and federal procurement officers with secondary validation. Primary sources included CTOs at financial services firms, IT procurement officers at hospital systems, integration specialists at channel partners, and platform engineers at SaaS providers. Secondary data drew from SEC cybersecurity disclosure filings, NIST algorithm standardization documents, FDA medical device guidance, and EU AI Act regulatory texts. Bottom-up deployment estimates and top-down market sizing triangulated to produce segment-level figures.
Segment-weighting approaches distributed value across cloud-based, on-premises, hybrid, and managed service deployment models. Organization size, vertical industry, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs derived from fitted growth curves applied to encrypted data volume projections and compliance-driven replacement cycle assumptions. Post-quantum migration timelines and confidential computing adoption curves served as industry-specific forecast inputs across the analysis window.
Several conditions sit outside the modeled scope, including nation-state cryptographic backdoor mandates, breakthrough advances in cryptanalysis, and abrupt standard abandonment. Forecasts reflect documented assumptions about regulatory enforcement continuity and algorithm standardization schedules. Practitioners should monitor NIST post-quantum standard publication dates and EU AI Act implementation guidance for early signals of procurement priority shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Endpoint Detection and Response Market
Security Software
Network Camera and Video Analytics Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
Identity Governance and Administration Market
Security Software
Certification Authority Market
Security Software
Global Mobile Identification Market
Security Software
Global Log Management Market
Security Software
Anti-Fraud Management System Market
Security Software
Embedded Security Market
Security Software
Anomaly Detection Tools Market
Security Software
Broadcast Censorship Solutions Market
Security Software
Cloud File Security Software Market
Security Software
SSL Inspection Solution Market
Security Software
ATM Security Market
Security Software
Mobile Identity Management Market
Security Software
Enterprise Rights Management Solution Market