
 Parental Monitoring Software Market | 2026-2036
Parental Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Parental Monitoring Software Market Insights
Subscription-based feature tiers is recalibrating how parental monitoring software monetizes ongoing protection rather than one-time licenses. Microsoft Corporation leverages its Azure cloud backbone to anchor enterprise-grade filtering for school districts. NortonLifeLock Inc. competes through bundled cybersecurity-family safety packages that extend consumer trust from antivirus into parental controls. Bark Technologies, Inc. specializes in natural-language processing for suicide-risk detection, differentiating its alert system from simpler keyword blockers.
Parental monitoring software encompasses applications and platforms that supervise, filter, and report on minors' digital interactions across endpoints, typically operating through agent-based screen capture, DNS redirection, or API-level OS integration with real-time dashboard analytics for administrators. The primary commercial purpose centers on liability reduction for educational institutions and anxiety mitigation for caregivers managing multi-device households. Mobile Applications currently dominate volume as smartphone-first parenting spreads, while Cloud Services capture expanding margin pools through recurring revenue and automatic model updates for threat detection. Activity Monitoring features lead enterprise attachment rates because schools require auditable proof of duty-of-care compliance, whereas Location Tracking grows fastest among caregiver segments managing neurodivergent children.
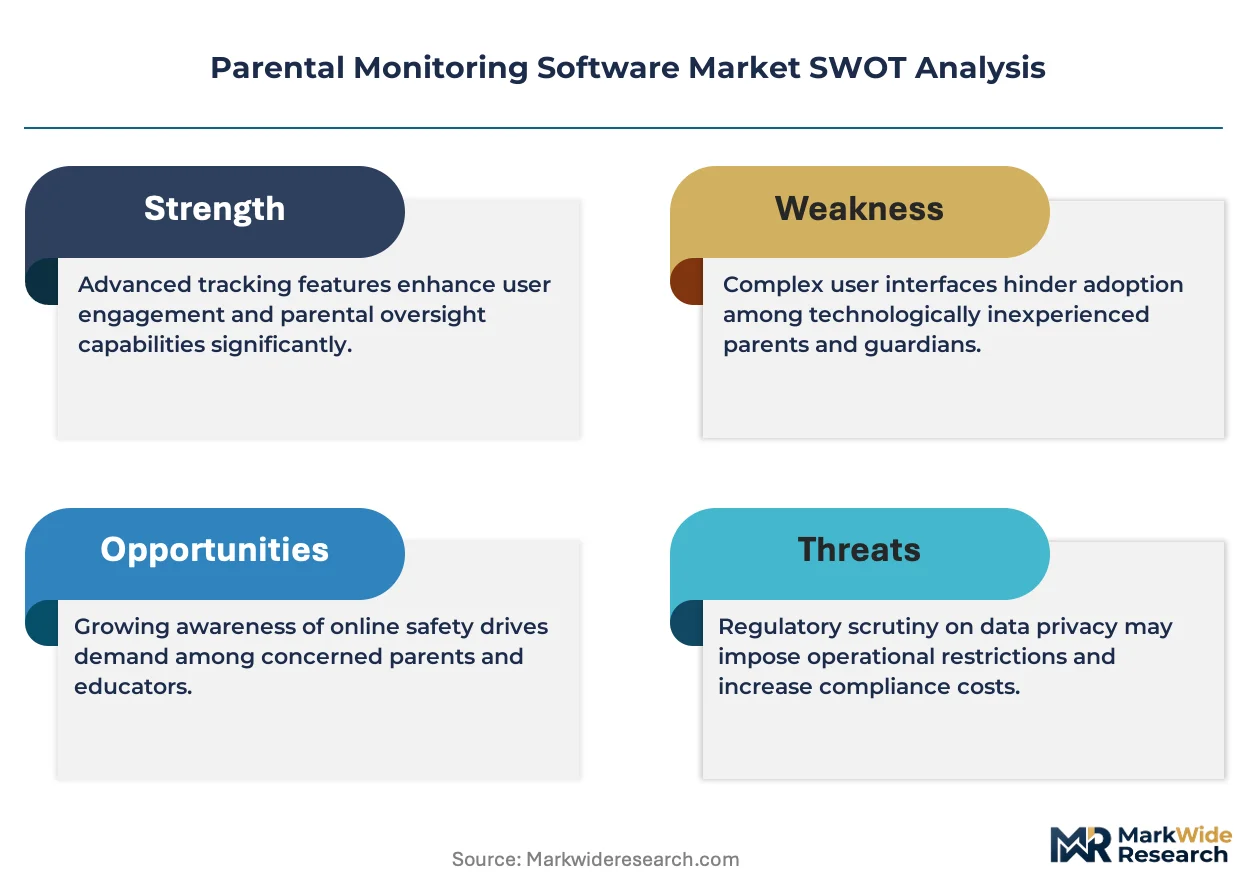
The Children's Online Privacy Protection Act shapes product architecture by restricting data collection from users under thirteen, forcing vendors to purge logs or obtain verifiable parental consent. The Federal Trade Commission enforces deceptive advertising standards around "invisible" monitoring claims, while state legislatures in California and Texas draft biometric consent rules for facial-recognition attendance systems that overlap with monitoring platforms. Stakeholders must track how fragmented state privacy laws will fragment compliance costs and determine whether modular architecture or geographic SKUs prove more sustainable.
Market Dynamics
Subscription-based feature tiers is recalibrating how parental monitoring software monetizes ongoing protection rather than one-time licenses, forcing vendors to architect continuous value delivery through automatic model updates and tiered service levels.
Growth Catalysts
- State-level digital safety mandates:Texas and California have enacted district-level procurement requirements for student device management, accelerating institutional adoption of screen-time analytics platforms.
- API-level OS integration:Deep system hooks into iOS and Android parental control frameworks enable real-time dashboard analytics without VPN latency, improving caregiver retention rates.
- Suicide-risk detection algorithms:Natural-language processing engines trained on crisis intervention datasets differentiate alert systems from rudimentary keyword blockers in school district RFPs.
Market Restraints
- COPPA compliance architecture:The Children's Online Privacy Protection Act forces vendors to purge logs from users under thirteen or obtain verifiable parental consent, inflating engineering overhead for age-gating systems.
- Cloud infrastructure concentration:Reliance on hyperscale providers for model training and inference creates single-point-of-failure risk for threat-detection latency during peak school hours.
- Biometric consent fragmentation:Emerging state rules for facial-recognition attendance systems in Illinois and Texas generate conflicting compliance matrices that complicate multi-state school district deployments.
Strategic Opportunities
- Neurodivergent caregiver segments:Location-tracking features for children with autism spectrum conditions represent an underserved vertical with premium willingness-to-pay in suburban United States markets.
- EU AI Act risk-classification framework:Algorithmic monitoring vendors can capture first-mover advantage by pre-certifying content-filtering engines for the European educational technology procurement channel.
- DNS redirection convergence:Integration with zero-trust network architectures creates cross-sell potential into enterprise remote-work security stacks beyond traditional education verticals.
Industry Challenges
- FTC deceptive advertising enforcement:The Federal Trade Commission's scrutiny of "invisible" monitoring claims requires legal review cycles that delay product marketing timelines.
- Legacy LMS integration friction:School information systems built on decades-old student data standards resist API harmonization, forcing costly custom middleware development for duty-of-care audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parental Monitoring Software Market |
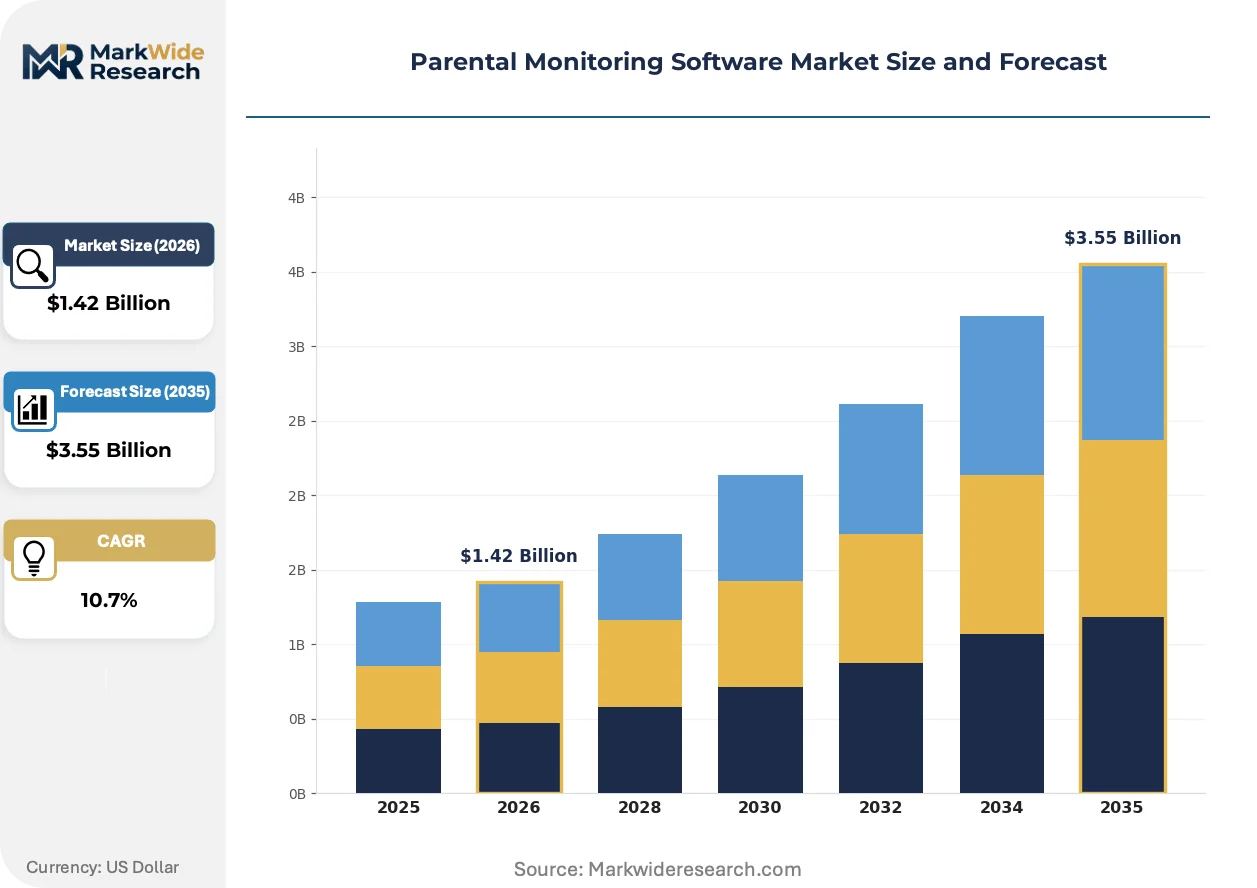
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.55 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Applications, Desktop Software, Web-Based Solutions, Cloud Services End User: Parents, Schools, Caregivers, Non-Profits Deployment: On-Premise, Cloud-Based, Hybrid, Software as a Service Feature: Screen Time Management, Location Tracking, Content Filtering, Activity Monitoring |
| Companies Covered | Microsoft Corporation, Alphabet Inc., NortonLifeLock Inc., Qustodio SL, Bark Technologies, Inc., McAfee, LLC, AO Kaspersky Lab, Net Nanny, Mobicip LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parental Monitoring Software Market Trends and Innovations
Natural-language processing for behavioral risk detection is rewriting competitive differentiation in this market, compressing margins for legacy keyword-blocking vendors while elevating AI-native alert systems.
Transformer-based sentiment analysis engines is rewriting how monitoring platforms interpret contextual nuance in student communications. School districts in California and Texas are piloting these systems for crisis intervention workflows. The technology is rewriting vendor selection criteria away from blocklist breadth toward predictive accuracy metrics.
The EU AI Act's risk-classification framework for algorithmic monitoring imposes conformity assessment obligations on content-filtering engines deployed in European schools. Vendors must now document training data provenance and bias mitigation protocols to access public procurement channels. French and German education ministries are requiring CE-marked AI components in district-level RFPs.
Caregiver purchasing patterns are fragmenting across device-specific ecosystems rather than consolidating on cross-platform solutions. Parents of teenagers prioritize smartphone-native controls with social-media deep linking over traditional desktop-centric packages. This shift is most visible in United States suburban markets where household device ratios exceed four endpoints per minor.
Parental Monitoring Software Market Segmentation
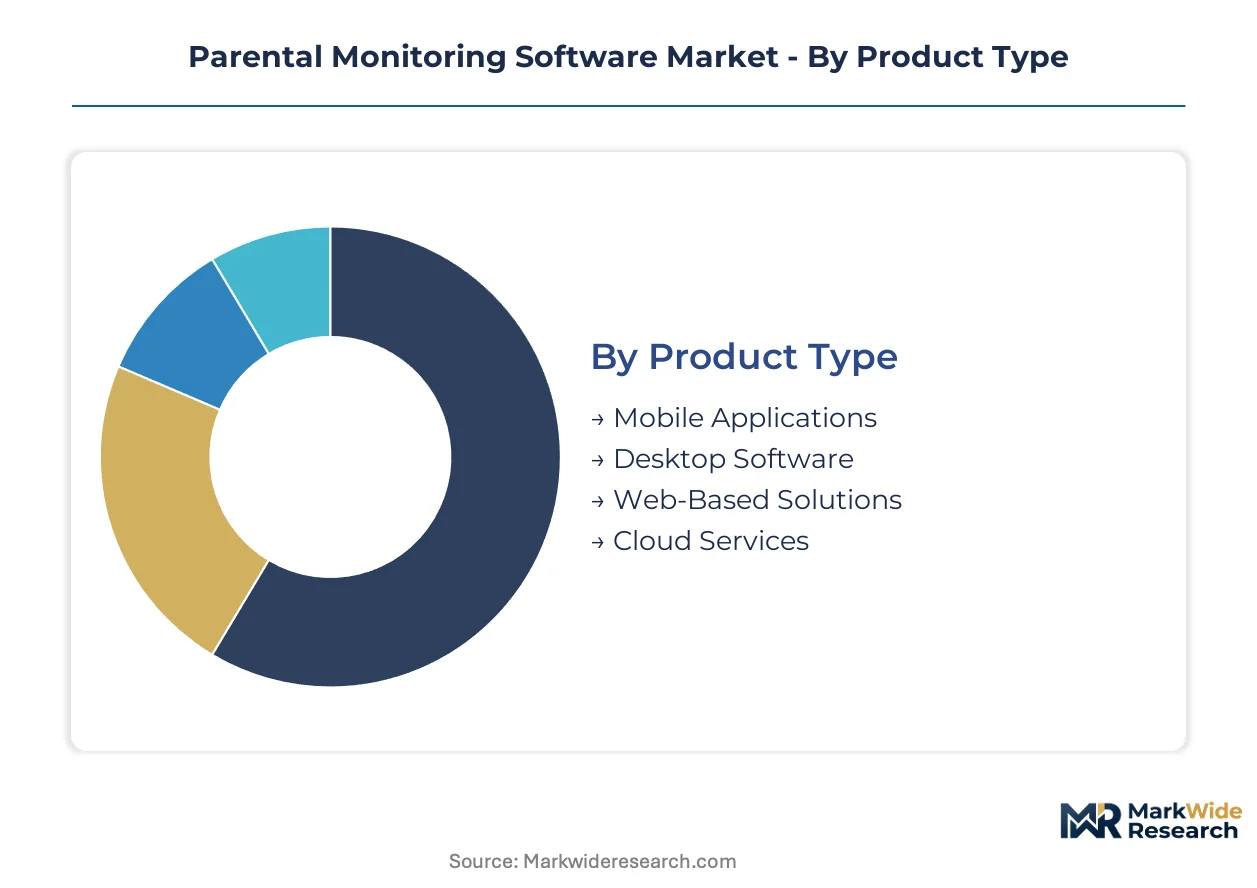
Parental monitoring software segments diverge sharply between consumer convenience and institutional compliance requirements. Product architecture, deployment models, and feature depth all map to distinct willingness-to-pay curves across caregiver and educational buyer personas.
Product Type:
Mobile Applications dominate transaction volume through smartphone-native distribution, while Cloud Services command premium recurring revenue through automatic threat-model updates.
- Mobile Applications:These deploy as iOS and Android native apps leveraging Screen Time API and Family Link frameworks for real-time supervision. Suburban United States households with four-plus devices per minor drive concentration here, prioritizing social-media deep linking over desktop legacy features.
- Cloud Services:Architected on hyperscale infrastructure for model training and inference, these platforms deliver automatic content-filtering updates without endpoint reinstallation. Texas and California school districts specify cloud-native architectures in procurement RFPs for duty-of-care audit trails.
- Desktop Software:Agent-based screen capture and keystroke logging for Windows and macOS endpoints, still specified by legacy enterprise buyers.
- Web-Based Solutions:Browser-extension deployments with DNS redirection for lightweight filtering without native app installation.
Today's leader: Cloud Services. Tomorrow's challenger: Mobile Applications.
End User:
Institutional buyers demand auditable compliance documentation, while individual caregivers prioritize frictionless installation and intuitive dashboards.
- Schools:K-12 districts require screen-time analytics platforms with API-level integration into student information systems. State-level digital safety mandates in Texas and California accelerate district-level procurement of enterprise-grade filtering with verifiable duty-of-care documentation.
- Parents:Individual caregivers managing multi-device households seek anxiety-mitigation tools with minimal configuration overhead. Neurodivergent child segments in suburban United States markets exhibit premium willingness-to-pay for location-tracking features.
- Caregivers:Extended family members and guardians seeking delegated monitoring permissions without full administrative control.
- Non-Profits:Youth-serving organizations requiring scaled licensing for device-lending programs and after-school digital safety initiatives.
Schools anchor current procurement volume. Parents represent the steepest expansion trajectory as smartphone-first supervision displaces desktop-centric legacy approaches.
Deployment:
Cloud-Based architectures reduce IT overhead for resource-constrained districts, while On-Premise retains footholds in jurisdictions with strict data residency requirements.
- Cloud-Based:Fully managed SaaS delivery with automatic scaling for peak school-hour inference loads. EU AI Act conformity assessment obligations are prompting vendors to document training data provenance for European educational procurement channels.
- Software as a Service:Subscription-tiered feature delivery with continuous model updates for suicide-risk detection algorithms, differentiating alert systems in competitive RFPs.
- On-Premise:Local server deployment for districts with stringent student data residency policies or limited internet bandwidth.
- Hybrid:Split architectures keeping sensitive biometric data local while leveraging cloud inference for threat detection.
Cloud-Based deployment captures expanding margin pools. Hybrid models gain share fastest where biometric consent fragmentation complicates multi-state school district deployments.
Feature:
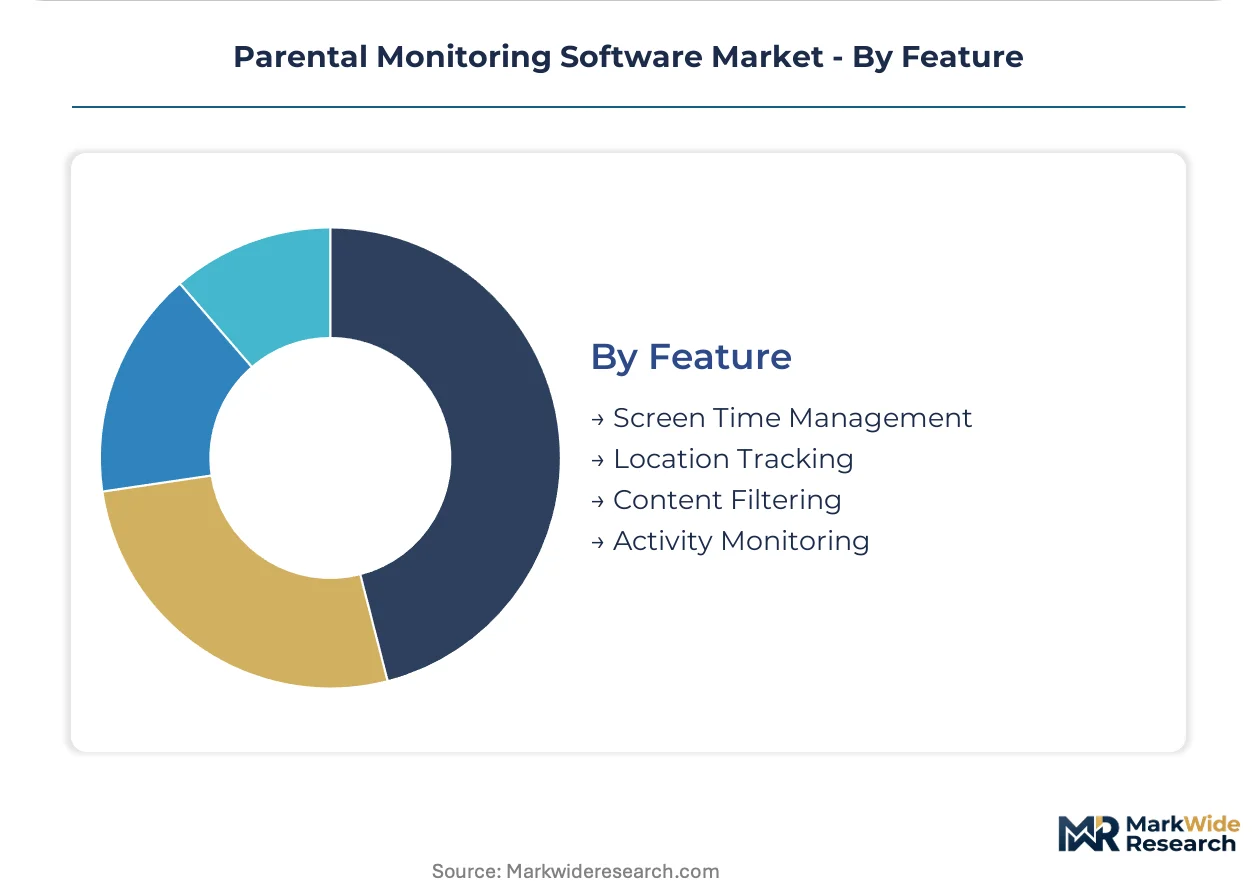
Activity Monitoring leads enterprise attachment rates for compliance documentation, while Location Tracking climbs fastest among specialized caregiver segments.
- Activity Monitoring:Comprehensive audit trails of application usage, browsing history, and communication patterns with timestamped reporting. School districts specify these features first in procurement evaluations for liability reduction.
- Location Tracking:GPS and geofencing capabilities with real-time alert triggers for boundary violations. Caregivers managing children with autism spectrum conditions in United States suburban markets drive premium pricing here.
- Content Filtering:URL blocklists and category-based restrictions, now being displaced by NLP-based contextual analysis in competitive differentiation.
- Screen Time Management:Scheduling controls and usage quotas, table-stakes features increasingly bundled rather than premium-priced.
Activity Monitoring anchors enterprise selection criteria. Location Tracking is gaining share fastest as neurodivergent caregiver segments expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates procurement volume for institutional parental monitoring software, while Germany shapes European compliance architecture through its federal data protection framework. Regulatory divergence between these markets is forcing vendors to maintain parallel certification tracks.
United States
Texas and California state mandates for student device management are accelerating district-level adoption of screen-time analytics platforms. The FTC enforces deceptive advertising standards around monitoring claims, creating legal review bottlenecks for product launches. Austin and San Francisco host competing clusters of NLP-focused alert system developers.
Germany
Federal education ministries specify CE-marked AI components in district procurement RFPs for algorithmic content filtering. The EU AI Act's risk-classification framework imposes conformity assessment obligations on vendors accessing public channels. Berlin anchors development of bias-mitigation documentation tools for training data provenance.
United Kingdom
Multi-academy trusts are consolidating purchasing power for cloud-native duty-of-care audit trail systems. The Information Commissioner's Office scrutinizes age-gating mechanisms for COPPA-equivalent compliance in cross-border deployments. London's EdTech corridor concentrates vendors specializing in neurodivergent caregiver location-tracking features.
France
The national education ministry requires documented bias mitigation protocols for AI components in school filtering platforms. ANSM and CNIL coordinate on biometric consent rules for facial-recognition attendance integrations. Paris hosts pre-certification service providers helping vendors navigate EU AI Act conformity pathways.
India
Private school chains in metropolitan areas are piloting smartphone-native supervision tools as household device ratios expand. The Digital Personal Data Protection Act shapes age-verification architecture for minor-facing platforms. Bangalore's SaaS cluster hosts developers integrating DNS redirection with zero-trust enterprise security stacks.
Parental Monitoring Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise education procurement favoring established cybersecurity brands while consumer segments tolerate narrower feature sets from niche developers. The vendor base organizes into three tiers: hyperscale cloud platforms with bundled family safety modules, dedicated parental control specialists with NLP differentiation, and regional white-label providers serving price-sensitive institutional buyers. Dominant competitive moves include API-level OS integration partnerships with mobile operating systems and pre-certification investments for EU AI Act compliance.
Within the hyperscale platform tier, Microsoft Corporation and Alphabet Inc. exemplify cloud-backbone strategies that leverage existing enterprise relationships to anchor school district filtering contracts. NortonLifeLock Inc. occupies a distinct position bridging consumer antivirus trust into family safety bundles. Bark Technologies, Inc. represents the specialist archetype, anchoring competitive differentiation on natural-language processing for behavioral risk detection rather than traditional keyword blocking.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Alphabet Inc. |
| NortonLifeLock Inc. |
| Qustodio SL |
| Bark Technologies, Inc. |
| McAfee, LLC |
| AO Kaspersky Lab |
| Net Nanny |
| Mobicip LLC |
| Others |
Pricing and Supply Chain Analysis
Transformer-based NLP model training is compressing development timelines for suicide-risk detection engines while simultaneously concentrating compute infrastructure dependencies among hyperscale cloud providers in the United States. This dual shift is elevating fixed-cost burdens for specialist vendors and reshaping how tiered service levels are priced across school district and consumer segments.
Pricing Analysis
Capacity additions in hyperscale cloud regions are reshaping price floors for SaaS-tiered parental monitoring platforms, particularly for cloud-native architectures with automatic model updates. Three-tier pricing structure across premium, standard, and economy levels segments by API integration depth and NLP sophistication, with Texas and California school districts exhibiting lowest price sensitivity due to state mandate urgency. Cost compression in the economy tier is intensifying because consumer smartphone-native apps commoditize basic screen-time features. Individual caregivers managing neurodivergent children demonstrate highest willingness-to-pay for location-tracking premium tiers.
Supply Chain Analysis
Freight costs for edge hardware deployments are negligible in this software-dominant market, though latency-sensitive inference workloads are concentrating cloud infrastructure in the United States, Ireland, and Germany. Raw material dependencies center on GPU compute allocations, training data licensing, and API access fees to iOS and Android parental control frameworks. Single-source vulnerability rests on hyperscale provider concentration for model training and peak-load inference during school hours. Distribution runs through direct SaaS provisioning for institutional buyers and mobile app stores for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement is shifting toward predictive accuracy metrics and EU AI Act pre-certification, favoring vendors with documented bias mitigation protocols over legacy keyword-blocking alternatives.
For Market Incumbents: Acquire specialized NLP engineering teams with crisis intervention dataset access to defend against AI-native alert system entrants. Prioritize backward integration into training data provenance documentation to satisfy French and German education ministry procurement requirements. Channel control through exclusive API-level OS integration partnerships with mobile operating systems remains critical for retention economics. For New Entrants and Emerging Players: Launch via white-label partnerships with regional school information system vendors to bypass entrenched district procurement relationships. Neurodivergent caregiver segments in United States suburban markets represent the most penetrable vertical, with premium pricing tolerance for location-tracking features unmet by institutional-focused incumbents. Direct-to-consumer social media influencer partnerships offer lowest customer acquisition cost for smartphone-native app distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among on-premise legacy desktop software vendors with stagnant R&D pipelines and declining school district renewals. Long-term viability favors cloud-native specialists with EU AI Act conformity assessment completion and recurring revenue concentration above transactional licensing. The signal to watch is Illinois and Texas biometric consent rule harmonization, which would trigger consolidation demand among multi-state district vendors facing compliance fragmentation costs.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | CE-marked AI components unlock French and German public education procurement channels. |
| NLP Model Training Data Acquisition | Crisis intervention datasets differentiate alert accuracy in competitive Texas and California RFPs. |
| API-Level OS Integration Partnership | Deep iOS and Android hooks eliminate VPN latency and improve caregiver retention rates. |
| Neurodivergent Segment Product Line Extension | Location-tracking features for autism spectrum conditions command premium pricing in suburban markets. |
| Zero-Trust Security Stack Convergence | DNS redirection integration opens enterprise remote-work cross-sell beyond education verticals. |
Research Methodology
Direct dialogue with school district technology directors, EdTech procurement officers, parental control software product managers, and special education program coordinators anchored primary intelligence gathering. Secondary validation drew from SEC 10-K filings of publicly traded cybersecurity vendors, hyperscaler capex disclosures, EU AI Act regulatory texts, and FTC enforcement action records. Bottom-up triangulation across deployment model, end-user segment, and feature category dimensions reconciled with top-down market sizing.
Top-down analytical framing applied penetration rate modeling across United States state-level mandate adoption curves, while bottom-up builds aggregated individual vendor revenue disclosures and district contract values. Segmentation dimensions modeled include product type, end user archetype, deployment architecture, and regional regulatory cluster throughout the forecast period. CAGRs were derived from logistic adoption curves for institutional procurement and linear extrapolation for consumer smartphone-native app penetration, with suicide-risk detection algorithm attach rates as a key industry-specific input.
Several conditions sit outside the modeled scope, including potential COPPA enforcement actions, biometric consent rule fragmentation across additional states, and hyperscale cloud provider service disruptions. Forecasts reflect documented assumptions regarding state mandate expansion timelines and EU AI Act implementation consistency. A model refresh is warranted upon material change in Texas or California district procurement acceleration rates or EU conformity assessment pathway modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Quantum Key Distribution System Market
Security Software
Certificate Authority Market
Security Software
Passwordless Authentication Market
Security Software
Global Email Verification Tools Market
Security Software
Spam Blocking Software Market
Security Software
Software Protection Dongle Market
Security Software
Banking Encryption Software Market
Security Software
Facial Recognition Market
Security Software
Phone Antivirus Software Market
Security Software
Global Advanced Authentication Market
Security Software
Global Electronic Offender Monitoring Solutions Market
Security Software
Europe Anti-Money Laundering Software Market
Security Software
AI Security Platforms Market
Security Software
Mobile Security Market
Security Software
Global Consumer IAM Market
Security Software
Japan Mobile Biometrics Market