

Encryption As A Service Market Size, Share, and Industry Trends Forecast 2026-2036
Encryption As A Service Market Insights
Channel architecture for encryption delivery is fragmenting as hyperscalers, independent software vendors, and managed security providers compete for enterprise workloads. AWS leverages its integrated key management infrastructure to anchor multi-cloud encryption contracts. Thales specializes in hardware security module integration for regulated industries. Microsoft extends its identity and compliance stack to differentiate encryption bundles from standalone offerings.
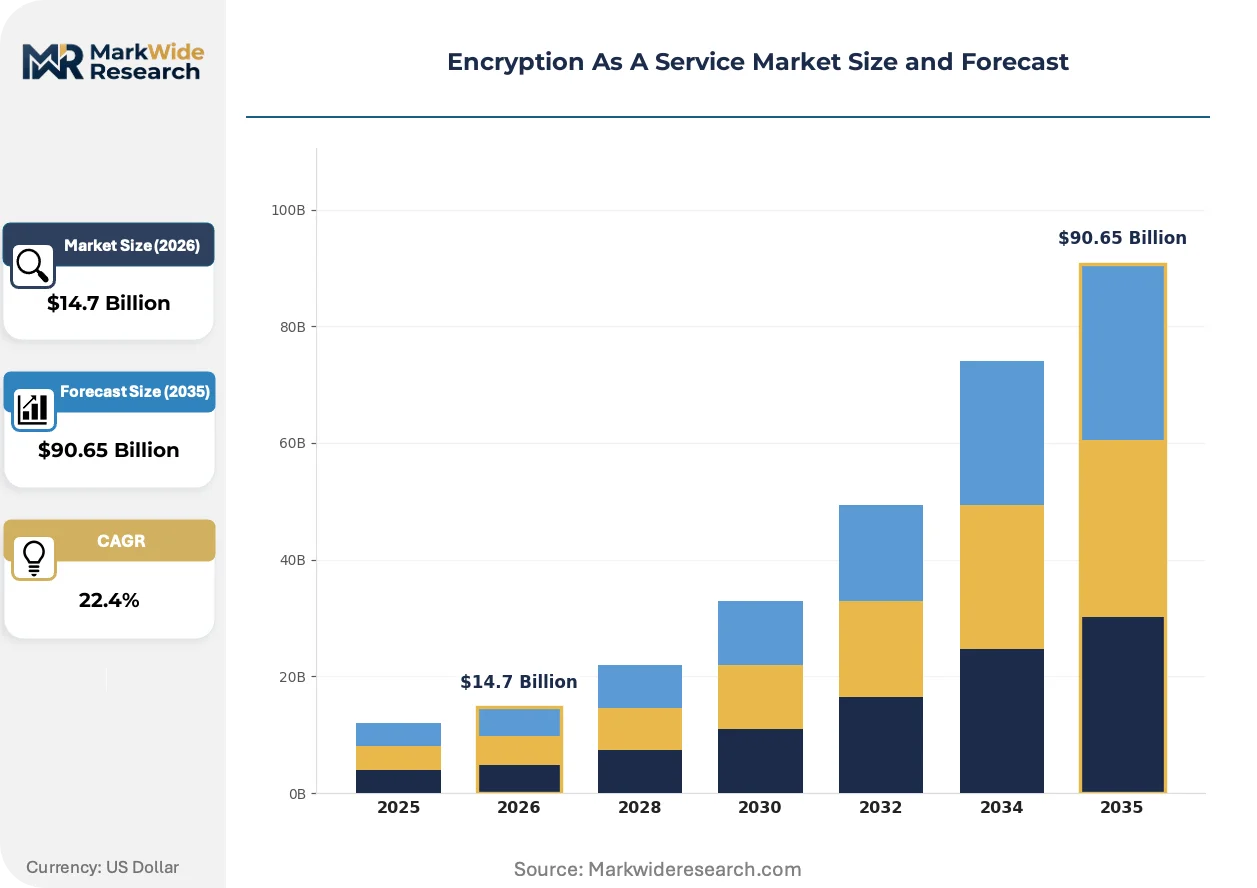
Encryption As A Service denotes the outsourced provision of cryptographic functions—key generation, data transformation, and access control—delivered via API or managed platform, typically employing AES-256 or RSA-4096 algorithms with FIPS 140-2 validated modules to protect data at rest, in transit, and during processing. Cloud Encryption services command the largest revenue pool among service types, reflecting enterprise migration of primary data stores to public infrastructure. Homomorphic Encryption represents the fastest-expanding technology segment, enabling computation on encrypted data without decryption, though commercial deployment remains concentrated in pilot programs within BFSI and government verticals.
FCC guidelines on telecommunications data protection, GDPR cross-border transfer mechanisms, and the EU AI Act's confidentiality requirements collectively elevate encryption from optional safeguard to mandatory infrastructure layer. HIPAA mandates for healthcare data at rest and NIST post-quantum cryptography standards are accelerating refresh cycles for legacy encryption implementations. Stakeholders must evaluate algorithm migration paths against emerging quantum threats while maintaining interoperability with existing certificate authorities and key escrow frameworks.
Market Dynamics
Post-quantum cryptography migration is compressing refresh cycles for enterprise encryption infrastructure as NIST standards finalize and threat actors harvest encrypted data for future decryption.
Growth Catalysts
- GDPR cross-border transfer mechanisms:EU enterprises must encrypt personal data leaving member states, mandating AES-256 or equivalent for cloud workloads. German automotive firms now embed encryption into supplier contracts.
- Homomorphic encryption maturation:BFSI pilot programs demonstrate secure computation on encrypted datasets without decryption, opening confidential analytics use cases previously blocked by privacy constraints.
- Healthcare digitization:HIPAA mandates for data at rest accelerate hospital migration to managed encryption services, with US health systems prioritizing FIPS 140-2 validated key management.
Market Restraints
- Hardware security module supply concentration:Thales and Entrust dominate FIPS-validated HSM production, creating single-source risk for regulated industries requiring certified key protection.
- Algorithm transition costs:Migrating from RSA-2048 to post-quantum lattice-based cryptography requires certificate authority re-issuance and application-layer reconfiguration across enterprise stacks.
- Key escrow complexity:Government lawful access mandates in multiple jurisdictions fragment key management architectures, forcing providers to maintain jurisdiction-specific escrow frameworks.
Strategic Opportunities
- Confidential computing convergence:Integration of trusted execution environments with encryption services enables processing of sensitive data in untrusted cloud infrastructure, targeting BFSI and government workloads.
- India data localization requirements:RBI and CERT-In mandates for domestic data storage create demand for indigenous encryption service providers with in-country key custody.
- EU AI Act confidentiality provisions:Training data protection requirements for high-risk AI systems mandate encryption throughout the machine learning pipeline, expanding addressable market for encryption-as-a-service.
Industry Challenges
- Cryptographic engineering talent scarcity:Enterprises struggle to hire specialists capable of implementing post-quantum migration paths while maintaining interoperability with legacy PKI infrastructure.
- Multi-cloud key synchronization:Organizations operating across AWS, Azure, and Google Cloud face operational complexity in maintaining consistent key rotation policies and access controls across heterogeneous environments.
- Quantum-safe certificate timelines:Certificate authorities have not standardized post-quantum signature algorithms, delaying enterprise procurement decisions and extending legacy vulnerability windows.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encryption As A Service Market Trends and Innovations
Encryption delivery models are bifurcating between integrated hyperscaler stacks and specialized independent platforms, with computational privacy technologies emerging as the next architectural frontier.
Fully homomorphic encryption schemes are rendering obsolete traditional extract-transform-load pipelines that required data decryption for analytics. Pharmaceutical firms conducting multi-party clinical trials now process encrypted patient records without exposing raw data, compressing compliance review timelines from months to weeks.
The EU AI Act's confidentiality requirements for high-risk systems are mandating encryption-by-default for training datasets and model weights. Medical device manufacturers deploying AI diagnostic tools must demonstrate end-to-end cryptographic protection, accelerating procurement of managed encryption platforms with automated compliance documentation.
Enterprise buyers are consolidating encryption procurement under zero-trust architecture mandates, displacing point solutions with integrated platforms spanning identity, access, and data protection. US federal agencies under OMB zero-trust directives now require encryption services with continuous authorization monitoring, favoring vendors with FedRAMP authorization over uncertified alternatives.
Encryption As A Service Market Segmentation
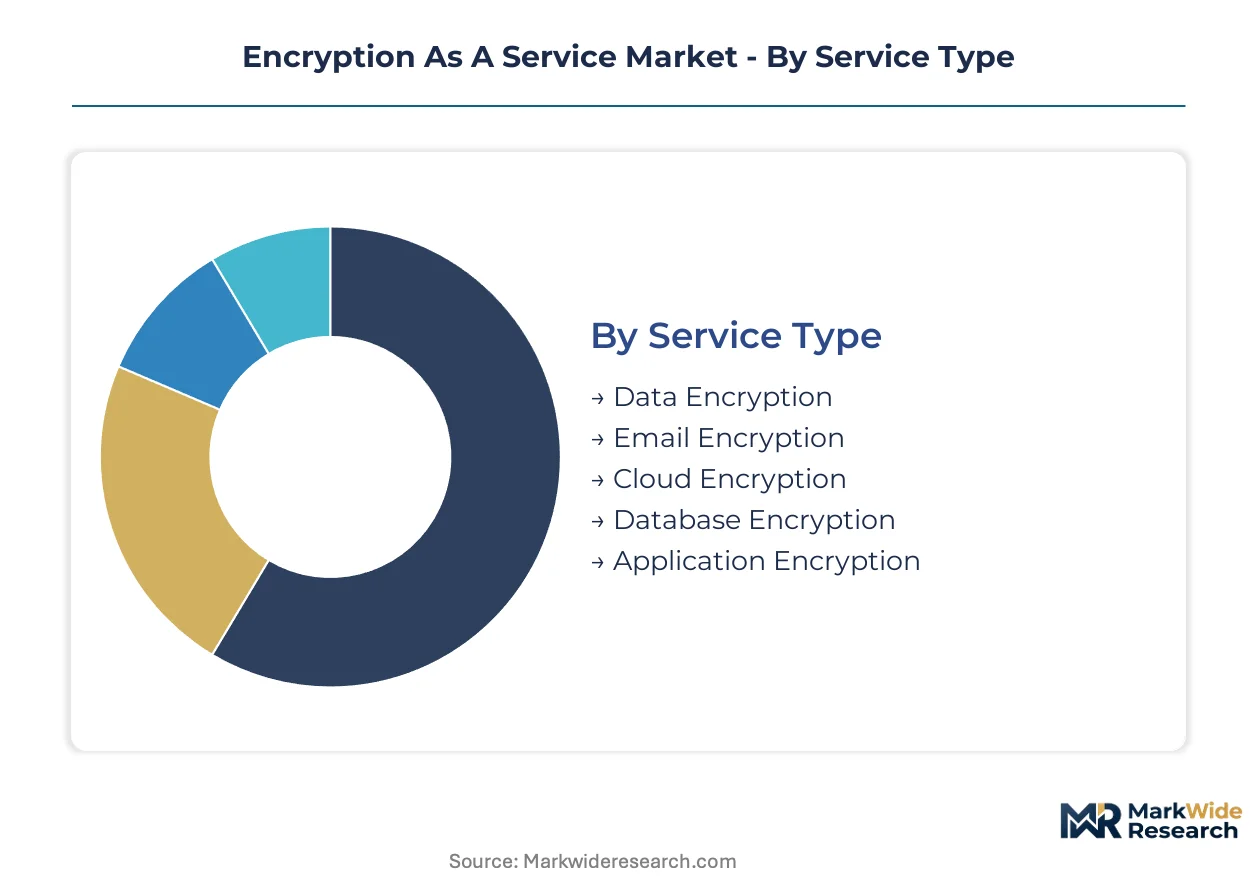
Encryption as a service providers configure delivery models around workload sensitivity, regulatory jurisdiction, and computational requirements. Segmentation reveals where commoditization pressures concentrate and where specialized cryptography commands premium positioning.
Service Type:
Cost tier differentiation separates basic data protection from infrastructure-integrated cryptographic services with compliance automation.
- Cloud Encryption:Managed key lifecycle services for object storage, block volumes, and serverless functions across AWS, Azure, and Google Cloud environments. German automotive manufacturers embed these services into supplier contracts to satisfy GDPR cross-border transfer requirements.
- Application Encryption:API-delivered cryptographic operations integrated directly into software pipelines, enabling field-level encryption without application rearchitecture. US health systems under HIPAA mandates prioritize FIPS 140-2 validated implementations for patient data flows.
- Data Encryption:File-system and volume-level protection for on-premises and hybrid workloads.
- Email Encryption:Gateway and client-side solutions for message confidentiality and non-repudiation.
- Database Encryption:Transparent data encryption and column-level protection for structured data stores.
Cloud Encryption commands the established base. The steepest expansion runs through Application Encryption.
Deployment Mode:
Volume concentration shifts toward consumption models that balance operational control with capital efficiency.
- Public Cloud:Fully managed encryption services where the provider controls key infrastructure and custody. Financial services firms in Singapore and the UAE accelerate adoption for payment processing workloads subject to PCI-DSS and local central bank guidelines.
- Hybrid Cloud:Unified key management spanning on-premises hardware security modules and public cloud key services. Energy enterprises in Norway and Canada deploy this architecture to protect seismic and reservoir data while maintaining sovereign control over cryptographic material.
- Private Cloud:Dedicated encryption infrastructure within single-tenant environments.
- On-Premises:Customer-managed hardware and software deployed within enterprise data centers.
Public Cloud anchors current procurement volumes. Hybrid Cloud gains share fastest as regulated industries navigate data sovereignty requirements.
End User:
Customer type determines algorithm selection, key custody models, and audit documentation intensity.
- BFSI:Multi-layered encryption for payment networks, core banking systems, and confidential analytics. Swiss and Luxembourg private banks pilot homomorphic encryption for cross-institutional fraud detection without exposing client portfolios.
- Government Agencies:Classified and unclassified workload protection with sovereign key custody mandates. India's Ministry of Defence and Australia's Defence Department require in-country HSM infrastructure for strategic systems.
- Telecommunication Firms:Subscriber data and lawful intercept protection under national security frameworks.
- Educational Institutions:Research data and student record protection with limited operational security expertise.
- Energy Enterprises:Operational technology and exploration data encryption for critical infrastructure.
BFSI contributes the dominant revenue pool. Government Agencies expand most quickly through classified cloud migration programs.
Encryption Technology:
Maturity curves separate production-deployed algorithms from experimental schemes awaiting standardization.
- Homomorphic Encryption:Computation on ciphertext enabling confidential machine learning and multi-party analytics. Pharmaceutical firms in Basel and Boston compress clinical trial data sharing timelines by processing encrypted patient records without decryption.
- Asymmetric Key:Public-key infrastructure for identity verification, key exchange, and digital signatures. Certificate authorities in the US and Germany accelerate post-quantum algorithm migration as NIST standards finalize.
- Symmetric Key:AES-256 and equivalent block ciphers for bulk data protection.
- Hashing Algorithms:Integrity verification and password storage without reversible transformation.
- Quantum Cryptography:Quantum key distribution and quantum-resistant algorithms for long-term confidentiality.
Asymmetric Key underpins existing infrastructure. Homomorphic Encryption climbs the fastest as confidential computing use cases mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-CyberRhein-Main digital corridor anchors European encryption demand through its concentration of financial data centers and automotive engineering clusters. This infrastructure asset underwrites Germany's role as the continental hub for sovereign cloud encryption services.
United States
Federal zero-trust mandates from OMB drive agency procurement of FedRAMP-authorized encryption platforms. HIPAA enforcement actions against hospital systems accelerate migration to managed key services. The Boston-Route 128 corridor hosts pharmaceutical firms piloting homomorphic encryption for multi-party clinical data sharing.
Germany
Automotive OEMs embed AES-256 encryption into supplier contracts to satisfy GDPR cross-border transfer requirements. The EU AI Act's confidentiality provisions mandate cryptographic protection for training datasets in high-risk AI systems. Stuttgart and Munich engineering clusters lead deployment of hardware security module infrastructure for industrial design data.
India
RBI and CERT-IN data localization mandates create demand for indigenous encryption providers with domestic key custody. The Ministry of Defence requires in-country HSM infrastructure for strategic systems. Bangalore and Hyderabad technology corridors attract cloud providers establishing sovereign encryption zones for financial services workloads.
United Kingdom
Financial conduct authority guidelines elevate encryption to mandatory infrastructure for payment service providers. NHS digitization programs accelerate hospital adoption of FIPS 140-2 validated key management. London's fintech cluster drives demand for confidential computing integration with encryption services.
Singapore
Monetary authority cybersecurity guidelines mandate encryption for banking system interconnections. The city-state's data center concentration attracts hyperscaler investment in regional key management hubs. Marina Bay financial district institutions pilot quantum-resistant algorithms for cross-border payment networks.
Encryption As A Service Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in hardware security module and key management infrastructure. The vendor base spans three functional layers: hyperscale cloud providers with native encryption stacks, independent software vendors with API-delivered cryptographic services, and hardware specialists with FIPS-validated module production. Market structure tilts toward consolidation at the platform layer while component supply remains concentrated among certified manufacturers. Dominant competitive moves include strategic partnerships between cloud providers and hardware security module vendors, plus geographic expansion through sovereign cloud deployments.
Within the hyperscaler tier, AWS, Microsoft, and Google Cloud anchor multi-cloud encryption contracts through integrated identity and compliance stacks. Thales and Utimaco occupy positions among hardware security module specialists serving regulated industries with certified key protection requirements. These five entities exemplify the bifurcation between platform-integrated delivery and specialized cryptographic component supply.
| Leading Market Players |
|---|
| AWS |
| Microsoft |
| Google Cloud |
| IBM |
| Cisco |
| HashiCorp |
| Thales |
| Fortanix |
| Utimaco |
| Others |
Pricing and Supply Chain Analysis
Thales and Entrust's dominance over FIPS-validated hardware security module production concentrates upstream cryptographic component supply in France and Germany, anchoring margin pools in the certified key protection tier where regulated BFSI and government buyers face single-source risk premiums.
Pricing Analysis
Volume-discount tiering structures separate consumption-based API pricing for cloud-native workloads from fixed-fee enterprise licenses for on-premises hardware security module deployments. FIPS 140-2 certification grade and sovereign key custody requirements drive price differentiation, with German automotive firms paying premiums for domestic HSM infrastructure. Cost compression in standard cloud encryption tiers is intensifying as AWS, Microsoft, and Google Cloud compete for multi-cloud contracts. Mid-market healthcare providers exhibit highest price sensitivity, while classified government agencies demonstrate lowest sensitivity due to mandatory compliance specifications.
Supply Chain Analysis
Export-control regimes limiting quantum cryptography and advanced encryption technology flows constrain hardware security module distribution to approved jurisdictions, fragmenting global availability. Manufacturing concentrates in France, Germany, and the United States for certified modules, with specialized semiconductor foundries in Taiwan producing cryptographic processors. Supply chains draw from rare earth elements for quantum key distribution hardware, precision lithography equipment, and FIPS-validation laboratory capacity. Single-source vulnerability runs through Thales and Entrust's combined grip on certified HSM production. Distribution runs through direct enterprise sales for regulated verticals and hyperscaler marketplaces for cloud-native consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
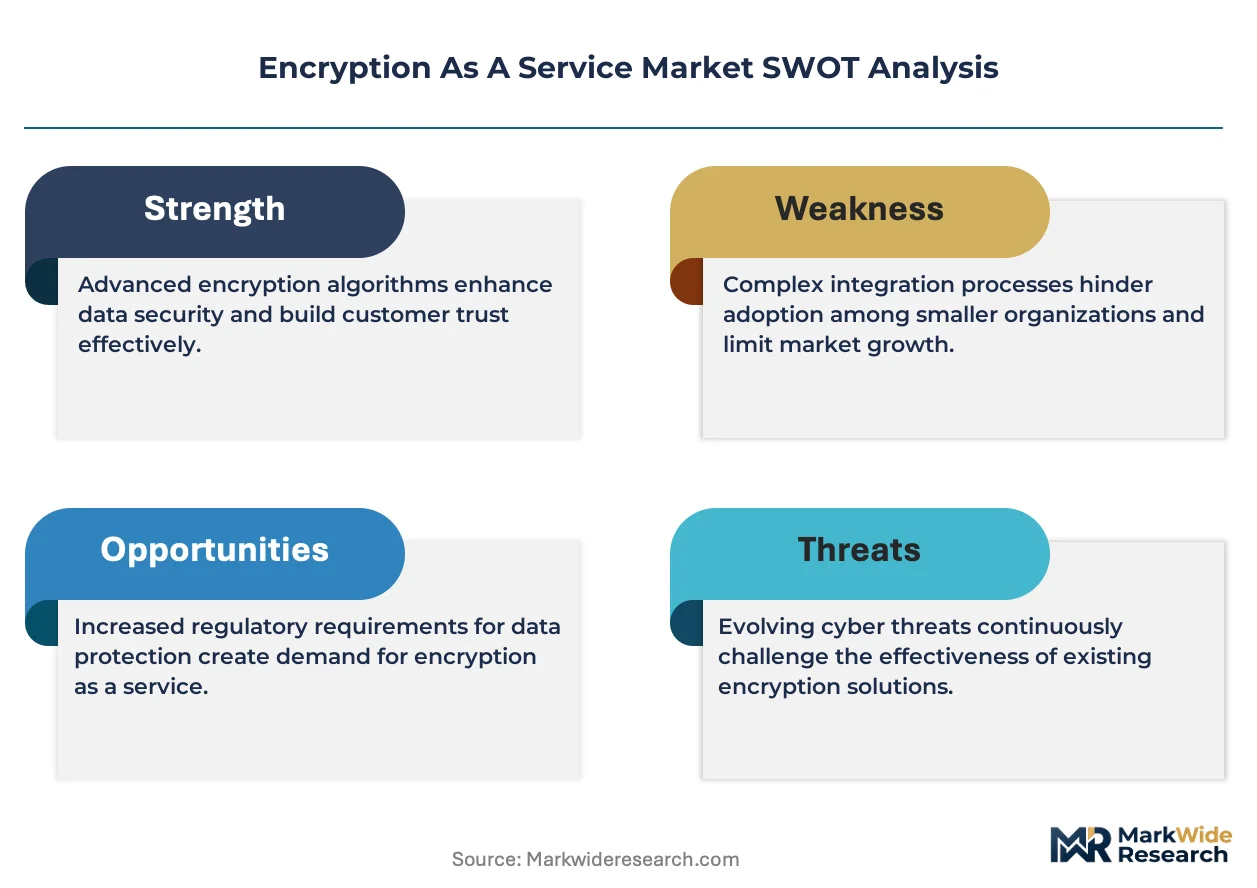
Post-quantum cryptography standardization by NIST is disrupting enterprise procurement cycles, compressing refresh timelines and forcing algorithm migration investments that favor vendors with integrated migration tooling.
For Market Incumbents: Pre-empt post-quantum obsolescence by embedding lattice-based algorithm support into existing key management platforms before certificate authorities finalize signature standards. Acquire specialized homomorphic encryption engineering teams to defend against confidential computing entrants. Vertical integration into sovereign cloud deployments across India and Germany addresses data localization threats from RBI and GDPR mandates. For New Entrants and Emerging Players: Mid-market healthcare systems in the United States represent the most penetrable entry point, as HIPAA enforcement drives FIPS-validated key management demand without incumbent lock-in. India's indigenous encryption provider gap under RBI localization rules offers second-mover advantage for domestic HSM infrastructure. Go-to-market through managed security service providers accelerates credentialing with risk-averse hospital procurement committees. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hardware security module specialists holding FIPS certifications but lacking cloud-native platform integration. Five-to-ten year viability hinges on post-quantum migration service revenue replacing legacy certificate authority dependence. Watch NIST post-quantum signature algorithm standardization as the inflection signal triggering enterprise procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Algorithm Integration | Lattice-based cryptography migration captures NIST-standardization-driven refresh cycles across federal and BFSI verticals. |
| Sovereign Cloud Partnership | Domestic HSM infrastructure in India and Germany satisfies RBI and GDPR data localization mandates. |
| Homomorphic Encryption Platform Launch | Confidential analytics capabilities unlock pharmaceutical multi-party clinical trial data sharing previously blocked by privacy constraints. |
| FedRAMP Authorization Acceleration | US federal zero-trust mandates under OMB directives favor authorized vendors for agency encryption procurement. |
| Hardware Security Module Supply Diversification | Second-source FIPS-validated production reduces single-source risk for Thales-dependent regulated industries. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC hyperscaler filings, NIST post-quantum cryptography standardization documents, and EU AI Act regulatory texts. Chief information security officers at German automotive manufacturers, cloud platform engineers at AWS and Microsoft, and procurement leads at US health systems provided operational validation. Bottom-up service-type demand modeling triangulates against top-down regional encryption spend estimates derived from GDPR enforcement action frequencies and data center construction permits.
Forecast inputs include encryption service adoption curves across public cloud, hybrid cloud, and on-premises deployment modes, algorithm transition timelines from RSA-2048 to post-quantum standards, and vertical-specific compliance mandate implementation schedules. Modeled dimensions span service type, deployment architecture, end-user industry, encryption technology maturity, and geographic regulatory cluster. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion across the projection horizon. Quantum threat perception indices and certificate authority re-issuance volumes inform technology transition pacing assumptions.
Macroeconomic conditions sit as an overlay; deviation in enterprise cloud migration spending or federal IT budget appropriations would shift the trajectory. Forecasts reflect documented assumptions regarding NIST standardization timelines, EU AI Act enforcement intensity, and hyperscaler pricing discipline. Material shifts in post-quantum algorithm finalization dates or export control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.