
 Magnesium Glycinate Market | 2026-2036
Magnesium Glycinate Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Glycinate Market Foresight
The EU Green Deal's sustainability mandates for pharmaceutical and nutraceutical supply chains is expanding scrutiny on mineral sourcing and carbon footprints across European markets. Albion Laboratories specializes in patented mineral chelation technology that commands premium positioning in clinical-grade formulations. NovoTech Nutraceuticals navigates contract manufacturing complexity by sustaining dual-site production across North American facilities. Ajinomoto leverages amino acid fermentation expertise to anchor glycinate precursor supply for integrated magnesium chelate output.
Magnesium glycinate denotes a magnesium salt of glycine formed through chelation, typically yielding 10-14% elemental magnesium by weight with superior intestinal absorption compared to oxide or citrate forms. Manufacturers employ aqueous reaction synthesis followed by spray-drying to produce powders meeting USP dissolution specifications for dietary supplement and pharmaceutical applications. Capsule formats dominate volume throughput in retail channels, though powder segments exhibit faster velocity among compounding pharmacies and personalized nutrition services. Healthcare provider prescribing of magnesium glycinate for sleep aid and stress reduction applications is deepening the professional channel's margin contribution relative to mass-market tablets.
FDA CGMP regulations and the Dietary Supplement Health and Education Act framework govern manufacturing quality, while EFSA novel food assessments shape European market entry pathways for new chelate formulations. ISO 17025 accreditation requirements for third-party testing laboratories are tightening analytical verification standards for elemental content and heavy metal limits. Stakeholders must monitor evolving pharmacopeial monograph revisions and state-level supplement registration expansions that could reshape compliance cost structures and competitive barriers.
Market Dynamics
CGMP enforcement by the FDA and EFSA novel food assessments are tightening quality thresholds, forcing manufacturers to upgrade analytical verification infrastructure and documentation systems. This regulatory compression favors chelation specialists with captive laboratory capabilities over commodity mineral processors.
Growth Catalysts
- Clinical nutrition protocols:Hospital formulary committees are expanding magnesium glycinate inclusion in perioperative and ICU supplementation guidelines due to superior bioavailability metrics.
- EFSA novel food pathways:Streamlined safety assessments for amino acid chelates are accelerating European market entry for reformulated products with enhanced dissolution profiles.
- Sports performance segment:Collegiate and professional athletic programs are standardizing magnesium glycinate in recovery protocols, driving institutional procurement contracts.
Market Restraints
- Glycine feedstock volatility:Amino acid precursor costs fluctuate with fermentation capacity utilization in bulk chemical manufacturing hubs.
- Chinese supply concentration:Intermediate magnesium oxide and glycinate precursor production clusters in Shandong and Jiangsu provinces create geographic risk exposure.
- Oxide and citrate substitution:Lower-cost magnesium salts retain formulary preference in mass-market multivitamin applications where elemental magnesium density outweighs absorption metrics.
Strategic Opportunities
- Compounding pharmacy channel:Personalized medicine services in the United States are expanding custom magnesium glycinate dosing for functional medicine practitioners.
- EU Green Deal alignment:Carbon footprint verification and sustainable sourcing certifications open premium positioning in environmentally-scored pharmaceutical procurement frameworks.
- Direct-to-consumer subscription models:Sleep aid and stress reduction applications are migrating from retail shelf to recurring delivery platforms with higher lifetime value metrics.
Industry Challenges
- ISO 17025 laboratory accreditation timelines:Third-party testing capacity constraints delay batch release for manufacturers expanding product lines.
- Chelate stability validation:Demonstrating intact bisglycinate structure versus dissociated magnesium-glycine mixtures requires advanced spectroscopic methods that strain analytical budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Glycinate Market |
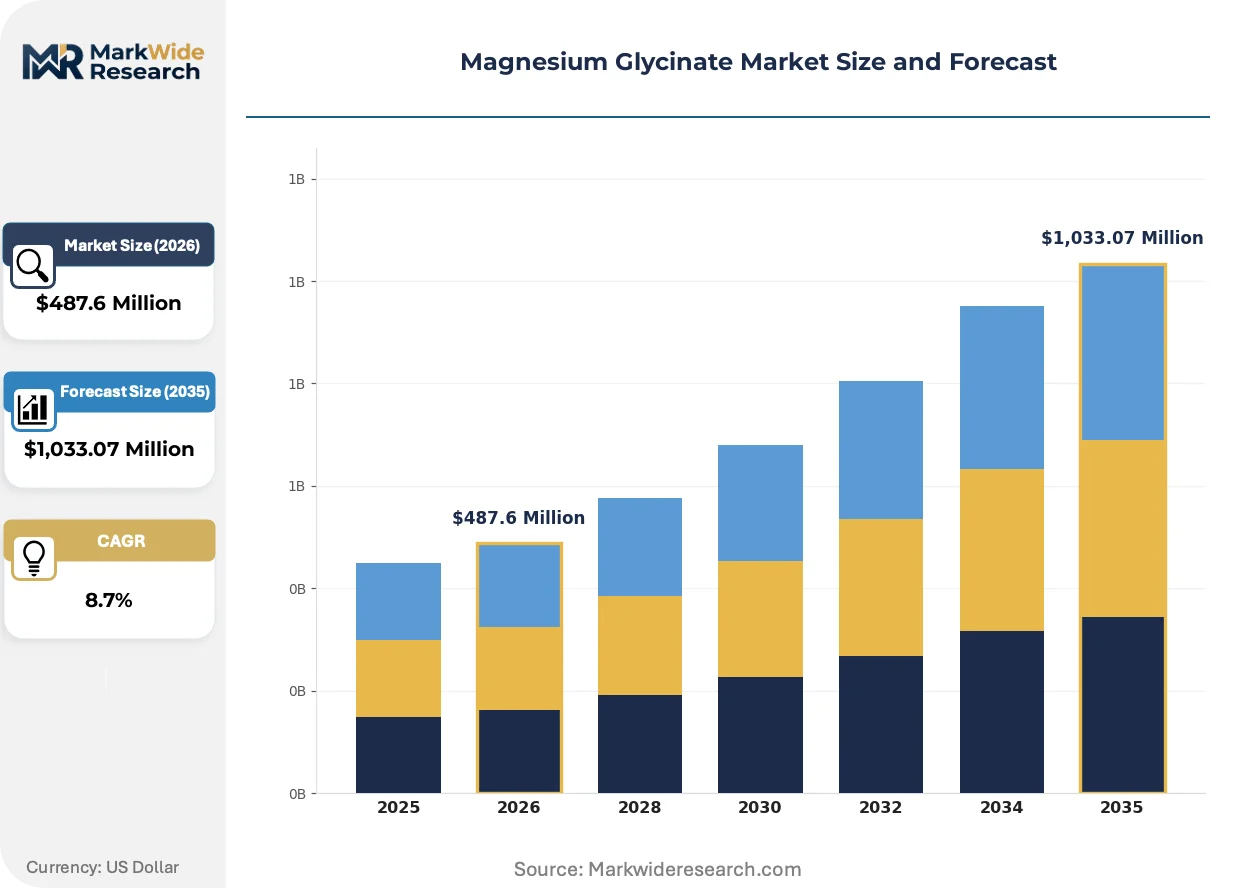
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powder, Liquid End User: Retail Consumers, Fitness Centers, Healthcare Providers, Online Shoppers Application: Muscle Recovery, Sleep Aid, Stress Reduction, Nutritional Supplement Distribution Channel: Pharmacies, Health Stores, E-commerce, Supermarkets |
| Companies Covered | BASF SE, Solvay SA, Ajinomoto Co., Inc., Albion Laboratories, Inc., NovoTech Nutraceuticals Inc., Clariant AG, Dunstan Nutrition Ltd., Avitech Nutrition Pvt. Ltd., OHMG Brands Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Glycinate Market Shifts & Advancements
Spray-drying process optimization and real-time dissolution monitoring are compressing production cycle times while elevating batch consistency. These technical advances intersect with tightening pharmacopeial standards and shifting procurement priorities among institutional buyers.
Continuous manufacturing systems for aqueous chelation reactions are consolidating batch-to-batch variation control. Dietary supplement contract manufacturers with pharmaceutical-grade facilities are adopting these platforms to serve dual-market clients. The technology is consolidating quality differentiation between clinical-grade and commodity mineral suppliers.
REACH registration requirements for glycinate derivatives are extending compliance timelines for new European market entrants. Manufacturers must submit full toxicological dossiers for chelated mineral substances not previously registered under the regulation. Specialty chemical distributors with existing REACH portfolios are capturing intermediary margins from supplement brands lacking in-house regulatory affairs capacity.
Healthcare provider prescribing patterns are shifting magnesium glycinate from retail self-selection to professional-channel recommendation. Functional medicine clinics and integrative health networks are building preferred supplier relationships with verified-quality manufacturers. This channel migration concentrates volume with fewer vendors capable of supporting clinical education and formulary documentation requirements.
Magnesium Glycinate Market Segmentation
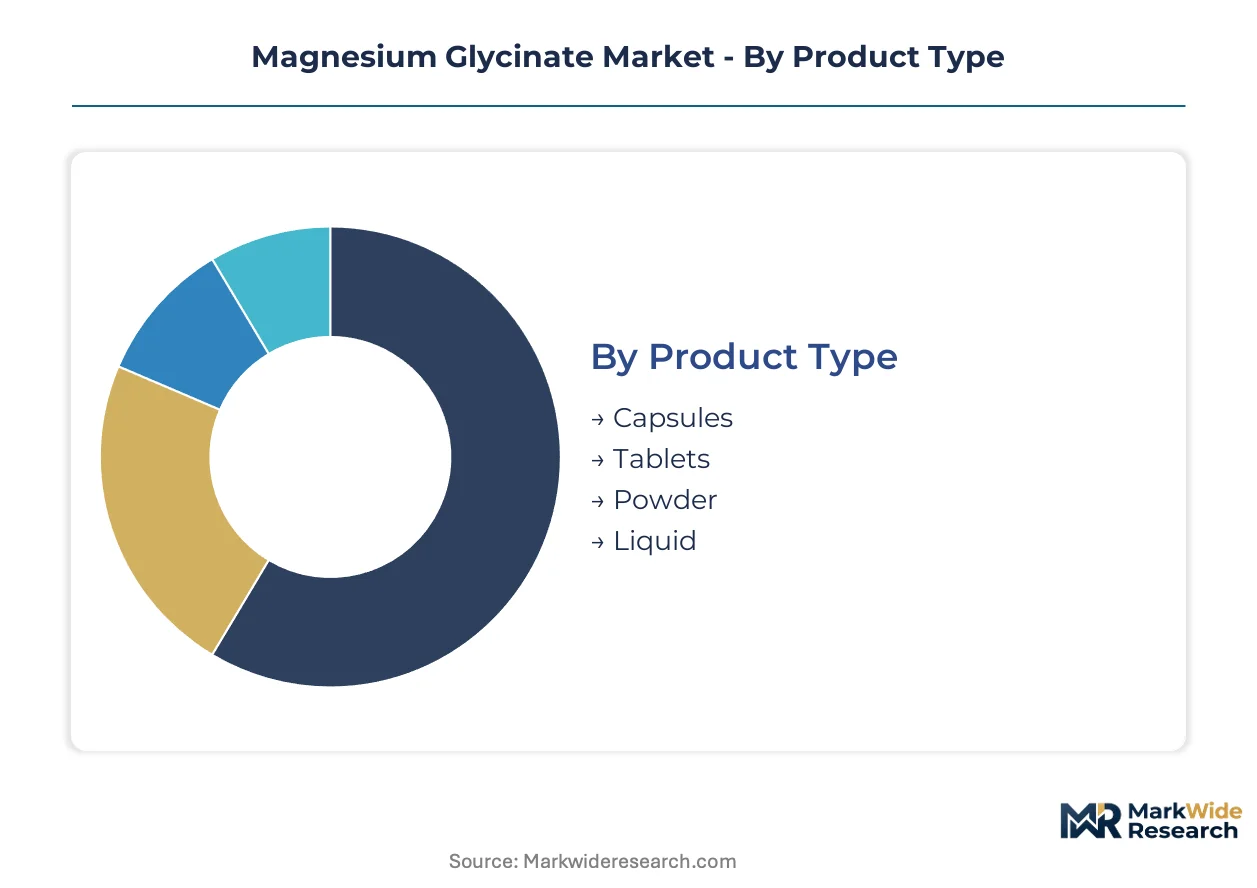
Magnesium glycinate formulations diverge sharply in manufacturing complexity and capital requirements. Spray-drying infrastructure for powder production demands higher upfront investment than tablet compression lines, while liquid formulations require sterile filling equipment that elevates facility costs.
Product Type:
Capital intensity peaks with powder production due to aqueous reaction synthesis and spray-drying equipment, while capsule and tablet formats leverage existing solid-dose infrastructure.
- Capsules:Hard-shell gelatin or vegetable cellulose shells encapsulate magnesium glycinate powder at 10-14% elemental magnesium density. Hospital formulary committees in the United States prioritize capsule formats for perioperative protocols due to precise dosing and dissolution reliability.
- Tablets:Compressed solid dosage forms incorporate binders and disintegrants to meet USP dissolution specifications. Mass-market multivitamin manufacturers favor tablets for cost efficiency in high-volume production runs despite inferior bioavailability metrics relative to chelated alternatives.
- Powder:Spray-dried fine granules enable flexible dosing for compounding pharmacies and personalized nutrition services.
- Liquid:Aqueous suspensions or solutions require preservative systems and sterile manufacturing environments.
Capsules absorb the bulk of installed capacity; powder is expanding most quickly among functional medicine practitioners.
End User:
Customer acquisition costs and margin structures vary dramatically across direct-to-consumer versus institutional procurement channels.
- Retail Consumers:Self-directed purchasers selecting magnesium glycinate for sleep aid and stress reduction applications through mass-market and specialty channels. Subscription-based direct-to-consumer platforms are capturing recurring revenue with higher lifetime value metrics than single-transaction retail.
- Fitness Centers:Collegiate and professional athletic programs standardizing magnesium glycinate in recovery protocols drive institutional procurement contracts with verified-quality manufacturers.
- Healthcare Providers:Functional medicine clinics and integrative health networks building preferred supplier relationships.
- Online Shoppers:Digital-native consumers researching bioavailability claims and third-party testing certifications before purchase.
Retail Consumers dominate transaction volume; Healthcare Providers are climbing the fastest as prescribing patterns shift from self-selection to professional recommendation.
Application:
Clinical validation depth and reimbursement pathways differentiate therapeutic positioning across use cases.
- Muscle Recovery:Athletic programs leverage magnesium glycinate's role in ATP synthesis and electrolyte balance for post-exercise protocols. Sports performance segments exhibit faster velocity as collegiate training facilities expand supplementation budgets.
- Sleep Aid:GABA receptor modulation and melatonin pathway support drive consumer selection for non-habit-forming sleep support. United States healthcare providers increasingly prescribe magnesium glycinate for insomnia management, deepening professional channel penetration.
- Stress Reduction:HPA axis regulation and cortisol modulation applications attract functional medicine practitioners.
- Nutritional Supplement:General wellness positioning in multivitamin and mineral complexes for deficiency prevention.
Sleep Aid captures the largest addressable population; Muscle Recovery is gaining share fastest through institutional athletic contracts.
Distribution Channel:
Channel economics reflect working capital requirements, margin stacking, and regulatory documentation burdens.
- Pharmacies:Brick-and-mortar and mail-order pharmacy chains require lot-level traceability and pharmacist consultation support. CGMP documentation and ISO 17025 testing certificates are mandatory for formulary inclusion.
- Health Stores:Specialty retailers emphasize third-party certifications and clean-label positioning for educated supplement consumers.
- E-commerce:Platform algorithms and review systems compress brand differentiation while enabling direct manufacturer-consumer relationships.
- Supermarkets:Mass-market retail demands economy pricing and high-volume packaging formats.
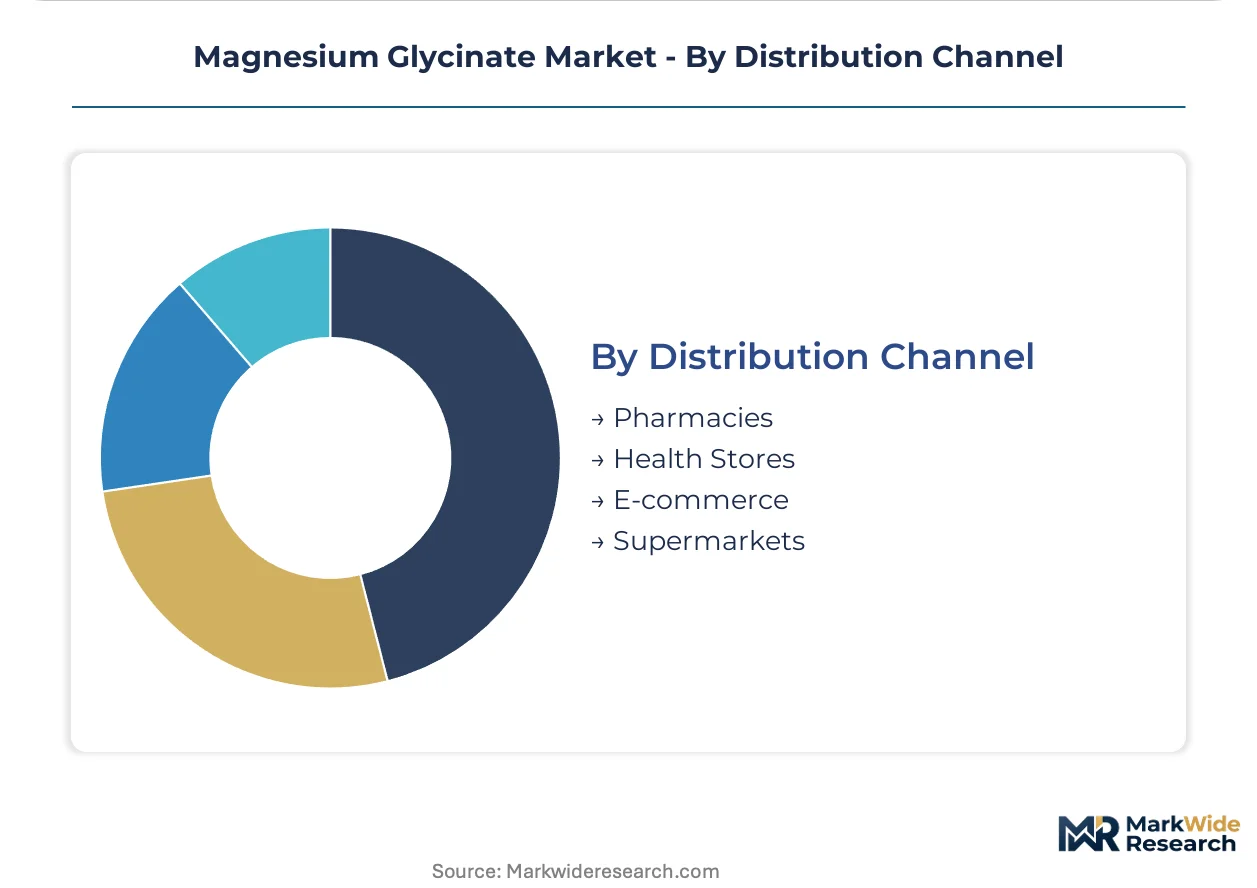
Pharmacies command premium positioning through clinical credibility; E-commerce is expanding most quickly as subscription models displace shelf-based purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates intermediate production of magnesium oxide and glycinate precursors, while the United States and Western Europe absorb the majority of finished formulation output. This geographic split concentrates upstream chemical synthesis in Shandong and Jiangsu provinces, with downstream encapsulation and branding concentrated in North American and European manufacturing hubs.
United States
Hospital formulary committees and collegiate athletic programs drive institutional procurement of magnesium glycinate for perioperative protocols and recovery applications. FDA CGMP enforcement and updated dietary supplement labeling requirements elevate compliance costs for domestic manufacturers. New Jersey and California host contract manufacturing clusters serving both pharmaceutical and nutraceutical clients with dual-market facility certifications.
Germany
Functional medicine practitioners and integrative health networks expand professional-channel prescribing of chelated minerals for stress reduction applications. EFSA novel food assessments and REACH registration requirements for glycinate derivatives extend compliance timelines for new market entrants. The Rhine-Ruhr industrial corridor maintains analytical testing infrastructure supporting ISO 17025 accreditation for third-party verification services.
China
Fermentation-based glycine production and magnesium oxide processing supply global precursor demand for chelate synthesis. SAMR oversight of dietary supplement manufacturing and dual carbon goals pressure energy-intensive spray-drying operations. Shandong province chemical parks concentrate aqueous reaction synthesis capacity, while Jiangsu province hosts specialized mineral chelation facilities serving export markets.
India
Expanding middle-class wellness expenditure and Ayurveda-influenced preventive health practices stimulate consumer demand for bioavailable mineral supplements. FSSAI regulations governing nutraceutical safety and quality standards tighten import requirements for finished formulations. Maharashtra and Gujarat house contract manufacturing operations producing magnesium glycinate for domestic consumption and export to Middle Eastern markets.
United Kingdom
Direct-to-consumer subscription platforms and personalized nutrition services accelerate powder format adoption among sleep aid and stress reduction users. MHRA guidance on borderline substances between food and medicine creates classification uncertainty for high-dose magnesium glycinate products. The Southeast England logistics corridor facilitates e-commerce fulfillment operations targeting European Union customers post-Brexit.
Magnesium Glycinate Market Competitive Landscape
The competitive structure tilts toward chelation technology specialists with captive laboratory capabilities rather than commodity mineral processors. Regulatory compression from FDA CGMP enforcement and EFSA novel food assessments favors manufacturers with integrated analytical verification infrastructure. Three archetypes dominate: fermentation-derived amino acid suppliers with backward integration into glycinate production, dedicated mineral chelation technology licensors, and contract manufacturers with pharmaceutical-grade facility certifications. Capacity expansion and strategic partnerships constitute the primary competitive moves, with players securing preferred supplier relationships through clinical education and formulary documentation support.
Among technology-focused specialists, Albion Laboratories, Inc. occupies a position exemplifying patented chelation intellectual property, while Ajinomoto Co., Inc. represents fermentation-based amino acid integration into magnesium glycinate supply chains. NovoTech Nutraceuticals Inc. anchors the contract manufacturing archetype with dual-site production capabilities across North American facilities. These three entities collectively illustrate the capability segmentation between upstream precursor control, proprietary chelation chemistry, and flexible manufacturing scale serving institutional and direct-to-consumer channels.
| Leading Market Players |
|---|
| BASF SE |
| Solvay SA |
| Ajinomoto Co., Inc. |
| Albion Laboratories, Inc. |
| NovoTech Nutraceuticals Inc. |
| Clariant AG |
| Dunstan Nutrition Ltd. |
| Avitech Nutrition Pvt. Ltd. |
| OHMG Brands Ltd. |
| Others |
Supply & Pricing Matrix
Spray-drying process optimization and continuous manufacturing adoption are compressing production economics while concentrating quality differentiation among chelation specialists with captive laboratory infrastructure. This technical transition simultaneously elevates capital barriers for commodity mineral processors and rewards clinical-grade manufacturers with ISO 17025 accreditation and pharmaceutical-grade facility certifications.
Pricing Analysis
Margin tightening in standard-grade powder formats reflects glycine feedstock volatility and Chinese supply concentration in Shandong and Jiangsu provinces. Three-tier pricing structure across clinical-grade, premium retail, and economy mass-market levels separates verified-quality manufacturers from commodity processors. Price differentiation hinges on chelation validation documentation and third-party testing certification. Mass-market tablet buyers exhibit highest price sensitivity; hospital formulary committees and compounding pharmacies accept premium positioning for bioavailability-verified capsules.
Supply Chain Analysis
Direct-to-manufacturer procurement channels handle institutional athletic program and hospital formulary demand, while specialty distributors serve retail health stores and e-commerce platforms. Upstream concentration in China for magnesium oxide and glycinate precursors draws from fermentation-based amino acid production and mineral processing clusters. Raw material dependencies rest on glycine fermentation capacity, magnesium oxide refining output, and spray-drying equipment availability. Single-source vulnerability in Chinese intermediate production creates geographic risk exposure for downstream formulators in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aqueous chelation reaction technology and real-time dissolution monitoring systems are displacing legacy batch-processing infrastructure, creating capability segmentation between clinical-grade specialists and commodity mineral suppliers.
For Market Incumbents: Extend analytical verification infrastructure to defend formulary positioning against oxide and citrate substitution in mass-market applications. Backward integration into glycinate precursor supply through partnerships with Shandong province fermentation facilities secures feedstock cost control. Investment in continuous manufacturing platforms compresses batch-to-batch variation and elevates quality differentiation versus commodity processors. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting sleep aid and stress reduction applications with powder format flexibility. The United Kingdom and United States personalized nutrition services represent the most penetrable white-space channel. Compounding pharmacy relationships with functional medicine practitioners offer formulary documentation requirements that filter out commodity competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by fermentation-derived amino acid suppliers seeking downstream chelation capabilities or pharmaceutical contract manufacturers expanding nutraceutical verticals. Long-term viability favors chelation technology licensors with patented intellectual property and captive ISO 17025 laboratory infrastructure. Watch EFSA novel food assessment timelines and REACH registration completion rates as inflection indicators for European market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Real-time dissolution monitoring elevates batch consistency for pharmaceutical-grade facility certifications. |
| Backward Integration into Glycinate Precursors | Fermentation capacity control in Shandong province mitigates amino acid feedstock volatility exposure. |
| ISO 17025 Laboratory Accreditation | Third-party testing certificates satisfy FDA CGMP documentation requirements for hospital formulary inclusion. |
| Direct-to-Consumer Subscription Launch | Recurring revenue platforms capture higher lifetime value metrics than single-transaction retail shelf placement. |
| EU Green Deal Alignment Certification | Carbon footprint verification opens premium positioning in environmentally-scored pharmaceutical procurement frameworks. |
Research Methodology
Multi-period observation of hospital formulary committee protocols, collegiate athletic program procurement patterns, and compounding pharmacy channel expansion anchored the trend analysis, supplemented by interviews with dietary supplement contract manufacturing executives, functional medicine practitioners, regulatory affairs specialists at chelation technology firms, and third-party testing laboratory directors. Secondary validation drew from FDA CGMP enforcement records, EFSA novel food assessment databases, USP dissolution specification revisions, and SAMR dietary supplement manufacturing oversight disclosures. Bottom-up volume modeling across product formats triangulated with top-down value aggregation from institutional procurement contract values.
Segment-weighting approaches distributed value across capsules, tablets, powders, and liquid formulations proportional to installed capacity utilization and margin contribution by channel. End-user segmentation incorporated retail consumers, fitness centers, healthcare providers, and online shoppers with distinct customer acquisition cost profiles. Application-based modeling separated muscle recovery, sleep aid, stress reduction, and general nutritional supplement demand with varying clinical validation depth. CAGRs derived from trajectory fitting across the projection horizon incorporated glycine feedstock cost indices and chelation technology adoption curves.
Regulatory timeline delays, glycine fermentation capacity utilization swings, and oxide-citrate substitution elasticity in mass-market multivitamins are the dominant revision risks to forecast outputs. Forecasts reflect assumptions regarding EFSA streamlined assessment pathway maintenance and FDA CGMP enforcement intensity continuity. Periodic stress-testing of base assumptions against REACH registration completion rates and hospital formulary committee guideline updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Detox Products Market
Dietary Supplements
Serotonin Supplement Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Non-Hormonal Steroid Modulators Market
Dietary Supplements
Alpha Lipoic Acid Market
Dietary Supplements
Canine Weight Loss Drugs Market
Dietary Supplements
Nausea Relief Chews Market
Dietary Supplements
Pet Herbal Supplements Market
Dietary Supplements
Menopause Supplement Market
Dietary Supplements
Glucosamine Supplements Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Herbal Tincture Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Global Melatonin Market
Dietary Supplements
Veterinary Dietary Supplements Market