
 Global Light Control Switches Market | 2026-2036
Global Light Control Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Light Control Switches Market Outlook
Buyer concentration in the commercial real estate sector is expanding as facility managers at large property portfolios consolidate vendor relationships across multi-site deployments. Lutron Electronics Co., Inc. leverages its proprietary Clear Connect wireless protocol to sustain premium positioning in spec-grade installations. Schneider Electric SE anchors its presence through integrated building management ecosystems that compete on energy analytics rather than hardware alone.
Light control switches are electromechanical or solid-state devices that interrupt, redirect, or modulate electrical current to luminaires, typically rated for 120-277V AC operation with load capacities from 600W to 2000W depending on dimming topology. Their primary commercial purpose is to enable manual or automated illumination management while supporting energy code compliance and occupant comfort objectives. Smart switches now lead product type dynamics as Wi-Fi and Zigbee variants capture retrofit demand from homeowners seeking app-based scheduling without hub dependency. Dimmer switches retain stronger margin pools in hospitality and upscale residential channels where load-type compatibility and flicker-free performance command specification premiums.
The U.S. EPA ENERGY STAR program and the EU Ecodesign Directive jointly shape product efficiency benchmarks and testing protocols for standby power and controlled load performance. China's GB standards for electrical accessories and the EU CE marking requirements under the Low Voltage Directive govern market access documentation and conformity assessment pathways. Stakeholders must monitor interoperability certification timelines under the Connectivity Standards Alliance and evolving national building electrification codes to align R&D roadmaps with procurement gate criteria.
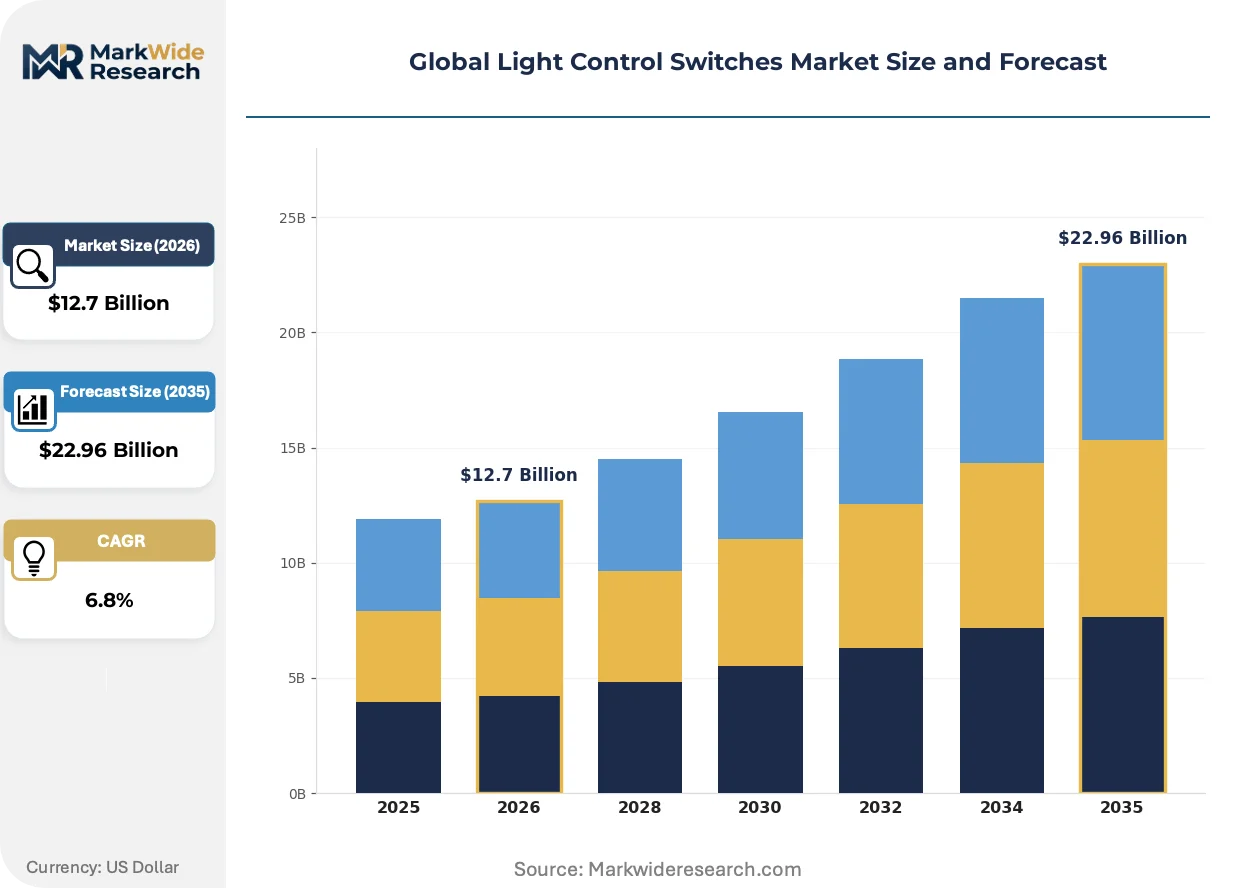
Market Dynamics
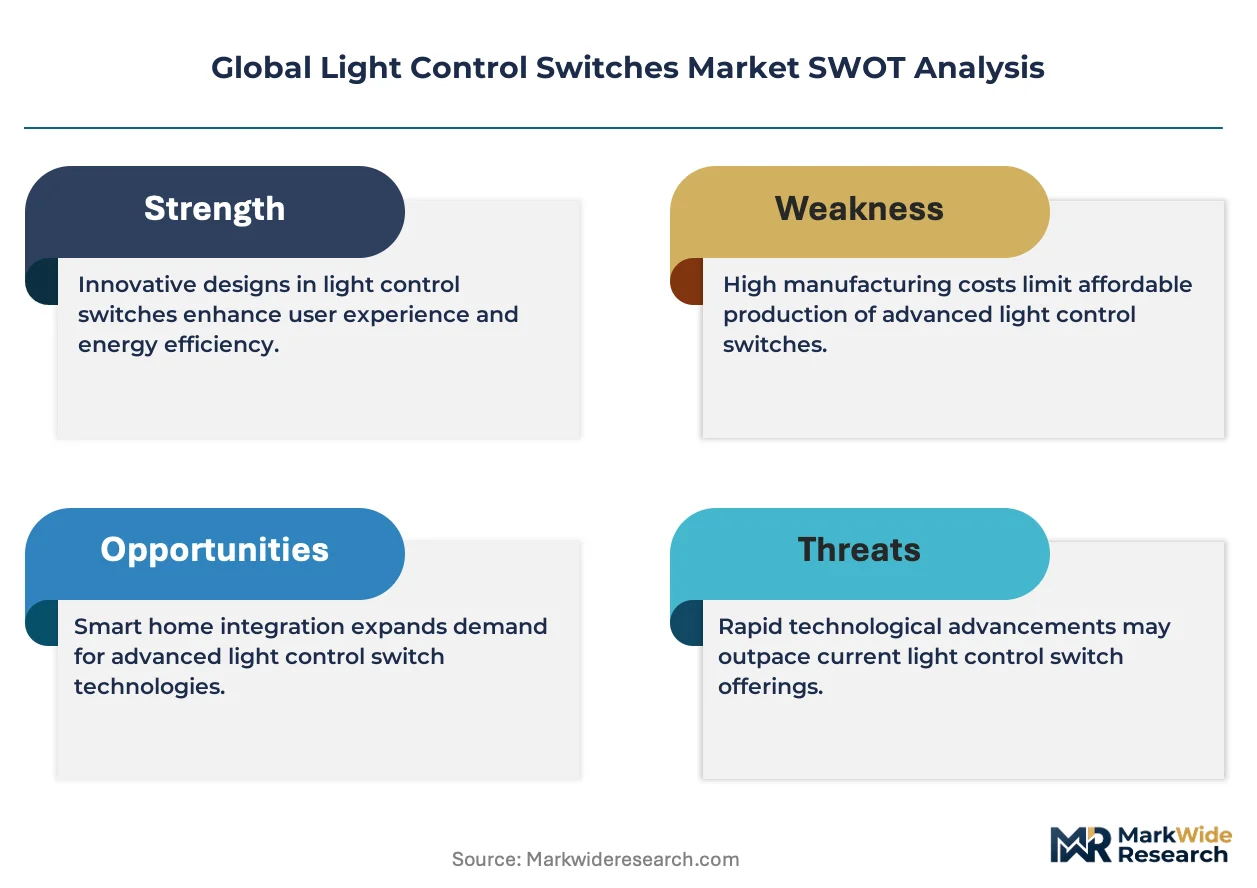
The EU Green Deal's building efficiency mandates are compressing specification timelines while Matter-compatible protocols rewire procurement criteria across residential and commercial channels. Facility managers now bundle lighting controls into broader building management ecosystems, altering vendor selection logic.
Growth Catalysts
- Building Electrification Codes:The EU Ecodesign Directive and U.S. state-level stretch codes mandate automated daylight harvesting in new commercial construction, expanding addressable market for sensor-integrated switches.
- Wi-Fi Mesh Retrofit Demand:Homeowners in Germany, Japan, and the United States bypass hub-dependent systems for direct-to-router smart switches, collapsing installation friction and accelerating replacement cycles.
- Urban Corridor Density:Retrofit-intensive construction in New York, Shanghai, and Mumbai concentrates demand for wireless dimming solutions that avoid rewiring costs in aging electrical infrastructure.
Market Restraints
- Semiconductor Supply Concentration:Zigbee and Thread radio chip fabrication concentrates in Taiwan and South Korea, exposing lead times to geopolitical friction and foundry allocation decisions.
- Copper and Rare Earth Volatility:Dimmer heat-sink copper and magnet materials in smart switch actuators face commodity price swings that compress hardware margins.
- Load Compatibility Complexity:LED driver diversity creates flicker and dropout failures that damage brand reputation and drive support costs for multi-vendor installations.
Strategic Opportunities
- India Tier-2 Urbanization:Smart City Mission funding in Pune, Ahmedabad, and Kochi creates pilot deployment channels for grid-responsive lighting controls in municipal buildings.
- Healthcare Circadian Lighting:Hospital and eldercare facilities adopt tunable-white dimming protocols to align artificial illumination with patient sleep-wake cycles, opening specification-driven premium segments.
- Matter Protocol Convergence:Cross-platform interoperability certification under the Connectivity Standards Alliance collapses ecosystem lock-in, enabling vendor entry across Apple, Google, Amazon, and Samsung home platforms.
Industry Challenges
- Embedded Firmware Talent Scarcity:Shortage of engineers fluent in real-time operating systems and wireless stack optimization delays product roadmaps and extends beta cycles.
- Multi-Protocol Certification Backlogs:Zigbee 3.0, Thread 1.3, and Matter 1.2 compliance testing queues at authorized test houses stretch time-to-market by 4-8 months.
- Legacy TRIAC Compatibility:Maintaining backward compatibility with installed base magnetic and electronic transformers fragments R&D resources across divergent dimming curve calibrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Light Control Switches Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toggle Switches, Dimmer Switches, Smart Switches, Wireless Switches Application: Residential, Commercial, Industrial, Hospitality Technology: Wi-Fi, Bluetooth, Z-Wave, Zigbee End User: Homeowners, Contractors, Architects, Facility Managers |
| Companies Covered | Lutron Electronics Co., Inc., Legrand S.A., Schneider Electric SE, Signify N.V., Acuity Brands, Inc., Leviton Manufacturing Co., Inc., Eaton Corporation plc, Honeywell International Inc., Hubbell Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Light Control Switches Market Strategic Shifts
Wireless protocol unification and edge computing migration are compressing the boundary between standalone switches and full building automation nodes. Vendors now compete on data granularity rather than hardware durability.
Sensor fusion is integrating passive infrared, daylight harvesting, and radar-based occupancy detection into single-gang switch form factors. Hospitality operators in Las Vegas and Singapore deploy these units to eliminate ceiling sensor clusters and reduce installation labor. The technology is integrating HVAC and lighting control decisions at the room level, collapsing the traditional separation between mechanical and electrical trades.
China's GB standards for electrical accessories now incorporate cybersecurity testing requirements for Wi-Fi-enabled devices, following draft frameworks from the MIIT. Manufacturers exporting to the Chinese market must submit to penetration testing and firmware signing protocols that extend certification timelines. Domestic brands with pre-approved security stacks capture specification momentum in government and state-owned enterprise procurement.
Facility management procurement teams now unbundle hardware purchase from commissioning and calibration services, treating lighting controls as subscription-ready infrastructure. Large property portfolios in London and Sydney negotiate enterprise-wide sensor data licenses rather than per-unit hardware pricing. This shift compresses upfront capital requirements while extending vendor lock-in through multi-year analytics contracts.
Global Light Control Switches Market Segmentation
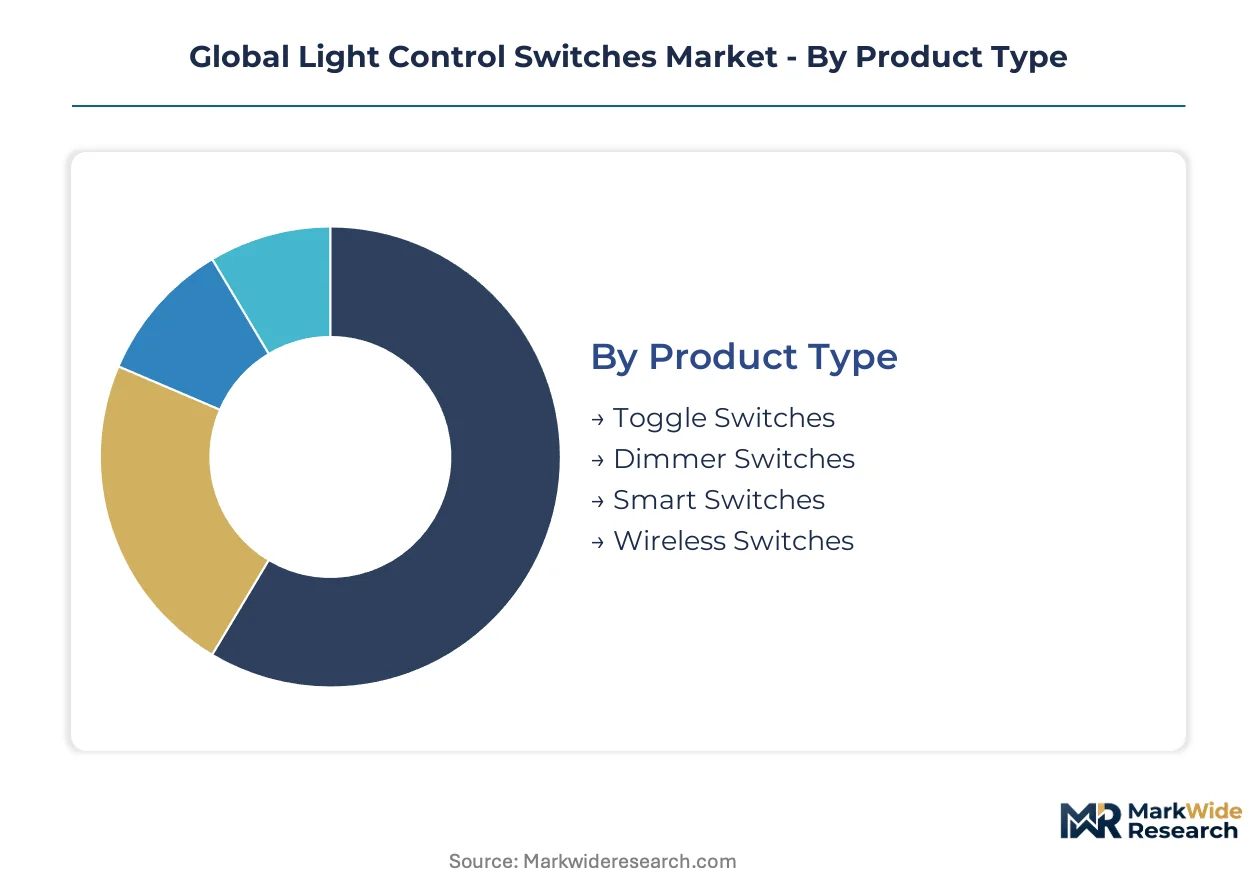
Light control switches fragment across four intersecting dimensions that reshape vendor strategy and channel economics. Product type determines margin architecture, while technology choice locks in ecosystem compatibility and retrofit feasibility. Application and end-user splits dictate specification authority and procurement cadence.
Product Type:
Volume concentrates in legacy electromechanical formats, yet premium capture shifts toward connected and wireless variants.
- Smart Switches:Solid-state devices with embedded radios enable app-based scheduling, voice control, and energy monitoring without hub dependency. Homeowners in Germany, Japan, and the United States drive retrofit demand as Wi-Fi mesh collapses installation friction. Matter protocol convergence accelerates replacement cycles by eliminating ecosystem lock-in.
- Dimmer Switches:TRIAC and ELV topologies modulate voltage waveform to control luminous flux, rated for 600W to 2000W loads depending on topology. Hospitality operators in Las Vegas and Singapore specify flicker-free performance for guest room ambiance, commanding specification premiums through load-type compatibility guarantees.
- Toggle Switches:Electromechanical snap-action mechanisms dominate new construction cost engineering.
- Wireless Switches:Battery-free kinetic harvesting and radio-linked wall controls bypass rewiring in aging infrastructure.
Today's leader: Smart Switches. Tomorrow's challenger: Wireless Switches.
Application:
Retrofit intensity varies sharply by built environment age and energy code stringency.
- Commercial:Sensor-integrated switches with daylight harvesting and occupancy detection satisfy EU Ecodesign Directive and U.S. state-level stretch codes for new construction. Facility managers at large property portfolios consolidate vendor relationships across multi-site deployments, unbundling hardware from commissioning services.
- Residential:Smart home adoption expands across Germany, Japan, and the United States as homeowners bypass hub-dependent systems for direct-to-router connectivity. Urban corridor density in New York, Shanghai, and Mumbai concentrates wireless dimming demand where rewiring costs prove prohibitive.
- Hospitality:Tunable-white dimming protocols align artificial illumination with circadian rhythms in guest rooms and wellness spaces.
- Industrial:Heavy-duty rated switches withstand vibration, moisture, and temperature extremes in manufacturing environments.
Commercial commands current procurement volume. Residential climbs fastest on retrofit momentum.
Technology:
Protocol choice determines interoperability range, power budget, and certification burden.
- Wi-Fi:Direct-to-router connectivity eliminates hub hardware, collapsing installation friction for residential retrofits. China's GB standards now incorporate cybersecurity testing requirements that extend certification timelines for exported devices.
- Zigbee:Mesh networking with sub-GHz and 2.4GHz variants supports large-scale commercial deployments with low latency. Radio chip fabrication concentrates in Taiwan and South Korea, exposing lead times to geopolitical friction.
- Bluetooth:Low-energy variants enable smartphone-native commissioning without dedicated gateways.
- Z-Wave:Sub-GHz proprietary protocol retains installed base in North American security-integrated installations.
Wi-Fi dominates consumer mindshare. Zigbee anchors commercial specification.
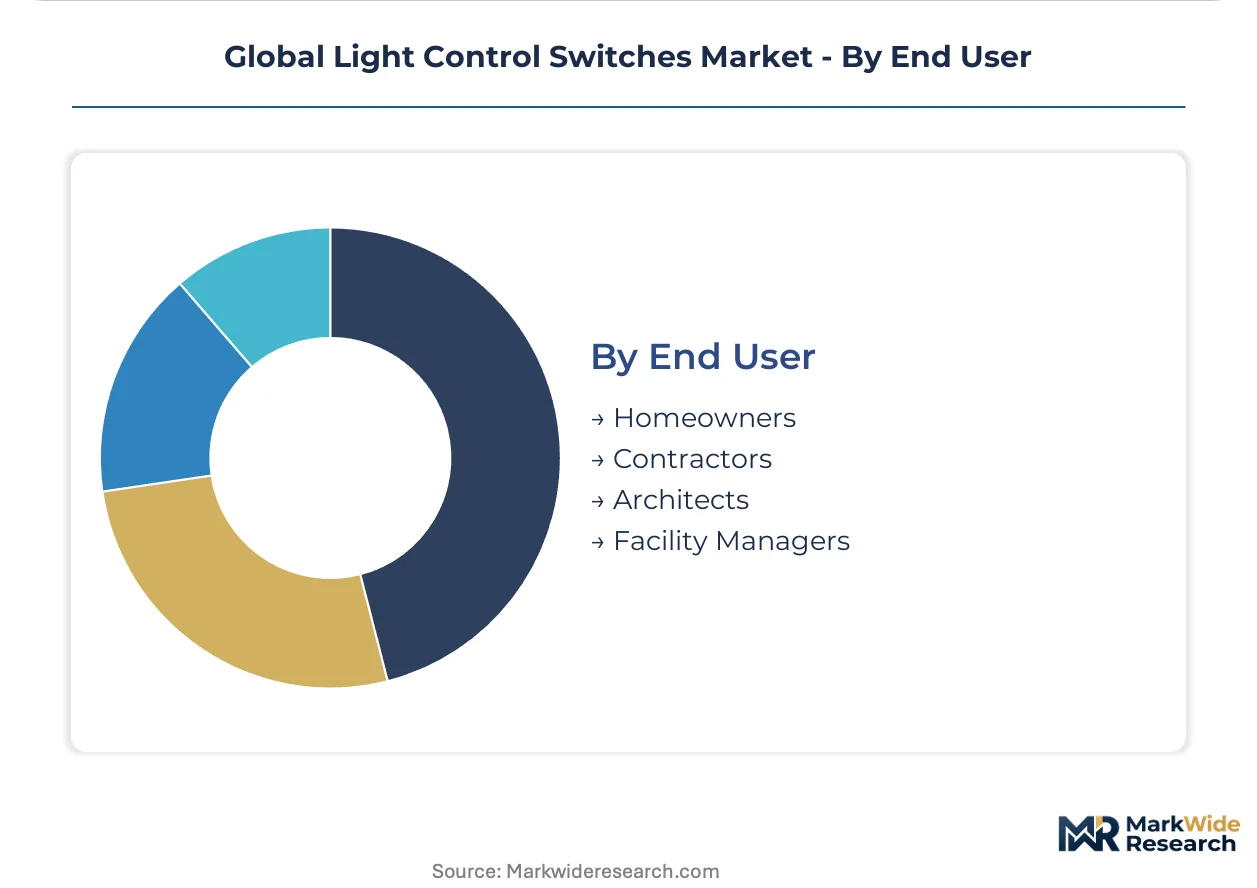
End User:
Specification authority migrates from trade contractors to data-driven facility managers.
- Facility Managers:Large property portfolios in London and Sydney negotiate enterprise-wide sensor data licenses rather than per-unit hardware pricing. Analytics subscriptions extend vendor lock-in through multi-year contracts while compressing upfront capital requirements.
- Homeowners:App-based scheduling and voice control drive replacement cycles in Germany, Japan, and the United States. Wi-Fi mesh retrofit demand accelerates as consumers prioritize installation simplicity over ecosystem depth.
- Contractors:Labor cost pressure favors wireless solutions that reduce rough-in time and permit modifications.
- Architects:Aesthetic integration and circadian lighting protocols influence early-stage specification in healthcare and hospitality.
Facility Managers control commercial procurement. Homeowners drive residential volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded firmware engineers cluster in Taiwan and South Korea, anchoring Zigbee and Thread radio chip fabrication for smart switch vendors worldwide.
United States
Retrofit demand concentrates in aging urban corridors where wireless dimming avoids rewiring costs. The EPA ENERGY STAR program mandates standby power thresholds for controlled load performance. Facility managers in New York and Los Angeles negotiate enterprise-wide sensor data licenses rather than per-unit hardware pricing.
Germany
Homeowners bypass hub-dependent systems for direct-to-router Wi-Fi mesh installations. The EU Ecodesign Directive compresses specification timelines for automated daylight harvesting in commercial construction. Industrial clusters in Bavaria and North Rhine-Westphalia supply specification-grade components for hospitality and healthcare circadian lighting projects.
China
GB standards for electrical accessories now incorporate cybersecurity testing for Wi-Fi-enabled devices. The MIIT draft frameworks require penetration testing and firmware signing protocols. Smart City Mission pilots in Shanghai and Shenzhen deploy grid-responsive lighting controls in municipal buildings.
Japan
METI efficiency standards drive replacement cycles in residential and commercial channels. JIS certification requirements govern market access for imported electrical accessories. Tokyo and Osaka metropolitan areas concentrate demand for tunable-white dimming protocols in eldercare facilities.
India
Tier-2 urbanization accelerates procurement for retrofit-intensive construction in Pune and Ahmedabad. The Smart City Mission funds pilot deployment channels for municipal building automation. BIS standards for electrical accessories create compliance pathways for domestic and imported switchgear.
Global Light Control Switches Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across specification-grade and mass-market tiers. The vendor base stratifies into three layers: integrated building management ecosystems, proprietary protocol specialists, and contract manufacturing scale players. Two strategic archetypes dominate: energy analytics platform vendors and wireless protocol stack owners. Competitive moves center on multi-year analytics subscription contracts and Matter certification convergence to collapse ecosystem lock-in.
Within the diversified industrial tier, Schneider Electric SE and Eaton Corporation plc represent integrated building management approaches. Lutron Electronics Co., Inc. exemplifies the proprietary protocol specialist archetype. These three anchors span French, Irish, and American geographic origins respectively, illustrating how vendor selection logic now prioritizes energy analytics over hardware durability alone.
| Leading Market Players |
|---|
| Lutron Electronics Co., Inc. |
| Legrand S.A. |
| Schneider Electric SE |
| Signify N.V. |
| Acuity Brands, Inc. |
| Leviton Manufacturing Co., Inc. |
| Eaton Corporation plc |
| Honeywell International Inc. |
| Hubbell Incorporated |
| Others |
Value Chain & Pricing Dynamics
Copper heat-sink material and Zigbee radio chipsets trace divergent paths through the value chain, with commodity volatility in Taiwan and South Korea feeding margin compression at the premium tier while firmware talent scarcity inflates commissioning costs for analytics-bundled contracts.
Pricing Analysis
The bundled-vs-unbundled service split now defines competitive positioning. Facility managers negotiate enterprise-wide sensor data licenses rather than per-unit hardware pricing, compressing upfront capital while extending vendor lock-in. Price differentiation hinges on certification grade and after-sales service depth. Pricing pressure stems from semiconductor supply concentration exposing lead times to geopolitical friction. Residential homeowners exhibit highest price sensitivity, while healthcare circadian lighting specifications tolerate premium capture.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated building management ecosystems, while electrical distributors serve retrofit-intensive residential retrofits. Manufacturing concentrates in China, Taiwan, and South Korea. Raw material dependencies include copper for dimmer heat-sinks, rare earth magnet materials for smart switch actuators, and silicon wafers for radio chip fabrication. Single-source vulnerability in Zigbee and Thread radio chip fabrication exposes lead times to foundry allocation decisions. Distribution runs through specification-grade electrical distributors, mass-market retail, and direct enterprise procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Ecodesign Directive compliance costs in Germany and France exceed India's BIS certification burden by multiples, enabling cost-engineered production repositioning.
For Market Incumbents: Deploy multi-year analytics subscription contracts to deepen enterprise lock-in. Consolidate vendor relationships across large property portfolios before Matter protocol convergence collapses ecosystem barriers. Threats include pure-play wireless protocol specialists and embedded firmware talent scarcity delaying product roadmaps.
For New Entrants and Emerging Players: The premium-to-economy tier price-point gap in India's Tier-2 municipal building automation offers white-space entry. Target Smart City Mission pilots in Pune and Ahmedabad with grid-responsive lighting controls. Circadian lighting protocols in Japan's eldercare facilities present specification-driven premium segments. Go-to-market angle: Matter-certified interoperability to bypass ecosystem lock-in.
For Investors and Strategic Acquirers: Consolidation pressure builds where firmware engineering talent scarcity fragments R&D execution across mid-cap specialists. Long-term viability favors vendors with captive protocol stacks or analytics platform integration. Acquisition target archetype: wireless switch specialists with pre-approved security stacks for China's GB standards. Signal to watch: Matter 1.2 certification backlogs at authorized test houses as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-platform interoperability collapses ecosystem lock-in across Apple, Google, Amazon home platforms. |
| Backward Integration into Radio Chip Design | Captive supply of Zigbee and Thread silicon insulates lead times from Taiwan foundry allocation decisions. |
| Healthcare Circadian Lighting Partnerships | Hospital system alliances in Tokyo and Osaka secure specification-driven premium positioning. |
| India Tier-2 Distribution Expansion | Smart City Mission procurement channels in Pune and Kochi capture municipal automation budgets. |
| Enterprise Analytics Subscription Launch | Sensor data licensing in London and Sydney property portfolios extends vendor lock-in beyond hardware. |
Study Parameters
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each market cluster. The research combines structured interviews with facility managers at large property portfolios, smart home product managers at electrical distributors, embedded firmware engineering directors, and regulatory affairs specialists at export-oriented manufacturers. Secondary validation draws from EPA ENERGY STAR filings, EU Ecodesign Directive implementation reports, China's GB standards documentation, Japan's METI efficiency standard updates, and India's BIS certification records. Bottom-up unit economics triangulate against top-down construction spend forecasts.
Granularity-level modeling operates at product type, application, technology protocol, and end-user dimensions, with additional cross-cutting analysis of retrofit intensity by urban corridor age. Value projections incorporate hardware unit pricing, commissioning service bundles, and analytics subscription revenue streams across the analysis window. CAGRs derive from regression against building electrification code adoption curves and smart home penetration rates. Industry-specific inputs include semiconductor lead time indices and copper commodity price volatility bands.
Caveats apply where geopolitical friction in Taiwan Strait shipping lanes or sudden Matter protocol revision timelines could materially shift the outlook. Forecasts embed assumptions regarding EU Green Deal enforcement consistency and China's MIIT cybersecurity framework finalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Zero Speed Switch Market
Switches
Smart Pole-Mounted Switch Market
Switches
Rotary Limit Switches Market
Switches
5G Electromechanical RF Switch Market
Switches
Pressure Switch Market
Switches
China Reed Sensors Switches Market
Switches
Navigation Switches Market
Switches
Smart Plugs and Switches Market
Switches
DC Switchgear Market
Switches
Analog Switches Market
Switches
United States Circuit Breaker Market
Switches
Carrier Router Switch Market
Switches
Japan Reed Sensors Switches Market
Switches
Electronic Shift-By-Wire Selector Modules Market
Switches
Disconnect Switch Market
Switches
Transfer Switch Market