
 Rotary Limit Switches Market | 2026-2036
Rotary Limit Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Limit Switches Market Analytics
Buyer concentration is recalibrating as mid-sized system integrators fragment procurement across specialized distributors rather than consolidating through single-source contracts. Honeywell International Inc. leverages its aerospace channel dominance to maintain premium positioning in safety-critical applications. Siemens AG anchors European demand through deep integration with its own programmable logic controller ecosystems. ABB competes in heavy-industry segments with ruggedized switch designs rated for extreme temperature cycling.
Rotary limit switches are electromechanical devices that convert shaft rotation into discrete electrical signals, typically offering contact ratings up to 10 A at 250 VAC with mechanical endurance exceeding one million operations for industrial-grade units. Their primary purpose is to establish precise position boundaries for rotating machinery, preventing overtravel damage in cranes, wind turbines, and automated guided vehicles. Electrically operated variants capture the dominant margin pool as factories replace mechanical cam switches with solid-state alternatives for predictive maintenance compatibility. Smart technology segments expand fastest as edge-computing architectures embed diagnostic algorithms directly into switch housings. Manufacturing end users sustain the largest volume base, though robotics applications exhibit the steepest trajectory as collaborative robot joints require multi-turn absolute encoding.
The EU Machinery Directive mandates functional safety validation for position-limiting devices in automated equipment, compelling manufacturers to pursue third-party SIL certification. OSHA lockout/tagout regulations in the United States and China's GB standards for crane safety equipment shape regional product specifications and testing protocols. IEC 60947-5-1 provides the foundational international benchmark for switch construction and performance verification. Stakeholders must monitor how wireless connectivity standards evolve to determine whether retrofit digitization or native smart-switch adoption delivers superior lifecycle economics.
Market Dynamics
Smart switch architectures with embedded diagnostics are compressing replacement cycles and forcing incumbents to restructure R&D budgets toward firmware development rather than purely mechanical engineering.
Growth Catalysts
- EU Machinery Directive compliance mandates:Automated equipment manufacturers across Germany, France, and Italy must install SIL-certified position-limiting devices, creating specification pull-through for validated switch suppliers.
- Robotics joint encoding requirements:Collaborative robot manufacturers require multi-turn absolute position feedback, expanding addressable unit volume beyond traditional single-turn crane and wind applications.
- China GB standards for crane safety:Domestic infrastructure buildout and port modernization are accelerating certified switch procurement from state-owned heavy equipment manufacturers.
Market Restraints
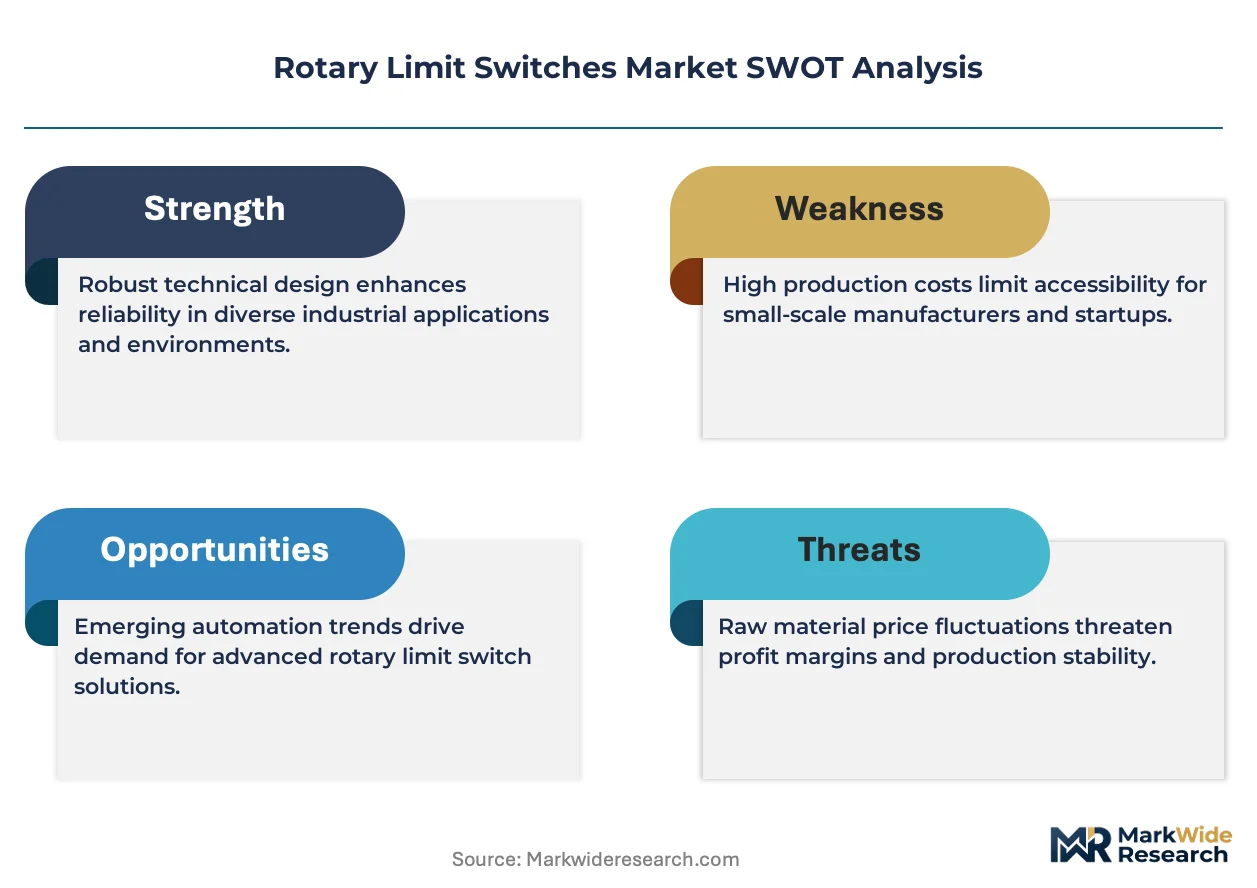
- Copper and rare earth magnet cost volatility:Contact assemblies and encoder magnets face input price swings that compress gross margins for mid-tier manufacturers without forward contracts.
- Supply concentration in precision bearing supply:Japanese and German specialty bearing producers create single-source vulnerability for high-cycle-life switch mechanisms.
- Solid-state encoder substitution:Magnetic and optical encoders eliminate mechanical wear points in new installations, threatening replacement demand for electromechanical switches.
Strategic Opportunities
- India industrial automation underpenetration:PLI scheme incentives for manufacturing localization are creating first-mover advantage for switch suppliers establishing domestic assembly.
- Predictive maintenance convergence:Integration of vibration sensing with position feedback enables condition-based monitoring contracts, expanding recurring revenue per installed base.
- OSHA lockout/tagout regulatory expansion:Proposed rulemaking for energy isolation in automated systems would mandate redundant position verification in US installations.
Industry Challenges
- Firmware engineering talent scarcity:Traditional electromechanical switch manufacturers face recruitment gaps for embedded systems developers needed for smart product lines.
- IEC 60947-5-1 certification timeline compression:Accelerated product development cycles conflict with third-party testing durations, delaying revenue recognition.
- Legacy PLC integration complexity:Brownfield automation retrofits require protocol translation layers that increase commissioning cost and failure modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Limit Switches Market |
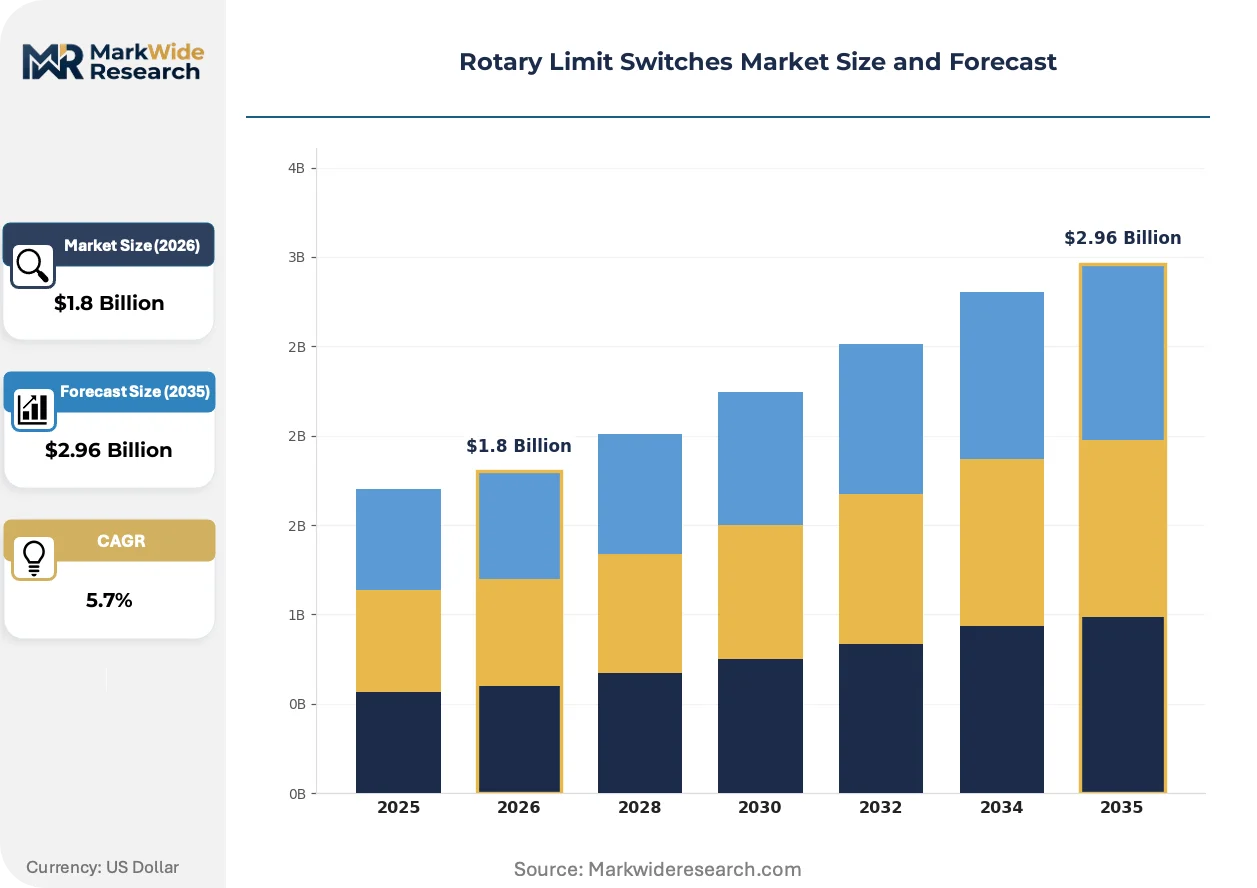
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanically Actuated, Electrically Operated, Programmable, Adjustable Technology: Analog, Digital, Wireless, Smart End User: Manufacturing, Automotive, Aerospace, Robotics Application: Position Sensing, Motion Control, Safety Interlock, Limit Positioning |
| Companies Covered | Honeywell International Inc., Siemens AG, Schneider Electric, ABB, Eaton Corporation plc, OMRON Corporation, Rockwell Automation, Tecno Elettrica Ravasi, AMETEK STC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Limit Switches Market Evolving Landscape
Edge-computing capabilities are migrating into switch housings, transforming position sensors from passive signal generators into active diagnostic nodes that feed digital twin architectures.
IO-Link communication protocols are consolidating device-level connectivity in factory automation networks. Automotive and electronics manufacturers in Germany and South Korea are specifying IO-Link-native switches for plug-and-play replacement. This standardization is consolidating supplier tiers as proprietary bus systems lose specification share.
REACH substance restrictions on certain contact plating materials are forcing redesigns of electrical contact assemblies. Manufacturers serving European wind energy and crane OEMs are qualifying alternative surface treatments to maintain corrosion resistance. The medical and food processing equipment segments are responding fastest due to parallel hygienic design requirements.
Mid-sized system integrators are fragmenting procurement across specialized distributors rather than consolidating through single-source contracts. Industrial distributors with regional technical support capabilities are capturing specification influence previously held by direct manufacturer relationships. This pattern is most visible in the US Midwest and German Ruhr industrial clusters where integrator density is highest.
Rotary Limit Switches Market Segmentation
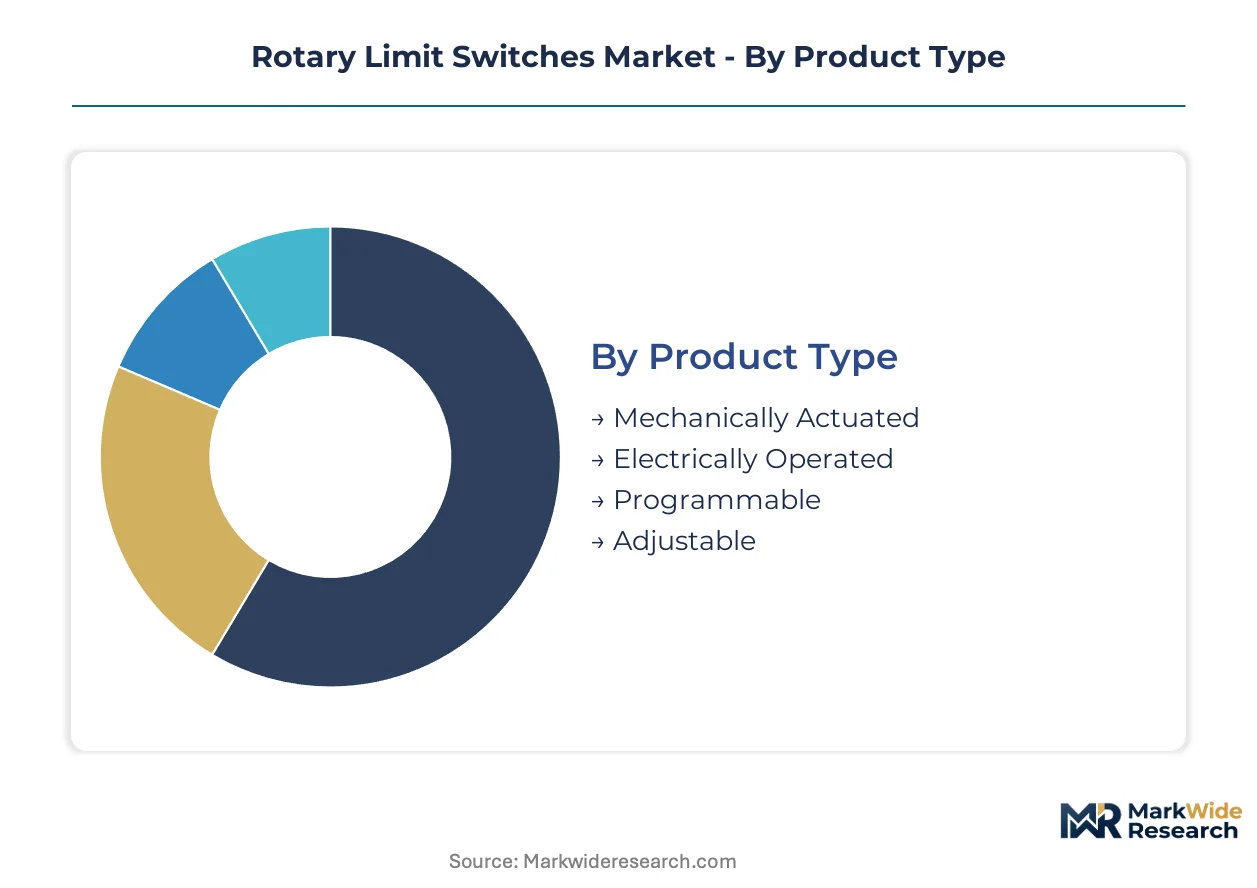
Rotary limit switch buyers select products based on integration complexity, safety certification requirements, and lifecycle cost models. Segmentation reveals how electromechanical heritage competes with solid-state alternatives across divergent application environments.
Product Type:
Cost tier differentiation separates buyers seeking minimum viable position feedback from those requiring predictive maintenance compatibility.
- Electrically Operated:Solid-state designs eliminate mechanical wear through Hall-effect or inductive sensing elements. Demand concentrates in German automotive assembly plants where IO-Link integration enables plug-and-play replacement and reduces commissioning downtime.
- Mechanically Actuated:Cam-operated contact assemblies deliver proven reliability in extreme temperature cycling. Crane OEMs in China and wind turbine manufacturers in Denmark specify these for safety-critical overtravel protection where functional safety certification outweighs maintenance burden.
- Programmable:Firmware-configurable setpoints reduce SKU proliferation for system integrators serving mixed automation portfolios.
- Adjustable:Field-modified actuation positions accommodate brownfield retrofit applications without controller reprogramming.
Volume sits with Mechanically Actuated switches; growth tilts toward Electrically Operated variants.
Technology:
Application maturity determines whether buyers prioritize signal fidelity or connectivity architecture.
- Smart:Edge-computing housings embed vibration sensing and temperature monitoring alongside position feedback. Robotics manufacturers in South Korea specify these for collaborative robot joints requiring multi-turn absolute encoding with embedded diagnostic algorithms.
- Digital:Binary output interfaces simplify PLC integration for mid-sized integrators in the US Midwest industrial corridor.
- Wireless:Battery-powered or energy-harvesting designs eliminate cable fatigue in rotating machinery applications.
- Analog:Continuous voltage or current outputs serve legacy control systems in mature manufacturing installations.
Installed base concentrates in Analog; expansion concentrates in Smart technology segments.
End User:
Customer type dictates procurement channel and technical support intensity.
- Robotics:Collaborative and industrial robot manufacturers require multi-turn absolute position feedback with SIL certification. ABB and KUKA specification engineers in Germany and Switzerland drive demand for compact, high-resolution encoders integrated into joint actuators.
- Manufacturing:Automated assembly line operators prioritize interchangeability and distributor availability over performance optimization.
- Automotive:Paint shop and body-in-white applications demand corrosion-resistant housings and hygienic design compliance.
- Aerospace:MRO providers and OEMs specify aerospace-grade switches for flight control surface position verification.
Manufacturing sustains the largest volume base; Robotics exhibits the steepest trajectory.
Application:
Functional requirement determines contact rating, enclosure integrity, and redundancy architecture.
- Safety Interlock:Redundant contact configurations with forced-guided relay structures prevent single-point failures. EU Machinery Directive compliance mandates in Germany, France, and Italy specify SIL-certified devices for automated equipment energy isolation.
- Position Sensing:Single-turn or multi-turn encoding provides precise angular feedback for crane boom extension and wind turbine blade pitch control.
- Motion Control:High-speed switching characteristics enable closed-loop velocity regulation in servo systems.
- Limit Positioning:End-of-travel detection prevents mechanical overtravel damage in linear actuator applications.
Position Sensing captures the broadest deployment; Safety Interlock commands premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for rotary limit switches clusters in three manufacturing powerhouses where factory automation investments concentrate. China, Germany, and the United States anchor regional procurement volumes through divergent regulatory and industrial ecosystems.
China
Port modernization and domestic infrastructure buildout accelerate certified switch procurement from state-owned heavy equipment manufacturers. GB standards for crane safety equipment mandate functional safety validation, compelling suppliers to pursue third-party certification. Shanghai and Tianjin industrial corridors concentrate demand from automated guided vehicle fleets and wind turbine OEMs.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg specify IO-Link-native switches for plug-and-play replacement and reduced commissioning downtime. EU Machinery Directive compliance mandates SIL-certified position-limiting devices across automated equipment installations. The Ruhr industrial cluster fragments procurement across specialized distributors with regional technical support capabilities.
United States
OSHA lockout/tagout regulations shape regional product specifications for energy isolation in automated systems. The US Midwest industrial corridor exhibits highest integrator density, with mid-sized system integrators fragmenting procurement across specialized distributors. Michigan and Ohio manufacturing bases sustain volume demand for interchangeable distributor-available units.
Japan
Precision bearing supply concentration creates single-source vulnerability for high-cycle-life switch mechanisms serving robotics and semiconductor equipment manufacturers. METI industrial automation incentives support domestic production of smart switch architectures with embedded diagnostics. Nagoya and Osaka industrial zones concentrate demand from collaborative robot joint manufacturers.
India
PLI scheme incentives for manufacturing localization create first-mover advantage for switch suppliers establishing domestic assembly operations. Maharashtra and Gujarat industrial corridors attract automation investments from automotive and electronics manufacturers. BIS certification requirements for industrial electrical equipment shape product specification and testing protocols.
Rotary Limit Switches Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart switch architectures with embedded firmware capabilities. The vendor base stratifies across three tiers: diversified industrial conglomerates with integrated control system portfolios, specialized electromechanical component manufacturers, and regional fabricators serving price-sensitive replacement markets. Two dominant competitive moves are reshaping positioning: firmware engineering talent acquisition to support predictive maintenance compatibility, and strategic partnerships with industrial distributors to capture specification influence in fragmented procurement environments.
Within the diversified industrial conglomerate tier, Honeywell International Inc., Siemens AG, and ABB exemplify archetypes spanning aerospace channel dominance, deep PLC ecosystem integration, and ruggedized heavy-industry designs respectively. Honeywell leverages aerospace certification heritage to maintain premium positioning in safety-critical applications. Siemens anchors European demand through captive supply relationships with its own programmable logic controller ecosystems. ABB occupies a position in heavy-industry segments where extreme temperature cycling ratings command specification priority.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Schneider Electric |
| ABB |
| Eaton Corporation plc |
| OMRON Corporation |
| Rockwell Automation |
| Tecno Elettrica Ravasi |
| AMETEK STC |
| Others |
Value Network & Pricing Analysis
EU REACH substance restrictions on contact plating materials gate qualified supply and premium-tier pricing access, forcing manufacturers to redesign electrical contact assemblies and qualify alternative surface treatments for corrosion resistance in European wind energy and crane OEM specifications.
Pricing Analysis
Volume concentrates in mechanically actuated switches while margins pool with electrically operated variants. Three-tier pricing structure across SIL-certified premium, standard industrial, and economy replacement levels reflects certification grade and IO-Link integration complexity. Price differentiation hinges on functional safety validation and predictive maintenance compatibility. Cost compression in economy tiers is intensifying because copper and rare earth magnet input volatility squeezes mid-tier manufacturers without forward contracts. System integrators in the US Midwest exhibit highest price sensitivity; aerospace MRO providers show least sensitivity due to certification lock-in.
Supply Chain Analysis
Third-party SIL certification and EU Machinery Directive compliance qualification gates upstream component sourcing. Precision bearing supply concentrates in Japan and Germany, creating single-source vulnerability for high-cycle-life switch mechanisms. Contact assemblies draw from copper suppliers and rare earth magnet producers facing commodity price swings. Tariff exposure runs through Japanese specialty bearing imports. Distribution runs through industrial distributors with regional technical support capabilities capturing specification influence from direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as firmware engineering talent scarcity forces players to pursue captive control over embedded systems development rather than outsourced R&D partnerships.
For Market Incumbents: Extend firmware development capabilities through targeted acquisition of embedded systems specialists to counter solid-state encoder substitution threats. Deepen backward integration into precision bearing supply relationships with Japanese and German producers to mitigate single-source vulnerability. Prioritize IO-Link protocol certification investment to maintain specification priority in German automotive assembly plants. For New Entrants and Emerging Players: E-commerce distributor partnerships with regional technical support capabilities offer lowest-friction market entry. India PLI scheme incentives for manufacturing localization represent the most penetrable geography for domestic assembly establishment. Target collaborative robot joint encoding applications in South Korea through direct OEM engineering relationships rather than distributor channels. For Investors and Strategic Acquirers: OSHA lockout/tagout regulatory expansion proposal advancing to final rulemaking is the leading indicator that redundant position verification mandates will reshape US installation specifications. Five-to-ten year viability favors suppliers with predictive maintenance convergence capabilities combining vibration sensing with position feedback. Acquisition target archetype: mid-sized electromechanical specialists with SIL certification heritage and latent firmware engineering capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Engineering Acquisition | Embedded systems talent capture enables smart switch architectures with diagnostic algorithms. |
| IO-Link Protocol Certification | German automotive OEMs specify native IO-Link switches for plug-and-play replacement. |
| India PLI Manufacturing Localization | Domestic assembly operations qualify for production-linked incentive scheme benefits. |
| Precision Bearing Supply Partnership | Long-term agreements with Japanese and German producers reduce single-source risk. |
| Predictive Maintenance Service Contracts | Condition-based monitoring expands recurring revenue per installed base in robotics. |
Research Methodology
Multi-period observation of factory automation investment flows, regulatory certification timelines, and raw material input costs anchored the trend analysis, supplemented by interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors. Secondary validation drew from IEC 60947-5-1 certification databases, EU Machinery Directive implementation records, SEC filings of diversified industrial conglomerates, and customs trade data for precision bearing imports. Bottom-up unit economics triangulated against top-down manufacturing automation spend estimates.
Segment-weighting across product type, technology tier, end-user industry, and application function shaped the analytical framework throughout the forecast period. CAGRs derived from installation base growth rates, replacement cycle compression from smart switch adoption, and regional regulatory mandate implementation schedules. Robotics joint encoding requirements and EU Machinery Directive compliance deadlines served as primary demand drivers in the projection model.
The model holds under stable copper and rare earth magnet pricing, sustained factory automation investment in China, Germany, and the United States, and incremental regulatory expansion rather than abrupt mandate implementation; deviation in trade policy affecting Japanese bearing imports, accelerated solid-state encoder substitution, or delayed OSHA rulemaking would shift volume and value trajectories. A model refresh is warranted upon material change in wireless connectivity standardization or SIL certification timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Level Switches Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
UK Reed Sensors Switches Market
Switches
Mexico Rocker Switch Market
Switches
Fixed Switch Cabinet Market
Switches
Global Switchgear Market
Switches
Analog Switches Market
Switches
ASEAN Switchgear Market
Switches
In-Wall Smart Switch Market
Switches
Global High Voltage Switchgear Market
Switches
Contactor-based Transfer Switch Market
Switches
Carrier Router Switch Market
Switches
Safety Limit Switches Market
Switches
Smart Plugs and Switches Market
Switches
Ethernet Switch Market
Switches
Canada Switch Gear Market