
 Electronic Shift-By-Wire Selector Modules Market | 2026-2036
Electronic Shift-By-Wire Selector Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Shift-By-Wire Selector Modules Market Insights
German transmission component manufacturing is decoupling from mechanical linkage dependency as electrified platforms multiply. ZF Friedrichshafen leverages its integrated driveline portfolio to anchor shift-by-wire contracts with European premium OEMs. Continental sustains R&D intensity in capacitive sensing architectures for rotary selectors. BorgWarner competes through its powertrain-electronics convergence strategy, positioning module supply adjacent to e-axle programs.
Electronic shift-by-wire selector modules replace mechanical transmission linkages with electronic signal transmission to the transmission control unit, typically operating on vehicle bus architectures with Hall effect or capacitive position sensing and redundant signal paths for functional safety. The primary purpose is enabling flexible cabin packaging, autonomous-ready vehicle architectures, and simplified manufacturing for electrified platforms. Rotary and push-button product types dominate premium passenger vehicle applications where cabin space optimization commands priority, while joystick configurations occupy niche positions in heavy equipment where operator ergonomics override aesthetic considerations. Hall effect and capacitive technologies lead volume deployment due to their immunity to environmental contamination and compatibility with sealed cabin environments, with inductive sensing emerging fastest in commercial truck applications demanding extreme durability cycles.
NHTSA guidelines in the United States, EU General Safety Regulation requirements, and China's GB standards for vehicle controls collectively mandate standardized shift-state indication and anti-rollback protections that shape module firmware architectures and validation protocols. ECE R79 in Europe enforces specific directional logic for gear selection interfaces, directly constraining toggle and rotary design freedoms available to Tier-1 manufacturers. Stakeholders must monitor divergence between regional human-machine interface mandates and platform-globalization imperatives as OEMs attempt single-module designs across multiple regulatory jurisdictions.
Market Dynamics
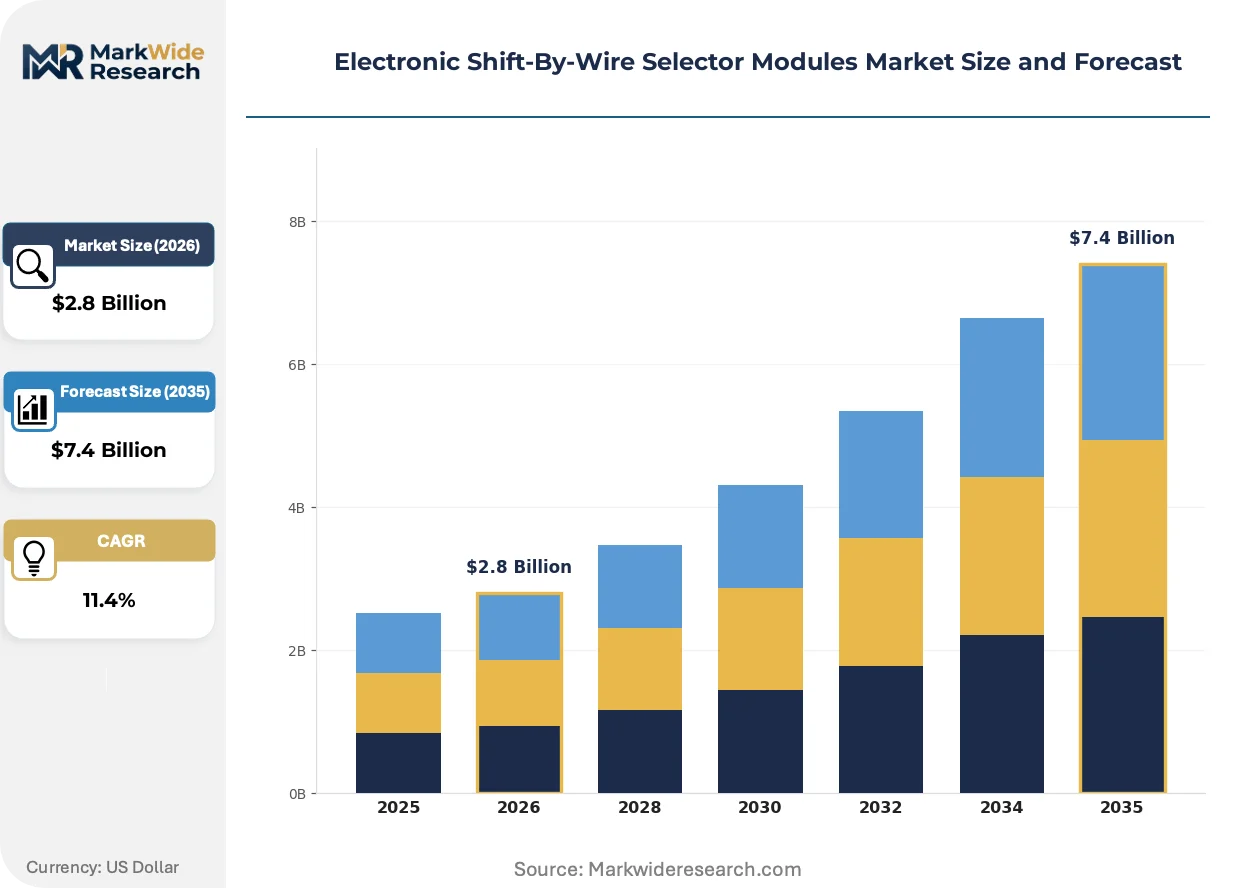
The Electronic Shift-By-Wire Selector Modules Market is undergoing fundamental restructuring as electrified vehicle architectures eliminate mechanical transmission linkages. Platform consolidation around centralized electronic control units is compressing supplier tiers and mandating redundant signal-path competencies.
Growth Catalysts
- NHTSA vehicle control harmonization:Standardized shift-state indication requirements in the United States are accelerating interface validation protocols and creating firmware architecture mandates that favor established module suppliers with safety-certified development processes.
- Capacitive sensing architectures:Rotary and push-button configurations employing capacitive position detection are penetrating luxury passenger vehicle cabins where space optimization and aesthetic minimalism command design priority.
- South Korea's Hyundai-Kia supplier ecosystem:Concentrated demand from this manufacturing cluster is generating volume efficiencies and localized validation capabilities that propagate through regional Tier-2 networks.
Market Restraints
- Hall effect sensor supply concentration:Dependency on specialized magnetic sensing components from limited semiconductor foundries creates input vulnerability and extended lead times for high-volume module programs.
- ECE R79 directional logic constraints:European enforcement of specific gear selection interface patterns restricts toggle and rotary design freedoms available to Tier-1 manufacturers, compressing product differentiation space.
- Mechanical linkage residual demand:Commercial truck and heavy equipment segments continue specifying cable-actuated selectors for extreme durability environments, limiting electronic module addressable market expansion.
Strategic Opportunities
- China's domestic EV platform programs:Indigenous electric vehicle architectures from BYD, NIO, and Xpeng are specifying locally sourced shift-by-wire modules, creating captive supply relationships outside established European supplier networks.
- Inductive sensing convergence:Marriage of inductive position detection with sealed commercial vehicle cabins is opening heavy-duty applications previously resistant to electronic selector adoption.
- EU General Safety Regulation anti-rollback mandates:Firmware-level protection requirements are creating specification differentiation for suppliers with integrated vehicle dynamics control expertise.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification competence remains concentrated among limited engineering teams, constraining supplier expansion and program execution velocity.
- Legacy powertrain integration friction:Hybrid architectures requiring mechanical-electronic selector coexistence demand dual-validation protocols that extend development timelines and testing expenditure.
- Cross-regulatory firmware divergence:Simultaneous compliance with NHTSA, ECE R79, and China's GB standards necessitates multiple software branches that complicate platform globalization strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Shift-By-Wire Selector Modules Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary, Toggle, Push-Button, Joystick Technology: Capacitive, Resistive, Optical, Hall Effect, Inductive Application: Passenger Vehicles, Commercial Trucks, Heavy Equipment, Industrial Machinery End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Vehicle Assemblers |
| Companies Covered | ZF Friedrichshafen, Continental, BorgWarner, Robert Bosch, Denso, Aisin, Magna International, Ficosa, Kostal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Shift-By-Wire Selector Modules Market Trends and Innovations
Interface modality convergence and sensing technology maturation are compressing product lifecycles while elevating firmware complexity requirements. Suppliers must now integrate cabin aesthetic mandates with functional safety imperatives.
Haptic feedback integration with rotary selectors is rewriting cabin interface expectations. Premium German OEMs are deploying force-feedback rotary dials that simulate mechanical detent feel through electromagnetic actuation. This technology is compressing the competitive window for purely passive selector designs and mandating mechatronics competencies among module suppliers.
EU General Safety Regulation requirements for standardized shift-state indication are mandating redundant visual and auditory feedback architectures. European enforcement of these provisions is forcing firmware-level integration with instrument cluster and head-up display systems. Luxury passenger vehicle platforms are absorbing the highest compliance costs, driving consolidation toward suppliers with full-stack HMI development capabilities.
Fleet procurement centralization around integrated vehicle control contracts is displacing discrete module sourcing patterns. Large commercial vehicle operators are specifying shift-by-wire modules as bundled elements within full powertrain electronics packages. North American heavy-duty truck manufacturing corridors are exhibiting this behavioral shift most prominently, with fleet managers prioritizing single-supplier accountability over component-level cost optimization.
Electronic Shift-By-Wire Selector Modules Market Segmentation
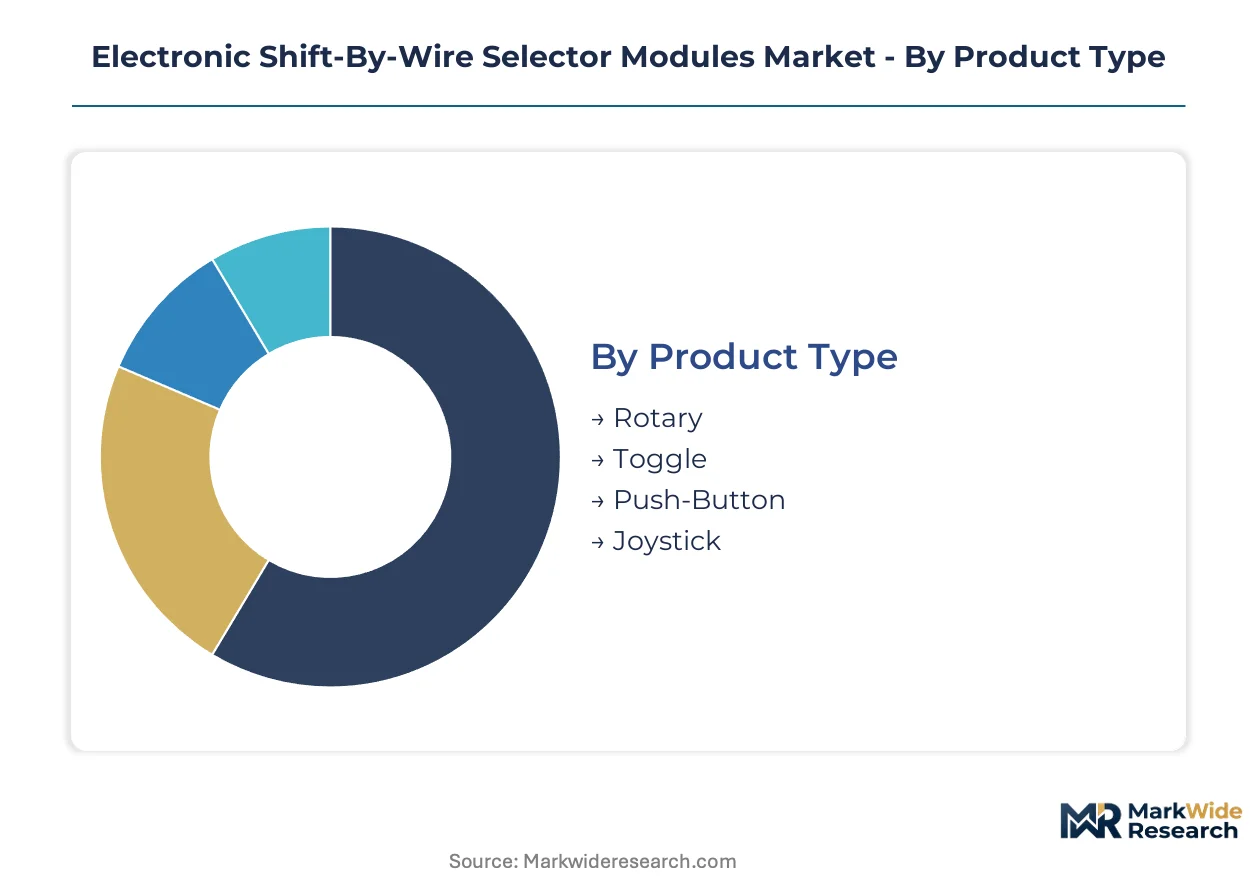
Shift-by-wire selector modules fragment across interface modalities, sensing architectures, and vehicle categories. Each dimension carries distinct certification burdens and supply chain configurations that determine supplier competitiveness.
Product Type:
Supply concentration tilts toward rotary and push-button formats where German and Japanese premium OEMs have consolidated procurement specifications.
- Rotary:Electromagnetic actuation simulates mechanical detent feedback through precision torque modulation. German luxury passenger vehicle platforms command the highest specification density for this format, driven by cabin space optimization mandates and haptic integration requirements.
- Push-Button:Sealed capacitive surfaces with redundant contact detection enable minimalist dashboard integration. South Korean Hyundai-Kia manufacturing clusters specify this format most aggressively for domestic EV platform programs prioritizing interior packaging flexibility.
- Toggle:Bidirectional lever configurations with spring-return neutral positioning occupy hybrid architecture applications requiring tactile gear-state confirmation.
- Joystick:Multi-axis position sensing accommodates heavy equipment operator ergonomics where directional ambiguity carries safety consequences.
Rotary selectors absorb the bulk of installed capacity; push-button configurations are expanding most quickly.
Technology:
Cost tier differentiation separates capacitive and Hall effect volumes from emerging inductive deployments in commercial vehicle segments.
- Capacitive:Non-contact position detection through dielectric field variation enables fully sealed module architectures immune to cabin contamination. German and Japanese premium passenger vehicle applications concentrate demand here, with NHTSA harmonization guidelines accelerating firmware validation standardization.
- Hall Effect:Magnetic field sensing through semiconductor junctions delivers proven reliability across temperature extremes. Foundry supply constraints from limited semiconductor manufacturers create input vulnerability for high-volume module programs serving mass-market OEMs.
- Inductive:Eddy-current position detection withstands extreme vibration cycles in unsealed commercial vehicle cabins. North American heavy-duty truck corridors are adopting this technology fastest as fleet procurement centralizes around integrated powertrain electronics packages.
- Optical:Photoelectric encoding delivers absolute position reference without magnetic interference susceptibility.
- Resistive:Contact-based potentiometric sensing occupies cost-sensitive aftermarket replacement applications.
Hall effect technologies carry the highest shipment volumes; inductive sensing is climbing the fastest as commercial vehicle electrification accelerates.
Application:
Customer type stratification separates passenger vehicle firmware complexity from commercial equipment durability specifications.
- Passenger Vehicles:Rotary and push-button configurations dominate cabin-integrated HMI architectures with redundant signal paths meeting ISO 26262 ASIL-D requirements. China's domestic EV platforms from BYD, NIO, and Xpeng are specifying locally sourced modules outside European supplier networks.
- Commercial Trucks:Inductive sensing modules with sealed environmental protection address fleet procurement centralization around single-supplier powertrain electronics accountability.
- Heavy Equipment:Joystick configurations with mechanical backup linkages persist where operator ergonomics override electronic reliability in extreme duty cycles.
- Industrial Machinery:Standardized CAN bus interfaces with programmable gear logic serve material handling and construction equipment OEMs.
Passenger vehicles command the dominant share of module value; commercial trucks are gaining share fastest through fleet electrification mandates.
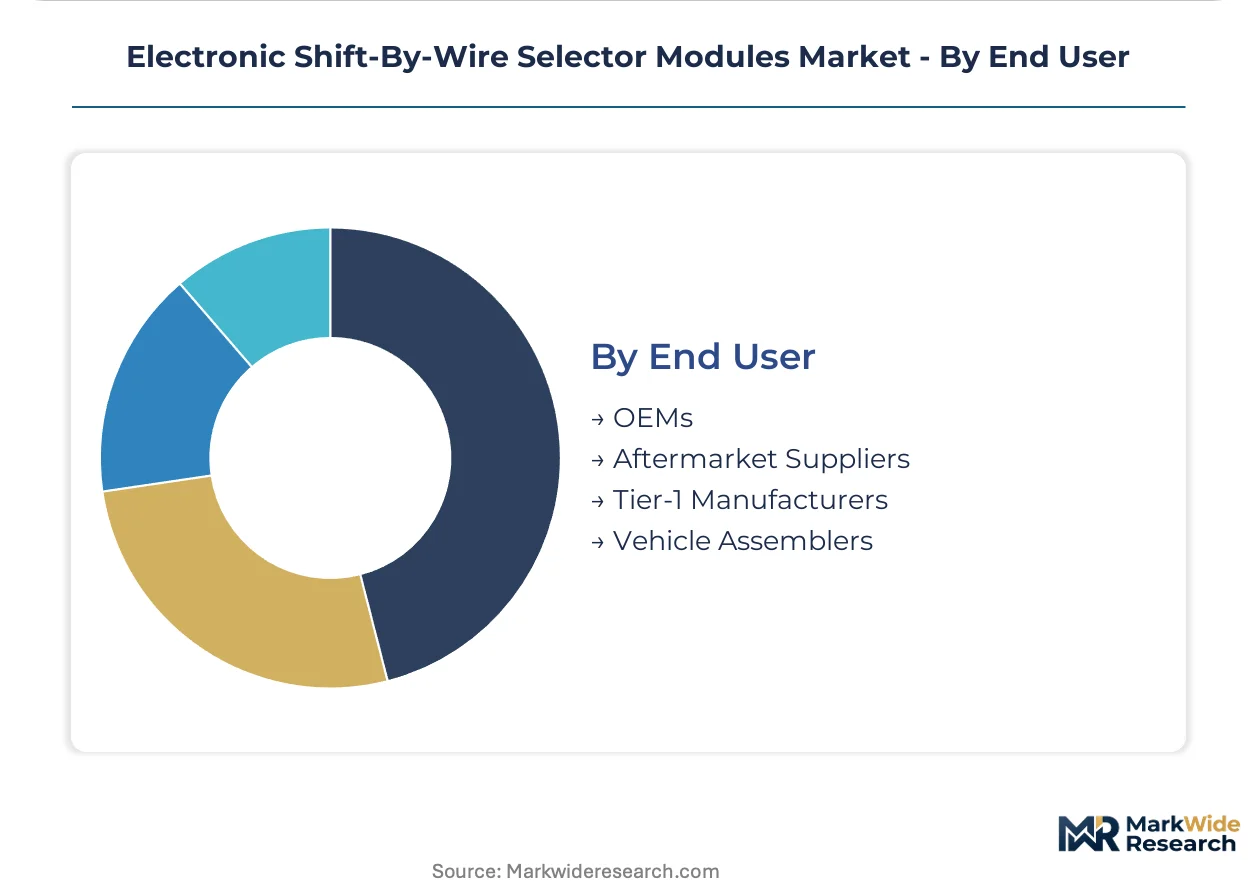
End User:
Margin structure varies sharply between captive OEM engineering and aftermarket price competition.
- OEMs:Direct specification control over firmware architectures and validation protocols enables platform-globalization strategies across NHTSA, ECE R79, and China's GB standard jurisdictions.
- Tier-1 Manufacturers:Integrated driveline and electronics competencies anchor shift-by-wire contracts through full-stack HMI development capabilities.
- Vehicle Assemblers:Contract manufacturing arrangements with localized validation capabilities concentrate in South Korean and Chinese production corridors.
- Aftermarket Suppliers:Resistive and optical retrofit modules serve legacy vehicle conversion demand with reduced functional safety certification requirements.
OEMs and Tier-1 manufacturers capture the preponderance of engineering value; vehicle assemblers are scaling most rapidly through China's domestic EV platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing capabilities in China anchor upstream material flows for Hall effect sensor production. Semiconductor foundry concentration in Taiwan and South Korea shapes component availability timelines. German transmission engineering clusters retain design authority despite manufacturing dispersion.
United States
NHTSA vehicle control harmonization guidelines accelerate interface standardization mandates for domestic OEMs. Federal Motor Vehicle Safety Standards enforcement creates firmware architecture requirements favoring suppliers with ASIL-D certification. Detroit-area engineering corridors concentrate validation expertise for North American truck electrification programs.
Germany
Luxury passenger vehicle platforms from BMW, Mercedes-Benz, and Audi drive rotary selector specification density. ECE R79 directional logic constraints limit design freedoms available to Tier-1 manufacturers. Stuttgart and Munich engineering clusters anchor ZF Friedrichshafen and Continental development activities for European premium OEM contracts.
China
Domestic EV platform programs from BYD, NIO, and Xpeng specify locally sourced shift-by-wire modules outside European supplier networks. GB standards for vehicle controls mandate standardized shift-state indication protocols. Yangtze River Delta manufacturing corridors concentrate module assembly capacity for indigenous electric vehicle architectures.
Japan
Toyota, Honda, and Nissan electrification roadmaps expand push-button and rotary selector adoption in hybrid and battery-electric platforms. METI technology roadmaps prioritize automotive electronics supply chain resilience. Nagoya and Tokyo-Yokohama engineering clusters sustain Denso and Aisin integrated powertrain-electronics competencies.
South Korea
Hyundai-Kia supplier ecosystem concentration generates volume efficiencies and localized validation capabilities. MFDS automotive component certification requirements align with international functional safety standards. Seoul metropolitan area and Busan-Ulsan manufacturing corridors anchor captive supply relationships for domestic EV platform programs.
Electronic Shift-By-Wire Selector Modules Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue inductive sensing specialization for commercial vehicle penetration. The supplier base compresses around three structural tiers: integrated driveline conglomerates with full-stack HMI capabilities, powertrain-electronics convergence specialists, and regional vehicle assemblers with localized validation competencies. Dominant competitive moves include strategic partnerships for firmware co-development and capacity expansion in China and South Korea to serve domestic EV platform demand.
Within the integrated driveline tier, ZF Friedrichshafen and Continental exemplify European engineering authority through transmission-electronics convergence strategies. BorgWarner occupies a position representing powertrain-electronics integration archetypes pursuing e-axle adjacencies. These three anchors demonstrate how functional safety certification concentration and cabin HMI development capabilities determine contract access for premium passenger vehicle platforms.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Continental |
| BorgWarner |
| Robert Bosch |
| Denso |
| Aisin |
| Magna International |
| Ficosa |
| Kostal |
| Others |
Pricing and Supply Chain Analysis
Captive supply relationships within South Korea's Hyundai-Kia ecosystem and China's domestic EV programs anchor both component sourcing positions and pricing power for shift-by-wire modules. This integration pattern insulates preferred suppliers from spot-market volatility while compressing margins for non-integrated competitors serving fragmented aftermarket demand.
Pricing Analysis
Warranty and validation-service bundling separates Tier-1 module pricing from unbundled aftermarket alternatives, with ASIL-D certification costs embedded in long-term supply agreements rather than per-unit transactions. Three-tier pricing structure across premium rotary configurations, standard push-button formats, and economy-grade resistive replacements reflects firmware complexity and functional safety investment levels. Cost compression in the economy tier intensifies as Chinese domestic suppliers capture volume through localized GB-standard validation. Fleet procurement managers at North American heavy-duty truck operators exhibit lowest price sensitivity due to single-supplier accountability priorities, while aftermarket distributors face acute margin pressure from unbranded Asian imports.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Seoul, and Shanghai coordinate hub-and-spoke fulfillment patterns for finished modules, with semiconductor foundries in Taiwan and South Korea feeding Hall effect sensor production. Rare earth magnet processing in China and specialized magnetic sensing wafers from limited foundry sources create dual-input dependencies for high-volume programs. Single-source vulnerability concentrates in ASIL-D-certified firmware engineering teams, where ISO 26262 competence scarcity constrains supplier expansion. Distribution runs through OEM-integrated Tier-1 channels for passenger vehicle platforms, while commercial truck fleets increasingly specify modules within bundled powertrain electronics packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic shift-by-wire selector modules occupy a technology-transition phase as capacitive and inductive sensing architectures displace legacy Hall effect dominance across passenger and commercial vehicle segments respectively.
For Market Incumbents: Anticipate firmware divergence risk across NHTSA, ECE R79, and China's GB standard jurisdictions by embedding regional compliance teams within platform engineering centers. Prioritize backward integration into capacitive sensing wafer supply through foundry partnerships in Taiwan and South Korea, securing volume allocation ahead of semiconductor capacity constraints. Defensive consolidation through acquisition of inductive sensing specialists will preempt commercial vehicle electrification entrants. For New Entrants and Emerging Players: Direct digital-channel engagement with Chinese domestic EV platform engineering teams at BYD, NIO, and Xpeng bypasses entrenched European supplier relationships. Heavy equipment joystick configurations with mechanical backup linkages present the most penetrable white-space target, as incumbent focus concentrates on passenger vehicle cabin integration. Position through aftermarket retrofit modules for legacy commercial fleet conversion, leveraging reduced functional safety certification requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated driveline conglomerates seeking full-stack HMI capabilities, with IPO viability contingent on demonstrated cross-OEM platform wins. Long-term viability favors suppliers with captive relationships to electrified vehicle architectures rather than hybrid-transition exposure. Watch inductive sensing adoption velocity in North American heavy-duty truck procurement as the inflection indicator for commercial segment tipping.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces firmware branch complexity across NHTSA and ECE R79 regulatory jurisdictions for global OEMs. |
| Battery Supply Agreement | Secures semiconductor foundry allocation for Hall effect sensor production in Taiwan and South Korea. |
| Software-Defined Vehicle Investment | Enables redundant signal-path integration with centralized electronic control unit architectures. |
| Geographic Manufacturing Footprint | Localizes validation capabilities in China's Yangtze River Delta for domestic EV platform programs. |
| Charging Infrastructure Partnership | Expands addressable market through fleet electrification procurement centralization in North America. |
Research Methodology
Multi-period observation of module shipment volumes, platform electrification roadmaps, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, semiconductor foundry account managers, and fleet operations managers at North American heavy-duty truck operators. Secondary validation drew from NHTSA FMVSS documentation, ECE R79 regulatory texts, China's GB standard publications, vehicle production databases, and SEC filings from listed automotive component manufacturers. Bottom-up module demand modeling triangulated against top-down electrified vehicle production forecasts.
Input-output matrices mapped sensing technology adoption rates against vehicle segment electrification timelines across the projection horizon, with segmentation dimensions spanning interface modality, position detection technology, vehicle class, propulsion architecture, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and new platform penetration curves, incorporating Hall effect sensor foundry capacity constraints and inductive sensing durability validation timelines as industry-specific forecast inputs.
The model holds under stable regulatory harmonization trajectories and continued electrified platform proliferation; deviation in semiconductor supply availability or regional trade restriction escalation would shift module availability timelines and pricing structures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Digital Crosspoint Switches Market
Switches
Drive Mode Selector Switch and Controller Systems Market
Switches
Low Voltage Switchgear Market
Switches
KVM Switch Market
Switches
Europe Switchgear Market
Switches
Analog Switches Market
Switches
Carrier Router Switch Market
Switches
Smart Dimmer Switch Market
Switches
Fusible Switches Market
Switches
Rocker Switch Market
Switches
Europe Low Voltage Switchgear Market
Switches
Global Disconnector Switch Market
Switches
5G Solid State Switches Market
Switches
High-Voltage Disconnect Switch Market
Switches
Temperature and Pressure Switches Market
Switches
North America Low Voltage Switchgear Market