
 Transfer Switch Market | 2026-2036
Transfer Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Transfer Switch Market Analysis
North American manufacturing expansion is rewriting supply dynamics for electromechanical power components. Schneider Electric leverages extensive distribution networks to sustain project fulfillment across utility-scale installations. Eaton Corporation anchors its position through deep integration with North American electrical contractors and specification engineers. Cummins Inc. competes by bundling transfer switches with generator sets, capturing packaged power system contracts.
A transfer switch is an electromechanical device that automatically or manually transfers electrical load between two sources, typically operating within voltage classes from 120V to 600V and interrupting ratings up to 200kA, designed to ensure uninterrupted power delivery for critical operations. Its primary industrial purpose centers on isolating failed utility feeds and connecting standby generation without manual intervention during outage events. Automatic transfer switch configurations dominate commercial and data center installations where sub-cycle transfer times prevent server disruption and equipment damage. Manual transfer switch variants retain substantial share in residential and light commercial segments where cost sensitivity outweighs automation requirements. Electronic and digital technology segments capture expanding margin pools as microprocessor-based controllers enable remote monitoring, predictive maintenance scheduling, and integration with building management systems.
NFPA 70 (National Electrical Code) and UL 1008 standards govern product safety and performance testing for transfer switches sold in the United States, while NERC reliability mandates enforce backup power redundancy for bulk electric system facilities. IEEE 1547 interconnection standards shape how distributed energy resources integrate with grid-tied transfer equipment, influencing product design priorities for bidirectional power flow. Stakeholders must monitor evolving state-level carbon reduction mandates that incentivize solar-plus-storage microgrids, requiring transfer switch architectures capable of seamless source selection among utility, generator, and battery inputs.
Market Dynamics
NERC reliability mandates and hyperscale data center construction are compressing procurement cycles for automatic transfer switches, forcing manufacturers to pre-certify products for rapid deployment across redundant electrical pathways.
Growth Catalysts
- NERC CIP-014 Physical Security Standards:Bulk electric system operators must harden substations against physical threats, mandating backup power redundancy that drives automatic transfer switch installations across transmission facilities.
- Hyperscale Data Center Clustering:Cloud providers in Northern Virginia, Dallas-Fort Worth, and Phoenix are building multi-hundred-megawatt campuses requiring synchronized transfer switch arrays for seamless generator synchronization.
- Lithium-Ion Battery Cost Curves:Declining battery storage economics enable solar-plus-storage microgrids that demand bidirectional transfer switch architectures capable of arbitrating between utility, generator, and battery sources.
Market Restraints
- Copper and Electrical Steel Volatility:Raw material input costs for contact assemblies and magnetic cores fluctuate with commodity markets, compressing margins on standard-duty transfer switch lines.
- Contractor Channel Concentration:North American specification authority concentrates among a limited pool of electrical engineering firms, creating gatekeeper friction for new market entrants seeking project approval.
- UL 1008 Certification Timeline:Extended testing protocols for short-circuit withstand ratings delay product launches by six to twelve months, freezing development capital in regulatory compliance.
Strategic Opportunities
- Edge Computing Node Proliferation:Distributed IT infrastructure in secondary metros creates demand for compact automatic transfer switches rated below 400A, a segment underserved by utility-scale manufacturers.
- IRA Clean Energy Tax Credits:Investment tax credits for standalone storage and microgrid investments incentivize transfer switch configurations that integrate battery energy storage systems with existing generator backup.
- Predictive Maintenance Platforms:Cloud-based condition monitoring services create recurring revenue streams by retrofitting installed transfer switches with IoT-enabled contact wear sensors and thermal monitoring.
Industry Challenges
- Power Systems Engineering Talent Scarcity:Specialized expertise in protective relay coordination and generator set synchronization commands premium compensation, constraining manufacturer technical support capacity.
- Legacy Electromechanical Retrofit Complexity:Aging installed base of manually operated transfer switches requires custom engineering for automation upgrades, fragmenting project economics and extending sales cycles.
- Interoperability Testing Burden:Each generator manufacturer maintains proprietary control protocols, forcing transfer switch vendors to maintain extensive compatibility libraries and field commissioning support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transfer Switch Market |
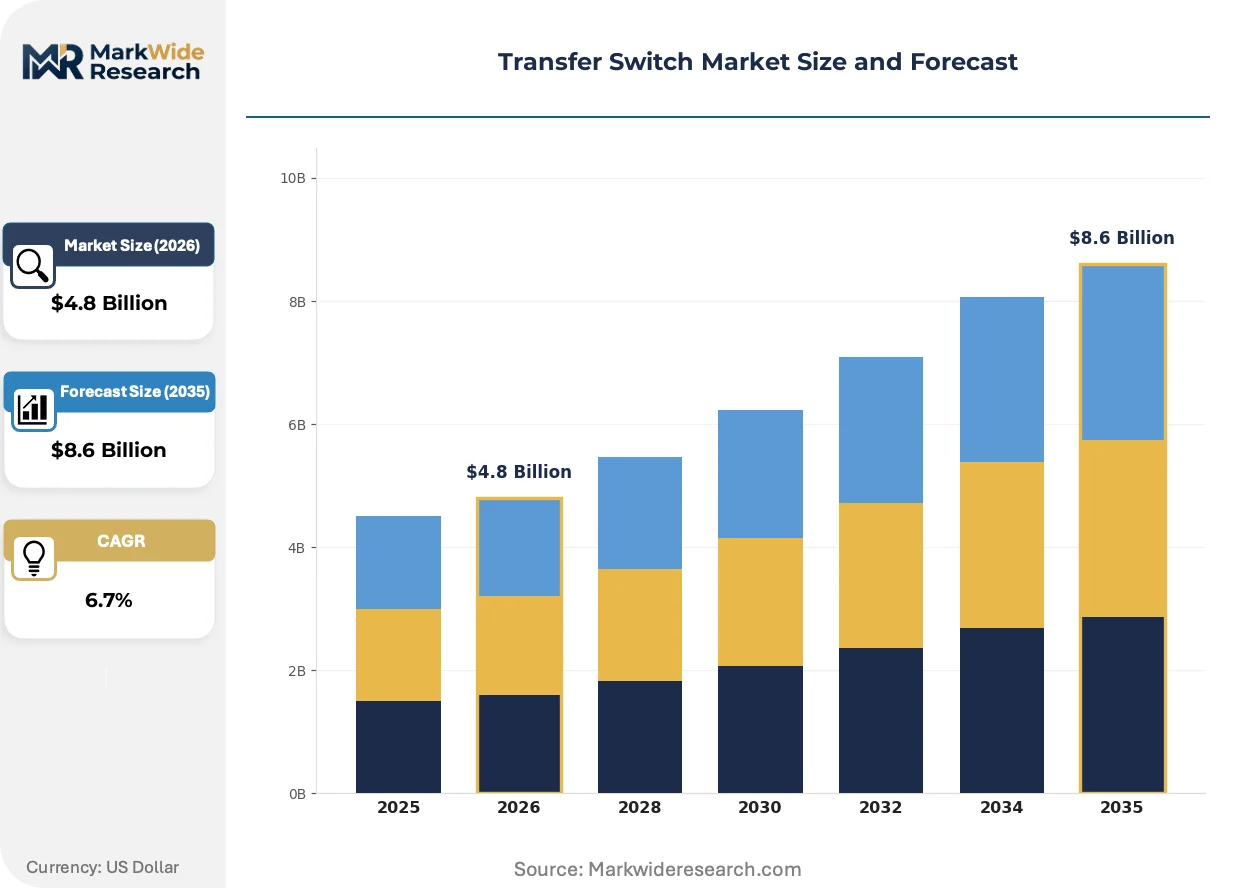
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Transfer Switch, Manual Transfer Switch, Bypass Isolation Switch, Switchgear End User: Commercial Facilities, Industrial Plants, Data Centers, Residential Buildings Technology: Mechanical, Electronic, Hybrid, Digital Installation: Wall-Mounted, Floor-Standing, Outdoor, Indoor |
| Companies Covered | Schneider Electric, Eaton Corporation, Generac Holdings, Cummins Inc., ABB Ltd., Siemens AG, Kohler Co., Caterpillar, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transfer Switch Market Emerging Trajectories
Digital control architectures and bidirectional power flow requirements are redefining transfer switch design priorities, compressing the gap between traditional electromechanical reliability and software-defined energy management.
Solid-state switching technology employing silicon carbide power semiconductors is migrating from experimental installations to commercial data center deployments. Sub-cycle transfer times below four milliseconds eliminate voltage sags that disrupt server power supplies. Hyperscale operators in Texas and Arizona are specifying solid-state transfer switches for critical IT loads, compressing the traditional electromechanical market at ratings below 800A.
IEEE 1547-2018 interconnection standards now govern distributed energy resource integration with utility grids, mandating ride-through capabilities and anti-islanding protection that complicate transfer switch control logic. Manufacturers must engineer programmable controllers capable of interpreting multiple grid condition signals and executing source transfers without violating interconnection agreements. Commercial and industrial microgrid projects in California face the strictest compliance timelines, driving early adoption of IEEE 1547-certified transfer equipment.
Specification authority is consolidating among national electrical contractors with integrated design-build capabilities, displacing traditional distributor-led sales models. Large infrastructure projects now route transfer switch selection through engineering-procurement-construction firms that bundle electrical infrastructure as single-source contracts. This concentration is most visible in data center construction corridors across Northern Virginia, where EPC firms pre-qualify transfer switch vendors for multi-year master service agreements.
Transfer Switch Market Segmentation
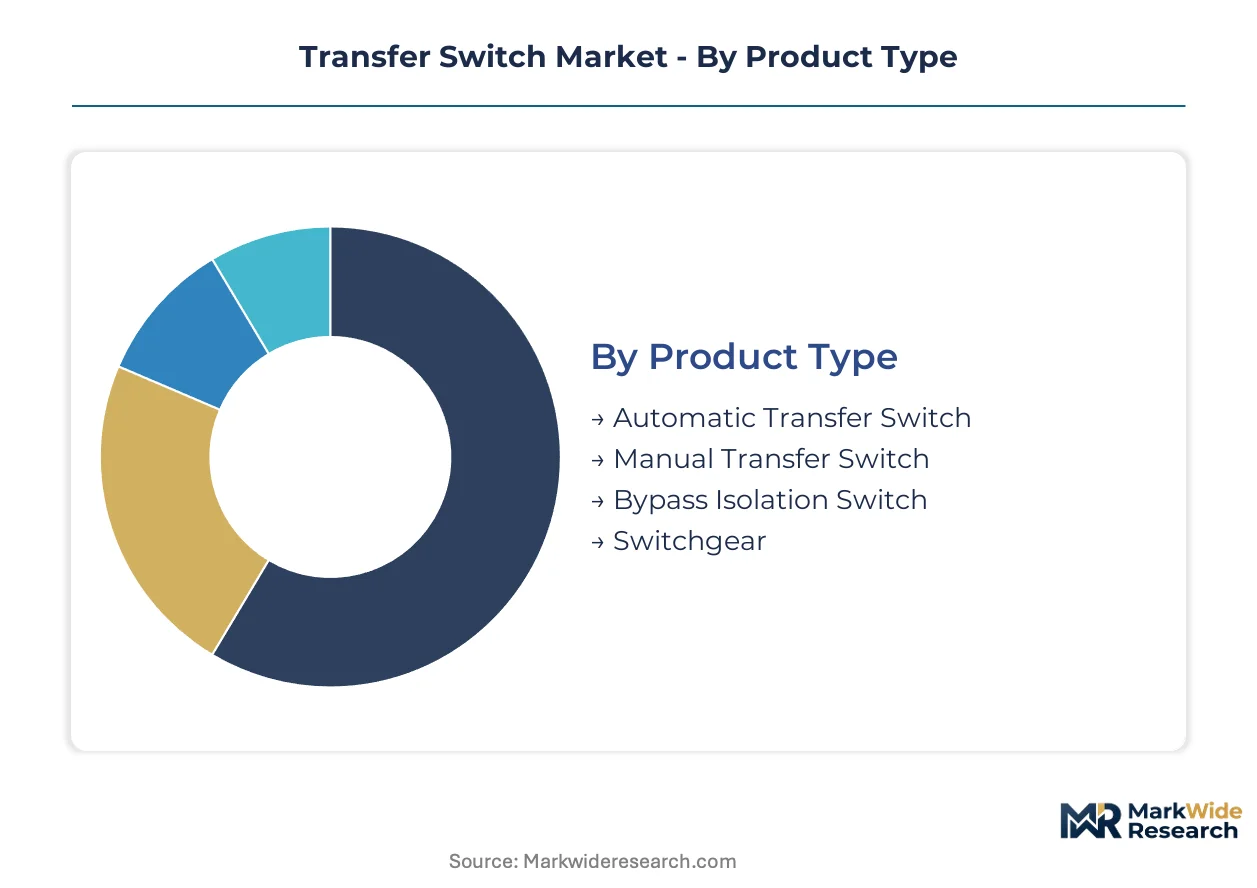
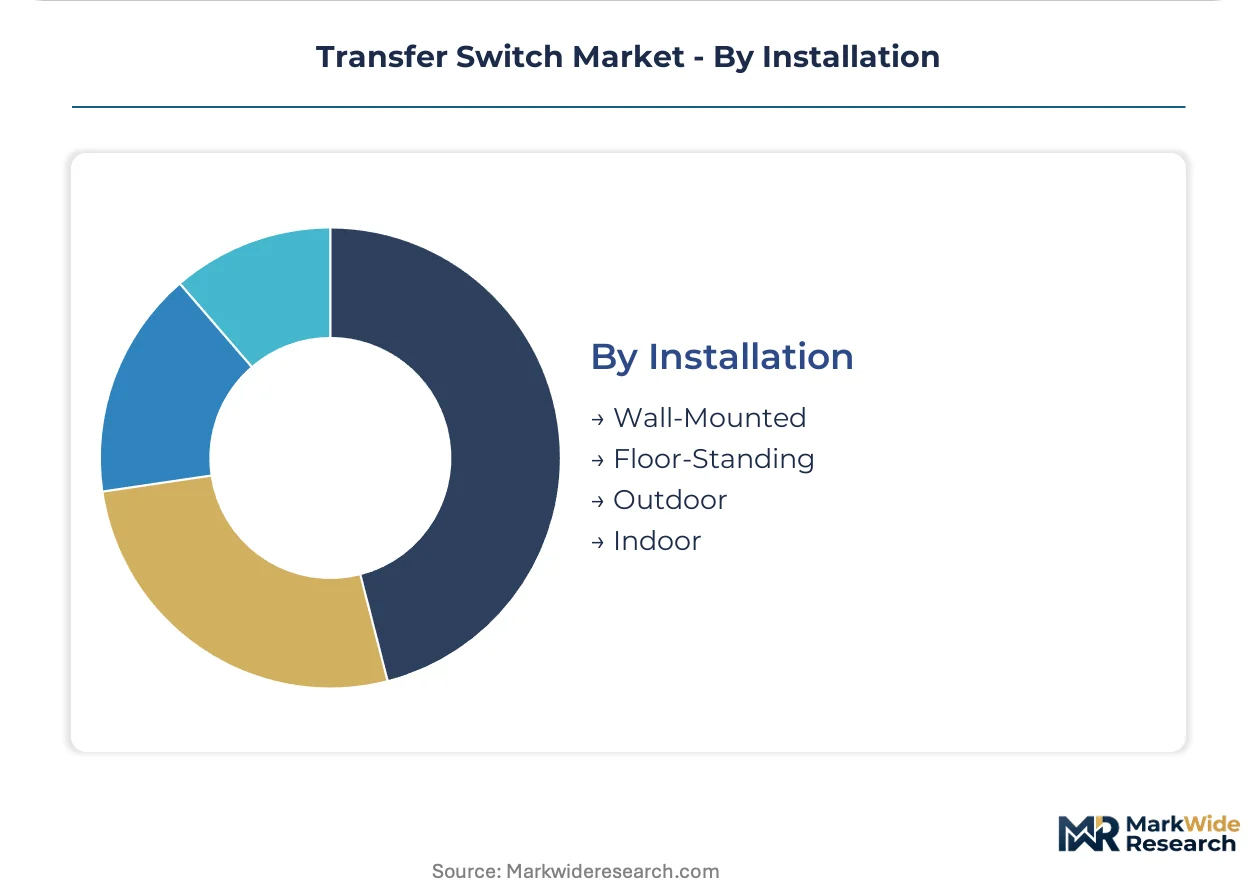
Transfer switch procurement patterns diverge sharply across voltage classes, automation levels, and installation environments. Specification engineers weight interrupting ratings, transfer speed, and remote monitoring capabilities differently depending on facility criticality and electrical infrastructure scale.
Product Type:
Mature electromechanical designs dominate high-current utility applications, while emerging solid-state architectures capture share in sub-cycle transfer environments.
- Automatic Transfer Switch:Electromechanical or solid-state configurations execute source transfers within 100 milliseconds to 4 milliseconds depending on technology grade. Hyperscale data centers in Northern Virginia and Phoenix specify automatic transfer switches for redundant power paths serving server racks and cooling infrastructure.
- Manual Transfer Switch:Operator-actuated designs require physical intervention to transfer load between sources, typically rated below 400A for cost-sensitive installations. Residential and light commercial segments in secondary metros specify manual variants where automation premiums outweigh outage frequency risks.
- Bypass Isolation Switch:Dual-function designs enable maintenance isolation of automatic transfer mechanisms without load interruption. Healthcare facilities and critical manufacturing plants specify bypass isolation configurations to satisfy NFPA 99 emergency system requirements.
- Switchgear:Integrated assemblies combine transfer switching with protection, metering, and distribution functions in unified enclosures. Utility-scale microgrid projects specify switchgear for centralized control of multiple generation sources and energy storage systems.
Automatic Transfer Switch handles the majority of throughput; Bypass Isolation Switch is expanding most quickly on share as maintenance requirements tighten.
End User:
Cost tier stratification separates specification-grade installations from commodity procurement, with data center premiums reaching multiples of residential pricing.
- Commercial Facilities:Office complexes, retail centers, and hospitality properties specify transfer switches rated 200A to 800A for emergency lighting and life safety loads. California commercial buildings facing Title 24 energy code compliance specify integrated transfer switches with demand response capabilities.
- Industrial Plants:Heavy manufacturing and process industries require transfer switches with high interrupting ratings and severe-duty contact assemblies. Petrochemical facilities along the Gulf Coast specify explosion-proof enclosures and marine-grade finishes for corrosive environments.
- Data Centers:Hyperscale and colocation facilities demand sub-cycle transfer speeds, redundant controller architectures, and remote monitoring integration. Northern Virginia data center clusters specify synchronized transfer switch arrays for generator paralleling across multi-hundred-megawatt campuses.
- Residential Buildings:Single-family and multi-family dwellings specify manual or basic automatic transfer switches rated 100A to 200A for standby generator connection. Hurricane-prone coastal markets in Florida and Texas drive residential automatic transfer switch adoption as backup power becomes standard equipment.
Data Centers command the highest specification premiums; Residential Buildings are climbing the fastest as standby generator penetration deepens.
Technology:
Volume concentration favors proven mechanical designs, while margin pools concentrate in digitally enabled segments with recurring software revenue.
- Mechanical:Solenoid or motor-operated contact mechanisms provide proven reliability across temperature extremes and electrical disturbances. Utility substations and industrial facilities specify mechanical transfer switches for their tolerance of harsh electrical environments.
- Electronic:Microprocessor-based controllers enable programmable transfer sequences, load shedding logic, and generator exercise scheduling. Commercial microgrid projects specify electronic controllers for integration with battery management systems and solar inverters.
- Hybrid:Combined mechanical contact assemblies with electronic supervision balance reliability and intelligence for mid-market applications. Regional hospital chains specify hybrid designs to gain monitoring capabilities without solid-state cost premiums.
- Digital:Fully networked architectures with cloud connectivity, predictive analytics, and API integration for building management systems. Edge computing nodes in secondary metros specify digital transfer switches for centralized visibility of distributed power infrastructure.
Mechanical technology handles the majority of unit volume; Digital is gaining share fastest as IoT integration becomes standard specification.
Installation:
Geography within the title scope drives enclosure specifications, with outdoor ratings commanding material cost premiums for corrosion resistance.
- Wall-Mounted:Compact enclosures rated below 400A mount directly to structural surfaces in space-constrained electrical rooms. Urban commercial retrofits in Manhattan and San Francisco specify wall-mounted designs to maximize floor space for revenue-generating equipment.
- Floor-Standing:Freestanding enclosures accommodate higher current ratings and integrated distribution sections for centralized power management. Data center electrical houses specify floor-standing transfer switches for accessibility during maintenance operations.
- Outdoor:NEMA 3R or 4X enclosures withstand precipitation, temperature cycling, and UV exposure for generator pad mounting. Telecommunications shelters and remote pump stations specify outdoor-rated transfer switches to eliminate dedicated building requirements.
- Indoor:Controlled-environment installations in electrical rooms or data center white spaces prioritize compact footprints and front-access serviceability. Hyperscale facilities in Phoenix and Dallas specify indoor configurations with enhanced thermal management for high-density arrangements.
Indoor installation handles the majority of throughput; Outdoor is expanding most quickly as distributed generation and edge infrastructure proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States electrical grid interconnect underpins North American transfer switch demand, with hyperscale data center corridors driving specification-grade procurement cycles.
United States
NERC CIP-014 standards mandate physical security hardening for bulk electric system substations, requiring redundant backup power architectures across transmission facilities. The Investment Tax Credit provisions of the IRA incentivize solar-plus-storage microgrids that demand bidirectional transfer switch capabilities. Northern Virginia's data center cluster consumes synchronized transfer switch arrays for multi-hundred-megawatt generator synchronization projects.
Germany
Industrial automation investments and chemical plant modernization sustain demand for severe-duty transfer switches with high interrupting ratings. The EU Green Deal and national carbon reduction mandates accelerate microgrid deployments requiring seamless source selection between utility, renewable, and battery inputs. The Rhine-Ruhr industrial corridor specifies integrated switchgear for centralized control of distributed generation assets.
China
Dual carbon goals and grid reliability investments drive automatic transfer switch installations across manufacturing hubs and critical infrastructure. National GB standards and MIIT industrial policies shape product certification requirements for domestic and export markets. The Yangtze River Delta data center cluster represents the fastest-growing specification-grade demand concentration in Asia-Pacific.
India
CEA grid reliability mandates and PLI scheme incentives for domestic manufacturing expand local production capacity for electromechanical power components. BIS certification requirements govern product safety standards for transfer switches deployed in commercial and industrial facilities. Maharashtra's Mumbai-Pune industrial corridor concentrates demand from pharmaceutical manufacturing and IT infrastructure projects.
Japan
METI energy security policies and earthquake resilience standards enforce backup power redundancy for critical facilities and semiconductor fabrication plants. JIS standards govern product performance testing for transfer switches integrated with distributed generation systems. The Kanto region's Tokyo metropolitan area sustains premium-tier demand from financial services and telecommunications infrastructure.
Transfer Switch Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The market structure consolidates around electrical infrastructure conglomerates with captive distribution networks and specification engineering relationships. Three archetypes dominate: integrated power system providers bundling generation and switching equipment; pure-play electromechanical component manufacturers with deep contractor channel penetration; and digital control specialists capturing margin pools through IoT-enabled predictive maintenance platforms. Dominant competitive moves include backward integration into contact assembly manufacturing and strategic partnerships with EPC firms for data center master service agreements.
Among diversified electrical infrastructure conglomerates, Schneider Electric, Eaton Corporation, and Siemens AG exemplify platform-scale positioning. Schneider Electric leverages extensive distribution networks across utility-scale installations. Eaton Corporation anchors its market presence through deep integration with North American electrical contractors. Siemens AG represents European engineering heritage with broad industrial automation portfolio adjacencies. These three entities collectively illustrate how specification authority, manufacturing scale, and channel control determine competitive positioning in electromechanical power distribution markets.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton Corporation |
| Generac Holdings |
| Cummins Inc. |
| ABB Ltd. |
| Siemens AG |
| Kohler Co. |
| Caterpillar |
| General Electric Company |
| Others |
Supply Flow & Price Mechanics
Chinese electrical steel and copper contact assembly manufacturing concentrates upstream, anchoring margin capture by integrated power system providers while fragmenting pricing power among pure-play component vendors. Raw material volatility transmits directly to project bids, compressing returns on standard-duty electromechanical transfer switch lines.
Pricing Analysis
UL 1008 dictates the pricing tier structure across certification-grade, commercial-grade, and economy-grade transfer switch portfolios. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade data center installations from commodity residential procurement. Cost compression in standard-duty mechanical transfer switches is intensifying because copper and electrical steel commodity fluctuations squeeze contact assembly margins. Residential standby generator buyers exhibit highest price sensitivity, while hyperscale data center operators prioritize sub-cycle transfer performance over unit economics.
Supply Chain Analysis
Export-control restrictions on silicon carbide power semiconductors limit solid-state transfer switch technology flows from United States and Japanese suppliers to Chinese manufacturers. Electromechanical contact assemblies draw from Chinese copper fabrication, Indian electrical steel processing, and German precision relay manufacturing. Single-source vulnerability concentrates in silicon carbide substrate supply for emerging solid-state architectures. Distribution runs through national electrical contractors with integrated design-build capabilities, displacing traditional distributor-led specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transfer switch market is accelerating through solid-state technology disruption as hyperscale data centers demand sub-four-millisecond transfer speeds that electromechanical designs cannot deliver.
For Market Incumbents: Build captive certification moats by pre-positioning UL 1008 and IEEE 1547-2018 compliant products ahead of NERC reliability mandate enforcement. Backward integration into copper contact assembly manufacturing defends margin position against commodity volatility. Channel control through EPC master service agreements locks out emerging solid-state specialists from data center specification cycles. For New Entrants and Emerging Players: Build out edge computing node infrastructure in secondary metros as the most penetrable white-space target, where compact sub-400A automatic transfer switch demand outstrips utility-scale manufacturer attention. Solar-plus-storage microgrid configurations present second entry vector, leveraging IRA tax credit visibility to specify bidirectional power flow architectures. Go-to-market execution partners with regional electrical engineering firms bypassing contractor channel gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital control specialists possessing IoT-enabled predictive maintenance platforms but lacking electromechanical manufacturing scale. Five-to-ten year viability hinges on solid-state technology migration pace and data center construction cycle durability. The signal to watch is hyperscale operator procurement committee solid-state specification adoption rates as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Assemblies | Captive copper fabrication insulates margin from LME volatility in commodity contact markets. |
| EPC Master Service Agreements | Multi-year pre-qualification with Bechtel, Fluor, and DPR Construction locks specification authority. |
| Solid-State Technology Licensing | Silicon carbide power semiconductor partnerships accelerate sub-cycle transfer capability deployment. |
| Predictive Maintenance Platform Launch | IoT-enabled contact wear sensors create recurring SaaS revenue from installed base retrofit. |
| IEEE 1547-2018 Certification Investment | Ride-through and anti-islanding compliance opens California microgrid procurement to qualified vendors. |
Methodological Framework
A standing panel of specification engineers at EPC firms, data center facility directors, electrical contractor procurement leads, and utility substation planners provided ongoing calibration across the study period. Primary interview intelligence combined with secondary validation from UL certification databases, NERC compliance filings, FERC interconnection queues, and EIA backup power installation records. Bottom-up project pipeline aggregation triangulated against top-down electromechanical component production estimates.
Scenario-bracketing around commodity price bands, data center construction cycle timing, and solid-state technology adoption curves bounded projection uncertainty across the analysis window. Segmentation modeling incorporated voltage class, automation level, technology grade, and installation environment dimensions. CAGRs derived from unit shipment trajectories weighted by average selling price evolution within each specification tier. Forecast inputs included hyperscale operator capex disclosure patterns and state-level carbon mandate enforcement timelines.
Stress conditions across copper price spikes, UL certification backlog extensions, and silicon carbide supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NERC mandate enforcement consistency and IRA tax credit continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
China Switchgear Market
Switches
Surface Mount Switch Market
Switches
Electromechanical Microwave Switch Market
Switches
UAE Switchgear Market
Switches
Paralleling Switchgear Market
Switches
Matrix Switches Market
Switches
APAC Push Buttons and Signaling Devices Market
Switches
Level Switches Market
Switches
Antenna Switch Module Market
Switches
Panel Mounted Disconnect Switch Market
Switches
Reed Switch Market
Switches
Smart Circuit Breaker Market
Switches
India Switchgear Market
Switches
Ethernet Switch Market
Switches
Fusible Switches Market
Switches
Middle-East and Africa Low Voltage Switchgear Market