
 Multivariate Testing Software Market | 2026-2036
Multivariate Testing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Multivariate Testing Software Market Insights
Cloud infrastructure is rebalancing traditional software economics as subscription models displace perpetual licensing. Optimizely leverages its experimentation platform to anchor enterprise accounts across retail and media verticals. VWO competes aggressively on price-performance for mid-market e-commerce operators. Adobe Target extends its dominance through Creative Cloud integration that locks in creative-to-analytics workflows.
Multivariate testing software executes simultaneous controlled experiments across multiple webpage or application variables to isolate statistically significant performance drivers. The technology employs fractional factorial designs and Bayesian inference engines to reduce required traffic volumes by up to 80% compared with full-factorial methods. Cloud-Based deployment leads absolute revenue contribution as hyperscaler partnerships lower infrastructure barriers for mid-size enterprises. SaaS delivery captures the fastest expansion trajectory among deployment modes due to automatic feature updates and elastic scaling. The E-Commerce end-user segment concentrates margin pools because transaction velocity generates abundant experimental data and measurable ROI.
ISO 27001 certification shapes vendor selection criteria for financial services procurement teams evaluating experimentation platforms. The EU AI Act imposes transparency obligations on automated decision systems that include algorithmic content optimization, forcing European deployments toward explainable testing methodologies. GDPR's consent requirements constrain cookie-based visitor segmentation, pushing vendors toward server-side testing architectures. Stakeholders must monitor regulatory divergence between privacy-first European frameworks and performance-oriented US enforcement postures when architecting cross-border experimentation programs.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for multivariate testing platforms as SaaS delivery models displace perpetual licensing structures across enterprise procurement cycles.
Growth Catalysts
- EU AI Act transparency mandates:Automated decision systems now require explainable optimization methodologies, accelerating adoption of Bayesian inference engines that document statistical reasoning for regulatory auditors.
- E-commerce transaction velocity:Retail platforms generate experimental data at scale, enabling fractional factorial designs that reduce traffic requirements and unlock ROI visibility for mid-market operators.
- Server-side testing architectures:Privacy frameworks in Germany and France constrain cookie-based segmentation, pushing infrastructure investment toward first-party data pipelines that bypass browser restrictions.
Market Restraints
- GDPR consent complexity:Visitor segmentation requires granular opt-in mechanisms that increase implementation overhead and reduce addressable sample pools for European deployments.
- Hyperscaler concentration:Cloud infrastructure dependencies on AWS, Azure, and Google Cloud create single-point-of-failure exposure for mid-size vendors without multi-cloud failover capabilities.
- Statistical expertise scarcity:Fractional factorial design implementation demands specialized data science talent that commands premium compensation in tight labor markets.
Strategic Opportunities
- ISO 27001 certification arbitrage:Financial services procurement teams in Switzerland and Singapore prioritize security-certified vendors, creating margin expansion for compliant platforms.
- Creative-to-analytics workflow convergence:Adobe Creative Cloud integration patterns reveal demand for experimentation tools that embed directly within design production environments.
- India PLI scheme digital incentives:Government subsidies for enterprise software adoption lower customer acquisition costs for cloud-native testing platforms targeting domestic e-commerce operators.
Industry Challenges
- Legacy on-premises migration friction:Enterprises with sunk infrastructure investments face integration complexity when bridging mainframe analytics systems to modern API-first experimentation stacks.
- Cross-border data residency alignment:Divergent enforcement postures between European privacy-first frameworks and US performance-oriented standards force redundant architecture investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multivariate Testing Software Market |
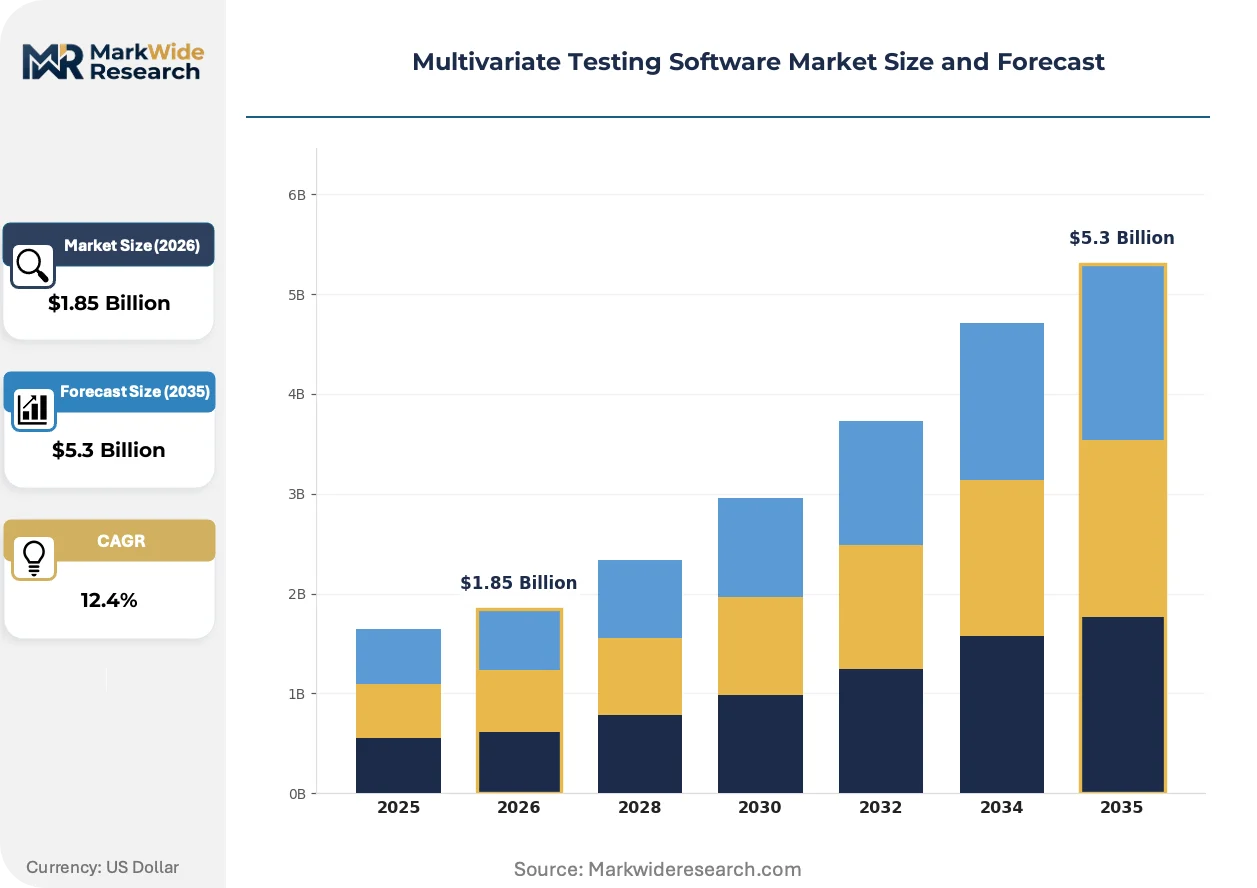
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: BFSI, E-Commerce, Healthcare, Education Solution: Analytics, Optimization, Reporting, Integration Industry Vertical: Retail, Travel, Telecommunications, Automotive |
| Companies Covered | Optimizely, Adobe Target, AB Tasty, Kameleoon, VWO, Convert, Statsig, Conductrics, Evolv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multivariate Testing Software Market Trends and Innovations
Experimentation platforms are embedding machine learning inference engines that compress hypothesis-to-insight cycles, fundamentally altering how optimization teams allocate engineering resources and measure statistical significance.
Bayesian bandit algorithms are unifying exploration and exploitation phases within single continuous experiments, eliminating traditional fixed-horizon test structures. Retail and media verticals in the United States are adopting these methods fastest, drawn by elastic scaling that matches traffic allocation to real-time performance signals. This convergence is unifying previously separate A/B testing and personalization workflows into single platform investments.
GDPR's consent requirements are reshaping visitor identification architectures across European deployments, forcing migration from client-side to server-side testing implementations. The regulation's territorial scope captures any platform processing EU resident data, extending compliance burdens to US and Asian vendors serving multinational accounts. Financial services and healthcare segments in Germany and France are responding fastest, procuring only architectures that eliminate third-party cookie dependencies entirely.
Subscription pricing models are displacing perpetual licenses as the dominant procurement structure for mid-market e-commerce operators. Annual recurring revenue arrangements with automatic feature updates are replacing multi-year capital expenditure commitments. This shift is most visible among digitally native retailers in the United Kingdom and Netherlands, where finance teams prioritize operational expenditure flexibility over depreciation schedules.
Multivariate Testing Software Market Segmentation
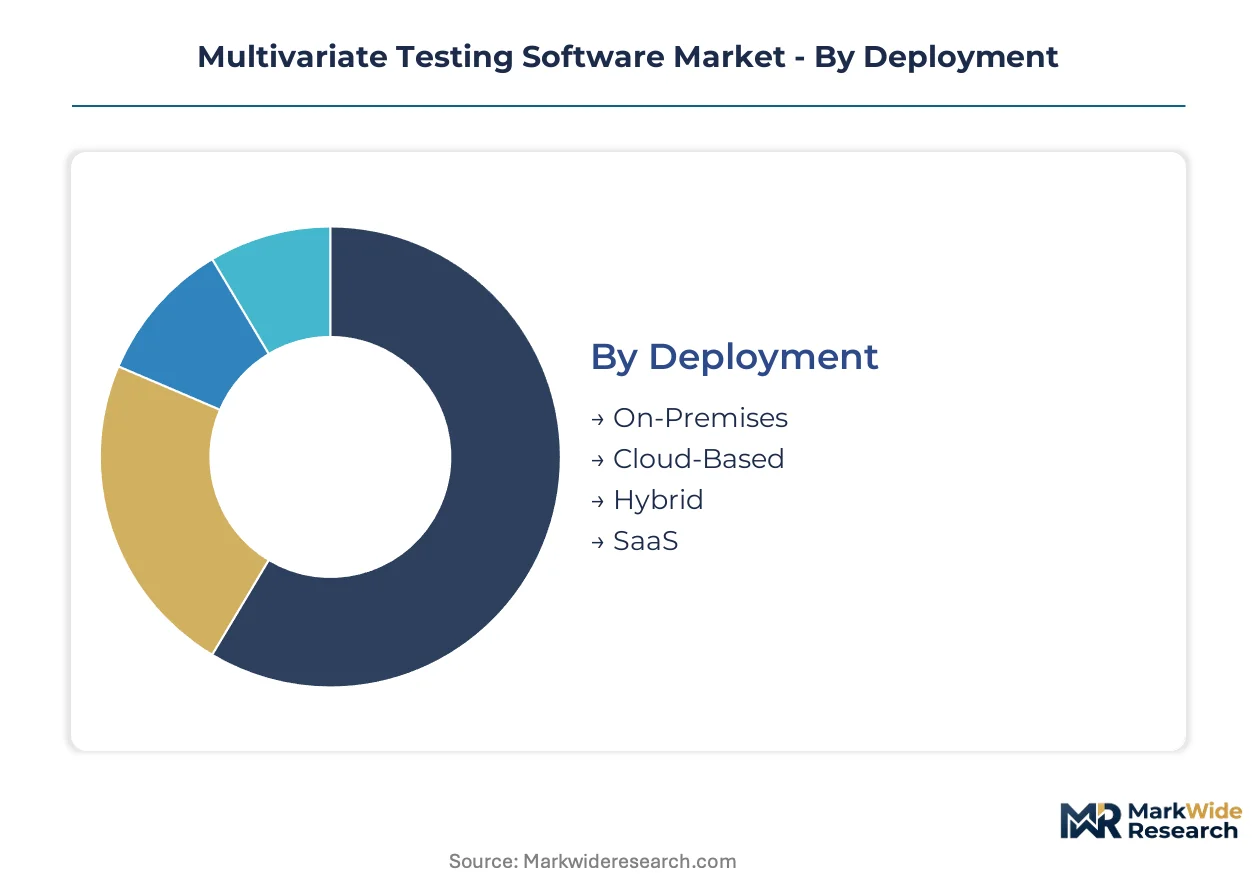
Multivariate testing software segments reflect divergent infrastructure maturity and data sovereignty requirements across enterprise buyers. Deployment mode determines architectural complexity, while end-user concentration shapes feature prioritization and pricing elasticity.
Deployment:
Standardized SaaS delivery contrasts with highly customized on-premises configurations across this spectrum of infrastructure control.
- Cloud-Based:Hyperscaler-hosted environments provision elastic compute for fractional factorial experiments without capital expenditure. Financial services operators in Singapore and Switzerland prioritize ISO 27001-certified cloud deployments to satisfy procurement security mandates.
- SaaS:Automatic feature updates and usage-based metering reduce total cost of ownership for mid-market e-commerce retailers. Subscription contracts with monthly billing cycles dominate procurement in the United Kingdom and Netherlands where finance teams favor operational expenditure classification.
- On-Premises:Air-gapped installations serve defense contractors and classified government facilities with data residency requirements.
- Hybrid:Split architectures route sensitive visitor data through on-premises pipelines while leveraging cloud analytics for non-PII processing.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in SaaS as digitally native retailers abandon perpetual licensing.
End User:
Application intensity varies from transaction-heavy retail platforms to compliance-constrained healthcare systems.
- E-Commerce:High-velocity transaction streams generate abundant experimental data for Bayesian inference engines. Retailers in the United States deploy server-side architectures to bypass browser cookie restrictions while maintaining visitor segmentation fidelity.
- BFSI:Banking and insurance operators demand audit trails for every optimization decision to satisfy regulatory examination. GDPR's consent complexity constrains European deployments, pushing German and French institutions toward first-party data collection methodologies.
- Healthcare:HIPAA-covered entities require business associate agreements with testing vendors processing protected health information.
- Education:University procurement cycles favor annual subscription terms aligned with fiscal year budgeting.
Transaction density concentrates in E-Commerce. Regulatory scrutiny is most intense in BFSI.
Solution:
Functional modularity ranges from standalone analytics engines to fully integrated optimization stacks.
- Optimization:Bayesian bandit algorithms unify exploration and exploitation within continuous experiments. Media companies in the United States adopt these methods to match traffic allocation against real-time performance signals.
- Analytics:Statistical significance engines process fractional factorial designs to isolate performance drivers across multiple variables simultaneously.
- Reporting:Automated dashboard generation translates experiment outputs into executive-ready visualizations for non-technical stakeholders.
- Integration:API-first architectures connect testing platforms to customer data platforms and content management systems.
Platform stickiness originates in Optimization modules. Integration capabilities determine competitive win rates in enterprise RFPs.
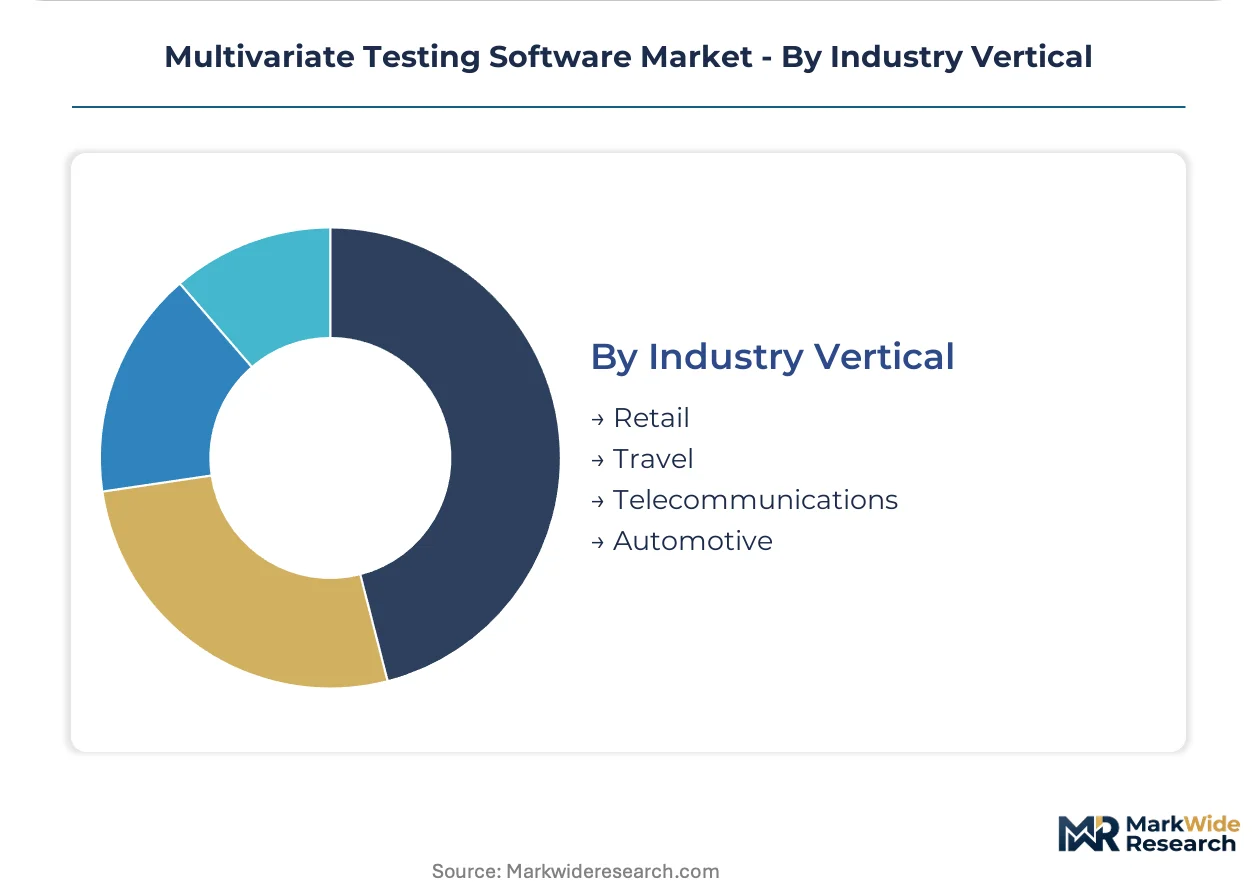
Industry Vertical:
Vertical specialization demands segment-specific compliance templates and use-case libraries.
- Retail:Product recommendation engines and checkout funnel optimization dominate implementation roadmaps. Omnichannel operators require unified experimentation across web, mobile, and in-store touchpoints.
- Travel:Dynamic pricing integration with revenue management systems creates complex multi-variate scenarios for airfare and hospitality bundles.
- Telecommunications:Subscription lifecycle management drives testing priorities around plan selection flows and upgrade prompts.
- Automotive:Configurator tools for vehicle customization require high-fidelity testing of option presentation sequences.
Experimentation maturity is highest in Retail. Automotive represents the most complex integration challenge due to legacy dealer network systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's experimentation technology cluster anchors worldwide multivariate testing software deployment, with enterprise digital transformation budgets in the United States commanding the largest absolute spend. Cloud-native architectures are compressing deployment timelines across North American and Western European procurement cycles. Privacy-first regulatory frameworks in Germany and France are accelerating server-side testing migrations.
United States
Retail media networks and streaming platforms drive experimentation platform procurement, with transaction velocity generating abundant Bayesian inference data. The FTC's evolving stance on algorithmic transparency creates compliance planning uncertainty for automated optimization systems. Seattle's cloud infrastructure corridor hosts hyperscaler partnerships that lower infrastructure barriers for mid-size SaaS vendors.
Germany
Automotive configurators and industrial B2B marketplaces require high-fidelity multivariate testing of complex option presentation sequences. GDPR's consent complexity and the KBA's data governance expectations push financial services toward first-party data pipelines. Munich's enterprise software cluster concentrates vendor development centers serving DAX-listed industrial clients.
United Kingdom
Digitally native retailers prioritize operational expenditure flexibility through monthly-billed SaaS subscriptions over perpetual licensing. The Information Commissioner's Office enforces granular opt-in mechanisms that reduce addressable sample pools for cookie-dependent platforms. London's fintech corridor demands ISO 27001-certified cloud deployments for experimentation infrastructure.
India
Domestic e-commerce operators leverage government digital incentives to lower customer acquisition costs for cloud-native testing platforms. The PLI scheme's enterprise software provisions accelerate procurement cycles for mid-market retailers. Bangalore's SaaS development ecosystem hosts engineering centers optimizing fractional factorial designs for emerging market traffic constraints.
Singapore
Wealth management and private banking operators require audit-trail documentation for every optimization decision to satisfy regulatory examination. The Monetary Authority of Singapore's technology risk management guidelines shape vendor security certification requirements. The city-state's regional headquarters concentration hosts procurement teams evaluating cross-border experimentation programs for Southeast Asian markets.
Multivariate Testing Software Market Competitive Landscape
Global majors compete with regional champions across deployment architecture and vertical specialization, creating a tiered competitive structure where scale advantages in cloud infrastructure coexist with niche expertise in compliance-constrained segments. The vendor base organizes around three strategic archetypes: hyperscaler-anchored platforms leveraging elastic compute, privacy-specialized providers serving European financial services, and mid-market SaaS operators competing on price-performance. Consolidation pressure manifests through strategic partnerships with customer data platforms and vertical integration into adjacent analytics stacks.
Within the experimentation platform tier, Optimizely and Adobe Target exemplify scale-driven architectures that anchor enterprise accounts through creative-to-analytics workflow convergence. VWO occupies a position among mid-market specialists competing aggressively on implementation velocity for e-commerce operators. These three vendors represent distinct competitive vectors: enterprise workflow integration, mid-market accessibility, and vertical-specific compliance adaptation.
| Leading Market Players |
|---|
| Optimizely |
| Adobe Target |
| AB Tasty |
| Kameleoon |
| VWO |
| Convert |
| Statsig |
| Conductrics |
| Evolv |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler compute costs cascade through SaaS subscription tiers as AWS, Azure, and Google Cloud infrastructure fees compress margins for mid-market multivariate testing vendors serving price-sensitive e-commerce operators in the United Kingdom and Netherlands.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers shapes three-tier pricing stratification across premium enterprise, standard mid-market, and economy self-serve levels. Price differentiation hinges on ISO 27001 certification status and integration depth with customer data platforms. Pricing pressure intensifies as VWO and Convert compete aggressively on implementation velocity for digitally native retailers. Mid-market e-commerce operators exhibit highest price sensitivity, while financial services procurement teams in Singapore and Switzerland prioritize security-certified premium tiers regardless of cost.
Supply Chain Analysis
Logistics and freight costs are negligible in software delivery, yet data residency requirements create geographic supply concentration in Ireland, Frankfurt, and Singapore where hyperscaler regions host compliant experimentation infrastructure. The supply chain draws from cloud compute, open-source statistical libraries, and specialized Bayesian inference engine components. Single-source vulnerability concentrates around AWS dominance in North American enterprise accounts. Distribution runs through direct sales teams for enterprise deployments and self-serve digital channels for mid-market SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as GDPR consent complexity and EU AI Act transparency mandates shift procurement toward premium server-side architectures with audit-trail documentation.
For Market Incumbents: Deepen vertical integration into first-party data pipeline technologies to defend against privacy-specialized entrants exploiting server-side testing demand. Anchor enterprise accounts through creative-to-analytics workflow convergence that locks in Adobe Creative Cloud-dependent media operators. Expand ISO 27001-certified cloud regions in Switzerland and Singapore where financial services procurement teams concentrate margin pools.
For New Entrants and Emerging Players: EU AI Act transparency mandates in Germany and France open a window for explainable Bayesian inference engines that document statistical reasoning for regulatory auditors. Target mid-market BFSI operators in India leveraging PLI scheme digital incentives to lower customer acquisition costs. Pursue API-first integration partnerships with customer data platforms as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where hyperscaler-anchored platforms lack vertical-specific compliance adaptation for European financial services. Five-to-ten year viability favors privacy-specialized providers with server-side architectures and first-party data capabilities. Target acquisition archetypes include mid-market SaaS operators with strong price-performance positioning in e-commerce. Watch regulatory divergence between European privacy-first frameworks and US performance-oriented enforcement postures as the key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Server-Side Architecture Migration | GDPR consent requirements in Germany and France force elimination of third-party cookie dependencies. |
| ISO 27001 Certification Investment | Swiss and Singaporean financial services procurement teams prioritize security-certified cloud deployments exclusively. |
| Bayesian Bandit Algorithm Integration | US retail media networks adopt continuous experimentation unifying exploration and exploitation phases. |
| Hyperscaler Partnership Expansion | AWS, Azure, and Google Cloud alliances lower infrastructure barriers for mid-size SaaS vendors. |
| Creative Cloud Workflow Embedding | Adobe Target locks in media verticals through design-to-analytics integration that competitors cannot replicate. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners alongside secondary validation. Primary research draws from hyperscaler capex disclosures, SEC filings, and EU regulatory filings. Secondary sources include experimentation platform documentation, GDPR enforcement actions, and ISO certification databases. Bottom-up deployment mode sizing triangulates against top-down vertical spend analysis.
Rate-of-change decomposition separates cloud-native adoption velocity from legacy migration friction across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs derive from Bayesian inference engine adoption curves and e-commerce transaction velocity expansion. Industry-specific forecast inputs encompass server-side testing migration timelines and EU AI Act implementation schedules.
Revisions become necessary when regulatory enforcement postures diverge sharply or hyperscaler pricing structures shift materially. Forecasts reflect assumptions about privacy framework stability and cloud infrastructure cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global HMI Software Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
Global Cloud Accounting Technology Market
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Global Managed File Transfer Software Market
Software & Services
Online Donation Software Market
Software & Services
Global Server Management Software Market
Software & Services
Custom Software Development Market
Software & Services
Global Nosql Software Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Special Effects (SFX) Software Market
Software & Services
Asia-Pacific Text to Speech (TTS) Software Market
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Global Client Portal Software Market
Software & Services
Payroll - HR Solutions and Services Market
Software & Services
Public Financial Management Software Market