
 Global Lead Capture Software Market | 2026-2036
Global Lead Capture Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lead Capture Software Market Foresight
BFSI is rebalancing toward cloud-based lead capture platforms as compliance costs reshape procurement priorities. HubSpot leverages integrated marketing automation to anchor mid-market share across North America. Apollo.io sustains R&D intensity in data enrichment algorithms that differentiate its platform from point solutions. Cognism competes through specialized intent-data layering for enterprise account-based sales teams.
Lead capture software encompasses digital tools that collect, validate, and route prospect information through automated workflows using API integrations, form builders, and real-time scoring algorithms. These systems serve commercial teams by converting anonymous traffic into qualified sales opportunities through behavioral tracking and progressive profiling. Cloud-based deployment leads solution architecture due to faster implementation cycles and lower total cost of ownership for distributed sales organizations. Data enrichment represents the fastest-expanding solution segment as buyers prioritize accuracy over volume in prospect databases. Marketing automation functionality commands premium pricing where it connects lead capture to nurture sequences and revenue attribution.
The EU AI Act and GDPR constrain automated lead scoring transparency requirements across European deployments, while the US FTC monitors consent mechanisms under Section 5 unfair practice standards. India's Digital Personal Data Protection Act introduces fresh compliance layers for SaaS vendors serving its domestic market. Stakeholders must monitor how fragmented privacy enforcement across the United States, Germany, and India reshapes product roadmaps and go-to-market sequencing.
Market Dynamics
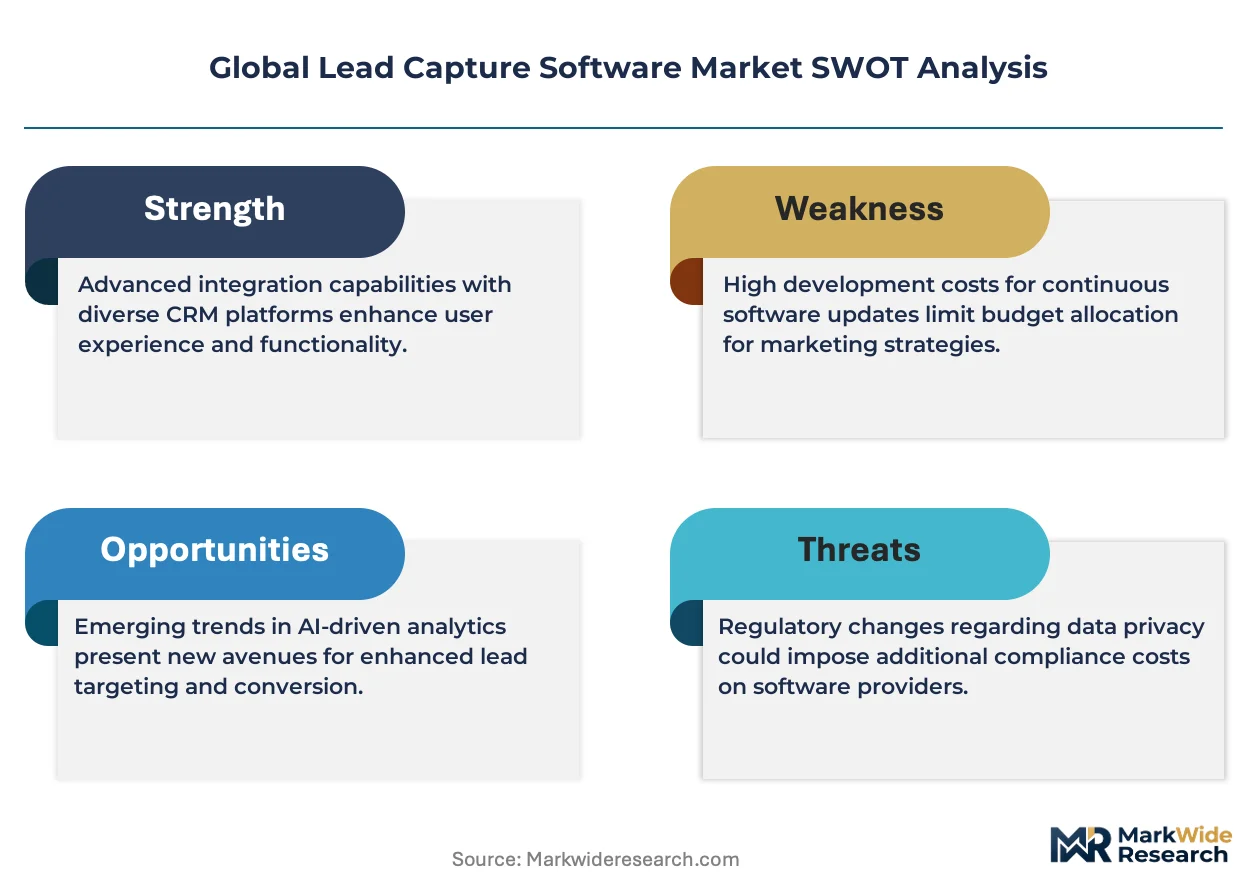
Data privacy enforcement fragmentation across the United States, Germany, and India is compressing vendor margins while forcing architectural redesign of consent management workflows.
Growth Catalysts
- GDPR consent-layer mandates:European enterprises must deploy auditable first-party data collection infrastructure, expanding subscription demand for compliant SaaS platforms.
- API-first architecture:Real-time CRM synchronization through native connectors eliminates manual lead handoff delays for distributed sales teams.
- India:Digital Personal Data Protection Act implementation accelerates domestic vendor procurement for consent-automation tooling.
Market Restraints
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud dominance in data residency regions creates vendor lock-in risk for multi-tenant deployments.
- EU AI Act transparency requirements:Automated lead scoring algorithms require explainability documentation, extending implementation timelines.
- First-party data substitutes:Cookie deprecation pushes brands toward walled-garden advertising platforms, reducing independent lead capture tool budgets.
Strategic Opportunities
- Brazil:LGPD enforcement maturity lags Europe by four years, creating first-mover advantage for localized compliance-first vendors.
- Progressive profiling + intent data fusion:Behavioral enrichment layers transform anonymous visitor identification into qualified pipeline without form abandonment.
- Partner marketplaces:Salesforce AppExchange and HubSpot ecosystem distribution reduces customer acquisition costs for specialized enrichment providers.
Industry Challenges
- Data engineering talent scarcity:Pipeline architecture roles requiring both MarTech stack expertise and privacy law fluency command premium compensation.
- Legacy CRM migration complexity:On-premise Siebel and SAP installations resist API-based integration without middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lead Capture Software Market |
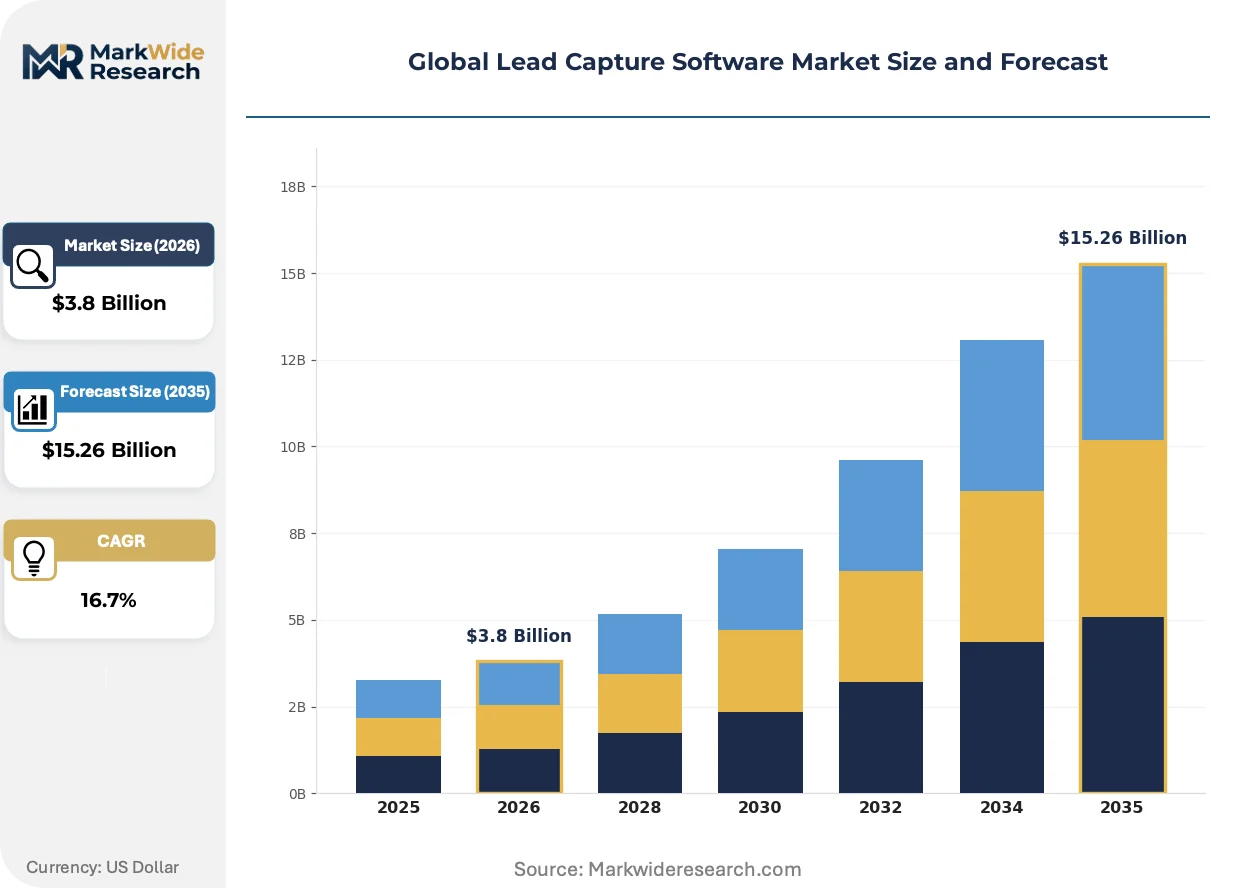
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Solution: Data Enrichment, Lead Management, Customer Relationship Management, Marketing Automation, Analytics Use Case: Event Management, Direct Sales, Telemarketing, Digital Campaigns, Channel Partner Management End User: BFSI, Manufacturing, Technology Providers, Education, Hospitality |
| Companies Covered | HubSpot, ZoomInfo Sales, Apollo.io, Agile CRM, Leadfeeder, Cognism, Lusha, Drift, Typeform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lead Capture Software Market Shifts & Advancements
Artificial intelligence is compressing the gap between anonymous website traffic and sales-ready opportunities through predictive intent modeling and automated enrichment pipelines.
Real-time data enrichment is consolidating vendor positioning by embedding third-party firmographic and technographic feeds directly into form submission workflows. Mid-market SaaS buyers now expect instant lead qualification without manual research overhead. This capability is consolidating competitive differentiation around data network effects rather than UI design.
The EU AI Act's risk-classification framework for automated decision-making imposes documentation burdens on lead scoring deployments across France, Germany, and the Netherlands. Vendors must maintain technical files proving algorithmic transparency for high-volume B2B use cases. Enterprise procurement teams in these markets now require compliance attestations before contract execution.
Subscription fatigue among revenue operations teams is compressing tool consolidation timelines, with buyers preferring unified capture-to-close platforms over point solutions. Marketing automation suites with native enrichment modules displace standalone form builders in mid-market evaluations. This preference shift is most pronounced in United States technology and financial services verticals where stack simplification reduces integration overhead.
Global Lead Capture Software Market Segmentation
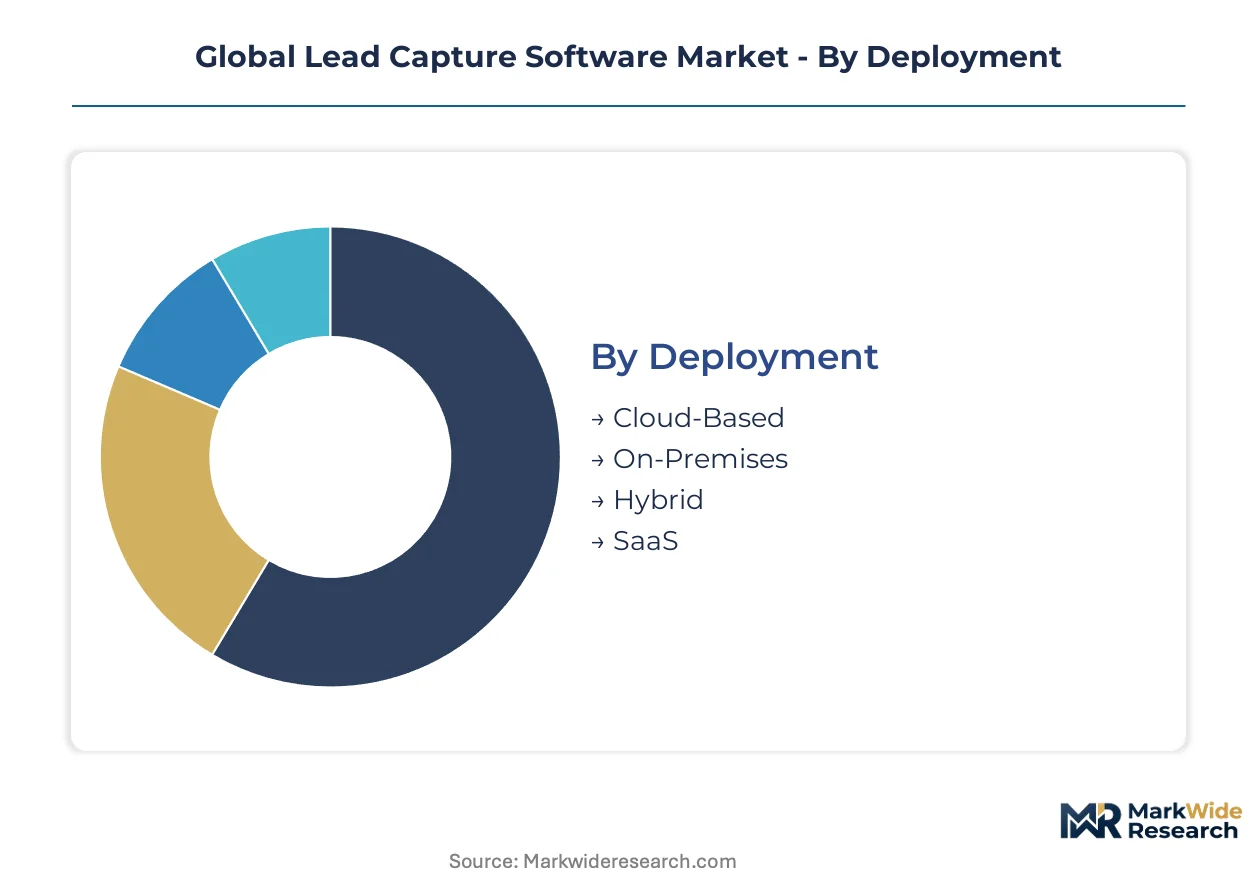
Lead capture software segmentation reveals how deployment architectures, solution bundles, and use-case specificity reshape vendor competitive positioning. Procurement patterns diverge sharply between enterprises replacing legacy CRM infrastructure and mid-market buyers consolidating point solutions into unified platforms.
Deployment:
Replacement cycles accelerate as organizations migrate from rigid on-premise installations toward API-native architectures that reduce IT maintenance overhead.
- Cloud-Based:Multi-tenant architectures with auto-scaling compute resources eliminate capital expenditure for hardware procurement. Demand concentrates among United States financial services firms modernizing branch-level lead routing to comply with SEC record-keeping mandates.
- On-Premises:Single-tenant deployments hosted within client data centers retain preference where data residency requirements block external hosting. German automotive manufacturers sustain this segment through KBA-aligned data sovereignty protocols for supplier prospecting databases.
- Hybrid:Split architectures process sensitive PII on-premise while pushing anonymized analytics to cloud tiers. Indian pharmaceutical distributors adopt this model to satisfy CDSCO audit trails without sacrificing real-time dashboard access.
- SaaS:Fully managed subscription platforms with zero infrastructure footprint dominate mid-market evaluations. Technology providers in Bangalore and Hyderabad drive procurement volume through rapid deployment timelines.
Cloud-Based sits at the top of the volume ranking, with SaaS climbing the fastest.
Solution:
Cost tier differentiation separates premium integrated suites from modular point solutions competing on specific functional depth.
- Data Enrichment:Real-time augmentation of form submissions with firmographic and technographic attributes from third-party data networks. United States B2B SaaS vendors prioritize this capability to reduce manual research overhead in enterprise account-based marketing programs.
- Lead Management:Pipeline staging, scoring algorithms, and routing rules that convert raw inquiries into sales-qualified opportunities. Manufacturing distributors in Germany deploy these tools to coordinate multi-channel distributor lead allocation across KBA-regulated territories.
- Customer Relationship Management:Core database functionality for contact storage, interaction history, and opportunity tracking. Education institutions in India leverage lightweight CRM modules to manage alumni and corporate partnership pipelines under UGC compliance frameworks.
- Marketing Automation:Nurture sequence orchestration, behavioral triggers, and revenue attribution connecting capture to conversion. Hospitality chains in the United States integrate these modules with property management systems for guest acquisition lifecycle management.
- Analytics:Dashboard visualization, cohort analysis, and predictive forecasting on lead quality and channel performance. Technology providers demand embedded analytics to justify marketing spend allocation across fragmented digital touchpoints.
Lead Management commands the largest installed base, with Data Enrichment gaining share fastest.
Use Case:
Application-specific configurations determine whether buyers prioritize mobile offline functionality, real-time API throughput, or batch processing scale.
- Event Management:Badge scanning, session tracking, and on-site lead qualification workflows for trade shows and conferences. German industrial equipment exhibitors deploy these tools to synchronize prospect data with SAP CRM before booth teardown.
- Direct Sales:Field rep mobile applications with offline synchronization and territory-based lead distribution. United States medical device manufacturers rely on this segment to maintain FDA-compliant interaction logs during hospital sales calls.
- Telemarketing:Predictive dialer integration, call scripting, and real-time disposition coding for outbound contact centers. Indian BFSI outbound operations use these platforms under TRAI DND registry compliance protocols.
- Digital Campaigns:Landing page builders, form embedding, and UTM parameter tracking for paid and organic web traffic. Technology providers dominate procurement as they A/B test conversion paths across Google Ads and LinkedIn sponsored content.
- Channel Partner Management:Co-branded lead registration, deal protection workflows, and MDF-aligned campaign execution. Manufacturing OEMs in the United States deploy these systems to prevent partner conflict over enterprise account pursuit.
Digital Campaigns leads current deployment volume, with Event Management rebounding fastest as in-person trade show attendance normalizes.
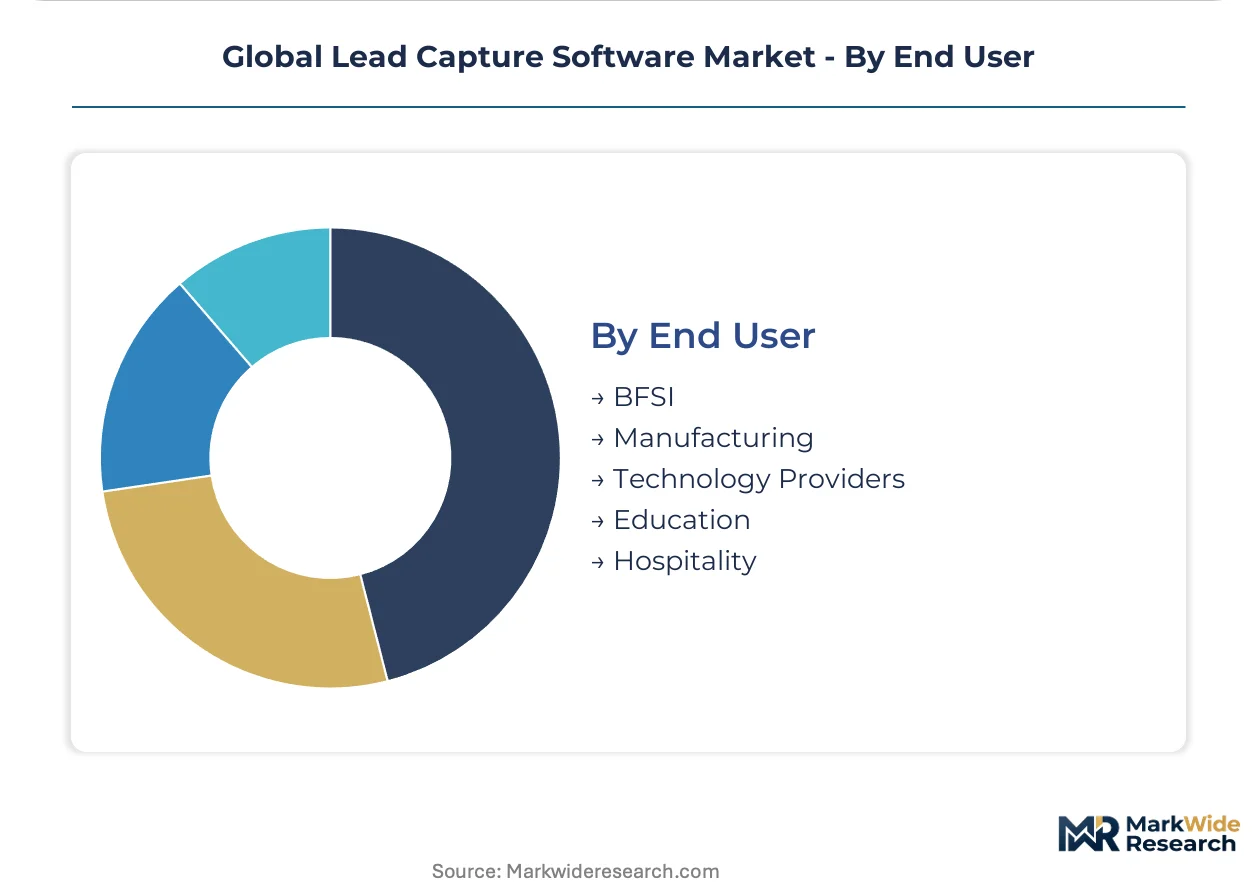
End User:
Customer type dictates security certification requirements, integration complexity, and pricing tolerance across vertical-specific procurement committees.
- BFSI:Regulated institutions requiring SOC 2 Type II, PCI-DSS, and jurisdictional data residency attestations. United States regional banks prioritize this segment to satisfy FFIEC examination criteria for third-party vendor risk management.
- Manufacturing:Industrial firms with complex distributor networks and long-cycle capital equipment sales processes. German automotive suppliers integrate capture platforms with existing KBA quality management databases for supplier onboarding workflows.
- Technology Providers:SaaS and software vendors with product-led growth models and developer-centric buyer journeys. Bangalore-based startups drive demand for API-first enrichment tools that embed directly into application signup flows.
- Education:Universities and professional training institutes managing student recruitment, alumni relations, and corporate partnership development. Indian institutions adopt these platforms to centralize inquiry handling across UGC-affiliated campuses.
- Hospitality:Hotel chains, resorts, and event venues capturing group sales leads and guest preference data. United States boutique hotel groups deploy specialized modules for wedding and corporate event pipeline management.
BFSI maintains the deepest penetration, with Technology Providers expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor deployment strategies as compliance-cost differentials between jurisdictions drive platform architecture decisions. Vendors now engineer consent-layer modularity to serve markets with divergent privacy enforcement maturity without duplicating core infrastructure.
United States
Financial services modernization and SEC record-keeping mandates propel cloud-based lead capture procurement among regional banks. The FTC monitors consent mechanisms under Section 5 unfair practice standards, tightening vendor accountability for data collection disclosures. Silicon Valley technology providers anchor demand for API-first enrichment tools that embed directly into product-led growth funnels.
Germany
Automotive supplier networks and KBA-aligned data sovereignty protocols sustain hybrid deployment preferences for prospect databases. GDPR consent-layer mandates require auditable first-party data collection infrastructure, extending implementation timelines for automated scoring algorithms. Industrial equipment exhibitors in Munich and Frankfurt drive event management solution adoption for trade show lead synchronization.
India
Digital Personal Data Protection Act implementation accelerates domestic procurement for consent-automation tooling among BFSI outbound operations. TRAI DND registry compliance protocols constrain telemarketing deployment architectures, favoring vendors with native regulatory modules. Bangalore and Hyderabad technology startups dominate demand for rapid-deployment SaaS platforms with zero infrastructure footprint.
United Kingdom
Post-Brexit regulatory divergence creates procurement complexity as enterprises navigate overlapping GDPR remnants and UK-specific data protection frameworks. Financial services firms in the City of London prioritize SOC 2 Type II attestation for vendor risk management. Marketing automation consolidation trends concentrate among mid-market SaaS buyers seeking unified capture-to-close platforms.
Brazil
LGPD enforcement maturity lags Europe by approximately four years, creating first-mover advantage windows for localized compliance-first vendors. Manufacturing OEMs in São Paulo deploy channel partner management systems to prevent distributor conflict over enterprise account pursuit. Domestic SaaS procurement accelerates as enterprises modernize from spreadsheet-based lead tracking.
Global Lead Capture Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated marketing automation suites commanding premium positioning against modular point solutions. The vendor landscape organizes around three tiers: enterprise platforms with native enrichment networks, mid-market consolidators bundling capture-to-close functionality, and specialized intent-data layerers serving account-based sales teams. Consolidation pressure intensifies as subscription fatigue compresses evaluation timelines toward unified platforms. Dominant competitive moves include ecosystem marketplace distribution to reduce customer acquisition costs and progressive profiling technology licensing to differentiate anonymous visitor identification capabilities.
Within the integrated-suite tier, HubSpot anchors mid-market positioning across North American evaluations through bundled marketing automation modules. Apollo.io and Cognism occupy specialized archetypes, with the former exemplifying data enrichment algorithm intensity and the latter representing intent-data layering for enterprise account-based sales workflows. These three vendors illustrate how competitive differentiation increasingly concentrates around data network effects rather than interface design or standalone form builder functionality.
| Leading Market Players |
|---|
| HubSpot |
| ZoomInfo Sales |
| Apollo.io |
| Agile CRM |
| Leadfeeder |
| Cognism |
| Lusha |
| Drift |
| Typeform |
| Others |
Supply & Pricing Matrix
Enterprise-midmarket functionality bifurcation in lead capture software manifests through divergent margin structures and sourcing strategies across deployment tiers. Premium suites command annual recurring revenue multiples through native data network effects, while modular point solutions compete on implementation velocity and API connectivity costs.
Pricing Analysis
Distributor margin layers in the lead capture software channel compress toward single-digit percentages as direct-to-enterprise sales cycles dominate procurement. Three-tier pricing structure across premium, standard, and economy levels aligns with enrichment depth, CRM integration complexity, and compliance certification grade. Pricing pressure stems from subscription fatigue among revenue operations teams consolidating point solutions into unified platforms. Mid-market SaaS buyers exhibit highest price sensitivity, while regulated BFSI procurement committees prioritize SOC 2 Type II attestation over per-seat cost.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure mandate multi-tenant qualification across AWS, Azure, and Google Cloud regions to satisfy data residency mandates. Software development concentrates in the United States, India, and Germany, with third-party data feeds anchored in proprietary firmographic networks. Supply chain risk centers on single-source vulnerability for real-time enrichment APIs and regulatory restriction exposure under divergent privacy frameworks. Distribution runs through partner marketplaces including Salesforce AppExchange and HubSpot ecosystem channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in lead capture software rests on automation-driven cost compression in data engineering workflows and premium-tier migration toward intent-data fusion capabilities.
For Market Incumbents: Hedge against consolidation pressure by deepening proprietary data network effects through exclusive third-party feed partnerships and progressive profiling algorithm licensing. Defensive positioning requires SOC 2 Type II and ISO 27001 certification investment to maintain BFSI procurement access. Capacity expansion in Bangalore and Hyderabad addresses talent scarcity while reducing implementation delivery costs. For New Entrants and Emerging Players: The price-point gap between Apollo.io-tier enrichment platforms and basic form builders creates white-space opportunity in localized compliance-first deployments for Brazil's LGPD-maturing market. Target telemarketing automation for Indian BFSI outbound operations under TRAI DND registry protocols. Channel partner co-development with regional system integrators accelerates enterprise trust acquisition without direct sales infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where subscription fatigue compresses evaluation timelines toward unified capture-to-close platforms. Long-term viability favors vendors with captive data network effects and regulatory module modularity across GDPR, EU AI Act, and India's Digital Personal Data Protection Act frameworks. Acquisition target archetype: specialized intent-data layerers with enterprise account-based sales penetration. Signal to watch: procurement committee mandates for algorithmic explainability documentation under automated decision-making risk classifications.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native CRM connectors eliminate manual lead handoff delays for distributed sales organizations. |
| Strategic Partnership | Exclusive data feed agreements with firmographic networks establish competitive moats against point solutions. |
| Product Launch | Progressive profiling modules transform anonymous visitor identification without form abandonment friction. |
| Acquisition of Specialist Firm | Intent-data layering capabilities deepen enterprise account-based marketing program penetration. |
| Geographic Expansion | Localized compliance-first deployments capture Brazil LGPD enforcement maturity lag against European standards. |
Research Methodology
Bottom-up deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with CTOs, revenue operations leaders, data privacy officers, and integration specialists informed functional requirement prioritization and procurement timeline validation. Secondary sources encompassed SEC SaaS company filings, hyperscaler partnership disclosures, GDPR enforcement action databases, and EU AI Act implementation guidance documents. Triangulation across stakeholder perspectives and documentary evidence established segmentation boundaries and competitive positioning assessments.
Input-output matrix framing connects lead volume assumptions by deployment tier to revenue per customer metrics across cloud-based, on-premises, hybrid, and SaaS architectures. Segmentation dimensions modeled include deployment model, solution bundle depth, use-case specificity, and end-user vertical regulatory complexity. CAGRs derived from fitted growth curves against historical adoption patterns and privacy enforcement trajectory projections. Industry-specific forecast inputs incorporated consent-layer implementation cost curves and marketing automation consolidation velocity indices.
The model assumes a particular technology adoption path; alternative pathways for AI-native predictive intent scoring would alter the outlook if explainability documentation burdens exceed implementation timeline tolerance. Forecasts reflect assumptions on regulatory enforcement harmonization across fragmented privacy frameworks. Deviation in EU AI Act risk-classification interpretation or India's Digital Personal Data Protection Act consent-automation mandate timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Mobile Tracking Software Market
Software & Services
3D CAD Software Market
Software & Services
Servicenow Tech Services Market
Software & Services
Team Collaboration Software Market
Software & Services
Global Technical Illustration Software Market
Software & Services
Russian IT Software and Services Market
Software & Services
Global Audience Response Software Market
Software & Services
Software Testing Tools Market
Software & Services
Urban Planning Software and Services Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Global Software Quality Assurance Market
Software & Services
Global Note Taking App Market
Software & Services
Driver Updater Software Market
Software & Services
Production Optimization Software Market
Software & Services
Global Applicant Tracking Software Market