
 Laboratory Furnaces Market | 2026-2036
Laboratory Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Furnaces Market Outlook
Modular furnace configurations with swappable heating elements and interchangeable chamber sizes is pivoting procurement patterns toward customizable platforms rather than fixed-capacity units. Thermo Fisher Scientific leverages its life sciences distribution network to bundle thermal analysis software with furnace hardware. Nabertherm GmbH anchors its position through captive production of ceramic fiber insulation in Germany. MTI Corporation specializes in compact benchtop systems for university research budgets.
Laboratory furnaces are enclosed heating devices designed to reach controlled temperatures from 300°C to over 1,800°C using resistive heating elements, ceramic insulation, and programmable temperature controllers for precise thermal processing of samples. Their primary purpose spans ashing organic matter, sintering ceramics, and heat-treating metals for quality verification. Muffle furnaces dominate routine ashing work in environmental and food safety labs where standardized protocols require uniform heat distribution. High-temperature furnaces above 1,600°C command premium positioning in materials science and aerospace alloy development. Electric technology leads installed base but faces selective displacement by induction heating in specialized metallurgical applications.
FDA process validation guidelines and EPA Method 5 emissions testing standards shape equipment specifications for pharmaceutical and environmental laboratories in the United States. REACH compliance in Europe restricts certain refractory ceramic fiber compositions, pushing manufacturers toward biosoluble alternatives. ISO 13579 energy efficiency standards for industrial furnaces are extending into laboratory-scale equipment procurement criteria. Stakeholders must monitor evolving thermal process documentation requirements across regulated industries while assessing induction technology migration timelines.
Market Dynamics
Modular furnace platforms with swappable heating elements and interchangeable chamber configurations are compressing replacement cycles as laboratories prioritize adaptability over fixed-capacity investments.
Growth Catalysts
- FDA Process Validation:Pharmaceutical quality control labs in the United States must document thermal processing parameters, mandating programmable controllers and data-logging capabilities in new equipment purchases.
- REACH Compliance Transition:European manufacturers are converting to biosoluble ceramic fiber insulation, creating replacement demand across installed bases using legacy refractory compositions.
- Induction Heating Migration:Specialized metallurgical applications above 1,200°C are adopting electromagnetic heating for faster ramp rates and reduced oxidation, pulling equipment upgrades in materials science departments.
Market Restraints
- Refractory Material Concentration:High-purity alumina and zirconia supply concentrates among Chinese producers, exposing European furnace manufacturers to input volatility and export control risks.
- Technical Ceiling at 1,800°C:Resistive heating elements face fundamental material limits for ultra-high-temperature sintering, constraining addressable demand in aerospace alloy development.
- ISO 13579 Adoption Friction:Energy efficiency certification requirements extend procurement timelines as laboratories must validate consumption metrics before budget approval.
Strategic Opportunities
- University Research Budgets:Compact benchtop systems priced below institutional capital thresholds can capture demand from materials science departments with constrained funding.
- EPA Method 5 Alignment:Environmental testing laboratories require standardized ashing protocols, creating specification lock-in for equipment meeting particulate emissions documentation standards.
- Software-Hardware Bundling:Thermal analysis platforms integrating temperature control with data visualization are displacing standalone furnace purchases in pharmaceutical development workflows.
Industry Challenges
- Thermal Process Documentation:FDA 21 CFR Part 11 compliance for electronic records demands specialized validation expertise that smaller laboratory operators struggle to maintain in-house.
- Legacy System Integration:Existing LIMS and building management protocols require custom middleware development, extending deployment timelines and inflating project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Furnaces Market |
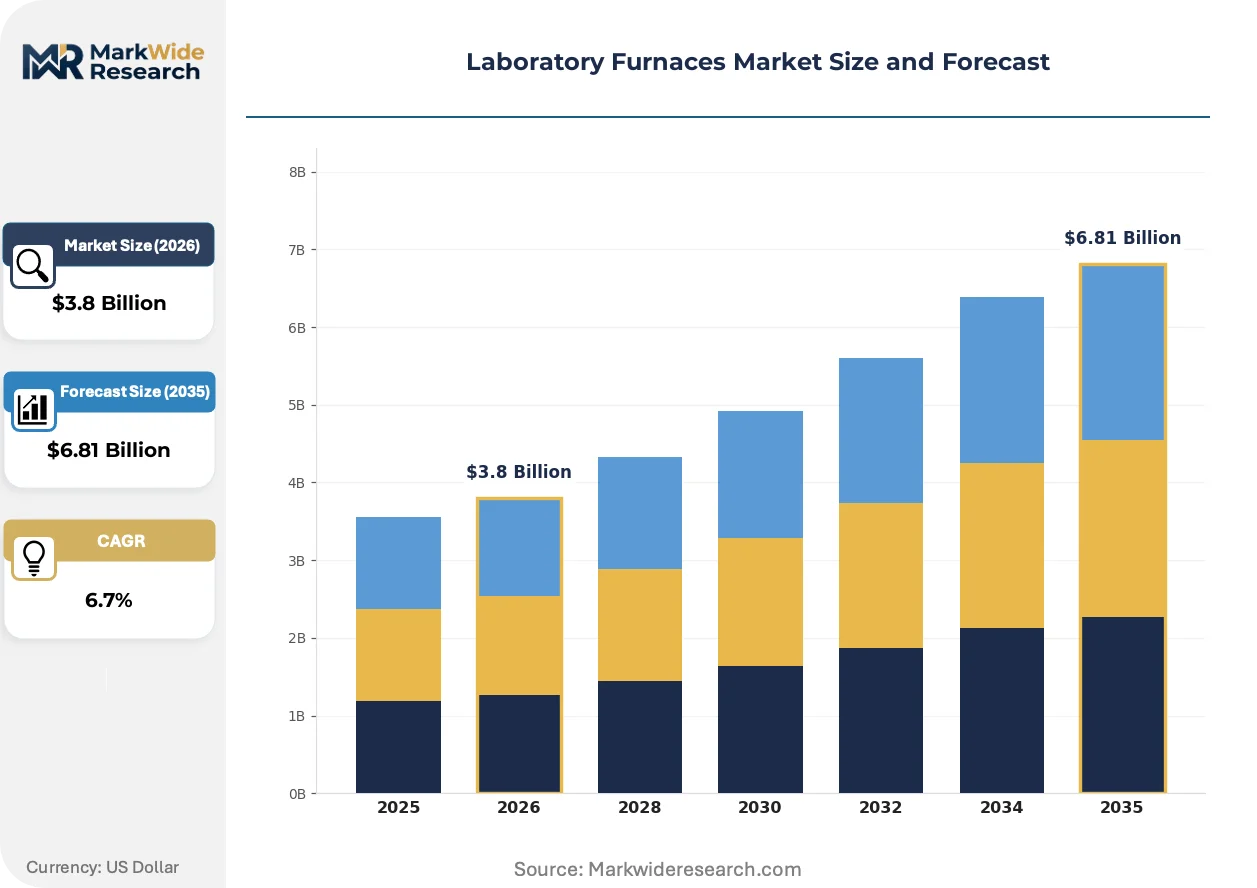
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Box Furnaces, Chamber Furnaces, Muffle Furnaces, High-Temperature Furnaces Technology: Electric, Gas, Infrared, Induction End User: Research Laboratories, Industrial Labs, Educational Institutions, Testing Facilities Application: Material Testing, Ashing, Heat Treatment, Sintering |
| Companies Covered | Yamato Scientific Co., Ltd., MTI Corporation, Thermo Fisher Scientific, Materials Research Furnaces, LLC, CM Furnaces, Inc., Nabertherm GmbH, Sentro Tech Corporation, Abbott Furnace Company, Carbolite Gero Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Furnaces Market Strategic Shifts
Temperature control intelligence and connectivity architectures are redefining how laboratories specify thermal processing equipment, shifting value capture toward integrated platforms.
Programmable logic controllers with embedded PID algorithms are automating thermal profile execution, reducing operator intervention in pharmaceutical stability testing. Quality control departments at generic drug manufacturers are adopting these systems to compress batch documentation preparation. The technology is automating compliance workflows that previously required manual temperature logging and transcription verification.
REACH restrictions on refractory ceramic fiber classifications are compelling insulation material transitions across European supply chains. Manufacturers must reformulate chamber linings using biosoluble alkaline earth silicate compositions to maintain market access. Germany's industrial research corridor around Jülich and Aachen faces the most concentrated compliance pressure given its density of high-temperature materials development facilities.
Service contract unbundling is fragmenting how laboratories acquire thermal processing capability. Pharmaceutical operators are separating equipment purchase from validation support and preventive maintenance, creating discrete procurement decisions. This pattern is most visible in the United States where FDA inspection readiness requirements drive specialized third-party qualification services independent of original equipment supply.
Laboratory Furnaces Market Segmentation
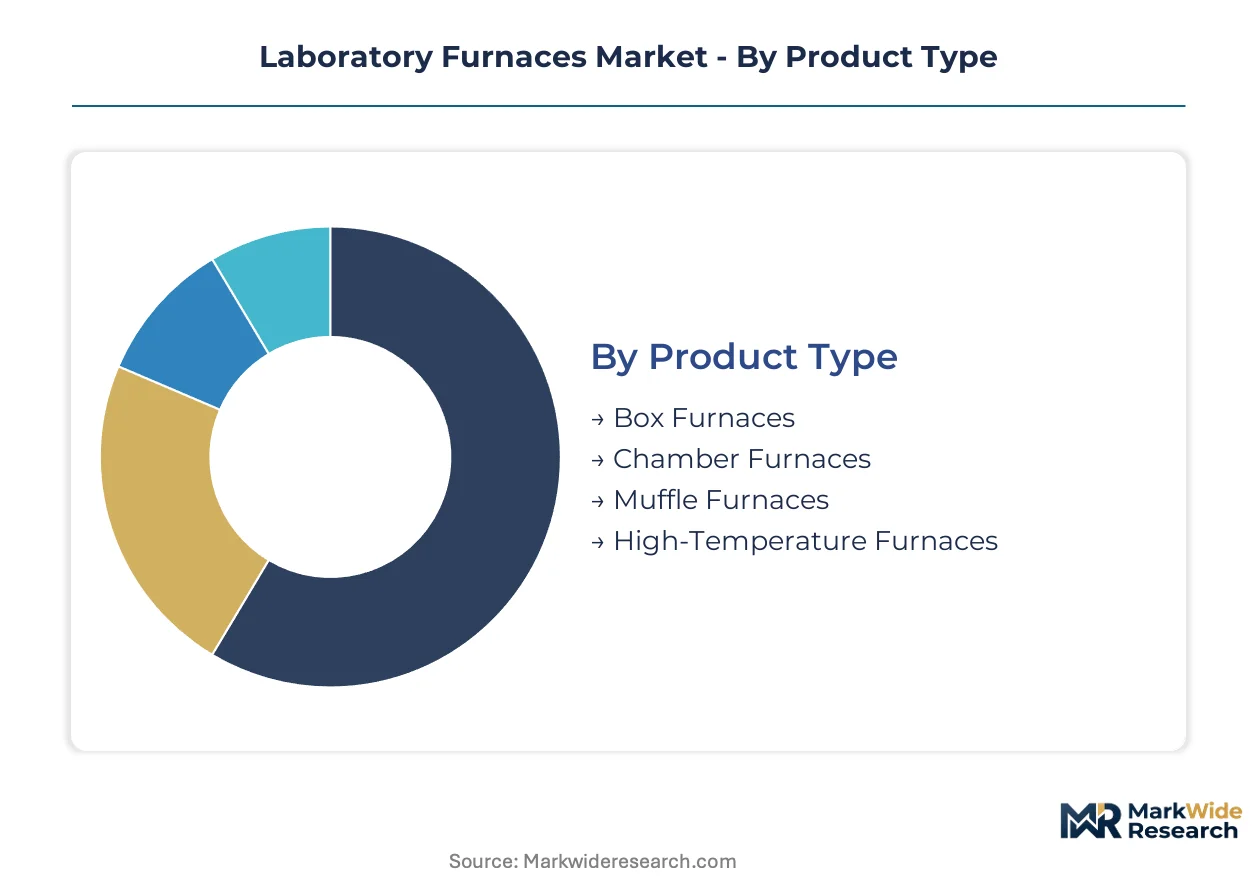
Laboratory furnace procurement patterns diverge sharply across product configurations, heating technologies, and institutional end-users. Each segment carries distinct specification requirements, compliance burdens, and supplier relationships that shape competitive positioning.
Product Type:
Supply concentration in ceramic fiber insulation and heating element manufacturing tilts competitive advantage toward furnace types with standardized chamber geometries.
- Box Furnaces:Rectangular chamber designs with front-loading access dominate routine thermal processing in quality control environments. Universities in Germany's industrial research corridor around Jülich and Aachen specify these units for materials characterization workflows, constrained by REACH-mandated insulation transitions.
- Muffle Furnaces:Enclosed heating chambers with isolated combustion zones serve standardized ashing protocols in environmental testing laboratories. EPA Method 5 emissions documentation requirements in the United States lock in procurement specifications for particulate analysis applications.
- Chamber Furnaces:Configurable internal volumes accommodate batch variability in pharmaceutical stability testing.
- High-Temperature Furnaces:Systems exceeding 1,600°C address aerospace alloy development and advanced ceramics sintering.
Today's leader: Muffle Furnaces. Tomorrow's challenger: High-Temperature Furnaces.
Technology:
Cost tier differentiation separates premium electromagnetic systems from commodity resistive heating across institutional budget categories.
- Electric:Resistive heating elements using silicon carbide or molybdenum disilicide dominate installed bases through programmable temperature control precision. Pharmaceutical quality control labs in the United States mandate these systems for FDA process validation documentation, despite fundamental material limits near 1,800°C.
- Induction:Electromagnetic field generation enables rapid ramp rates and reduced oxidation in specialized metallurgical applications above 1,200°C. Materials science departments with constrained funding face procurement barriers from elevated capital requirements.
- Gas:Combustion-based heating persists in high-volume industrial laboratory settings.
- Infrared:Radiant heat transfer suits surface treatment and rapid thermal processing.
Electric technology commands current volume. Induction heating climbs the fastest in materials science adoption.
End User:
Customer type determines specification complexity, with regulated industries demanding validation support that fragments procurement decisions.
- Research Laboratories:Academic and government facilities prioritize modular platforms with swappable configurations over fixed-capacity investments. Compact benchtop systems priced below institutional capital thresholds capture demand from university materials science departments.
- Industrial Labs:Corporate R&D and quality control operations require integration with existing LIMS and building management protocols.
- Educational Institutions:Undergraduate training facilities emphasize durability and simplified operation.
- Testing Facilities:Third-party certification laboratories face ISO 13579 energy efficiency certification friction extending procurement timelines.
Industrial Labs anchor current revenue. Research Laboratories gain share fastest through modular platform transitions.
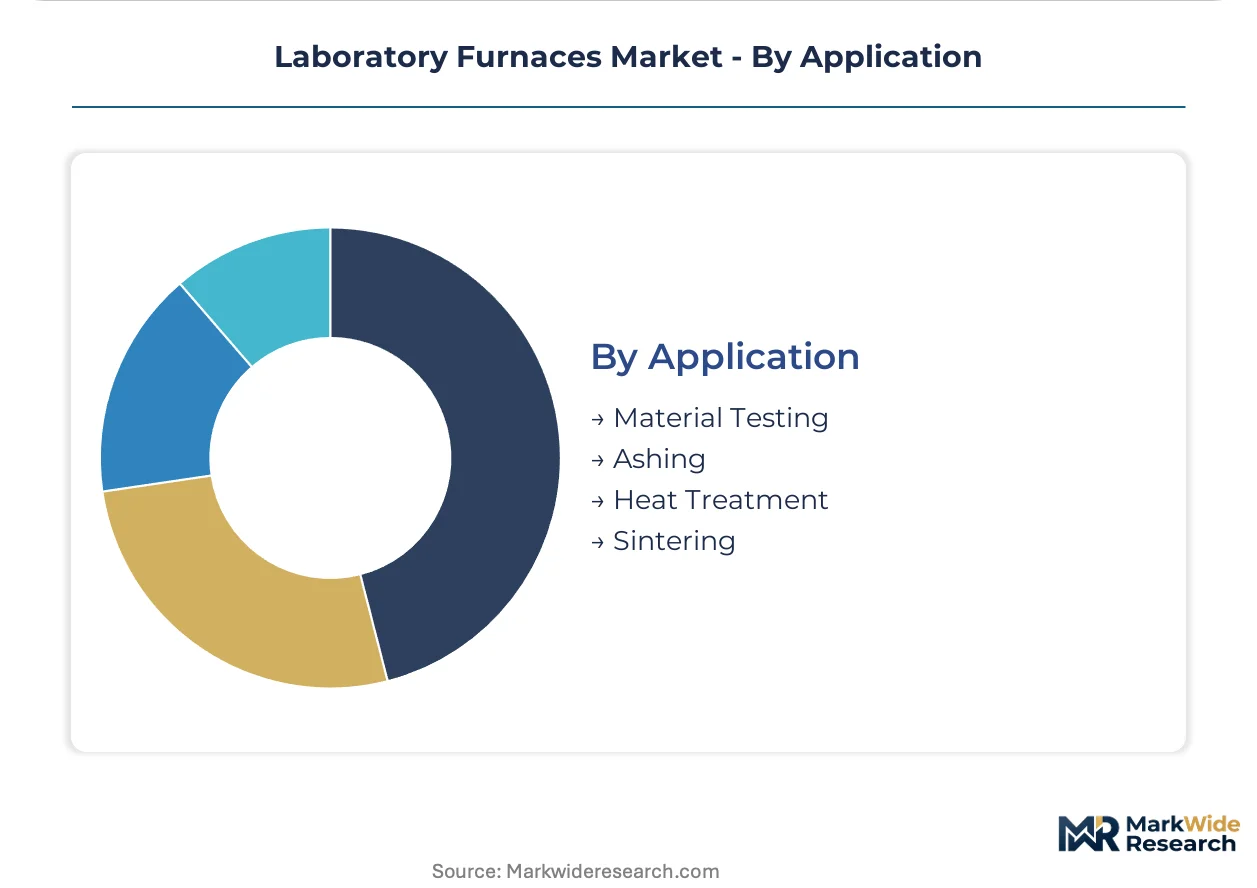
Application:
Application maturity varies, with standardized protocols creating specification lock-in while emerging materials processes demand flexible thermal profiles.
- Ashing:Controlled combustion of organic matter for gravimetric analysis follows rigid EPA and FDA protocols. Environmental testing laboratories in the United States require standardized equipment meeting particulate emissions documentation standards.
- Sintering:Densification of ceramic and metal powders demands precise atmosphere control and temperature uniformity. Aerospace alloy development in Germany's high-temperature materials facilities pushes equipment specifications toward ultra-high-temperature capabilities.
- Material Testing:Mechanical and thermal property characterization spans diverse institutional requirements.
- Heat Treatment:Metallurgical modification for hardness and microstructure adjustment serves industrial quality verification.
Ashing dominates procedural standardization. Sintering shows steepest expansion trajectory in advanced materials development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Laboratory furnace manufacturing traces its industrial lineage to Germany's precision engineering tradition and the United States' post-war scientific instrumentation expansion. These origins established quality benchmarks that persist in contemporary procurement specifications. Regulatory divergence now shapes distinct regional equipment requirements.
United States
Pharmaceutical quality control labs in Massachusetts and North Carolina are expanding thermal processing capacity for generic drug manufacturing. FDA 21 CFR Part 11 compliance mandates programmable controllers with electronic records capabilities. The Research Triangle Park cluster anchors demand from contract research organizations validating thermal stability protocols.
Germany
High-temperature materials development in the Jülich-Aachen corridor drives premium furnace specifications for aerospace alloy research. REACH restrictions on refractory ceramic fiber classifications compel insulation material transitions across domestic supply chains. Bavarian equipment manufacturers are reformulating chamber linings using biosoluble alkaline earth silicate compositions.
China
Materials science departments in Beijing and Shanghai universities are procuring compact benchtop systems for constrained research budgets. The national pharmaceutical regulator's alignment with ICH quality guidelines elevates documentation requirements for thermal processing equipment. Yangtze River Delta industrial labs are adopting modular platforms with swappable configurations.
Japan
Automotive and electronics manufacturers in Nagoya and Osaka maintain captive R&D furnace installations for quality verification. METI energy efficiency standards for industrial equipment extend procurement criteria toward consumption metrics validation. Kansai-region ceramics producers are upgrading sintering capacity for advanced electronic substrate development.
India
Central Drug Standard Control Organization process validation guidelines are shaping equipment specifications for pharmaceutical quality control labs in Hyderabad and Mumbai. Maharashtra-based generic drug manufacturers are prioritizing programmable thermal analysis platforms. Bangalore materials research institutes face procurement barriers from elevated capital requirements for induction heating systems.
Laboratory Furnaces Market Competitive Environment
The competitive structure tilts toward diversified scientific instrumentation conglomerates with captive thermal processing divisions. Tiered specialization separates premium high-temperature system fabricators from commodity benchtop suppliers. Three archetypes dominate: life sciences distribution integrators bundling software with hardware, German engineering specialists with in-house insulation production, and compact-system specialists targeting academic budget constraints. Geographic expansion and strategic software-hardware bundling constitute the dominant competitive vectors.
Among diversified instrumentation conglomerates, Thermo Fisher Scientific exemplifies the distribution-integrated archetype leveraging life sciences networks. Nabertherm GmbH anchors the German engineering specialist position through captive ceramic fiber insulation production. MTI Corporation occupies the compact-system specialist tier targeting university research budgets with benchtop configurations.
| Leading Market Players |
|---|
| Yamato Scientific Co., Ltd. |
| MTI Corporation |
| Thermo Fisher Scientific |
| Materials Research Furnaces, LLC |
| CM Furnaces, Inc. |
| Nabertherm GmbH |
| Sentro Tech Corporation |
| Abbott Furnace Company |
| Carbolite Gero Limited |
| Others |
Value Chain & Pricing Dynamics
FDA process validation mandates in the United States are compressing procurement timelines for programmable furnace systems with embedded data-logging capabilities, forcing European manufacturers to absorb biosoluble insulation reformulation costs while defending price positions against Asian benchtop competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates high-temperature systems above 1,600°C from modular mid-range platforms and entry-level benchtop units. Price differentiation hinges on ISO 13579 energy efficiency certification tier and after-sales validation support bundling. Cost compression in the economy tier is intensifying as Chinese producers expand compact system exports. University materials science departments exhibit highest price sensitivity; aerospace alloy development facilities show lowest.
Supply Chain Analysis
Direct-to-laboratory channels handle institutional buyer demand, while distributor networks serve smaller testing facilities and educational markets. Manufacturing concentrates in Germany, China, and the United States, with high-purity alumina and zirconia heating elements drawing from Chinese refractory producers. Biosoluble ceramic fiber insulation sources from German and Japanese specialty material suppliers. Single-source vulnerability in refractory ceramic fiber feedstocks exposes European fabricators to export control disruptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: German engineering premiums capture aerospace alloy research budgets while Chinese manufacturing scale exploits university procurement constraints across Asia-Pacific and emerging markets.
For Market Incumbents: Extend software-hardware bundling architectures to lock in pharmaceutical quality control workflows before induction heating systems displace resistive platforms above 1,200°C. Deepen captive insulation production to offset REACH-driven biosoluble material cost inflation. Prioritize validation service unbundling to capture third-party qualification revenue streams independent of equipment sales. For New Entrants and Emerging Players: Scientific instrumentation distributors with existing life sciences relationships offer the most penetrable channel infrastructure for compact benchtop furnace penetration. Target India's CDSCO-aligned pharmaceutical quality control labs in Hyderabad and Mumbai where programmable thermal analysis platforms face supply gaps. Lead with modular platform configurations priced below institutional capital thresholds to bypass incumbent specification lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with German engineering specialists possessing in-house ceramic fiber insulation production and established REACH compliance infrastructure. Five-to-ten year viability favors acquisition targets with captive material supply and pharmaceutical validation service capabilities. Monitor induction heating adoption rates in materials science departments as inflection signal for resistive technology displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Biosoluble Insulation Reformulation | REACH compliance transitions in Germany's Jülich-Aachen corridor drive replacement demand across installed bases. |
| Software-Hardware Bundling | Thermal analysis platforms integrating data visualization displace standalone furnace purchases in FDA-regulated workflows. |
| Modular Platform Expansion | Swappable heating element configurations capture university research budgets prioritizing adaptability over fixed capacity. |
| Validation Service Unbundling | Third-party qualification services separate from equipment supply to address FDA 21 CFR Part 11 compliance gaps. |
| Induction Heating Migration | Electromagnetic systems above 1,200°C penetrate aerospace alloy development applications demanding rapid ramp rates. |
Study Parameters
Multiple input streams — structured interviews with laboratory equipment procurement managers, thermal processing R&D directors, and aftermarket service heads; regulatory filing analysis from FDA, ECHA, and CDSCO databases; and trade flow data from customs records — were reconciled through bottom-up demand modeling and top-down market sizing triangulation.
Historical shipment volumes were cross-referenced against expert panel inputs to anchor growth trajectory assumptions across the analysis window. Segmentation modeling incorporated product configuration, heating technology type, end-user institutional category, and application protocol requirements. CAGRs were derived from installed base replacement cycles, regulatory compliance transition timelines, and technology migration patterns in materials science research funding.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH regulatory expansion, induction heating cost curves, and pharmaceutical capital expenditure cycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Human Milk Analyzers Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
UK Pipette Tips Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Automated Plate Readers Market
Laboratory Equipment
Global Laboratory Plasticware Market
Laboratory Equipment
Laboratory Temperature Control Units Market
Laboratory Equipment
ASEAN Laboratory Equipment Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Microplate Handling Instruments Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Global Graduated Cylinder Market
Laboratory Equipment
Western Blotting Processors Market