
 Centrifuge Tubes Market | 2026-2036
Centrifuge Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifuge Tubes Market Outlook
ISO 13485 certification is rotating as the primary gating mechanism for centrifuge tube suppliers seeking entry into regulated clinical channels. Thermo Fisher Scientific leverages its diagnostic distribution network to sustain shelf presence across North American hospital systems. SARSTEDT anchors European supply through vertically controlled polymer molding operations in Germany. Greiner Bio One International competes on pre-sterilized, pyrogen-free product lines targeting pharmaceutical quality labs.
Centrifuge tubes are cylindrical vessels engineered from medical-grade polypropylene or polycarbonate, typically rated for rotational forces between 10,000 and 30,000 × g, designed to separate fluid components by density gradient during high-speed rotation. Conical tubes dominate clinical blood processing workflows where volume graduation accuracy and cap seal integrity prevent aerosol leakage during centrifugation. Microcentrifuge tubes capture expanding share in genomics workflows as PCR and DNA extraction protocols miniaturize reaction volumes. Polypropylene formulations lead material selection for thermal stability across autoclave and cryogenic storage cycles.
FDA enforces Class I medical device controls over centrifuge tubes used in diagnostic applications, while EMA's MDR framework imposes stricter biocompatibility and traceability documentation on European suppliers. ISO 10993 cytotoxicity testing now gates market access for any polymer contacting human-derived specimens. Stakeholders must monitor evolving polymer recycling mandates from the EU Green Deal and EPA sustainable procurement guidelines, as single-use plastic restrictions threaten cost structures in high-throughput diagnostic settings.
Market Dynamics
Workflow automation in clinical diagnostic centers is compressing procurement cycles and mandating sterile single-use tube formats that integrate with robotic liquid handling systems.
Growth Catalysts
- ISO 13485 certification mandates:Clinical laboratories in the United States and Germany now require supplier quality management certification as a procurement gate, filtering out uncertified polymer converters.
- PCR protocol miniaturization:Genomics laboratories are scaling microcentrifuge tube volumes downward to match reduced reaction footprints in DNA extraction workflows.
- Centralized hospital network expansion:China's tier-one municipal health systems are consolidating purchasing authority, driving volume concentration toward pre-sterilized tube suppliers.
Market Restraints
- Medical-grade polypropylene supply concentration:Polymer feedstock production clusters in the US Gulf Coast and Northeast Asia expose tube manufacturers to regional disruption cascades.
- EU Green Deal plastic recycling mandates:Single-use medical plastic restrictions threaten cost structures in high-throughput diagnostic settings where sterile disposables dominate.
- Autoclave thermal stability ceiling:Polypropylene formulations face hard upper temperature limits that constrain reuse protocols in resource-constrained settings.
Strategic Opportunities
- Indian diagnostic laboratory buildout:CDSCO regulatory streamlining and private hospital chain expansion create procurement volume in Mumbai and Bangalore clusters.
- Cryogenic storage integration:Biobank sample preservation protocols are converging with centrifuge tube thermal cycling requirements, opening specification overlap.
- Direct-to-laboratory distribution platforms:E-procurement portals are bypassing traditional medical distributor markups in German university hospital networks.
Industry Challenges
- ISO 10993 cytotoxicity documentation backlog:Biocompatibility testing timelines for new polymer grades are extending supplier certification cycles.
- Legacy ERP integration with automated procurement:Hospital supply chain systems require middleware development to connect with tube vendor digital catalogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifuge Tubes Market |
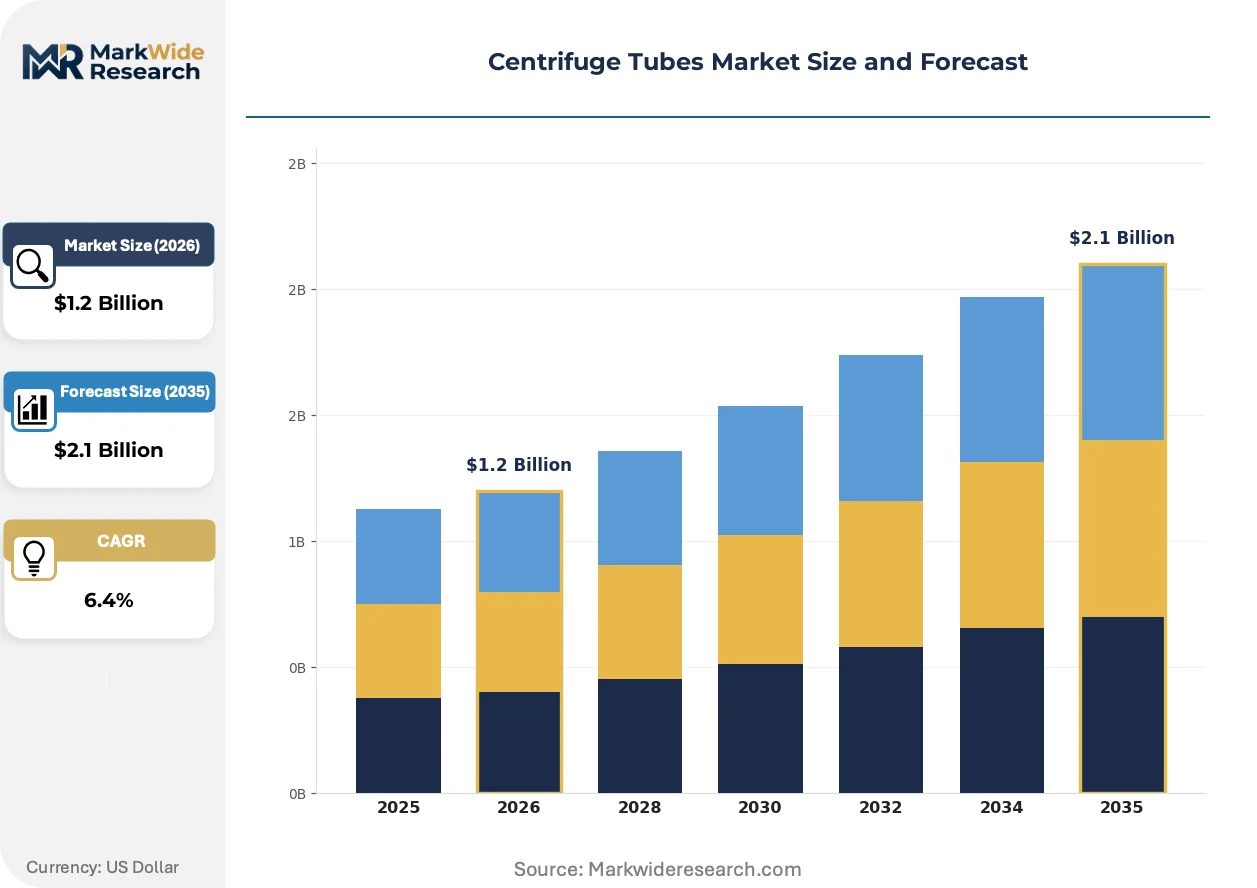
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcentrifuge Tubes, Conical Tubes, Cryogenic Tubes, Filter Tubes, Screw Cap Tubes Material: Polypropylene, Polycarbonate, Polystyrene, Polyethylene, Glass Application: Sample Preparation, Cell Culture, Blood Collection, Protein Purification, DNA Extraction End User: Research Laboratories, Pharmaceutical Firms, Biotech Companies, Diagnostic Centers, Academic Institutions |
| Companies Covered | Medline Industries, Kimble Chase Life Science Research Products, Thermo Fisher Scientific, Stockwell Scientific, Abdos Labtech, SARSTEDT, Labcon North America, Corning, Greiner Bio One International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifuge Tubes Market Strategic Shifts
Material science advances and regulatory documentation requirements are reshaping competitive differentiation around thermal performance traceability and supply chain transparency rather than commodity volume.
Graduated conical tubes with laser-etched volume markings are supplanting molded graduation lines in clinical blood processing workflows. North American hospital laboratories are adopting these formats for automated liquid handling compatibility. This shift is compressing price premiums for precision-molded alternatives while elevating specification requirements for optical clarity and chemical resistance.
EMA's MDR biocompatibility traceability framework is tightening documentation burdens on European suppliers. Manufacturers must now maintain batch-level polymer sourcing records for human-derived specimen contact applications. German and Swiss medical device producers are responding by backward integrating into compounding operations to secure audit trail control.
Consolidated buying contracts are displacing spot purchasing in multi-site hospital systems. United States integrated delivery networks are centralizing centrifuge tube procurement through single-source agreements with performance metrics. This concentration is visible most acutely in California and Texas health system alliances where annual volume commitments lock in multi-year supplier relationships.
Centrifuge Tubes Market Segmentation
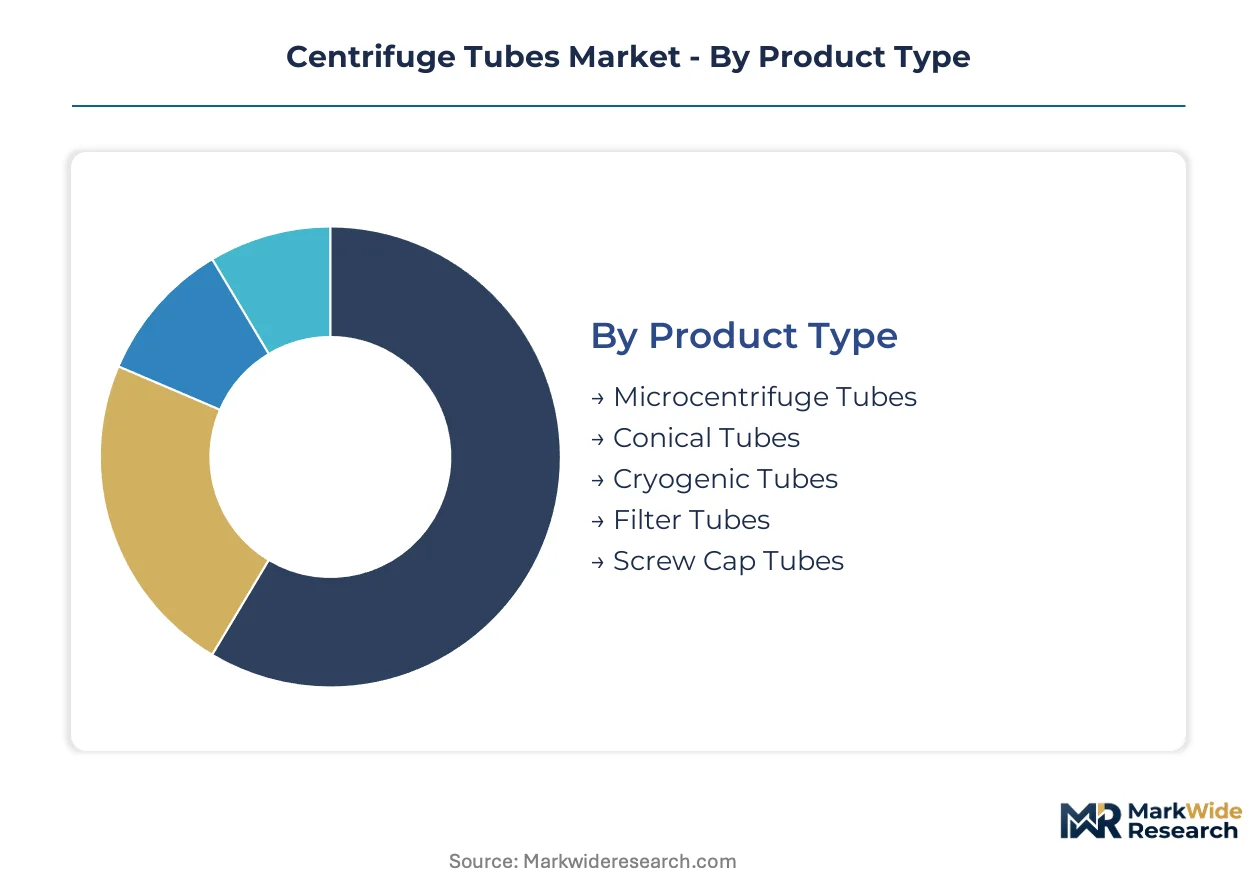
Centrifuge tube procurement decisions fragment across four distinct category axes. Product geometry and material composition determine compatibility with automated workflows and thermal cycling protocols. Application specificity and end-user scale dictate volume commitments and certification requirements.
Product Type:
Margin pools concentrate in tubes that integrate with robotic liquid handling systems and maintain seal integrity under maximum rotational force.
- Conical Tubes:Tapered-bottom vessels with molded graduation lines enable precise volume measurement during blood processing workflows. Clinical diagnostic centers in the United States specify these formats for automated centrifugation protocols where aerosol containment prevents cross-contamination. FDA Class I device controls mandate lot traceability for suppliers serving hospital laboratory networks.
- Microcentrifuge Tubes:Small-capacity vessels engineered for PCR and DNA extraction miniaturization protocols. Genomics laboratories in Germany and China are scaling procurement downward to match reduced reaction footprints. ISO 10993 cytotoxicity documentation requirements extend supplier certification cycles for polymer grades contacting human-derived specimens.
- Cryogenic Tubes:Threaded-cap vessels rated for ultra-low temperature storage in biobank preservation protocols.
- Filter Tubes:Membrane-integrated formats combining centrifugation with solid-phase separation in protein purification workflows.
- Screw Cap Tubes:Leak-resistant closures for long-term sample archiving and transport stability.
Conical tubes hold installed capacity. Microcentrifuge tubes are rotating up the share rankings.
Material:
Cost tier differentiation separates medical-grade certified polymers from commodity-grade alternatives in procurement specifications.
- Polypropylene:Thermoplastic polymer dominating material selection for autoclave stability and cryogenic storage cycling. Biopharma R&D clusters in the United States, Germany, and China specify this formulation for thermal performance across sterilization protocols. EMA MDR biocompatibility traceability requirements tighten batch-level sourcing documentation burdens on European suppliers.
- Polycarbonate:Transparent thermoplastic selected for optical clarity in visual sample inspection applications. Pharmaceutical quality labs prioritize this material for chemical resistance during aggressive solvent exposure. EU Green Deal recycling mandates threaten cost structures for single-use medical plastic consumption in high-throughput settings.
- Polystyrene:Rigid polymer for low-force applications where disposability outweighs thermal cycling requirements.
- Polyethylene:Flexible formulation for cap and seal components requiring compression set resistance.
- Glass:Inert material retained for solvent compatibility beyond polymer chemical resistance limits.
Polypropylene commands volume scale. Polycarbonate is gaining specification share in quality-controlled environments.
Application:
Customer type concentration varies sharply across workflow automation maturity and regulatory exposure levels.
- Sample Preparation:Foundational centrifugation step preceding analytical instrumentation in clinical and research settings. Diagnostic centers expanding automation procurement specify sterile single-use formats integrating with robotic liquid handling systems. ISO 13485 certification gates supplier entry into regulated clinical channels in the United States and Germany.
- DNA Extraction:Nucleic acid isolation protocols driving microcentrifuge tube miniaturization. Genomics laboratories in China and India are scaling reaction volume downward to match PCR efficiency improvements. CDSCO regulatory streamlining in Mumbai and Bangalore clusters creates procurement volume in private hospital chain expansion.
- Blood Collection:Clinical phlebotomy workflows requiring graduated conical formats with cap seal integrity.
- Cell Culture:Sterile expansion protocols for biologics manufacturing and regenerative medicine research.
- Protein Purification:Density gradient and membrane filtration applications in biopharma process development.
Sample preparation anchors current procurement volume. DNA extraction is climbing the fastest as genomics workflows expand.
End User:
Volume concentration tracks centralized purchasing authority consolidation in multi-site health system networks.
- Diagnostic Centers:High-throughput clinical laboratories driving sterile single-use tube procurement as workflow automation spreads. United States integrated delivery networks centralize purchasing through single-source agreements with performance metrics. California and Texas health system alliances lock in multi-year supplier relationships through annual volume commitments.
- Pharmaceutical Firms:Quality-controlled manufacturing and analytical development operations specifying pre-sterilized, pyrogen-free product lines. German and Swiss medical device producers backward integrate into compounding operations to secure EMA MDR audit trail control. Batch-level polymer sourcing records are now mandatory for human-derived specimen contact applications.
- Research Laboratories:Academic and government facilities with fragmented procurement and lower certification stringency.
- Biotech Companies:Venture-funded development stage operations prioritizing speed over long-term supplier contracts.
- Academic Institutions:Price-sensitive procurement with spot purchasing patterns and minimal automation integration.
Diagnostic centers concentrate purchasing power. Pharmaceutical firms are expanding specification requirements fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic centers and pharmaceutical quality labs concentrate procurement authority in the United States, Germany, and China. Hospital network consolidation and biopharma R&D clustering drive sterile single-use tube volume in these three markets.
United States
FDA Class I medical device controls govern centrifuge tubes used in diagnostic applications. Integrated delivery networks in California and Texas centralize purchasing through single-source agreements with annual volume commitments. Greater Boston and San Francisco Bay Area biotech clusters specify pre-sterilized, pyrogen-free formats for automated liquid handling integration.
Germany
EMA's MDR framework imposes batch-level polymer sourcing documentation for human-derived specimen contact. Vertically controlled polymer molding operations in Baden-Württemberg and North Rhine-Westphalia secure audit trail control for medical device producers. Munich and Heidelberg university hospital networks bypass traditional distributor markups through direct e-procurement portals.
China
Tier-one municipal health systems in Beijing and Shanghai consolidate purchasing authority toward pre-sterilized tube suppliers. NMPA quality mandates for medical-grade plastics tighten material traceability requirements for polymer converters. Yangtze River Delta biopharma R&D clusters drive microcentrifuge tube procurement as genomics workflows expand.
India
CDSCO regulatory streamlining accelerates procurement volume in Mumbai and Bangalore diagnostic laboratory buildouts. Private hospital chain expansion creates demand for sterile single-use formats compatible with workflow automation. Maharashtra and Karnataka clusters concentrate purchasing authority as centralized laboratory networks replace fragmented spot buying.
Switzerland
Swissmedic biocompatibility requirements align with EMA MDR traceability standards for European market access. Basel and Zurich pharmaceutical quality labs specify polycarbonate formulations for optical clarity in solvent-exposed applications. German and Swiss producers backward integrate into compounding operations to secure polymer grade certification cycles.
Centrifuge Tubes Market Competitive Environment
Player mix skews toward diversified life science conglomerates with diagnostic distribution networks and specialized medical plastics manufacturers with captive molding operations. Consolidation pressure operates through ISO 13485 certification gates that filter uncertified polymer converters from regulated clinical channels. Two strategic archetypes dominate: vertically integrated European specialists with backward polymer control and North American distributors leveraging hospital system relationships. Competitive moves center on certification-driven supplier consolidation and direct e-procurement platform development bypassing traditional medical distributor markups.
Among diversified life science conglomerates, Thermo Fisher Scientific and Corning exemplify the distribution-network archetype, leveraging diagnostic channel presence to sustain shelf access across hospital laboratory networks. SARSTEDT anchors the European specialist tier with German-based vertically controlled molding operations securing EMA audit trail compliance. Greiner Bio One International occupies a position bridging both vectors, competing on pre-sterilized pyrogen-free product lines while maintaining Austrian production integration for pharmaceutical quality lab specifications.
| Leading Market Players |
|---|
| Medline Industries |
| Kimble Chase Life Science Research Products |
| Thermo Fisher Scientific |
| Stockwell Scientific |
| Abdos Labtech |
| SARSTEDT |
| Labcon North America |
| Corning |
| Greiner Bio One International |
| Others |
Value Chain & Pricing Dynamics
Medical-grade polypropylene substitution for polycarbonate in high-throughput diagnostic workflows simultaneously redistributes supply geography toward US Gulf Coast and Northeast Asian polymer clusters while compressing per-unit pricing economics for optical-grade alternatives.
Pricing Analysis
Cost-plus contracts with polypropylene resin indexation dominate procurement between tube manufacturers and hospital purchasing committees. Three-tier pricing structure across ISO 13485-certified premium, standard medical-grade, and uncertified economy levels separates suppliers by audit trail depth. Pricing pressure stems from EU Green Deal single-use plastic mandates threatening cost structures in sterile disposable consumption. Academic institutions exhibit highest price sensitivity through spot purchasing patterns, while pharmaceutical quality labs absorb premiums for pyrogen-free certification.
Supply Chain Analysis
Just-in-time inventory strategies prevail among automated diagnostic centers, though strategic stockpiling of medical-grade polypropylene feedstock is expanding among German and Swiss producers facing EMA MDR traceability documentation backlogs. Supply concentrates in the United States, Germany, and China where biopharma R&D clusters anchor polymer conversion capacity. Raw material dependencies center on propylene monomer, nucleating agents, and colorant masterbatches. Single-source vulnerability runs through concentrated medical-grade polymer compounding operations. Distribution runs through diagnostic distributor networks and direct e-procurement portals serving consolidated hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The centrifuge tube market functions as a service-attach opportunity where sterilization validation and lot-traceability documentation layers expand faster than commodity tube hardware. Recurring revenue from certification maintenance and audit support outpaces per-unit margin capture.
For Market Incumbents: Compound certification advantage by backward integrating into polymer compounding operations to secure EMA MDR batch-level sourcing control. Expand direct e-procurement platform deployment to bypass distributor markups in German university hospital networks. Defend against emerging Asian polymer converters by locking multi-year volume commitments with California and Texas integrated delivery networks. For New Entrants and Emerging Players: Digital lot-traceability services represent a service-layer gap where incumbents under-serve mid-sized diagnostic laboratories lacking ERP middleware for automated procurement integration. Target Indian private hospital chain expansion in Mumbai and Bangalore clusters where CDSCO regulatory streamlining creates procurement volume without entrenched supplier relationships. Lead with ISO 10993 cytotoxicity documentation acceleration as a differentiated go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive polymer molding and compounding operations. Long-term viability hinges on regulatory certification moats widening through MDR biocompatibility traceability requirements. Acquisition focus should center on German and Swiss mid-cap producers with backward-integrated supply chains. Watch for EU Green Deal recycling mandate enforcement as the inflection signal threatening single-use disposable economics.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Gates supplier entry into FDA-regulated US hospital laboratory networks. |
| Backward Polymer Integration | Secures EMA MDR batch-level sourcing documentation for European market access. |
| Direct E-Procurement Platform | Bypasses traditional medical distributor markups in German university hospital systems. |
| Cryogenic Storage Specification Expansion | Captures biobank sample preservation protocol convergence with thermal cycling requirements. |
| Indian Diagnostic Laboratory Partnership | Positions for CDSCO-regulated procurement volume in Mumbai and Bangalore clusters. |
Study Parameters
Operator-level perspectives from diagnostic laboratory directors, hospital purchasing committee managers, biomedical engineers, GPO contracts administrators, and polymer compounding technical directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement contract registries, and ISO certification authority records. Bottom-up tube volume modeling triangulated against top-down biopharma R&D expenditure patterns.
Sensitivity analysis tested forecast outputs against polymer feedstock price volatility, regulatory timeline slippage, and automation adoption rate variations across the projection horizon. Segmentation dimensions modeled include product geometry, material grade tier, application workflow, end-user scale, and regional regulatory cluster. CAGRs derived from weighted average of historical volume trends and forward-looking procurement intent indicators. Industry-specific inputs incorporated PCR protocol miniaturization rates and centralized hospital network consolidation trajectories.
Underlying assumptions cover sterile single-use format dominance, ISO 13485 certification gate persistence, and polymer recycling mandate enforcement timelines, with deviation risk concentrated in EU Green Deal implementation acceleration and medical-grade polypropylene supply disruption. Revision becomes warranted when single-use plastic restriction thresholds cross into diagnostic laboratory operational cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Laboratory Temperature Control Units Market
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Cell Analysis Instruments Market
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
Laboratory Fume Hoods Market
Laboratory Equipment
Laboratory Glassware and Plasticware Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Asia Pacific Cell Counting Market
Laboratory Equipment
ASEAN Laboratory Equipment Market
Laboratory Equipment
Portable Hemoglobin Analyzer Market
Laboratory Equipment
Cuvettes Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Pipettes and Accessories Market