
 Surface and Field Analytics Market | 2026-2036
Surface and Field Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Surface and Field Analytics Market Analysis
North American sensor fabrication capacity is restructuring as domestic foundries expand output for geospatial instrument cores. Thermo Fisher Scientific leverages its mass spectrometry heritage to anchor premium surface chemistry detection workflows. Bruker Corporation sustains R&D intensity in atomic force microscopy, competing for semiconductor metrology contracts. Danaher Corporation differentiates through vertical life sciences integration, extending diagnostics expertise into environmental sample analysis.
Surface and field analytics encompasses the acquisition, processing, and interpretation of spatially referenced data from terrestrial, aerial, and orbital platforms, typically resolving features at sub-meter to centimeter scales using multi-spectral, electromagnetic, or acoustic sensing modalities; its primary purpose is to transform raw geophysical signals into actionable intelligence for resource allocation, risk assessment, and operational planning across distributed physical environments. GIS technology occupies the largest installed base among technology segments, reflecting decades of municipal and utility investment in spatial data infrastructure. Satellite imagery registers the fastest expansion as commercial constellation operators drive revisit frequency and spectral resolution improvements. Predictive modeling solutions within the solution segment command disproportionate margin pools due to proprietary algorithm development and client-specific training data requirements.
The US EPA enforces site remediation standards that mandate validated field analytical methods, directly shaping instrument certification pathways and service provider qualifications. ESA's Copernicus program and the EU's INSPIRE directive collectively standardize data interoperability across member states, conditioning market access on compliance with specified metadata and accuracy thresholds. Stakeholders must monitor evolving AI governance frameworks, as automated feature extraction from geospatial imagery attracts escalating scrutiny from data protection and national security regulators.

Market Dynamics
Precision agriculture operations across the US Corn Belt are compressing sensor deployment cycles from annual to sub-seasonal intervals, forcing platform vendors to re-architect hardware for field durability and edge computing capacity. This demand compression is reshaping supplier qualification criteria and service-level structures.
Growth Catalysts
- CSRD disclosure mandates:The EU's Corporate Sustainability Reporting Directive compels land-intensive corporations to deploy verified field measurement systems for carbon stock verification and biodiversity baseline documentation.
- Spectral resolution leaps:Commercial satellite constellation operators are driving revisit frequency improvements that enable near-real-time crop stress detection and irrigation scheduling.
- Ruhr corridor convergence:Germany's mining remediation obligations and infrastructure monitoring requirements are concentrating demand for multi-modal surface analytics in a single industrial cluster.
Market Restraints
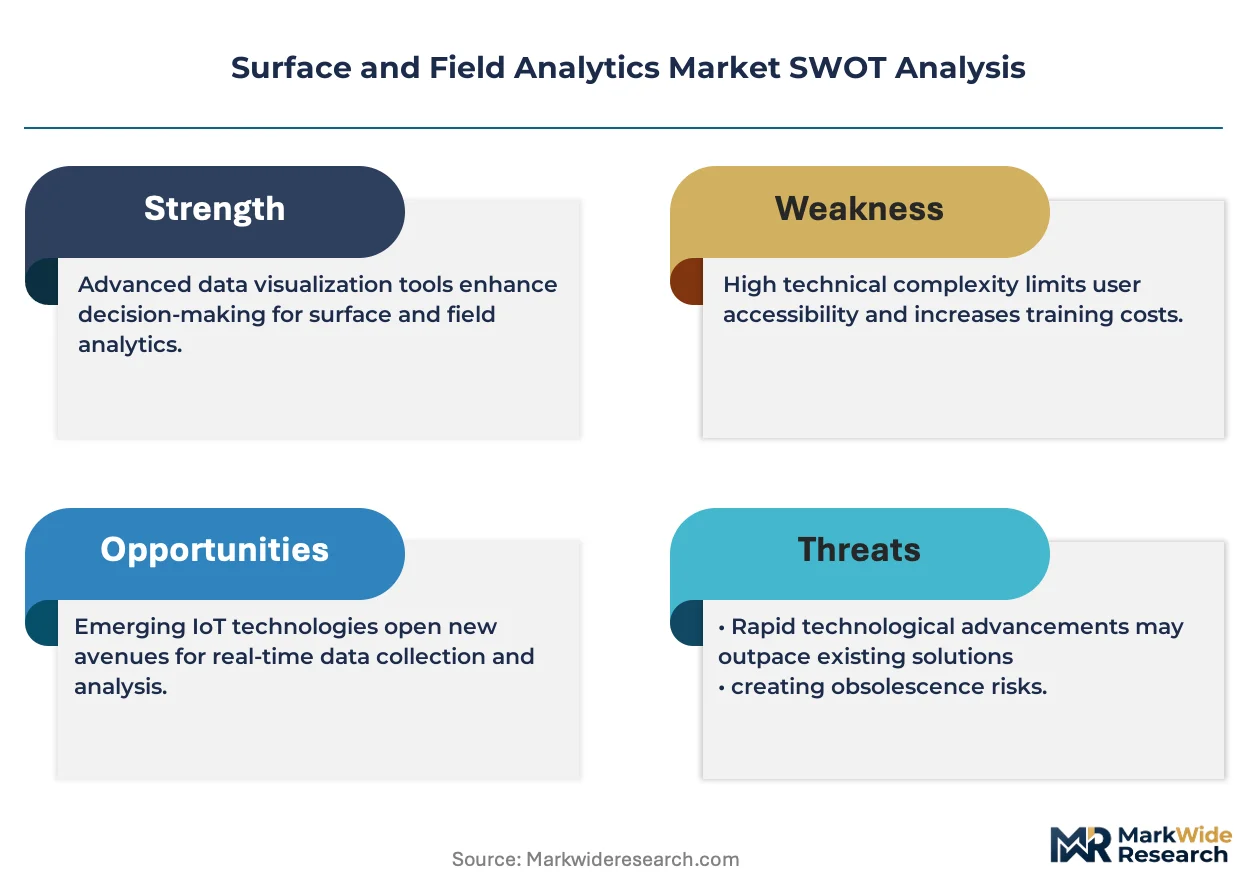
- Sensor fabrication concentration:Geospatial instrument core production remains concentrated in a limited number of domestic foundries, creating supply vulnerability for specialized multi-spectral arrays.
- Metrology-grade input costs:Atomic force microscopy components and precision optical substrates face price volatility tied to rare earth element sourcing constraints.
- Interoperability friction:ESA's Copernicus program and the EU's INSPIRE directive impose metadata and accuracy thresholds that condition market access on costly compliance adaptation.
Strategic Opportunities
- Yield prediction platform expansion:Soil nutrient mapping services remain underpenetrated in Eastern European agricultural markets where cooperative farming structures delay technology procurement.
- AI governance arbitrage:Automated feature extraction from geospatial imagery is attracting escalating scrutiny from data protection and national security regulators, creating first-mover advantage for compliant workflow architects.
- Life sciences extension:Environmental sample analysis capabilities developed for pharmaceutical diagnostics are transferring to field-deployable contaminant detection with minimal reconfiguration.
Industry Challenges
- Geospatial data scientist scarcity:The intersection of remote sensing expertise and agricultural domain knowledge remains thinly staffed across service provider organizations.
- EPA certification timelines:Site remediation standards mandating validated field analytical methods extend instrument qualification periods and compress deployment windows.
- Legacy GIS integration complexity:Municipal spatial data infrastructure built over decades resists API-based connectivity with modern predictive modeling platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface and Field Analytics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Sensor Fusion, LiDAR, Satellite Imagery, GIS Application: Agriculture, Environmental Monitoring, Urban Planning, Disaster Management End User: Government Agencies, Agriculture Firms, Research Institutions, Utility Companies Solution: Data Analytics, Predictive Modeling, Geographic Visualization, Real-time Monitoring |
| Companies Covered | Danaher Corporation, Bruker Corporation, Carl Zeiss AG, JEOL Ltd., Nikon Corporation, Olympus Corporation, Shimadzu Corporation, Thermo Fisher Scientific, Inc., Waters Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface and Field Analytics Market Emerging Trajectories
Hyperspectral imaging systems are migrating from research-grade installations to operational agricultural fleets, compressing the data-to-decision pipeline from weeks to hours. This acceleration is forcing adjacent technology categories to reconfigure around real-time throughput rather than batch processing.
Hyperspectral sensors capture reflectance signatures across hundreds of narrow wavelength bands, enabling sub-pixel material identification for crop disease and soil mineralogy. Large-scale farming cooperatives in the US Corn Belt are retrofitting existing aerial platforms with these payloads at accelerating pace. The technology is converging with edge-computing architectures that process raw spectral data aboard the acquisition platform, eliminating ground-station bottlenecks.
EPA enforcement of site remediation standards is tightening instrument certification pathways and service provider qualification requirements. Field analytical methods must now demonstrate validated performance against reference laboratory procedures before regulatory acceptance. Environmental consulting firms serving Superfund and RCRA corrective action sites are restructuring procurement to favor pre-certified device portfolios.
Subscription-based analytics access is displacing perpetual license models across municipal and utility buyer segments. GIS software vendors are unbundling core platform access from premium predictive modeling modules, forcing channel partners to rebuild revenue around implementation and training services. This shift is most visible in German industrial land management, where CSRD compliance deadlines are compressing procurement cycles and favoring operational expenditure treatment.
Surface and Field Analytics Market Segmentation
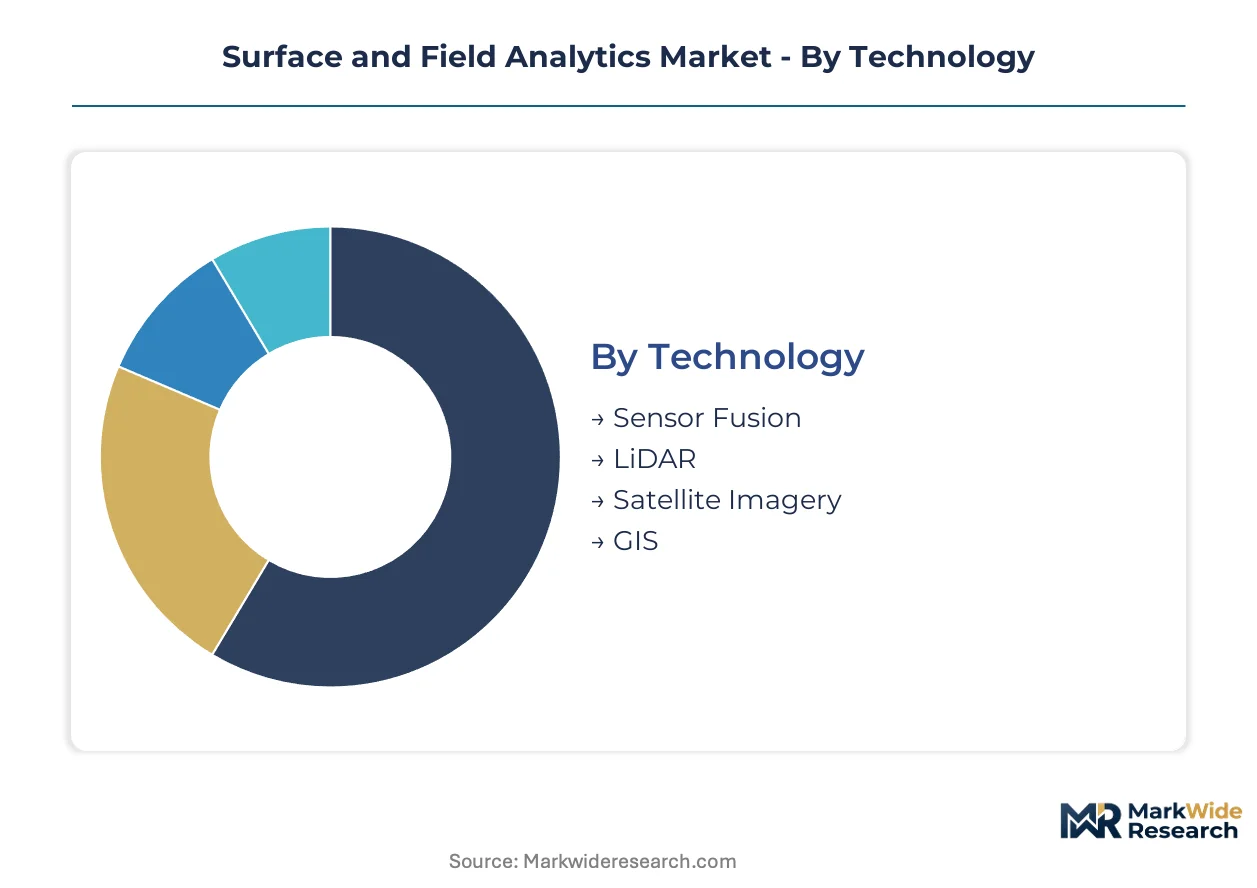
Surface and field analytics vendors configure product portfolios around distinct technology stacks and buyer workflows. Segment boundaries are blurring as platform providers bundle sensing hardware with predictive software, forcing buyers to evaluate total cost of ownership rather than component pricing.
Technology:
Supply concentration in geospatial instrument cores favors vendors with captive fabrication relationships or long-term foundry allocations.
- GIS:Spatial data infrastructure software manages layer-based georeferenced datasets for municipal utilities and industrial asset operators. German land managers under CSRD deadlines are consolidating procurement around platforms with pre-certified metadata handling. Today's leader: GIS. Tomorrow's challenger: Satellite Imagery.
- Satellite Imagery:Commercial constellation operators deliver sub-meter resolution with sub-daily revisit frequency for agricultural stress monitoring. US Corn Belt cooperatives are retrofitting decision workflows around near-real-time spectral feeds. This segment is expanding most quickly as launch economics improve and spectral band proliferation enables material identification.
- LiDAR:Pulsed laser ranging generates dense point clouds for topographic mapping and infrastructure deformation tracking.
- Sensor Fusion:Multi-modal integration of optical, thermal, and acoustic inputs enables anomaly detection in complex terrain.
Component sourcing strategies now separate vendors with assured supply from those facing allocation delays.
Application:
Cost tier differentiation separates turnkey subscription offerings from capital-intensive bespoke deployments.
- Agriculture:Precision farming operations deploy nutrient mapping and yield prediction across variable-rate input management. US Corn Belt operations are compressing sensor cycles from annual to sub-seasonal intervals, demanding field-hardened edge computing. This application commands the largest addressable spend.
- Environmental Monitoring:Contaminant detection and remediation verification follows EPA-mandated field analytical protocols with extended certification timelines. German mining remediation in the Ruhr corridor concentrates demand for validated measurement systems.
- Urban Planning:Municipal zoning and infrastructure lifecycle management leverages decades of accumulated spatial data assets.
- Disaster Management:Rapid damage assessment and resource routing depends on low-latency acquisition and automated feature extraction.
Subscription penetration is deepest in agriculture; perpetual licenses persist in municipal planning.
End User:
Customer type determines procurement cycle length and technical support intensity.
- Government Agencies:Federal and state environmental departments enforce regulatory standards that shape instrument certification pathways. EPA Superfund site managers require pre-validated field methods that compress vendor qualification periods.
- Agriculture Firms:Large-scale cooperatives and input suppliers purchase predictive modeling services as operational expenditures rather than capital investments.
- Research Institutions:Academic and government laboratories drive hyperspectral imaging adoption from research-grade to operational deployment.
- Utility Companies:Electricity and water infrastructure operators monitor corridor vegetation and asset condition across distributed networks.
Public sector procurement dominates volume; private agriculture firms drive margin expansion.
Solution:
Margin concentration pools in proprietary algorithm development and client-specific training data architectures.
- Predictive Modeling:Machine learning workflows trained on proprietary agricultural or environmental datasets generate yield forecasts and risk assessments. These solutions command premium pricing due to data network effects and domain-specific feature engineering.
- Data Analytics:Statistical processing and pattern recognition tools transform raw sensor feeds into structured intelligence for operational decisions.
- Geographic Visualization:Map-based interfaces and dashboard tools remain essential for stakeholder communication but face commoditization pressure.
- Real-time Monitoring:Edge-processed alerts and automated anomaly detection enable immediate response workflows for irrigation scheduling or contamination events.
Predictive capabilities separate premium vendors; visualization layers standardize.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial Ruhr corridor concentrates mining remediation demand while the United States Corn Belt drives precision agriculture adoption, creating divergent regional growth profiles across the surface and field analytics market.
United States
EPA Superfund site managers enforce validated field analytical methods for contamination detection, compressing vendor qualification timelines. The agency's RCRA corrective action protocols mandate instrument certification pathways that favor pre-certified device portfolios. Texas Gulf Coast petrochemical clusters and Arizona copper mining districts deploy multi-modal surface analytics for environmental compliance monitoring.
Germany
CSRD disclosure rules compel corporate land managers to deploy verified field measurement systems for carbon stock verification. ESA's Copernicus program and the EU's INSPIRE directive standardize data interoperability across member states. The Ruhr corridor concentrates demand where mining remediation obligations intersect with infrastructure monitoring requirements.
China
Dual carbon goals accelerate environmental monitoring deployment across industrial zones and agricultural provinces. The Ministry of Ecology and Environment enforces site remediation standards that shape instrument procurement specifications. Yangtze River Delta manufacturing hubs and Shanxi coal mining regions invest in surface analytics for regulatory compliance and resource optimization.
Japan
METI industrial policy supports precision agriculture technology adoption in Hokkaido grain belts and Kyushu vegetable production zones. JIS standards govern spectral sensor calibration protocols for agricultural and environmental applications. Osaka-Kobe industrial corridors deploy field analytics for infrastructure lifecycle management and disaster preparedness.
India
CEA grid modernization programs drive vegetation monitoring across electricity transmission corridors in Maharashtra and Gujarat. BIS certification requirements condition market access for imported geospatial instrumentation. Punjab and Haryana agricultural belts experiment with yield prediction platforms amid cooperative farming structure transitions.
Surface and Field Analytics Market Vendor Landscape
German and Japanese producers anchor one tier in precision optical instrumentation; American conglomerates hold diversified positions across life sciences and environmental diagnostics. The vendor base separates into three strategic archetypes: diversified technology conglomerates with captive fabrication relationships, specialized microscopy and spectroscopy houses with deep R&D benches, and emerging platform vendors bundling predictive software with sensing hardware. Competitive positioning hinges on M&A activity targeting algorithm development capabilities and strategic partnerships securing foundry allocations for geospatial instrument cores.
Within the diversified conglomerate tier, Danaher Corporation exemplifies vertical life sciences integration extending diagnostics expertise into environmental sample analysis, while Thermo Fisher Scientific occupies a position leveraging mass spectrometry heritage for premium surface chemistry detection workflows. Bruker Corporation sits within the specialized instrumentation archetype, sustaining competitive intensity in atomic force microscopy for semiconductor metrology applications. These three anchors represent distinct strategic postures: conglomerate platform breadth, analytical instrument depth, and precision measurement specialization.
| Leading Market Players |
|---|
| Danaher Corporation |
| Bruker Corporation |
| Carl Zeiss AG |
| JEOL Ltd. |
| Nikon Corporation |
| Olympus Corporation |
| Shimadzu Corporation |
| Thermo Fisher Scientific, Inc. |
| Waters Corporation |
| Others |
Supply Flow & Price Mechanics
Captive fabrication relationships in North American foundries anchor supply security for geospatial instrument cores while simultaneously enabling premium pricing power for vendors with assured allocations. This integration pattern separates vendors capable of serving EPA-mandated certification timelines from competitors facing allocation delays and price volatility.
Pricing Analysis
Capacity additions in domestic North American foundries are reshaping price floors for multi-spectral sensor arrays. Three-tier pricing structure across premium, standard, and economy levels separates metrology-grade optical substrates from field-deployable agricultural sensors. Price differentiation hinges on EPA certification tier and volume procurement scale. Cost compression in standard-tier instrumentation intensifies because rare earth element sourcing constraints propagate through precision optical substrate supply. Municipal utility buyers exhibit highest price sensitivity; semiconductor metrology clients demonstrate lowest.
Supply Chain Analysis
Dual-sourcing qualification requirements from German industrial land managers and US EPA Superfund site operators mandate multi-supplier relationships for geospatial instrument cores. Production concentrates in the United States, Germany, and Japan for precision optical components and atomic force microscopy substrates. Raw material dependencies include rare earth elements, precision optical glass, and semiconductor-grade silicon wafers. Single-source vulnerability in specialized multi-spectral array fabrication creates supply risk. Distribution runs through direct OEM relationships for large agriculture cooperatives and environmental consulting firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in predictive modeling solutions where proprietary algorithm development and client-specific training data architectures command premium positioning. Cost-down drivers in edge-computing hardware deployment compress data-to-decision timelines and reduce service delivery overhead.
For Market Incumbents: Deploy backward integration into geospatial instrument core fabrication to secure foundry allocations against emerging platform vendors. Consolidate around pre-certified device portfolios that compress EPA qualification timelines for Superfund site service providers. Channel control through exclusive distribution agreements with German industrial land managers under CSRD deadlines defends margin position against subscription-based analytics entrants. For New Entrants and Emerging Players: Capture underpenetrated Eastern European agricultural markets where cooperative farming structures delay technology procurement and yield prediction platforms remain nascent. White-space exists in AI governance-compliant workflow architectures for automated feature extraction from geospatial imagery. Go-to-market through municipal utility subscription bundling bypasses capital expenditure approval cycles that favor incumbent GIS vendors. For Investors and Strategic Acquirers: Roll-up economics work for specialized microscopy and spectroscopy houses with deep R&D benches because algorithm development capabilities fragment across academic spinouts and regional service providers. Long-term viability favors acquisition targets with captive training data archives and domain-specific feature engineering expertise. Watch EPA enforcement intensity for site remediation standards as the inflection indicator for instrument certification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Algorithm development capabilities from agricultural analytics startups transfer proprietary training data archives. |
| Platform Integration | Edge-computing architectures aboard aerial platforms eliminate ground-station processing bottlenecks for US Corn Belt cooperatives. |
| Geographic Expansion | Eastern European agricultural markets present white-space for yield prediction platforms amid cooperative structure transitions. |
| Strategic Partnership | Foundry allocation agreements with domestic North American sensor fabricators secure supply for EPA-certified instrument production. |
| Product Launch | Hyperspectral imaging payloads for operational agricultural fleets compress data-to-decision pipelines from weeks to hours. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with precision agriculture operations managers, EPA Superfund site remediation directors, German industrial land management executives, geospatial data scientists, and municipal utility GIS administrators with secondary validation. Secondary sources included EPA enforcement action databases, ESA Copernicus program technical specifications, EU CSRD disclosure guidance documents, SEC filings from diversified instrumentation conglomerates, and agricultural cooperative technology procurement records. Bottom-up sensor deployment estimates and top-down market sizing triangulated across technology and application segments.
Segment-weighting approaches distributed value across GIS installed base depreciation, satellite imagery constellation capacity expansion, and predictive modeling solution margin pools. Modeled dimensions spanned technology modality, application vertical, end-user procurement archetype, and solution type complexity. CAGRs derived from regression analysis against historical precision agriculture technology adoption curves and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated CSRD disclosure timeline compression and EPA instrument certification pathway extensions.
Regulatory enforcement intensity, rare earth supply disruption, and AI governance framework evolution are the dominant revision risks for surface and field analytics demand projections. Forecasts reflect documented assumptions regarding satellite revisit frequency improvements and edge-computing cost trajectories. Deviation in EPA Superfund site remediation funding allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Automated Microscopy Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Global Raman Spectroscopy Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Handheld XRF Analyzers Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Portable Particle Counter Market
Analytical Instruments
Bolometer Market
Analytical Instruments
Modular Instruments Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Middle East and Africa Dissolved Gas Analyzer Market