
 Single Cell Analysis System Market | 2026-2036
Single Cell Analysis System Market Size, Share, and Industry Trends Forecast 2026-2036
Single Cell Analysis System Market Analytics
Leasing and asset-light procurement models are reshaping competitive access in the single cell analysis system space. 10x Genomics leverages its droplet microfluidics ecosystem to anchor recurring consumable revenue streams. Thermo Fisher Scientific sustains broad channel control through integrated reagent-instrument workflows. Illumina competes by extending sequencing-readout partnerships that lower customer switching costs.
Single cell analysis systems isolate, manipulate, and characterize individual cells using microfluidic channels, fluorescent labels, or mass spectrometry readouts with resolution down to picoliter volumes. These platforms enable transcriptomic, proteomic, and metabolic profiling at cellular heterogeneity levels impossible with bulk methods. Microfluidics dominates instrument placements due to lower per-sample cost and scalability in high-throughput screening. Single-cell sequencing captures the fastest expansion as CRISPR-compatible multi-omic workflows migrate from research institutions toward pharmaceutical validation labs. Flow cytometry occupies a mature margin pool sustained by clinical diagnostics demand and established service infrastructure.
FDA oversight of laboratory-developed tests and cell therapy manufacturing standards shapes instrument validation protocols for clinical laboratories. The EPA and OSHA frameworks govern reagent handling and laser safety classifications in research and production facilities. Stakeholders must monitor how evolving ISO 13485 quality management requirements affect the transition from research-use-only to in-vitro diagnostic labeling.
Market Dynamics
Pharmaceutical validation labs are pulling multi-omic workflows from academic settings into regulated environments, forcing instrument vendors to reengineer hardware for FDA-compliant quality management systems.
Growth Catalysts
- CRISPR-compatible multi-omic workflows:Pharmaceutical validation labs in the United States are standardizing these platforms for target identification and safety pharmacology. This migration from research-only to regulated settings expands addressable instrument placements.
- ISO 13485 quality management requirements:The transition path from research-use-only to in-vitro diagnostic labeling is accelerating as laboratories prepare for companion diagnostic partnerships. Equipment manufacturers are pre-validating systems to capture this certification-driven demand.
- Biotech clusters in Boston and San Diego:Academic medical centers in these geographies are anchoring regional demand for high-throughput single-cell sequencing platforms. Proximity to venture capital and CRO infrastructure concentrates procurement velocity.
Market Restraints
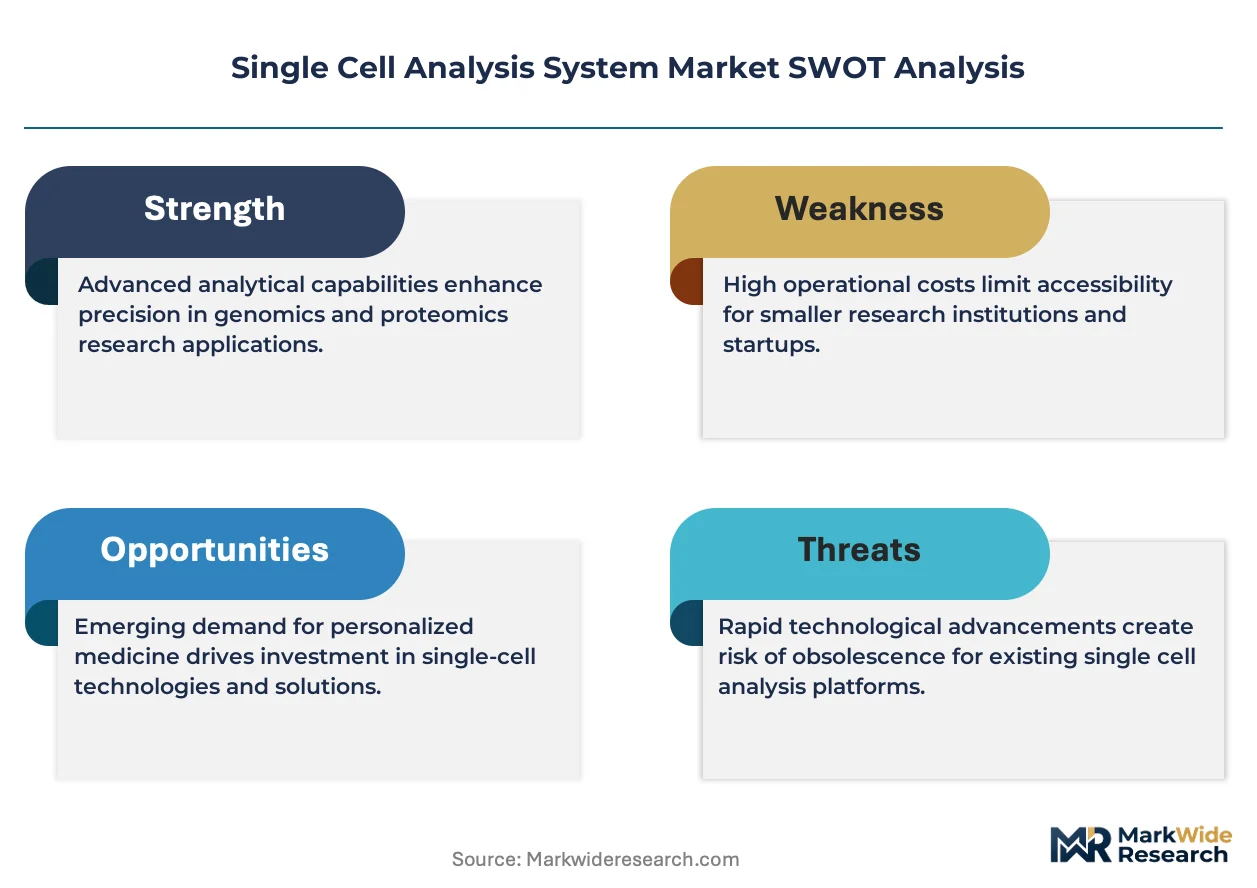
- Consumable cost concentration:Droplet microfluidics cartridges and proprietary reagent kits lock users into recurring expenditure structures that constrain budget flexibility for mid-sized research institutions.
- Laser safety classifications under OSHA frameworks:Flow cytometry and mass spectrometry readout systems trigger facility modification requirements that extend installation timelines and inflate total cost of ownership.
- Technical limitation in low-input samples:Primary tissue and fixed archival specimens present nucleic acid degradation challenges that bulk methods handle more reliably, restricting single-cell adoption in clinical pathology workflows.
Strategic Opportunities
- Cell therapy manufacturing standards:FDA guidance on laboratory-developed tests is creating validation service opportunities for instrument vendors willing to document reproducibility across GMP-compliant production environments.
- Spatial transcriptomics convergence:Integration of single-cell isolation with in-situ imaging is opening tissue microenvironment applications that pure suspension methods cannot address. This technology pair is attracting oncology and immuno-oncology research funding.
- Leasing and asset-light procurement models:Contract research organizations are replacing capital purchases with operational expenditure structures that bundle instrumentation, training, and technical support into multi-year service agreements.
Industry Challenges
- Bioinformatics pipeline complexity:Single-cell datasets require specialized computational biology expertise that outstrips supply in contract research and mid-tier pharmaceutical settings. Training timelines extend deployment cycles and inflate service costs.
- Reagent cold chain integrity:Temperature-sensitive enzymes and barcoded oligonucleotides demand logistics infrastructure that smaller academic sites struggle to maintain, creating fulfillment friction and sample quality variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Cell Analysis System Market |
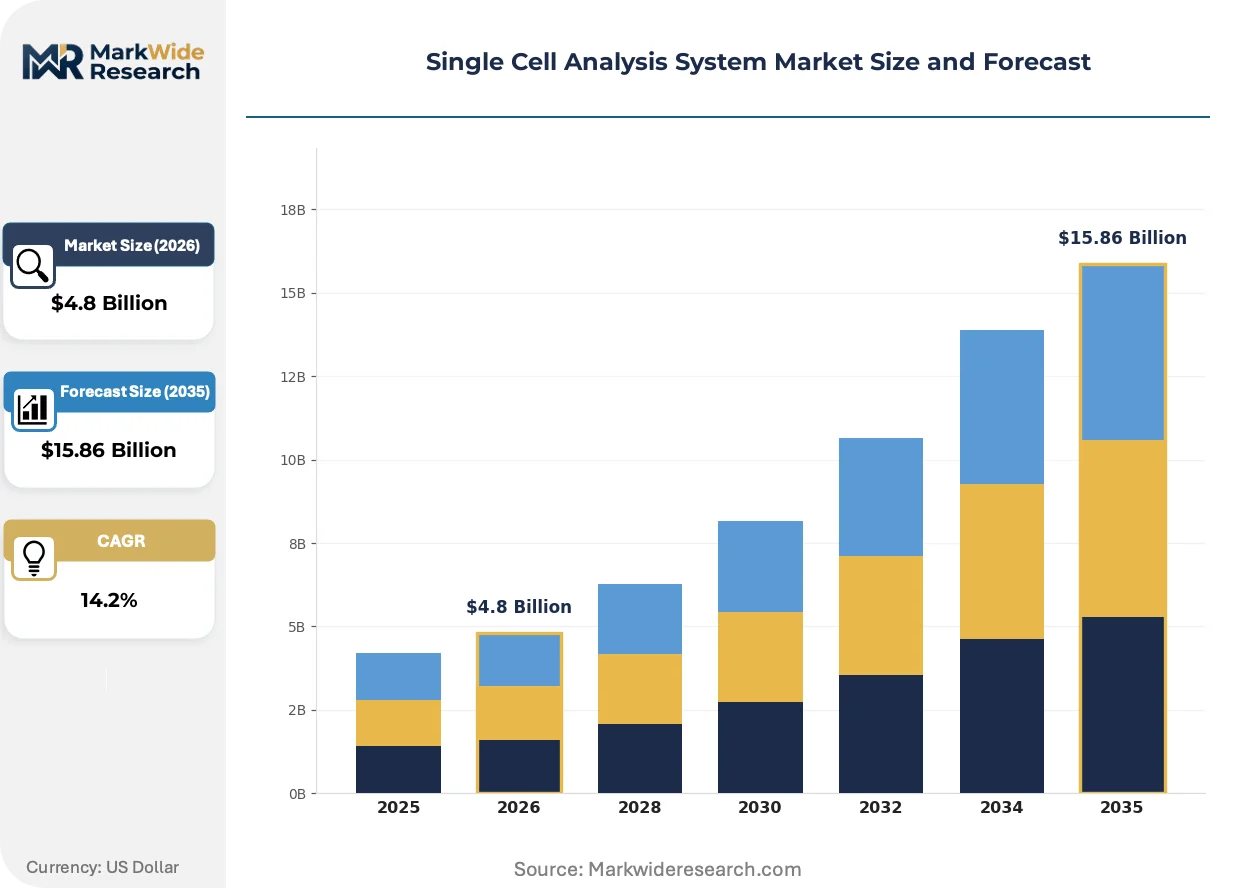
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidics, Cell Sorters, Imaging Systems, Analyzers Application: Genomics, Drug Discovery, Proteomics, Diagnostics End User: Research Institutions, Biotechnology Companies, Pharmaceutical Companies, Clinical Laboratories Technology: Single-Cell Sequencing, Flow Cytometry, Mass Cytometry, Imaging Cytometry |
| Companies Covered | Thermo Fisher Scientific, 10x Genomics, Illumina, Becton, Dickinson and Company, Bio-Rad Laboratories, QIAGEN, Standard BioTools, Agilent Technologies, Parse Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Cell Analysis System Market Evolving Landscape
Workflow automation and regulatory pre-certification are converging to compress the gap between research discovery and clinical deployment. Instrument vendors are racing to embed quality documentation into hardware architecture.
Machine-learning-assisted cell classification is digitizing the interpretation bottleneck that has historically constrained single-cell data throughput. Pharmaceutical bioinformatics teams are deploying these tools to accelerate target validation timelines. The compression of manual analysis steps is digitizing the economics of large-scale screening campaigns.
EMA's evolving position on cell-based therapy manufacturing standards is tightening documentation requirements for equipment used in ATMP production. European academic medical centers are now demanding ISO 13485-aligned quality systems as a procurement prerequisite. This regulatory friction is favoring vendors with established in-vitro diagnostic regulatory track records over research-focused competitors.
Service unbundling is fragmenting traditional instrument-sales relationships in the United States. Biotech startups are purchasing hardware through reagent-rental agreements that shift capital risk to vendors. This consumption-pattern shift is visible most acutely in Boston and San Francisco Bay Area clusters where venture-funded companies prioritize operational flexibility over asset ownership.
Single Cell Analysis System Market Segmentation
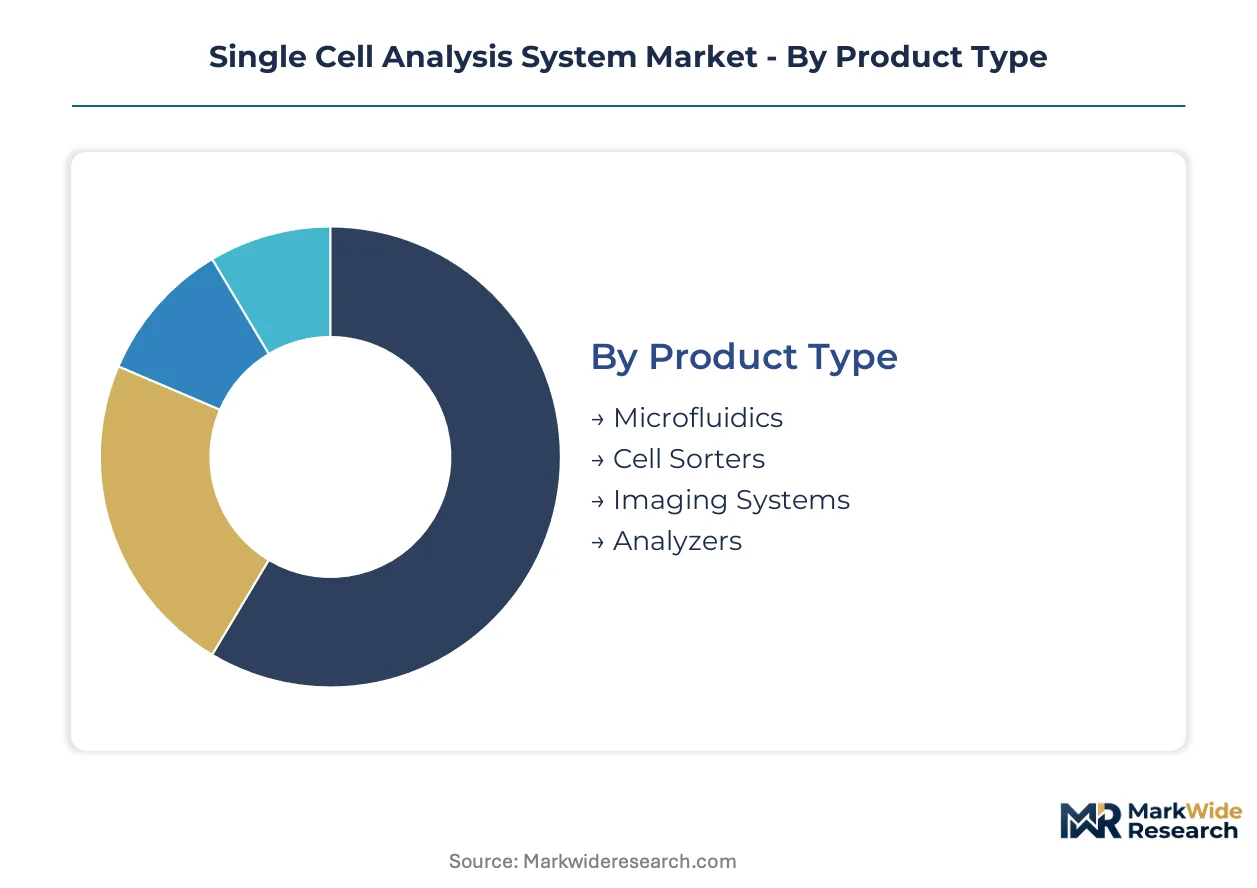
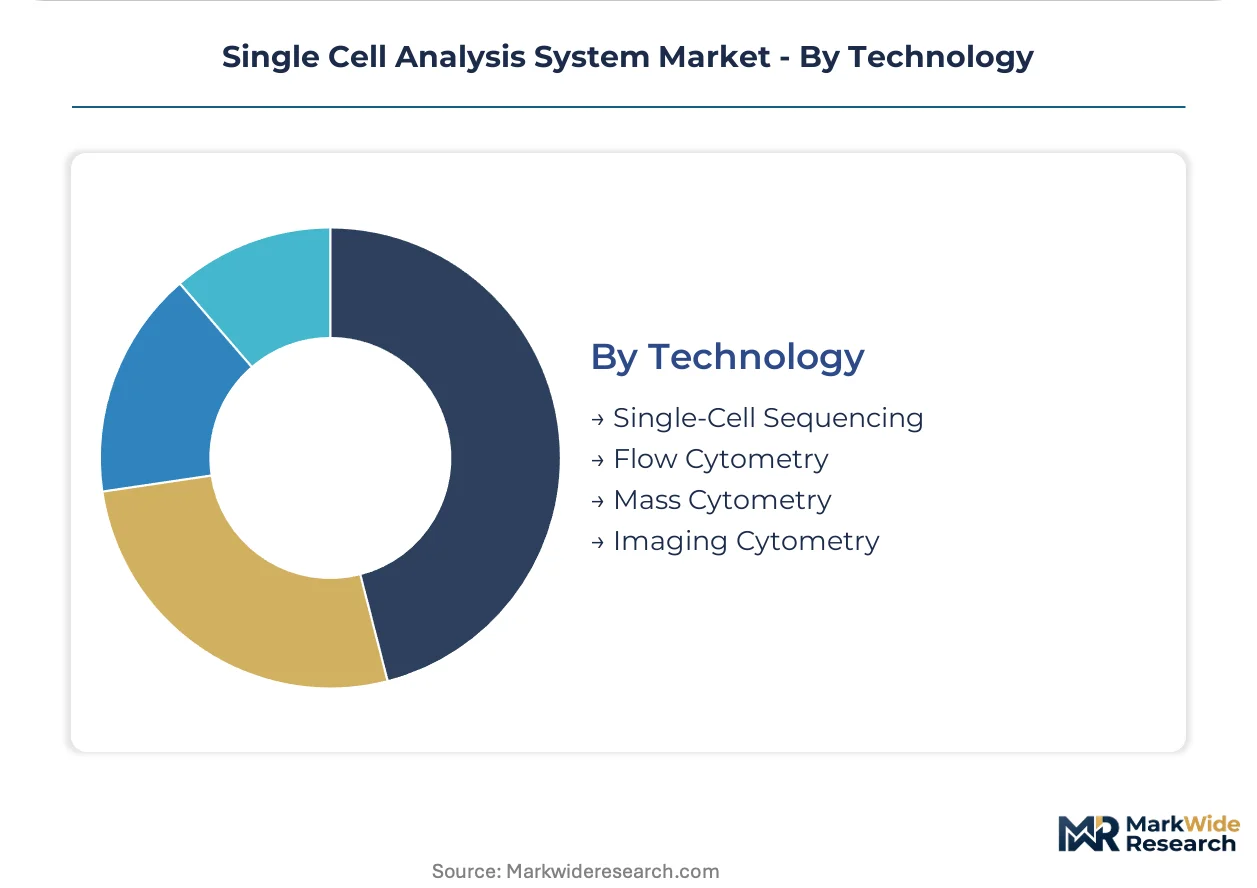
Technology choice in single cell analysis systems determines consumable economics, regulatory pathway, and bioinformatics burden. Procurement decisions across product type, application, end user, and technology layers create distinct margin pools and switching cost profiles.
Product Type:
Cost tier stratification separates capital-intensive platforms from reagent-dependent systems with divergent total cost of ownership structures.
- Microfluidics:Droplet-based isolation platforms partition individual cells into picoliter droplets for parallel processing. Pharmaceutical companies in the United States anchor demand for 10x Genomics and comparable systems where consumable lock-in generates recurring revenue streams.
- Cell Sorters:Fluorescence-activated and magnetic-activated separation instruments enable live cell recovery for downstream culture. Academic medical centers in Boston and San Diego biotech clusters drive placements for stem cell and immunology workflows.
- Imaging Systems:High-content microscopy platforms capture morphological and spatial data at single-cell resolution.
- Analyzers:Integrated readout instruments combine detection with automated quantification for standardized reporting.
Microfluidics commands the established base. The steepest expansion runs through Cell Sorters as cell therapy manufacturing scales.
Application:
Customer type differentiation separates exploratory research budgets from validated pharmaceutical development programs with distinct procurement authority and timeline pressures.
- Genomics:Transcriptomic profiling at single-cell resolution enables cell atlas construction and developmental trajectory mapping. CRISPR-compatible multi-omic workflows are migrating from research institutions toward FDA-compliant pharmaceutical validation labs.
- Drug Discovery:Target identification and safety pharmacology applications require reproducible platform performance under GMP-adjacent conditions. ISO 13485 pre-certification is becoming a procurement prerequisite for companion diagnostic partnerships.
- Proteomics:Mass spectrometry and antibody-based protein quantification at single-cell resolution.
- Diagnostics:Clinical-grade single-cell analysis for hematological malignancy and immune monitoring.
Drug Discovery commands the established base. The steepest expansion runs through Genomics as reference atlases mature into therapeutic hypotheses.
End User:
Volume concentration and margin tolerance vary sharply across institutional types with different funding mechanisms and regulatory exposure.
- Research Institutions:Academic laboratories prioritize publication-grade data with flexible capital budgets. Leasing and reagent-rental agreements are displacing outright purchases as NIH funding cycles tighten.
- Biotechnology Companies:Venture-funded startups in San Francisco Bay Area and Boston clusters demand operational flexibility. Asset-light procurement models bundle instrumentation, training, and technical support into multi-year service agreements.
- Pharmaceutical Companies:Large-cap drug developers with validated quality management systems.
- Clinical Laboratories:Hospital-based and reference labs facing FDA oversight of laboratory-developed tests.
Research Institutions command the established base. The steepest expansion runs through Biotechnology Companies as venture deployment concentrates in spatial transcriptomics.
Technology:
Maturity and regulatory clearance status create divergent competitive moats and substitution risks across detection modalities.
- Single-Cell Sequencing:NGS-based transcriptomic and genomic readouts with CRISPR compatibility for perturbation studies. Multi-omic workflows are expanding fastest as pharmaceutical validation labs standardize platforms for target identification.
- Flow Cytometry:Established laser-based fluorescence detection with mature clinical diagnostics infrastructure. OSHA laser safety classifications and established service networks sustain margin pools despite slower innovation velocity.
- Mass Cytometry:Heavy metal isotope detection enabling 40+ parameter protein profiling without spectral overlap.
- Imaging Cytometry:Morphological and spatial data capture with in-situ context preservation.
Flow Cytometry commands the established base. The steepest expansion runs through Single-Cell Sequencing as readout costs decline and multi-omic integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on cell-based therapies and companion diagnostics accelerates instrument validation requirements in the United States. EMA's evolving ATMP manufacturing standards tighten documentation demands across European academic medical centers. Japan's PMDA and China's NMPA are converging on ISO-aligned quality systems for clinical-grade single-cell platforms.
United States
Pharmaceutical validation labs in Boston and San Diego biotech clusters anchor regional procurement velocity for CRISPR-compatible multi-omic workflows. FDA oversight of laboratory-developed tests shapes equipment validation protocols for clinical laboratories transitioning toward companion diagnostic partnerships. Academic medical centers in these geographies concentrate demand for high-throughput single-cell sequencing platforms.
Germany
EMA-aligned academic medical centers in Heidelberg and Munich are demanding ISO 13485-certified quality systems as procurement prerequisites. The country's federal framework for cell therapy manufacturing standards accelerates validation service opportunities for instrument vendors. Bavarian biotech clusters around Munich concentrate pharmaceutical development programs requiring GMP-adjacent platform performance.
China
NMPA regulatory convergence on international quality standards drives domestic pharmaceutical labs toward validated single-cell platforms. The country's dual carbon goals intersect with reagent cold chain infrastructure investments in Shanghai and Beijing biotech parks. Yangtze River Delta clusters concentrate CRISPR research institutions migrating multi-omic workflows toward regulated environments.
Japan
METI-supported precision medicine initiatives expand academic procurement of spatial transcriptomics platforms in Tokyo and Osaka medical centers. PMDA guidance on regenerative medicine products shapes instrument validation requirements for cell therapy manufacturing. Kanto region biotech infrastructure concentrates demand for automated single-cell isolation systems.
United Kingdom
London and Cambridge academic medical centers drive placements for stem cell and immunology workflows requiring live cell recovery capabilities. The Medicines and Healthcare products Regulatory Agency framework on ATMP production standards influences equipment documentation requirements. Southeast England biotech clusters concentrate venture-funded demand for asset-light procurement models.
Single Cell Analysis System Market Competitive Landscape
On the supply side, the industry is consolidating around integrated reagent-instrument workflows and droplet microfluidics ecosystems that lock users into recurring consumable revenue streams. Three strategic archetypes dominate: platform-integrated conglomerates with broad channel control, microfluidics specialists anchoring consumable-dependent revenue models, and sequencing-readout partners lowering customer switching costs through collaborative data pipelines. Competitive moves concentrate on strategic partnerships for multi-omic workflow integration and pre-certification investments for ISO 13485-aligned quality management systems.
Within the platform-integrated tier, Thermo Fisher Scientific exemplifies supply-side consolidation through captive reagent-instrument bundles. 10x Genomics occupies the microfluidics specialist position with droplet-based isolation platforms that generate recurring cartridge revenue. Illumina represents the sequencing-readout partnership archetype, extending collaborative pipelines that reduce migration friction for pharmaceutical validation labs.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| 10x Genomics |
| Illumina |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories |
| QIAGEN |
| Standard BioTools |
| Agilent Technologies |
| Parse Biosciences |
| Others |
Value Network & Pricing Analysis
Boston and San Diego biotech clusters anchor North American instrument manufacturing capacity, concentrating supply-side leverage that filters downstream into reagent pricing power and platform bundling terms for pharmaceutical buyers.
Pricing Analysis
Certification level (ISO 13485/FDA-grade) creates the primary spread between research-use-only and clinical-grade systems. Three-tier pricing structure across premium, standard, and economy levels segments by validation depth and consumable lock-in intensity. Price differentiation hinges on after-sales service bundling and proprietary cartridge ecosystems. Mid-sized academic institutions exhibit highest price sensitivity due to NIH funding compression, while large-cap pharmaceutical companies absorb premium tiers for companion diagnostic readiness.
Supply Chain Analysis
US export controls on droplet microfluidics and laser subassemblies constrain cross-border flows of precision instrumentation. Manufacturing concentrates in the United States, Germany, and China for microfluidic chips, optical components, and barcoded reagent kits. Raw material dependencies include photoresists, rare-earth laser crystals, and temperature-sensitive enzymes. Single-source vulnerability runs through specialized MEMS foundries serving droplet generator production. Distribution runs through direct sales forces for pharmaceutical accounts and academic distributors for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single cell analysis systems sit in early-cycle expansion as CRISPR-compatible multi-omic workflows migrate from academic discovery toward FDA-compliant pharmaceutical validation, opening instrument placement velocity not yet captured by installed-base saturation metrics.
For Market Incumbents: Entrench consumable-dependent revenue streams by deepening captive supply of proprietary droplet cartridges and pre-validated reagent kits. Accelerate ISO 13485 certification pipelines to capture companion diagnostic partnership demand before research-focused competitors close the gap. Defend against emerging microfluidics specialists by embedding machine-learning-assisted cell classification into bundled service agreements that raise switching costs. For New Entrants and Emerging Players: Mid-market contract research organizations in European biotech clusters represent the most penetrable entry point, as these buyers prioritize operational flexibility over brand legacy and accept asset-light procurement models. Spatial transcriptomics workflows in immuno-oncology research present application-specific white space where pure suspension methods fail. A reagent-rental go-to-market structure shifts capital risk to vendors while capturing recurring revenue through technical support bundling. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because droplet microfluidics ecosystems generate durable consumable lock-in and regulatory pre-certification creates moats against commoditization. Acquisition targets should display ISO 13485-aligned quality systems and established pharmaceutical validation lab relationships. The signal to watch is FDA guidance tightening on laboratory-developed tests, which would accelerate replacement demand for research-grade instrumentation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | ISO 13485 alignment opens companion diagnostic partnerships with FDA-registered pharmaceutical labs. |
| Consumable Ecosystem Expansion | Proprietary droplet cartridges generate recurring revenue streams that dilute instrument margin pressure. |
| Machine-Learning Pipeline Integration | Automated cell classification compresses bioinformatics bottlenecks that constrain large-scale screening economics. |
| Asset-Light Procurement Structuring | Reagent-rental agreements capture venture-funded biotech demand in Boston and San Francisco Bay Area clusters. |
| Spatial Transcriptomics Convergence | In-situ imaging integration opens tissue microenvironment applications inaccessible to suspension methods. |
Research Methodology
The analysis maps microfluidics platforms, cell sorters, imaging systems, and analyzers, each validated through instrument vendor executives, pharmaceutical bioinformatics directors, academic core facility managers, and clinical laboratory quality officers. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA ATMP guidance documents, ISO certification registries, and NIH RePORTER funding databases. Bottom-up instrument placement counts triangulated against top-down pharmaceutical R&D expenditure allocations.
Assumptions held fixed include regulatory pathway convergence on ISO 13485 standards and continued CRISPR workflow adoption across pharmaceutical validation labs. Variables included geographic funding cycle volatility and reagent cold chain infrastructure development rates. The analytical framework modeled technology type, application area, end-user institution class, and regional regulatory cluster across the projection horizon. CAGRs derived from instrument placement velocity curves and consumable attach-rate trajectories. Forecast inputs incorporated multi-omic workflow standardization timelines and cell therapy manufacturing scale-up rates.
Macroeconomic conditions sit as an overlay; deviation in NIH funding appropriations, venture deployment into biotech startups, or cross-border technology transfer restrictions would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Material shifts in FDA guidance on laboratory-developed tests or EMA ATMP manufacturing standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Laser-Based Gas Analyzers Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
Microfluidic Modulation Spectroscopy Market
Analytical Instruments
Process Analytical Instrumentation Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Dioxin Analyzer Market
Analytical Instruments
Europe Surface Analysis Market
Analytical Instruments
High-Sensitivity Luminometers Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Global Mass Spectrometry Market
Analytical Instruments
Automated Microscopy Market
Analytical Instruments
Analytical Ultracentrifuge Systems Market
Analytical Instruments
Surface Plasmon Resonance Market