
 High-End Bicycle Market | 2026-2036
High-End Bicycle Market Size, Share, and Industry Trends Forecast 2026-2036
High-End Bicycle Market Analysis
Carbon fiber monocoque construction is collapsing the price barrier between factory-team replicas and consumer-grade road bikes. Specialized leverages in-house composites R&D to control layup quality from Taiwan facilities to retail floors. Trek anchors North American premium distribution through its dealer-certified fit-studio network. Pinarello dominates European grand-tour visibility and sustains pricing power via limited Dogma production runs.
A high-end bicycle denotes a performance-oriented machine engineered to sub-kilogram frame weights, typically employing Toray T1100G carbon pre-preg, hydroformed aluminum, or 3Al-2.5V titanium tubing, with primary purpose spanning elite competition, gran fondo endurance events, and premium urban mobility. Road bikes and electric bikes capture divergent growth vectors, with road platforms concentrating margin in sub-seven-kilogram disc-brake builds and e-bikes expanding through 250W mid-motor integration that extends rider range thresholds. Carbon fiber frame material leads value density while titanium occupies a narrowing artisan niche serving custom-fit touring and competitive segments.
FDA oversight of recovery and biometric wearables paired with cycling apps creates adjacent compliance burdens for integrated health-tracking components. ECHA REACH restrictions on resin systems and volatile compounds constrain European manufacturing chemistry choices and elevate supplier qualification costs. ISO 4210 and CEN safety standards govern frame fatigue testing protocols that determine market access eligibility. Stakeholders must monitor evolving battery certification requirements for e-bike powertrains as regulatory scope widens beyond traditional mechanical safety domains.
Market Dynamics
Carbon fiber monocoque construction is collapsing the price barrier between factory-team replicas and consumer-grade road bikes, compressing margin structures across Taiwanese contract manufacturers and European heritage brands alike.
Growth Catalysts
- EU Green Deal bike-to-work subsidies:Germany, France, and the Netherlands channel commuter spending toward premium frames through tax-advantaged employer schemes.
- Gran fondo endurance events:Amateur racing programs across Italy and Spain drive replacement cycles for sub-seven-kilogram disc-brake builds.
- Toray T1100G carbon pre-preg:Advanced composite layup protocols enable sub-kilogram frame weights at scaled production volumes.
Market Restraints
- Taiwanese frame manufacturing concentration:Over-reliance on Taichung-area composites facilities creates geopolitical and logistics vulnerability.
- ECHA REACH resin restrictions:Volatile compound limits constrain European manufacturing chemistry choices and elevate supplier qualification costs.
- 250W mid-motor technical ceiling:E-bike powertrain integration hits thermal dissipation limits that throttle range extension ambitions.
Strategic Opportunities
- Urban mobility corridors:Copenhagen and Amsterdam infrastructure investments position premium urban bikes for daily commuter capture.
- Biometric wearable convergence:Integrated health-tracking components create adjacent revenue streams beyond hardware sales.
- Direct-to-consumer fit-studio networks:Dealer-certified measurement protocols bypass traditional retail markups while preserving margin.
Industry Challenges
- ISO 4210 fatigue testing certification:Extended validation timelines delay new frame platform launches by 8-14 months.
- Composites layup technician scarcity:Specialized carbon fiber craftsmanship commands wage premiums that compress assembly margins.
- Battery certification scope expansion:E-bike powertrain safety standards now require UN 38.3 transport testing and IEC 62133 cell validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-End Bicycle Market |
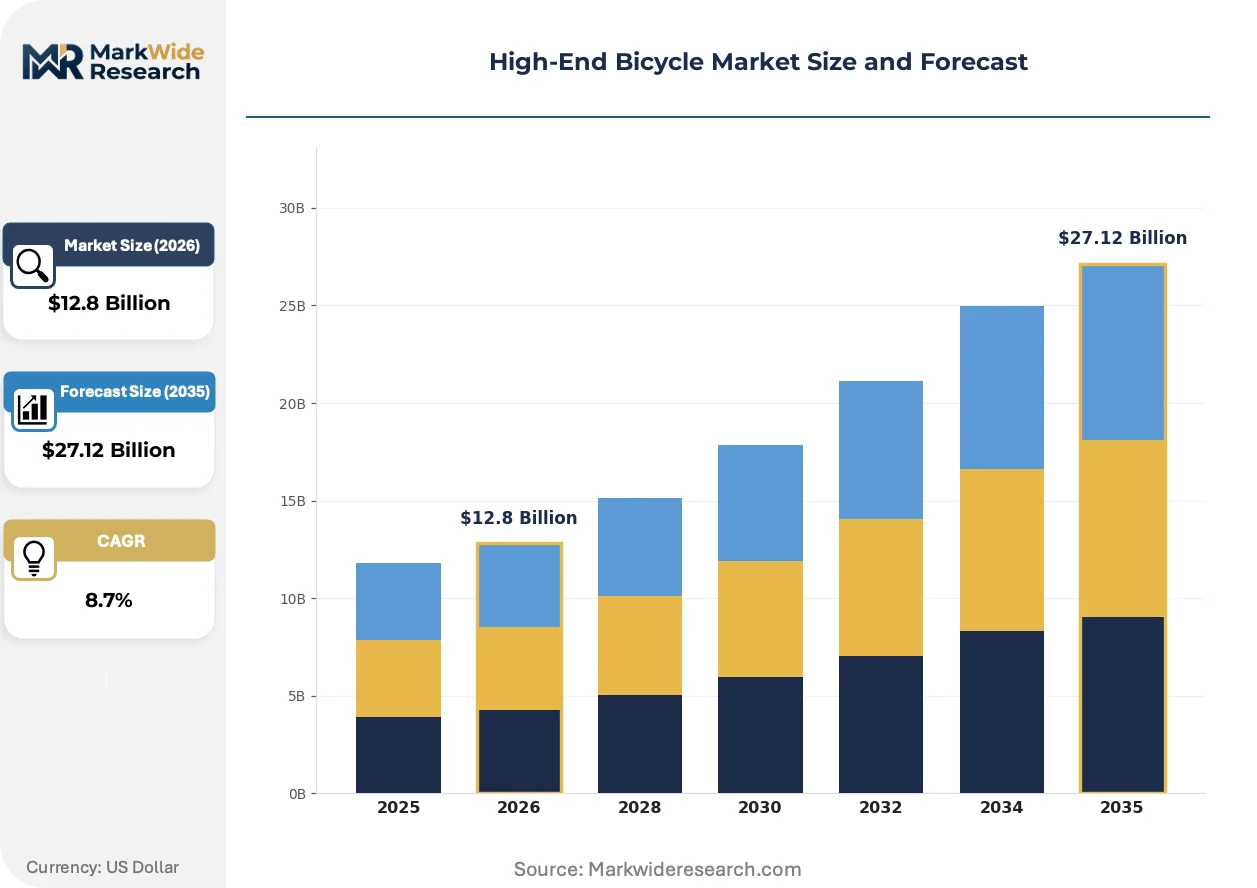
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Road Bikes, Mountain Bikes, Hybrid Bikes, Electric Bikes Frame Material: Carbon Fiber, Aluminum, Titanium, Steel Component Type: Groupsets, Wheelsets, Brakes, Tires Usage Type: Commuting, Recreational, Competitive, Touring |
| Companies Covered | Colnago, Bianchi, Specialized, Cervelo, Giant, Trek, Scott, Cannondale, Pinarello, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-End Bicycle Market Emerging Trajectories
Three intersecting forces are restructuring competitive positioning: materials science breakthroughs, regulatory scope expansion into electronic systems, and channel disintermediation through fit-technology investments.
Integrated power meter and biometric sensor modules are miniaturizing to sub-20-gram packages that embed directly into crank arms and handlebar stems. Elite amateur racers and gran fondo participants adopt these systems at replacement-cycle frequency. Component suppliers compress electronics manufacturing cost curves while frame builders redesign cockpit architectures around concealed wiring channels.
REACH restrictions on epoxy resin systems and volatile organic compounds constrain chemistry choices for European manufacturing facilities. Frame producers shift toward water-based pre-preg alternatives or relocate final assembly to Asian facilities with less stringent emissions protocols. Premium road bike categories with European heritage branding face the steepest compliance cost escalations.
Certified fit-studio investments displace traditional retail relationships as the primary purchase channel for four-figure road bikes. Trek's dealer network and Specialized's Retül acquisition exemplify this pattern. North American metropolitan markets show the fastest channel rotation, with urban centers like Boulder and Marin County leading studio-density concentration.
High-End Bicycle Market Segmentation
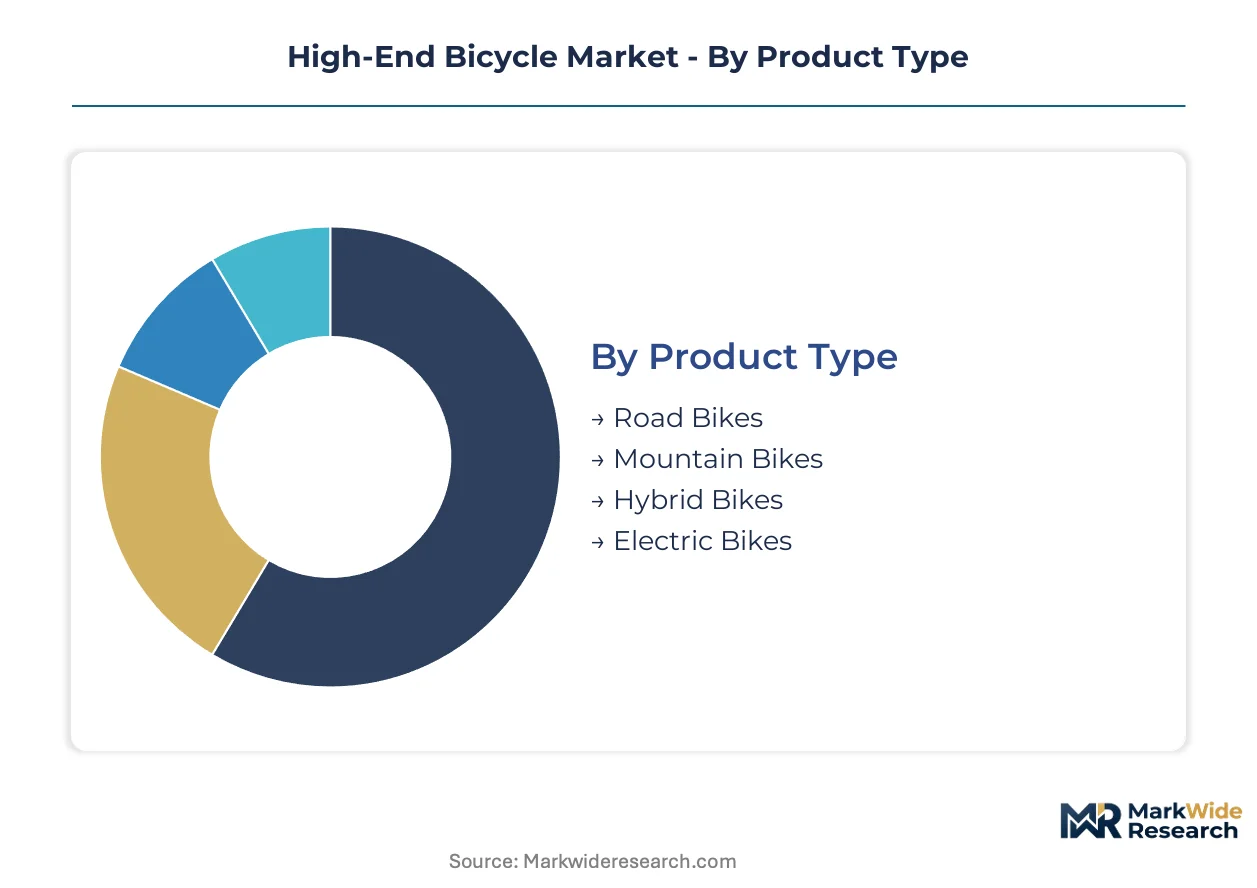
Segmentation in the high-end bicycle market exposes where technical differentiation commands price premiums and where supply constraints limit competitive entry. Frame materials and product architectures concentrate margin in distinct pools that reward specialized manufacturing capabilities.
Product Type:
Margin pools concentrate in sub-seven-kilogram road platforms and mid-motor electric systems where integration complexity sustains pricing power.
- Road Bikes:Sub-kilogram disc-brake builds employing Toray T1100G carbon pre-preg dominate gran fondo and elite amateur racing replacement cycles. Demand clusters in Italian and Spanish endurance event corridors where gram-counting justifies four-figure frame investments.
- Electric Bikes:250W mid-motor integration extends range thresholds for premium urban mobility, though thermal dissipation limits throttle power-to-weight ambitions. Germany, France, and Netherlands bike-to-work subsidy schemes channel commuter spending toward premium e-bike frames.
- Mountain Bikes:Full-suspension carbon platforms serve enduro and cross-country disciplines with hydroformed aluminum rear triangles.
- Hybrid Bikes:Flat-bar endurance geometry bridges recreational and commuting use cases with aluminum or entry-carbon construction.
Road bikes hold installed capacity. Electric bikes are rotating up the share rankings.
Frame Material:
Cost tier stratification separates aerospace-grade composites from artisan metalwork, with volume scale determining supplier qualification economics.
- Carbon Fiber:Monocoque construction employing pre-impregnated Toray T1100G sheets enables sub-kilogram frame weights at scaled production volumes. Taiwanese Taichung-area facilities concentrate layup expertise, creating geopolitical vulnerability for brands dependent on contract manufacturing.
- Titanium:3Al-2.5V tubing occupies a narrowing artisan niche serving custom-fit touring and competitive segments where weld quality commands wage premiums. European heritage brands face steepest ECHA REACH compliance cost escalations for resin-adjacent finishing processes.
- Aluminum:Hydroformed 6061-T6 variants deliver performance-to-price ratios for entry-premium road and mountain categories.
- Steel:Chromoly and stainless Reynolds tubing persists in bespoke touring and randonneuring segments.
Carbon fiber holds installed capacity. Titanium is rotating up the share rankings.
Component Type:
Application intensity determines replacement frequency, with power transfer components cycling faster than safety-critical systems.
- Groupsets:Integrated electronic shifting with concealed wiring channels commands the highest per-gram premium in complete builds. Miniaturized power meter modules embedding into crank arms drive replacement-cycle frequency among data-driven amateur racers.
- Wheelsets:Carbon rim brake and disc-brake variants concentrate aerodynamic R&D investment, with depth profiles segmenting across flat-sprint and climbing-specialist use cases.
- Brakes:Hydraulic disc systems displaced rim calipers across premium road categories, with thermal management determining pad compound selection.
- Tires:Tubeless-ready casings with proprietary rubber compounds balance rolling resistance against puncture protection for gran fondo distances.
Groupsets hold installed capacity. Wheelsets are rotating up the share rankings.
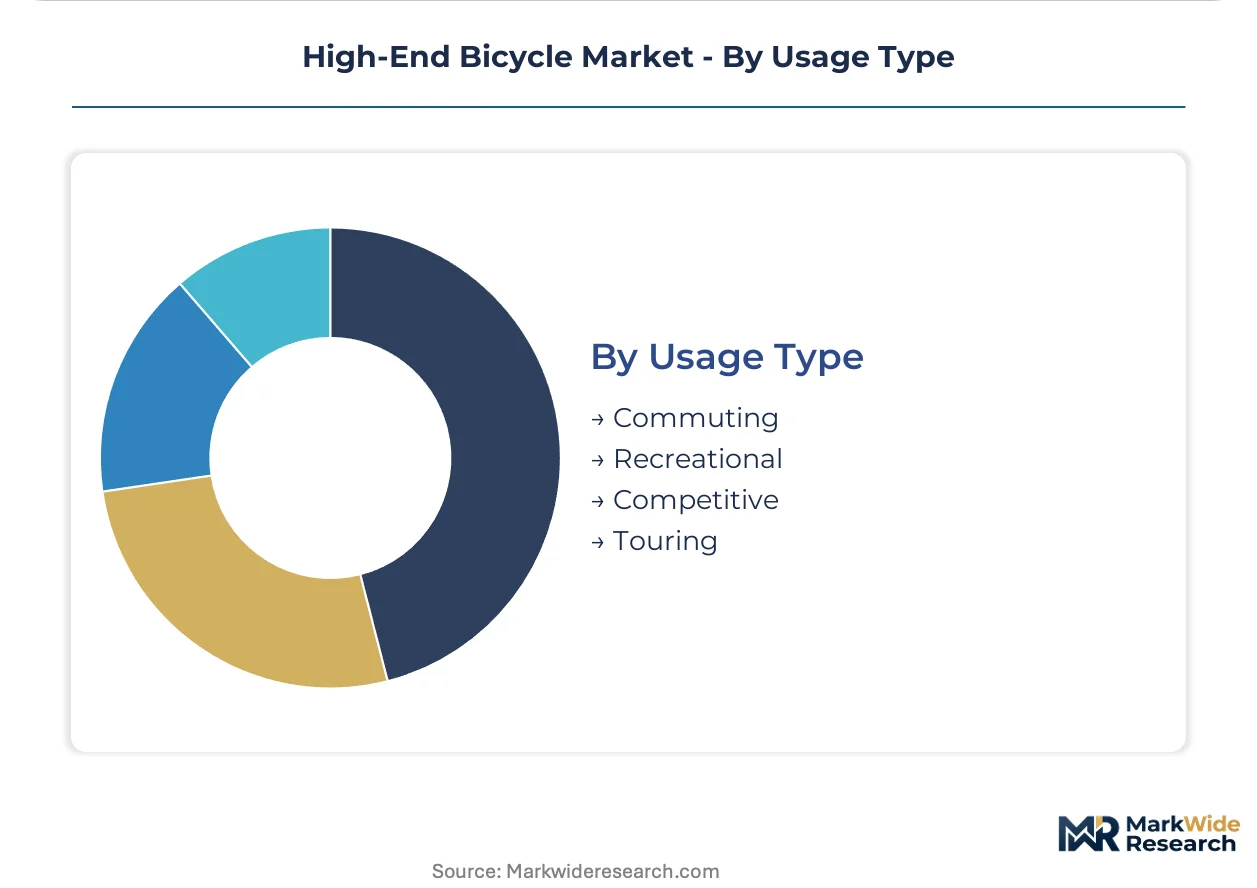
Usage Type:
Customer type separates daily utility riders from event-driven purchasers, with competitive segments showing shortest replacement cycles.
- Competitive:Elite amateur and professional racing programs across Italy, Spain, and Belgium drive sub-seven-kilogram frame turnover at 18-24 month intervals. ISO 4210 fatigue testing certification requirements extend validation timelines for new platform launches.
- Commuting:EU Green Deal subsidy schemes in Germany, France, and Netherlands reframe premium bicycle ownership as tax-advantaged transportation infrastructure. Copenhagen and Amsterdam corridor investments position urban bikes for daily capture.
- Recreational:Weekend endurance riders prioritize fit-studio certified geometry over gram-counting, extending replacement cycles.
- Touring:Multi-day expedition use cases favor titanium durability and steel repairability over carbon weight savings.
Competitive holds installed capacity. Commuting is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taichung-area composites facilities concentrate carbon fiber layup expertise for multiple heritage brands, creating geographic dependency that shapes procurement patterns across the industry. European assembly plants face escalating ECHA REACH compliance costs for resin-adjacent finishing processes. North American distribution networks pivot toward certified fit-studio formats that bypass traditional retail markups.
Germany
KBA-administered bike-to-work subsidies channel commuter spending toward premium frames through tax-advantaged employer schemes. The EU Green Deal mandates transport sector decarbonization that elevates cycling infrastructure investment priorities. Stuttgart and Munich metropolitan corridors concentrate fit-studio density and gran fondo event participation.
United States
Elite amateur racing programs across Colorado and California drive replacement cycles for sub-seven-kilogram disc-brake builds. FDA oversight of biometric wearables creates adjacent compliance burdens for integrated health-tracking components. Boulder and Marin County anchor certified fit-studio network expansion.
Italy
Gran fondo endurance events across Lombardy and Tuscany sustain demand for Toray T1100G carbon pre-preg road platforms. REACH restrictions on volatile organic compounds constrain domestic manufacturing chemistry choices. Milan and Treviso industrial clusters concentrate heritage brand headquarters and limited production runs.
Netherlands
Amsterdam and Utrecht infrastructure investments position premium urban bikes for daily commuter capture. National bike-to-work subsidy schemes extend tax advantages to four-figure frame purchases. Randstad corridor cycling mode share exceeds fifty percent in core districts.
Taiwan
Taichung-area contract manufacturers control scaled carbon fiber monocoque production for multiple global brands. Geopolitical logistics vulnerability concentrates in this single manufacturing basin. Local facilities employ specialized layup technicians that command wage premiums compressing assembly margins.
High-End Bicycle Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with heritage European marques commanding brand premiums and Asian contract manufacturers capturing scale efficiencies. The market structures around a tiered hierarchy: limited-production artisan builders, vertically integrated mid-volume specialists, and mass-market brands with premium sub-lines. Strategic moves concentrate on certified fit-studio network expansion and direct-to-consumer channel development that preserves margin while reducing retail dependency.
Within the heritage European tier, Colnago and Pinarello exemplify limited-production positioning anchored to grand-tour racing visibility. Trek represents the vertically integrated North American archetype with controlled distribution through dealer-certified measurement protocols. Specialized occupies a technology-forward position emphasizing in-house composites R&D and acquired fit-technology assets.
| Leading Market Players |
|---|
| Colnago |
| Bianchi |
| Specialized |
| Cervelo |
| Giant |
| Trek |
| Scott |
| Cannondale |
| Pinarello |
| Others |
Supply Flow & Price Mechanics
ISO 4210 fatigue testing certification gates both supplier qualification economics and frame-tier price differentiation, compressing margin structures for new platform entrants while rewarding heritage brands with amortized validation pipelines. E-bike powertrain UN 38.3 transport testing and IEC 62133 cell validation now extend this certification burden into electronic systems, bifurcating pricing power between mechanical-heritage and electronics-integrated product architectures.
Pricing Analysis
ISO 4210 dictates the pricing tier structure across factory-team replica, certified performance, and entry-premium frame categories, with validation timeline differentials separating four-figure builds from mass-market alternatives. Price differentiation rests on carbon layup grade and fit-studio certification depth, with sub-kilogram Toray T1100G frames commanding sustained premiums. Cost compression in entry-carbon tiers is intensifying because Taiwanese contract manufacturers are scaling monocoque production for multiple brand clients. Gran fondo participants show lowest price sensitivity while recreational commuters exhibit highest elasticity to frame cost.
Supply Chain Analysis
Taichung-area composites facilities underwrite global carbon fiber monocoque capacity for European and North American heritage brands, creating single-basin dependency that amplifies geopolitical risk exposure. Raw material feeds draw from Toray T1100G pre-preg supply, 3Al-2.5V titanium billet, and hydroformed 6061-T6 aluminum extrusions. Tariff exposure concentrates in finished frame imports from Taiwan into EU and US markets. Distribution runs through certified fit-studio networks that bypass traditional retail markups while preserving brand margin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power meter and biometric sensor miniaturization is shifting value capture from frame hardware to integrated electronics ecosystems, with concealed wiring channel architectures becoming the interoperability standard that determines platform stickiness.
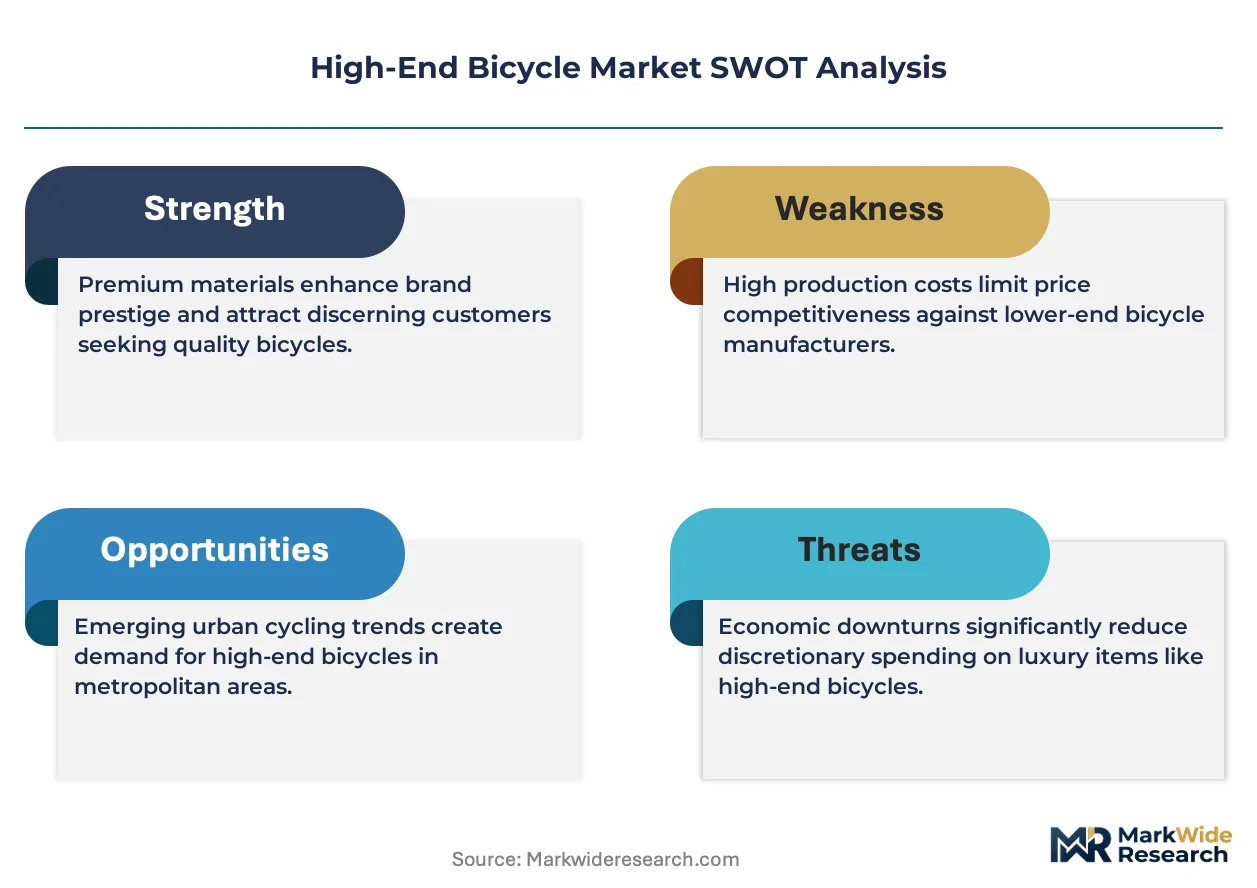
For Market Incumbents: Fortify in-house composites R&D control over Taichung layup specifications to defend against contract manufacturer margin compression, while accelerating ISO 4210 pre-validation pipelines to shorten new platform launch timelines. Channel control through dealer-certified fit-studio networks preserves pricing power against direct-to-consumer entrants. Backward integration into power meter module design hedges against electronics supplier consolidation. For New Entrants and Emerging Players: CE marking fast-track for 250W mid-motor e-bike systems opens white-space in German and Dutch bike-to-work subsidy corridors, where employer tax-advantaged schemes reduce effective price resistance. Target urban mobility segments in Copenhagen and Amsterdam infrastructure investment zones, where daily commuter capture rewards premium frame durability over gram-counting. Go-to-market leverage rests on direct-to-consumer fit-technology partnerships that replicate studio certification without retail overhead. For Investors and Strategic Acquirers: EU Green Deal transport decarbonization mandates reshape the acquisition landscape toward subsidy-dependent commuter platforms and gran fondo event-serving endurance specialists. Long-term viability favors vertically integrated mid-volume specialists with captive Taiwan manufacturing relationships and acquired fit-technology assets. Watch battery certification scope expansion beyond UN 38.3 into thermal runaway testing protocols as the signal for e-bike powertrain consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Fit-Studio Network Expansion | Dealer-certified measurement protocols in Boulder and Marin County bypass retail markups while preserving four-figure frame margins. |
| In-House Composites R&D | Toray T1100G layup quality control from Taiwan facilities to retail floors collapses price barriers between factory replicas and consumer builds. |
| E-Bike Powertrain Integration | 250W mid-motor thermal management investments extend range thresholds for German and Dutch bike-to-work subsidy capture. |
| Biometric Wearable Convergence | Sub-20-gram power meter modules embedding into crank arms create adjacent revenue streams beyond hardware sales for data-driven racers. |
| REACH Compliance Relocation | Water-based pre-preg alternatives or Asian assembly shifts reduce ECHA volatile compound cost escalations for European heritage brands. |
Methodological Framework
A spread of perspectives from frame engineering directors, fit-studio operators, gran fondo event organizers, and bike-to-work subsidy program administrators converged on the working assumptions that shape this analysis. Primary fieldwork combined with secondary validation from ISO 4210 certification databases, ECHA REACH substance restriction filings, EU Green Deal transport policy documents, and Taiwan customs export records. Bottom-up build estimates from component cost structures and top-down demand calibration from subsidy program enrollment data were triangulated to anchor volume and value outputs.
Segmentation dimensions modeled include frame material tier, product architecture, component integration depth, and usage intensity across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves fitted to replacement-cycle frequency data and infrastructure investment trajectories. Industry-specific forecast inputs incorporated gran fondo event participation rates and employer bike-to-work scheme adoption curves.
Decision-makers should treat outputs as directional under sustained EU Green Deal subsidy authorization and stable Taiwan manufacturing access assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as E-bike battery certification scope expansion and REACH resin restriction enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Windsurf Masts Market
Sports Equipment
Crampon Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Recreational Rowing Boats Market
Sports Equipment
Golf Shoes Market
Sports Equipment
Europe Archery Equipment Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
Soccer Gear Market
Sports Equipment
Rowing Machine Market
Sports Equipment
Agility Ladders Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Football Equipment Market
Sports Equipment
Mini Balance Beam Market
Sports Equipment
Ergonomic Strap Systems Market
Sports Equipment
Hydration Belt Market