
 Middle East and Africa Shiitake Mushroom Market | 2026-2036
Middle East and Africa Shiitake Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Shiitake Mushroom Market Foresight
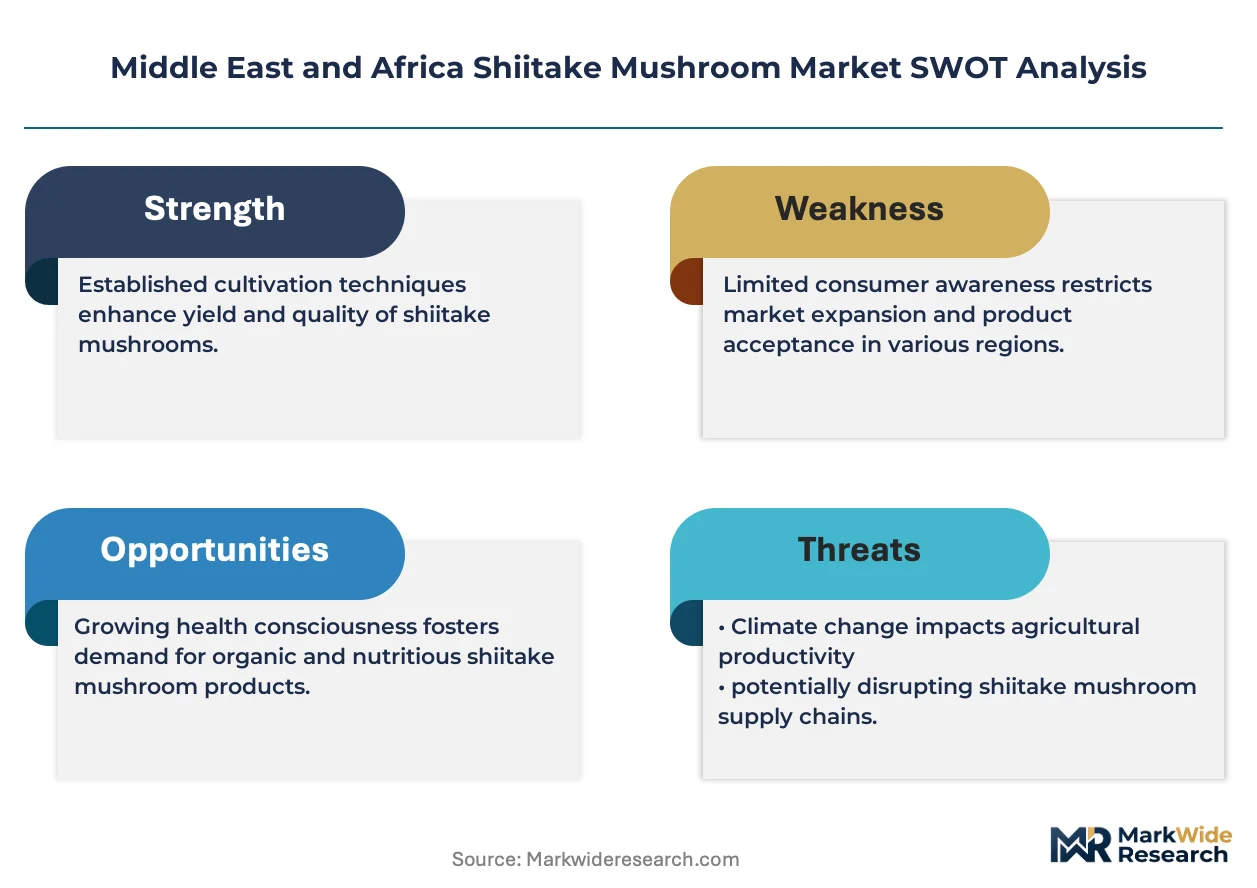
Specialized mycology technicians is reorganizing production capacity across the Middle East and Africa Shiitake Mushroom Market as commercial farms scale beyond artisanal output. African Mushroom Company anchors its position through backward integration into substrate preparation, while Nile Mushrooms Ltd leverages controlled-environment expertise to sustain year-round supply consistency. FungusAfrica competes on organic certification depth, differentiating its harvests for premium nutraceutical buyers in the Gulf Cooperation Council zone.
Shiitake mushrooms denote Lentinula edodes, a wood-decaying basidiomycete cultivated on sterilized hardwood sawdust or log substrates, prized for umami-rich lentinan polysaccharides and ergosterol content that drives both culinary and functional food applications. Fresh Shiitake commands the dominant value share across retail channels, though Dried Shiitake extends shelf-stable access into markets with limited cold-chain infrastructure. The Nutraceuticals end-user segment captures expanding margin pools as extract-grade material feeds supplement formulators in South Africa and the United Arab Emirates.
South Africa's Department of Agriculture, Land Reform and Rural Development sets phytosanitary standards for mushroom imports, while Saudi Arabia's SFDA governs nutraceutical ingredient registrations that determine market access for extract suppliers. Egypt's agricultural quarantine authority enforces substrate-origin documentation that shapes cross-border trade flows from Nile Delta production zones. Stakeholders must monitor how evolving halal certification requirements for functional foods will redirect formulation sourcing decisions across Gulf state processing hubs.
Market Dynamics
Controlled-environment agriculture techniques are compressing production seasonality across Middle East and Africa Shiitake Mushroom Market cultivation zones, enabling year-round supply consistency that reconfigures traditional import dependency patterns.
Growth Catalysts
- Substrate sterilization automation:Steam-based sterilization systems reduce contamination rates in Egyptian and South African growing facilities. This process innovation lowers batch failure frequency for commercial-scale operators.
- Nutraceutical formulation demand:Extract-grade Shiitake supplies supplement manufacturers in South Africa and the United Arab Emirates. Lentinan polysaccharide applications drive premium pricing for pharmaceutical-grade material.
- Gulf re-export circuit expansion:Cairo-based distributors channel Egyptian production into Saudi Arabia and UAE retail networks. This geographic concentration amplifies volume throughput for regional cultivators.
Market Restraints
- Hardwood sawdust supply volatility:Substrate feedstock costs fluctuate with South African timber processing output. This input dependency squeezes margin predictability for non-integrated growers.
- Cold-chain infrastructure gaps:Limited refrigerated logistics capacity in interior African markets constrains fresh Shiitake distribution reach. Dried product formats absorb demand that fresh cannot serve.
- Halal certification complexity:Saudi Arabia's SFDA and UAE's MOHAP maintain divergent functional food approval timelines. Registration friction delays nutraceutical ingredient market access.
Strategic Opportunities
- Organic certification depth:Premium nutraceutical buyers in the Gulf Cooperation Council zone pay price premiums for certified organic harvests. This segment remains underpenetrated relative to conventional supply.
- Specialty food retail expansion:South African premium retailers represent a rapidly expanding buyer segment for cultivated varieties. Direct-to-retail relationships bypass traditional wholesale markups.
- Backward integration into substrate preparation:Captive sawdust processing and spawn production reduce external dependency. Integrated operators capture value that currently flows to third-party suppliers.
Industry Challenges
- Specialized mycology technician scarcity:Commercial farm scaling beyond artisanal output requires skilled personnel for contamination control and strain management. Training pipelines lag behind facility expansion timelines.
- Phytosanitary documentation burden:Egypt's agricultural quarantine authority enforces substrate-origin traceability requirements. Cross-border shipment delays accumulate from paperwork verification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Shiitake Mushroom Market |
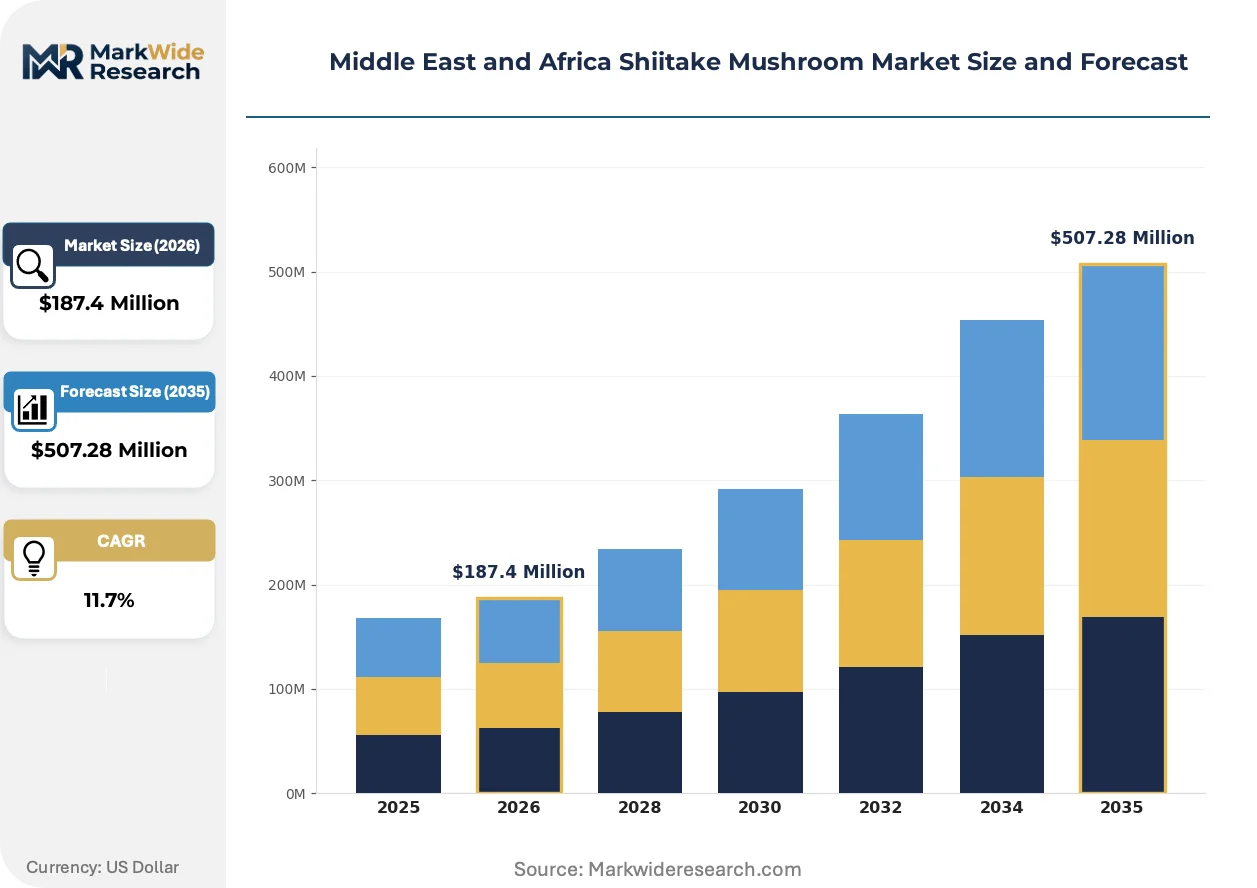
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Shiitake, Dried Shiitake, Shiitake Extract, Shiitake Powder Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Restaurants, Households, Food Processing, Nutraceuticals Packaging Type: Bags, Boxes, Retail Packs, Bulk Packaging |
| Companies Covered | Mushroom Majestic, African Mushroom Company, FungusAfrica, Zimbabwe Mushroom Company, Nile Mushrooms Ltd, Chaminuka Organic Mushrooms, Monterey Mushrooms, Hirano Mushroom LLC, M2 Ingredients, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Shiitake Mushroom Market Shifts & Advancements
Production economics across Middle East and Africa Shiitake Mushroom Market cultivation are restructuring around climate-controlled infrastructure investments that sever traditional growing season constraints.
Automated climate control systems with precision humidity and CO2 management are displacing passive greenhouse designs in commercial Egyptian and South African facilities. Large-scale nutraceutical extract buyers now mandate year-round supply consistency clauses in procurement contracts. This technology shift compresses price premiums that seasonal scarcity previously supported.
Saudi Arabia's SFDA nutraceutical ingredient registration requirements are tightening documentation standards for functional food formulations. Extract suppliers must now submit lentinan polysaccharide concentration assays and stability data. Gulf state processing hubs are responding by pre-qualifying Egyptian and South African cultivators through dedicated supplier development programs.
Direct procurement relationships between cultivators and specialty food retailers are shortening distribution layers that historically absorbed margin. South African premium supermarket chains now contract directly with controlled-environment farms for consistent fresh supply. This channel restructuring concentrates volume with integrated operators capable of meeting private-label specifications.
Middle East and Africa Shiitake Mushroom Market Segmentation
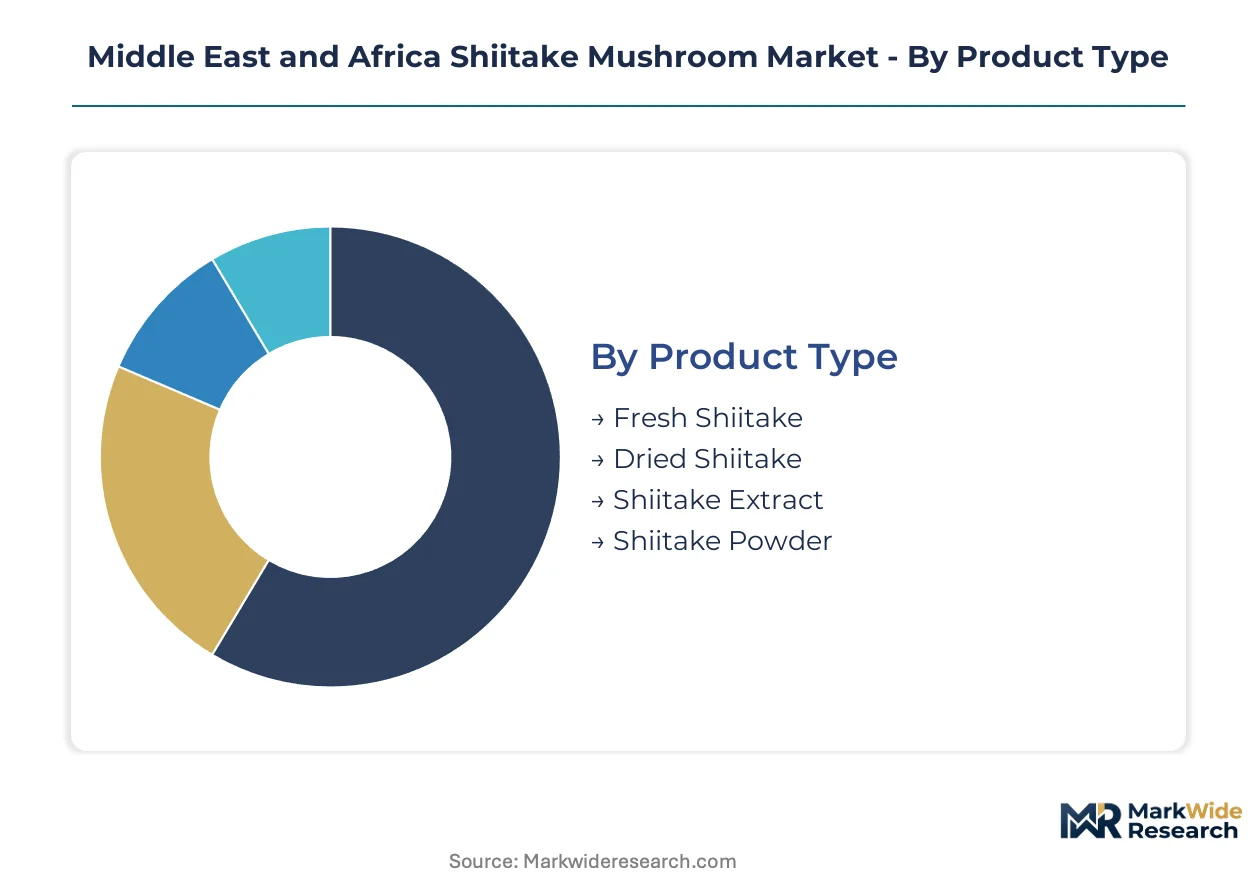
Shiitake mushroom segmentation across the Middle East and Africa reveals how product form, channel access, and end-use application determine margin capture. Each dimension carries distinct regulatory, logistical, and pricing implications for regional operators.
Product Type:
Fresh Shiitake faces substitution pressure from oyster and button mushroom varieties where cold-chain reliability falters, while processed formats compete with imported Asian supply.
- Fresh Shiitake:Whole caps with intact gills deliver maximum umami intensity for premium culinary applications. South African specialty retailers and Cairo-based Gulf re-export distributors concentrate procurement here, though perishability limits interior African market penetration.
- Dried Shiitake:Dehydrated whole caps and slices concentrate lentinan polysaccharides while eliminating refrigeration dependency. Nigerian and Kenyan buyers favor this format where logistics infrastructure gaps persist.
- Shiitake Extract:Standardized lentinan concentrates for nutraceutical formulation.
- Shiitake Powder:Milled fruiting body material for functional food fortification.
Fresh Shiitake retains volume leadership; Shiitake Extract holds the steepest expansion curve.
Distribution Channel:
Channel economics stratify sharply between temperature-controlled fresh logistics and ambient-stable distribution, with margin compression most severe in intermediary-heavy wholesale tiers.
- Online Retail:E-commerce platforms aggregate fragmented demand across Gulf Cooperation Council urban centers. Dubai-based fulfillment hubs enable direct-to-consumer dried and extract product delivery, bypassing traditional import markups.
- Supermarkets:South African premium chains contract directly with controlled-environment farms for private-label fresh supply. This channel restructuring eliminates distributor margins for integrated cultivators.
- Specialty Stores:Gourmet and organic-focused independents in Cairo and Johannesburg.
- Wholesale:Traditional bulk aggregation for food service and processing buyers.
Supermarkets capture the highest value per kilogram; Online Retail climbs fastest as logistics platforms mature.
End User:
Application-driven demand splits between culinary volume and extract-grade premium, with nutraceutical buyers imposing the strictest quality certification requirements.
- Nutraceuticals:Extract-grade material feeds supplement formulators in South Africa and the United Arab Emirates. Saudi Arabia's SFDA registration mandates for lentinan polysaccharide content and stability data restrict supplier qualification to pre-certified Egyptian and South African cultivators.
- Restaurants:High-end dining establishments in Dubai, Riyadh, and Cape Town specify fresh cap diameter and stem trim standards. Direct procurement relationships with farms are replacing traditional produce distributors.
- Households:Retail consumers purchasing through supermarkets and online channels.
- Food Processing:Ingredient buyers for soups, sauces, and ready-meal formulations.
Restaurants dominate fresh volume; Nutraceuticals expand most quickly on extract-grade premiumization.
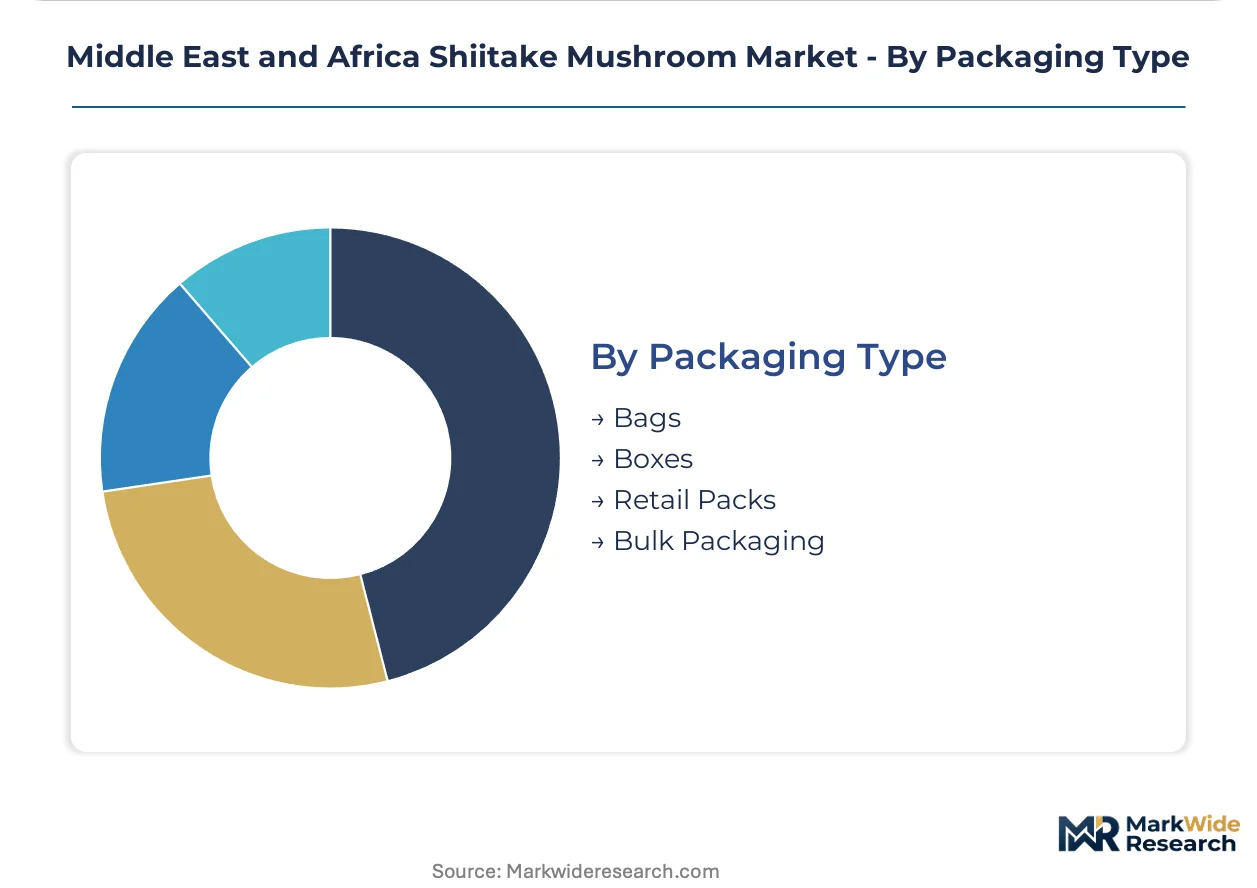
Packaging Type:
Packaging configuration tracks product form and channel destination, with modified atmosphere technology commanding price premiums in retail-facing formats.
- Retail Packs:Modified atmosphere trays and punnets preserve fresh Shiitake quality for supermarket display. South African chains specify oxygen-permeable film specifications that extend shelf life without condensation damage.
- Bulk Packaging:Ventilated crates and totes serve food service and processing volume buyers. Egyptian exporters to Gulf re-export circuits favor this format for cost-efficient air freight consolidation.
- Bags:Flexible packaging for dried and powder product formats.
- Boxes:Rigid corrugated for wholesale and export shipments.
Bulk Packaging moves the greatest tonnage; Retail Packs gain share fastest on supermarket channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's Department of Agriculture, Land Reform and Rural Development anchors phytosanitary governance across the region, setting import standards that Egyptian and Saudi regulators reference in bilateral trade protocols. Cairo-based distributors channel production into Gulf re-export circuits, while Johannesburg and Cape Town clusters concentrate domestic cultivation investment.
South Africa
Specialty food retailers in Cape Town and Johannesburg drive procurement for premium cultivated varieties. The Department of Agriculture, Land Reform and Rural Development enforces phytosanitary standards for mushroom imports that shape cross-border sourcing decisions. Controlled-environment farms in the Western Cape supply year-round volumes to supermarket private-label programs.
Egypt
Nile Delta production zones feed Gulf re-export demand through Cairo-based distributor networks. The agricultural quarantine authority mandates substrate-origin documentation that slows cross-border shipment clearance. Giza and Alexandria clusters specialize in extract-grade material for nutraceutical buyers in Saudi Arabia and the UAE.
Saudi Arabia
The SFDA governs nutraceutical ingredient registrations that determine market access for lentinan polysaccharide suppliers. Riyadh and Jeddah processing hubs pre-qualify Egyptian and South African cultivators through dedicated supplier development programs. Functional food formulators face tightening documentation standards for stability data and concentration assays.
United Arab Emirates
MOHAP maintains functional food approval timelines that diverge from Saudi protocols, creating registration friction for extract suppliers. Dubai-based fulfillment hubs aggregate e-commerce demand for dried and extract products across Gulf Cooperation Council urban centers. The emirate's logistics platforms enable direct-to-consumer delivery that bypasses traditional import markups.
Zimbabwe
Hardwood sawdust supply from timber processing zones near Harare supports substrate preparation for regional cultivation. Limited cold-chain infrastructure constrains fresh product distribution to interior markets, favoring dried format absorption. Chaminuka-area farms supply organic-certified harvests to premium buyers in South Africa and the Gulf.
Middle East and Africa Shiitake Mushroom Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa Shiitake Mushroom Market. Controlled-environment agriculture specialists command premium positioning through year-round supply consistency, while substrate-integrated operators capture margin through backward integration into sawdust processing and spawn production. The competitive landscape stratifies into three archetypes: integrated cultivators with captive substrate supply, extraction-focused nutraceutical suppliers, and regional distributors with Gulf re-export relationships. Dominant competitive moves include capacity expansion in climate-controlled facilities and strategic partnerships with specialty food retailers for direct procurement relationships.
Among Egypt-based operators, Nile Mushrooms Ltd occupies a position exemplifying controlled-environment expertise, while African Mushroom Company anchors the integrated archetype through substrate preparation capabilities. FungusAfrica represents the organic certification depth tier competing for premium nutraceutical buyers in the Gulf Cooperation Council zone.
| Leading Market Players |
|---|
| Mushroom Majestic |
| African Mushroom Company |
| FungusAfrica |
| Zimbabwe Mushroom Company |
| Nile Mushrooms Ltd |
| Chaminuka Organic Mushrooms |
| Monterey Mushrooms |
| Hirano Mushroom LLC |
| M2 Ingredients |
| Others |
Supply & Pricing Matrix
Facility scale economies in Egyptian and South African controlled-environment agriculture operations compress unit production costs while concentrating supply volume with integrated operators, creating asymmetric pricing power against fragmented substrate-dependent growers and establishing quality-differentiated price floors that Gulf re-export distributors must absorb or bypass.
Pricing Analysis
Cairo-to-Jeddah price spreads exceed Johannesburg-to-Dubai differentials due to Egyptian substrate-origin documentation burdens and quarantine clearance delays. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified nutraceutical grade from conventional fresh and dried commodity formats. Price differentiation hinges on halal certification depth and lentinan assay documentation, with nutraceutical buyers least sensitive and interior African food service distributors most price-responsive. Cost compression in standard-tier fresh supply intensifies as South African supermarket chains consolidate direct procurement relationships.
Supply Chain Analysis
Strategic stockpiling of hardwood sawdust substrate dominates inventory strategy among integrated Egyptian operators, while South African cultivators favor just-in-time spawn delivery to minimize contamination exposure. Geographic supply concentration centers on Egypt, South Africa, and Zimbabwe, with raw material dependencies spanning timber processing residues, gypsum supplements, and spawn inoculum. Single-source vulnerability permeates Gulf re-export circuits where Cairo-based distributors control channel access to Saudi and UAE buyers. Distribution runs through temperature-controlled air freight consolidation for fresh product and ambient containerized logistics for dried formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits defensive moat characteristics rooted in regulatory entrenchment, where SFDA and MOHAP nutraceutical registration requirements create multi-year supplier qualification barriers that pre-certified Egyptian and South African cultivators exploit.
For Market Incumbents: Shield year-round supply consistency advantages by locking in multi-season contracts with Gulf nutraceutical formulators before climate-control capacity additions by competitors reach operational status. Deepen backward integration into captive sawdust processing to neutralize South African timber output volatility that threatens margin stability. Prioritize halal certification investment as Saudi Arabia tightens functional food documentation standards.
For New Entrants and Emerging Players: Anchor in organic-certified extract-grade production for underpenetrated Gulf Cooperation Council nutraceutical buyers willing to pay certification premiums that incumbent conventional suppliers have not pursued. Target Zimbabwe and Kenya interior markets where cold-chain gaps exclude fresh competitors and dried product demand absorbs unmet volume. Pursue direct-to-retail relationships with South African specialty food chains as the primary go-to-market angle.
For Investors and Strategic Acquirers: Controlled-environment agriculture specialists with pre-qualified SFDA supplier status represent the most defensible acquisition archetype given registration timeline moats. Long-term viability hinges on climate-control technology depreciation cycles and substrate integration depth rather than commodity price exposure. Watch for Egyptian agricultural quarantine authority documentation streamlining as the inflection signal that could erode incumbent clearance-speed advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Preparation | Captive sawdust processing neutralizes South African timber output volatility that squeezes non-integrated growers. |
| Halal Certification Investment | SFDA tightening of functional food documentation standards redirects Gulf formulation sourcing toward pre-certified suppliers. |
| Direct-to-Retail Channel Development | South African supermarket private-label programs eliminate distributor markups for integrated cultivators meeting specification. |
| Controlled-Environment Capacity Expansion | Year-round supply consistency clauses in nutraceutical procurement contracts displace seasonal artisanal production. |
| Organic Certification Depth | Premium pricing from Gulf Cooperation Council nutraceutical buyers remains underpenetrated relative to conventional supply. |
Research Methodology
Initial hypotheses were tested against primary input from commercial farm operations managers, Gulf nutraceutical formulation procurement leads, Egyptian agricultural quarantine officials, and South African specialty retail category buyers and refined through secondary validation against customs trade records, SFDA nutraceutical registration databases, timber processing output statistics, and controlled-environment agriculture equipment import data. Bottom-up cultivation capacity estimates and top-down nutraceutical ingredient demand projections were triangulated to resolve variance.
Variance decomposition across product form, distribution channel, end-use application, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume trajectory modeling incorporating substrate sterilization automation adoption curves, Gulf re-export circuit throughput expansion, and nutraceutical formulation demand elasticity. Industry-specific forecast inputs included hardwood sawdust supply forecasts from South African timber processing and Egyptian quarantine clearance velocity trends.
Material uncertainties — regulatory harmonization failures between Saudi SFDA and UAE MOHAP, climate-control equipment supply disruptions, and hardwood substrate cost spikes — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding registration timeline stability and cold-chain infrastructure investment continuity. Revision becomes warranted when halal certification requirement divergence crosses thresholds that fragment Gulf sourcing decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Canned Fruits and Vegetables Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Cucumber and Gherkins Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
Sudachi Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
Global Bean Sprouts Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Yacon Fruit Extract Market
Fruits and Vegetables
Red Berries Market