
 Global Dehydrated Onion Flakes Market | 2026-2036
Global Dehydrated Onion Flakes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dehydrated Onion Flakes Market Analysis
Recipe-ready seasoning subscriptions and automated replenishment programs are broadening what processors purchase beyond commodity bulk. Olam Group leverages integrated farming operations across multiple continents to secure raw onion supply. Jain Farm Fresh Foods Limited anchors its position through backward integration into cold-chain agriculture and controlled-atmosphere storage. Sensient Natural Ingredients differentiates via clean-label extraction technologies that preserve volatile sulfur compounds.
Dehydrated onion flakes consist of Allium cepa bulbs that undergo washing, peeling, slicing, and controlled hot-air dehydration to moisture levels below six percent, yielding shelf-stable aromatic ingredients for industrial and consumer kitchens. Powdered formats command premium placement in seasoning blends where dispersion uniformity determines flavor delivery, while whole flakes retain structural integrity for visual applications in soups and sauces. Food service channels generate disproportionate volume pull from quick-service restaurant chains standardizing ingredient specifications across locations.
The FDA enforces pathogen testing and preventive controls under FSMA for dehydrated vegetable imports into the United States, while the EMA and EFSA coordinate mycotoxin thresholds across European member states. India's FSSAI mandates hygiene ratings for spice processing facilities exporting to institutional buyers. Stakeholders must monitor evolving maximum residue limits for pesticides in onion crops across multiple jurisdictions to avoid supply disruptions.
Market Dynamics
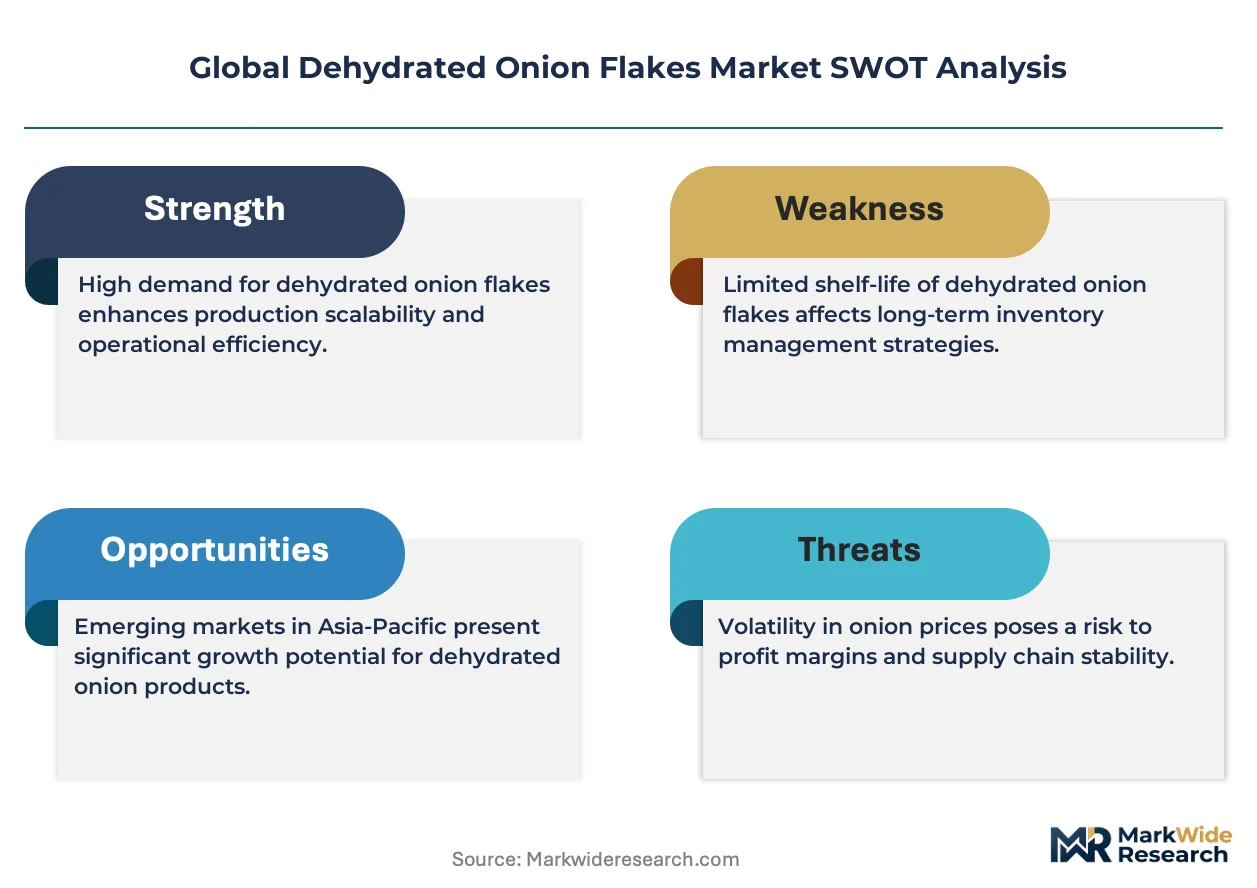
FSMA traceability mandates are forcing processors to requalify suppliers and consolidate procurement around vertically integrated onion processors with certified cold-chain documentation systems.
Growth Catalysts
- Quick-service restaurant standardization:Global chains are locking in dehydrated onion flake specifications across franchised locations to ensure flavor consistency in soups, sauces, and seasoning blends.
- India's FSSAI hygiene ratings:Mandatory facility ratings for spice exporters are accelerating consolidation toward large-scale processors with automated washing and sorting lines.
- Clean-label extraction technologies:Advanced low-temperature dehydration methods that preserve volatile sulfur compounds are opening premium placement in organic and natural product lines.
Market Restraints
- Fresh onion price volatility:Weather-induced crop failures in Maharashtra and Gujarat states directly compress processor margins during deficit harvest cycles.
- Single-origin supply concentration:Overreliance on Indian bulk processors exposes buyers to export duty fluctuations and port congestion at Nhava Sheva and Mundra.
- Freeze-dried substitutes:Higher-end food manufacturers are substituting conventional hot-air flakes with freeze-dried alternatives for superior aroma retention in gourmet applications.
Strategic Opportunities
- Recipe-ready subscription channels:Direct-to-consumer meal kit services are creating demand for pre-portioned, retail-packaged flakes beyond traditional industrial bulk formats.
- EU Green Deal agricultural incentives:Carbon footprint reduction mandates are favoring European processors with renewable-powered dehydration facilities and shorter logistics loops.
- Blockchain-enabled traceability:Integration of distributed ledger systems with farm management software is creating premium pricing tiers for fully documented supply chains from bulb to package.
Industry Challenges
- Skilled equipment maintenance:Shortages of technicians trained on continuous-belt dehydration systems and moisture-control instrumentation delay facility ramp-ups.
- FSMA compliance timelines:Foreign supplier verification program documentation requirements extend onboarding cycles for new Indian and Chinese processors by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dehydrated Onion Flakes Market |
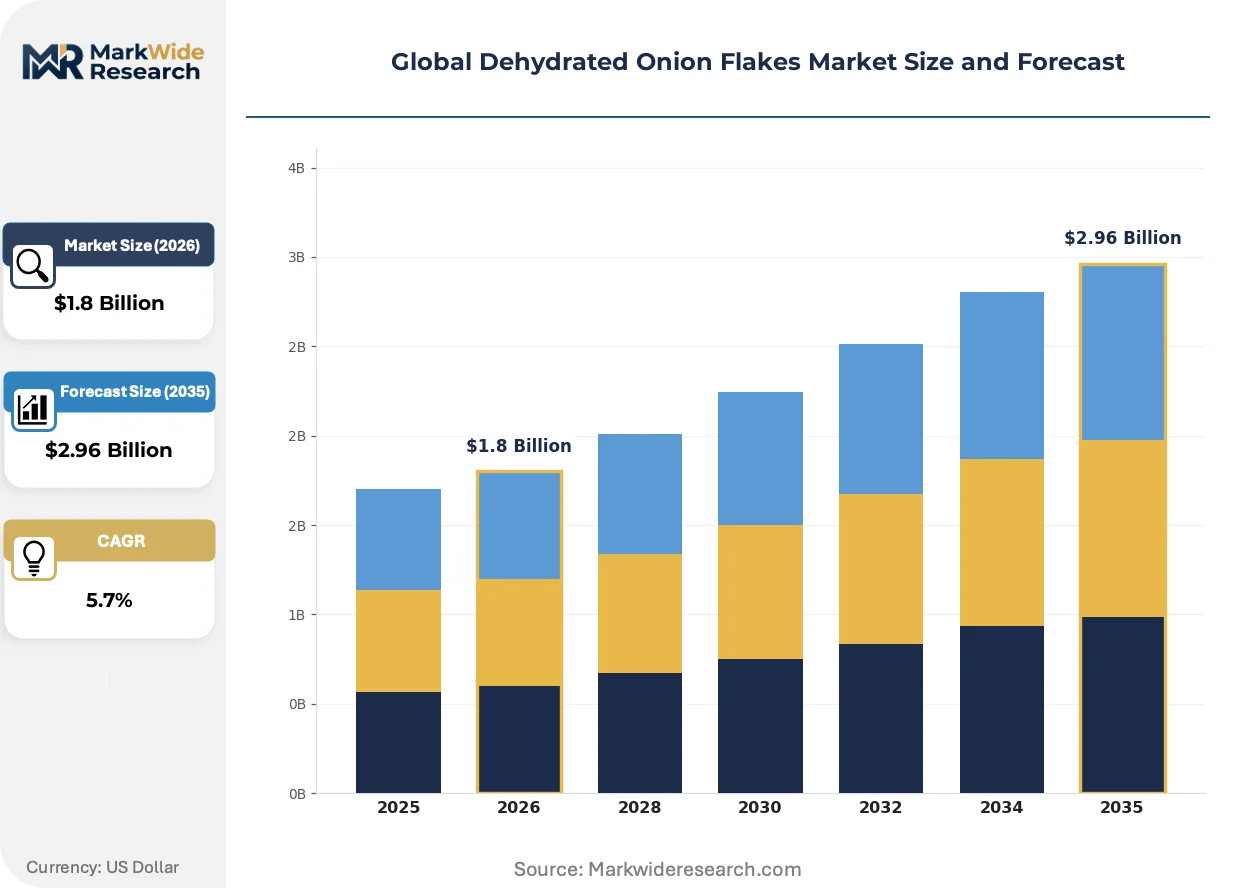
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Flakes, Minced, Granulated, Powdered End User: Food Processing, Retail, Food Service, Household Packaging Type: Bags, Jars, Pouches, Bulk Containers Distribution Channel: Online, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Olam Group, Jain Farm Fresh Foods Limited, Sensient Natural Ingredients, Real Dehydrates Pvt. Ltd., Daksh Foods Pvt. Ltd., Harmony House Foods, Inc., Silva International, Rocky Mountain Spice Company, Natural Dehydrated Vegetables Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dehydrated Onion Flakes Market Emerging Trajectories
Controlled-atmosphere storage and precision agriculture are converging to reshape raw material quality and processing economics across the dehydrated onion value chain.
Infrared-assisted hot-air dehydration is electrifying energy efficiency benchmarks in flake production. Mid-scale processors in Spain and Egypt are retrofitting conventional drying tunnels with combined infrared-convective systems that cut fuel consumption by one-third. The technology is electrifying competitive positioning for regional suppliers seeking to offset European natural gas price volatility.
REACH chemical registration requirements are tightening contaminant thresholds for imported dehydrated vegetables entering European Union member states. The regulation is forcing non-EU processors to implement third-party laboratory testing protocols for pesticide residues and heavy metals. Indian exporters to Germany and the Netherlands are responding by segregating organic-certified growing regions and investing in on-site gas chromatography equipment.
Automated replenishment algorithms tied to food service inventory management systems are compressing order cycles and fragmenting shipment sizes. Large institutional distributors in the United States are replacing quarterly bulk contracts with algorithm-triggered weekly deliveries direct to commissary kitchens. The pattern is most visible in California and Texas quick-service restaurant clusters where real-time stock monitoring minimizes working capital tied to seasoning inputs.
Global Dehydrated Onion Flakes Market Segmentation
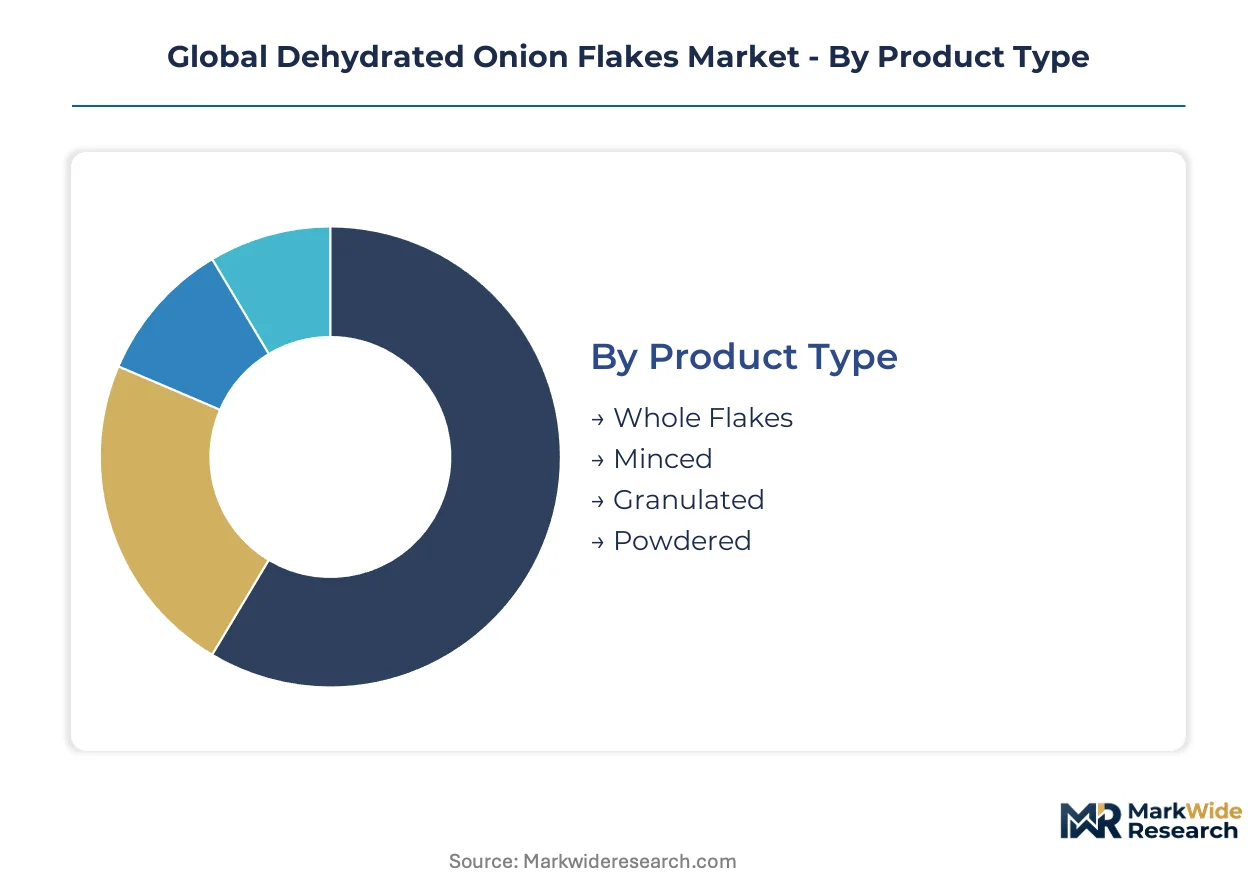
Dehydrated onion flake processors configure production lines around specific cut sizes and moisture specifications, with capital allocation decisions locking in capacity for years. Segmentation reveals where equipment investments concentrate and which customer channels command premium pricing tiers.
Product Type:
Capital intensity escalates with particle size reduction, as pulverization equipment and dust-control systems require substantial upfront investment beyond basic slicing and drying infrastructure.
- Whole Flakes:Large-cut onion pieces retain cellular structure and visual integrity for garnish applications in soups and prepared salads. Quick-service restaurant chains in Texas and California standardize on whole flake specifications for consistent rehydration performance across commissary kitchens.
- Powdered:Fine-ground particles below 80 mesh enable uniform dispersion in dry seasoning blends and soup bases. Blending houses in Illinois and New Jersey drive procurement volume for powdered formats where flavor delivery consistency determines contract renewals.
- Minced:Intermediate 3-6mm particles balance surface area with structural presence for sauce applications.
- Granulated:Coarse-ground material flows freely through automated dispensing equipment in industrial seasoning operations.
Whole flakes absorb the bulk of installed capacity; powdered formats are expanding most quickly as seasoning blend manufacturers consolidate procurement.
End User:
Customer scale determines order frequency and specification rigor, with institutional buyers imposing traceability requirements that reshape supplier qualification protocols.
- Food Processing:Industrial manufacturers of soups, sauces, and seasoning blends purchase in bulk totes with certified moisture content and microbial specifications. Facilities in Gujarat and Maharashtra supply dehydrated flakes to European ready-meal producers under FSSAI hygiene rating requirements.
- Food Service:Quick-service restaurant chains and contract caterers specify flake size and sulfite residual limits for cross-location consistency. Automated replenishment programs in California quick-service clusters compress order cycles from quarterly to weekly deliveries.
- Retail:Branded consumer packaging through supermarkets and specialty stores demands retail-ready jar and pouch formats with extended shelf-life claims.
- Household:Direct-to-consumer channels serve recipe-ready meal kit subscribers seeking pre-portioned seasoning packets.
Food processing commands the largest revenue share; food service channels are climbing the fastest as chain restaurant standardization accelerates.
Packaging Type:
Packaging format selection hinges on moisture barrier requirements and customer handling infrastructure, with bulk formats minimizing unit costs and retail formats maximizing shelf visibility.
- Bulk Containers:Fiber drums and food-grade totes holding 50-200 kilograms serve industrial processors with automated ingredient handling systems. Port congestion at Nhava Sheva and Mundra favors bulk consolidation for export shipments to European and North American destinations.
- Pouches:Multi-layer laminated bags with oxygen scavengers extend shelf life for mid-volume food service distributors. REACH chemical registration compliance for packaging materials tightens supplier qualification for EU-bound shipments.
- Bags:Paper and polywoven sacks balance cost and protection for domestic wholesale distribution.
- Jars:Glass and PET containers with tamper-evident closures target retail shelf placement and consumer pantry storage.
Bulk containers dominate export volume; pouches are gaining share fastest as food service distributors adopt just-inventory practices.
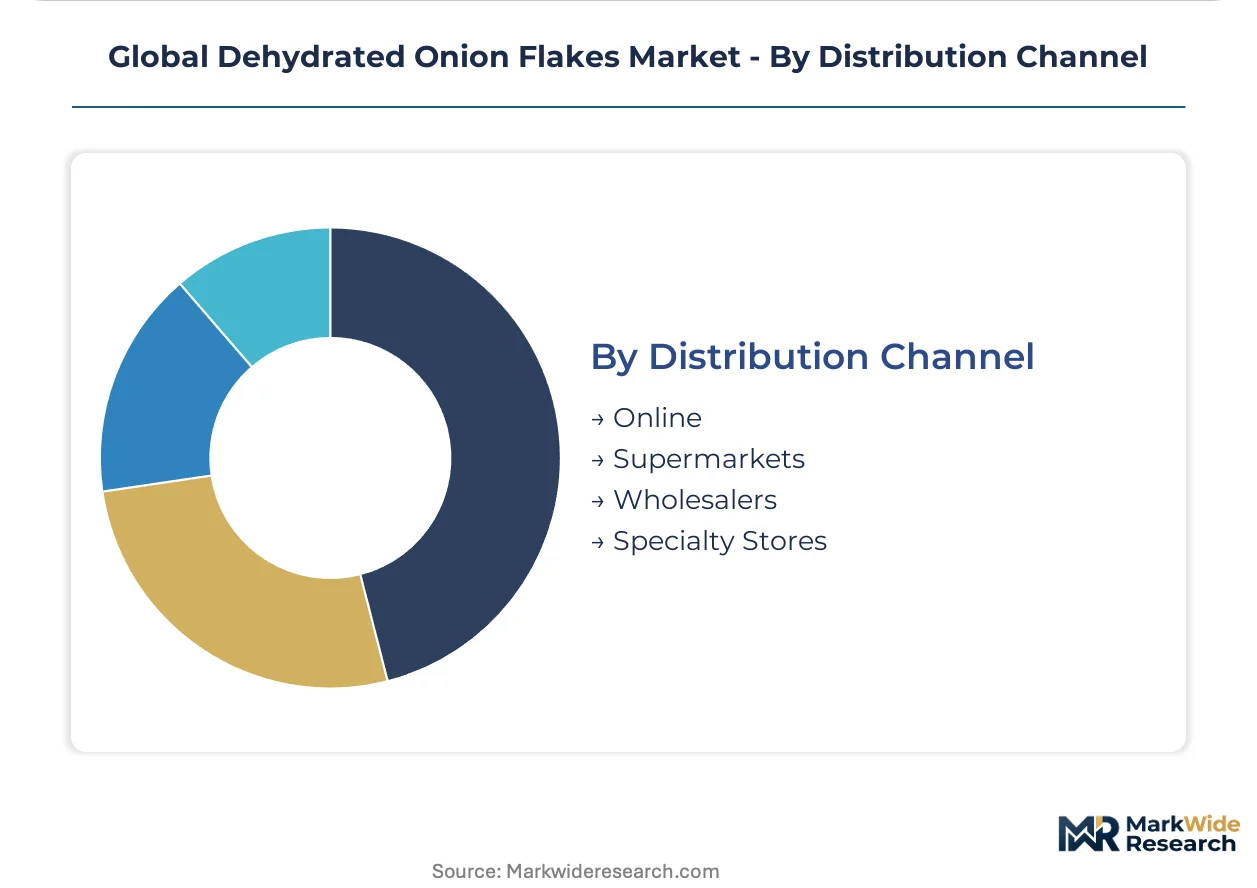
Distribution Channel:
Channel selection reflects customer procurement sophistication, with digital platforms fragmenting order sizes and traditional wholesalers maintaining volume concentration.
- Wholesalers:Institutional distributors consolidate bulk procurement for food manufacturers and restaurant chains, leveraging warehouse networks across Illinois, Texas, and California. FSMA foreign supplier verification program documentation flows through wholesaler quality assurance departments.
- Online:Direct-to-processor platforms and B2B marketplaces enable small-batch procurement with transparent pricing. Algorithm-triggered replenishment systems in quick-service restaurant clusters compress working capital requirements for seasoning inputs.
- Supermarkets:Retail grocery chains stock consumer-packaged formats for household cooking applications.
- Specialty Stores:Gourmet and organic retailers curate premium-certified and clean-label onion flake selections.
Wholesalers channel the majority of industrial volume; online platforms are expanding most quickly as procurement digitization penetrates mid-scale processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India harvests the majority of global onion tonnage while the United States and Germany absorb the largest import volumes for processed food manufacturing. This geographic split between raw material origin and consumption centers defines logistics strategies and regulatory compliance burdens across the value chain.
United States
Quick-service restaurant chains in California and Texas drive bulk procurement through automated replenishment systems that compress order cycles to weekly deliveries. FDA enforcement of FSMA foreign supplier verification programs extends onboarding timelines for new Indian processors by four to six months. Chicago and New Jersey blending houses concentrate demand for powdered formats where dispersion uniformity determines contract renewals.
Germany
REACH chemical registration requirements tighten contaminant thresholds for imported dehydrated vegetables entering through Rotterdam and Hamburg ports. EMA coordination with EFSA on mycotoxin limits forces non-EU processors to implement third-party laboratory testing protocols. Bavarian and North Rhine-Westphalia food manufacturers favor European processors with renewable-powered dehydration facilities under EU Green Deal agricultural incentives.
India
Maharashtra and Gujarat states host the dominant share of dehydration capacity with controlled-atmosphere storage infrastructure anchoring processor margins. FSSAI hygiene ratings for spice exporters accelerate consolidation toward large-scale facilities with automated washing and sorting lines. Port congestion at Nhava Sheva and Mundra exposes buyers to shipment delays during peak export seasons.
Netherlands
Rotterdam serves as the primary European entry point for Indian bulk shipments destined for German and French food manufacturers. ECHA enforcement of REACH packaging material standards tightens supplier qualification for EU-bound pouch shipments. The Randstad logistics cluster enables just-in-time distribution to mid-volume food service distributors across the Benelux region.
Egypt
Mid-scale processors in the Nile Delta region retrofit conventional drying tunnels with combined infrared-convective systems that cut fuel consumption by one-third. The country's national food safety regulator mandates hygiene certifications for facilities exporting to European institutional buyers. Alexandria and Cairo industrial zones attract investment from regional suppliers seeking to offset European natural gas price volatility.
Global Dehydrated Onion Flakes Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the dehydrated onion flake value chain. Integrated farming operations with captive dehydration capacity face pressure from specialized processors outsourcing raw material procurement. Three archetypes dominate: agricultural conglomerates with backward integration into cold-chain infrastructure, standalone dehydration specialists leveraging contract farming networks, and ingredient technology firms differentiating through extraction process patents. Consolidation accelerates through acquisition of regional processors to secure FSMA-compliant supply bases, while technology licensing agreements spread low-temperature dehydration methods that preserve volatile sulfur compounds.
Among India-based processors, Jain Farm Fresh Foods Limited and Real Dehydrates Pvt. Ltd. occupy positions within the integrated agricultural tier, exemplifying the archetype of processors with upstream control over cold-chain agriculture and controlled-atmosphere storage. Singapore-based Olam Group represents the multinational agricultural conglomerate model with operations across multiple continents. Sensient Natural Ingredients anchors the ingredient technology specialist segment, differentiating through clean-label extraction capabilities. Dakota Foods Pvt. Ltd. sits within the mid-scale regional processor tier serving European export markets.
| Leading Market Players |
|---|
| Olam Group |
| Jain Farm Fresh Foods Limited |
| Sensient Natural Ingredients |
| Real Dehydrates Pvt. Ltd. |
| Daksh Foods Pvt. Ltd. |
| Harmony House Foods, Inc. |
| Silva International |
| Rocky Mountain Spice Company |
| Natural Dehydrated Vegetables Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Fresh onion procurement costs from Maharashtra and Gujarat growing belts cascade through contract-based long-term offtake agreements into three-tier pricing structure across premium, standard, and economy levels, with FSSAI hygiene-rated processors commanding premiums over uncertified competitors serving spot-market buyers.
Pricing Analysis
Margin tightening in economy-grade bulk flake segments reflects weather-induced crop failures compressing processor spreads during deficit harvest cycles. Pricing stratifies across premium, standard, and economy tiers based on FSSAI certification status and volume scale commitments from quick-service restaurant chains. Cost-down pressure on standard-grade processors accelerates because Egyptian and Spanish competitors deploy infrared-assisted dehydration cutting fuel consumption. Food service distributors show highest price sensitivity due to automated replenishment compressing working capital, while organic-certified retail channels absorb premiums with minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Chicago, and Singapore anchor hub-and-spoke patterns for Indian bulk shipments. Supply concentrates in India, Egypt, and Spain for dehydration capacity, with raw material dependencies on fresh Allium cepa bulbs, natural gas for drying tunnels, and laminated packaging films. Single-source vulnerability at Nhava Sheva and Mundra ports exposes buyers to congestion delays during peak export seasons. Distribution runs through institutional wholesalers consolidating procurement for food manufacturers and restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dehydrated onion flake supply is tightening around FSSAI-certified capacity, with qualified processor onboarding timelines extending four to six months under FSMA foreign supplier verification programs.
For Market Incumbents: Extend controlled-atmosphere storage infrastructure in Gujarat and Maharashtra to buffer against weather-induced crop volatility. Deepen backward integration into precision agriculture and blockchain-enabled traceability systems to defend against freeze-dried substitutes capturing gourmet segments. Lock in multi-year offtake agreements with quick-service restaurant chains before Egyptian infrared-retrofitted capacity scales. For New Entrants and Emerging Players: Direct-to-processor B2B platforms offer the lowest barrier entry point for mid-scale dehydration specialists lacking wholesaler relationships. Target recipe-ready subscription channels and meal kit services seeking pre-portioned retail packaging beyond commodity bulk. Penetrate EU Green Deal incentive zones by retrofitting with renewable-powered dehydration and securing ECHA REACH compliance for European institutional buyers. For Investors and Strategic Acquirers: FSMA compliance completion by Indian processors is the leading indicator that acquisition multiples will compress as qualified supply expands. Position for five-to-ten year holding periods around processors with captive cold-chain agriculture and automated washing lines. Monitor FSSAI hygiene rating acceleration as the signal for consolidation timing toward large-scale integrated operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold-Chain Agriculture | Jain Farm Fresh Foods Limited anchors margins through captive onion storage infrastructure. |
| Blockchain-Enabled Traceability Deployment | Distributed ledger integration with farm management software creates premium pricing tiers. |
| Infrared-Convective Dehydration Retrofit | Egyptian processors cut fuel consumption by one-third offsetting European natural gas volatility. |
| Direct-to-Consumer Subscription Launch | Recipe-ready meal kit channels fragment order sizes beyond traditional industrial bulk formats. |
| FSSAI Hygiene Rating Certification | Mandatory facility ratings accelerate consolidation toward automated washing and sorting lines. |
Methodological Framework
Trade databases, FSSAI facility registration records, and FDA import refusal reports formed the secondary backbone validating primary intelligence. Plant managers at Gujarat and Maharashtra dehydration facilities, procurement leads at Illinois and New Jersey seasoning blend houses, and quality assurance directors at California quick-service restaurant commissaries contributed operational data. Bottom-up capacity tallies triangulated against top-down consumption estimates from customs records and food service distributor shipment manifests.
Historical trendline analysis of dehydration capacity additions and fresh onion harvest yields anchored projection modeling across the analysis window. Segmentation dimensions included product type, end-user channel, packaging format, and distribution pathway. CAGRs derived from equipment investment pipelines and chain restaurant standardization timelines. Forecast inputs incorporated FSSAI certification velocity and REACH chemical registration compliance progression.
Inputs from dehydration equipment manufacturers and port authority shipping records were available through the study window; gaps in small-scale processor financial disclosures introduce uncertainty bands around consolidation timing. Forecasts reflect documented assumptions about regulatory enforcement intensity and climate variability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Japan Fresh Fruits Market
Fruits and Vegetables
US Vegetable Puree Market
Fruits and Vegetables
Europe Blueberry Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Cranberries Market
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Global Dried Apricots Market
Fruits and Vegetables
Boysenberry Market
Fruits and Vegetables
Jackfruit Market
Fruits and Vegetables
Yellow Oyster Mushroom Market
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
Global Gooseberry Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market