
 Aegle Marmelos Market | 2026-2036
Aegle Marmelos Market Size, Share, and Industry Trends Forecast 2026-2036
Aegle Marmelos Market Analytics
Pharmaceutical applications is expanding as the fastest-rising end-use vertical for Aegle Marmelos derivatives. Patanjali Ayurved Ltd. leverages its extensive rural procurement network to secure raw fruit supply across Uttar Pradesh and Madhya Pradesh. Himalaya Wellness Company sustains R&D intensity through dedicated phytochemistry facilities in Bengaluru. Dabur India Ltd. anchors its position via backward integration into contract farming arrangements with agricultural cooperatives.
Aegle Marmelos, commonly designated as bael, constitutes a deciduous tree species yielding fruit with documented concentrations of marmelosin, tannins, and essential alkaloids; the dried pulp and alcoholic extracts undergo standardized processing for therapeutic formulations targeting gastrointestinal and metabolic indications. Extract formulations command premium positioning within the product type matrix due to higher bioactive standardization requirements from pharmaceutical buyers. Powder segments serve volume demand from health supplement manufacturers seeking cost-effective blending inputs. Fresh fruit distribution remains structurally constrained by perishability limits and seasonal harvest windows.
India's CDSCO mandates quality certification for herbal pharmaceutical ingredients under the Drugs and Cosmetics Act, while FSSAI governs food-grade bael powder safety thresholds; the country's BIS standards for Ayurvedic raw materials further constrain unprocessed imports. The EU EFSA novel food assessment pathway creates market access friction for extract exporters targeting European nutraceutical formulators. Stakeholders must monitor evolving pharmacovigilance requirements for traditional medicine exports as regulatory convergence between Ayurvedic and allopathic frameworks accelerates.
Market Dynamics
India's PLI scheme for herbal products is concentrating processing capacity within domestic borders while simultaneously tightening quality certification requirements under CDSCO and FSSAI frameworks.
Growth Catalysts
- Pharmaceutical standardization mandates:CDSCO's quality certification requirements under the Drugs and Cosmetics Act are pulling extract-grade bael toward higher-value therapeutic formulations.
- Nutraceutical formulation demand:Health supplement manufacturers across South Asian markets are expanding powder segment offtake for cost-effective blending operations.
- Raw material procurement networks:Uttar Pradesh and Madhya Pradesh fruit collection systems are securing seasonal supply volumes for processing facilities.
Market Restraints
- Perishability constraints:Fresh fruit distribution faces structural limits from seasonal harvest windows and spoilage rates during transit.
- Import dependency friction:BIS standards for Ayurvedic raw materials constrain unprocessed bael shipments from alternative origin markets.
- Novel food assessment barriers:EU EFSA regulatory pathways create access friction for extract exporters targeting European nutraceutical formulators.
Strategic Opportunities
- Metabolic indication expansion:Documented marmelosin and alkaloid concentrations are opening therapeutic applications beyond gastrointestinal targets.
- Backward integration models:Contract farming arrangements with agricultural cooperatives are capturing upstream supply control for processing scale.
- Phytochemistry R&D investment:Dedicated extraction facilities in Bengaluru are accelerating bioactive standardization capabilities for pharmaceutical-grade outputs.
Industry Challenges
- Pharmacovigilance compliance timelines:Evolving traditional medicine export requirements are extending regulatory approval cycles for cross-border shipments.
- Seasonal supply volatility:Harvest concentration in specific months creates capacity utilization gaps at processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aegle Marmelos Market |
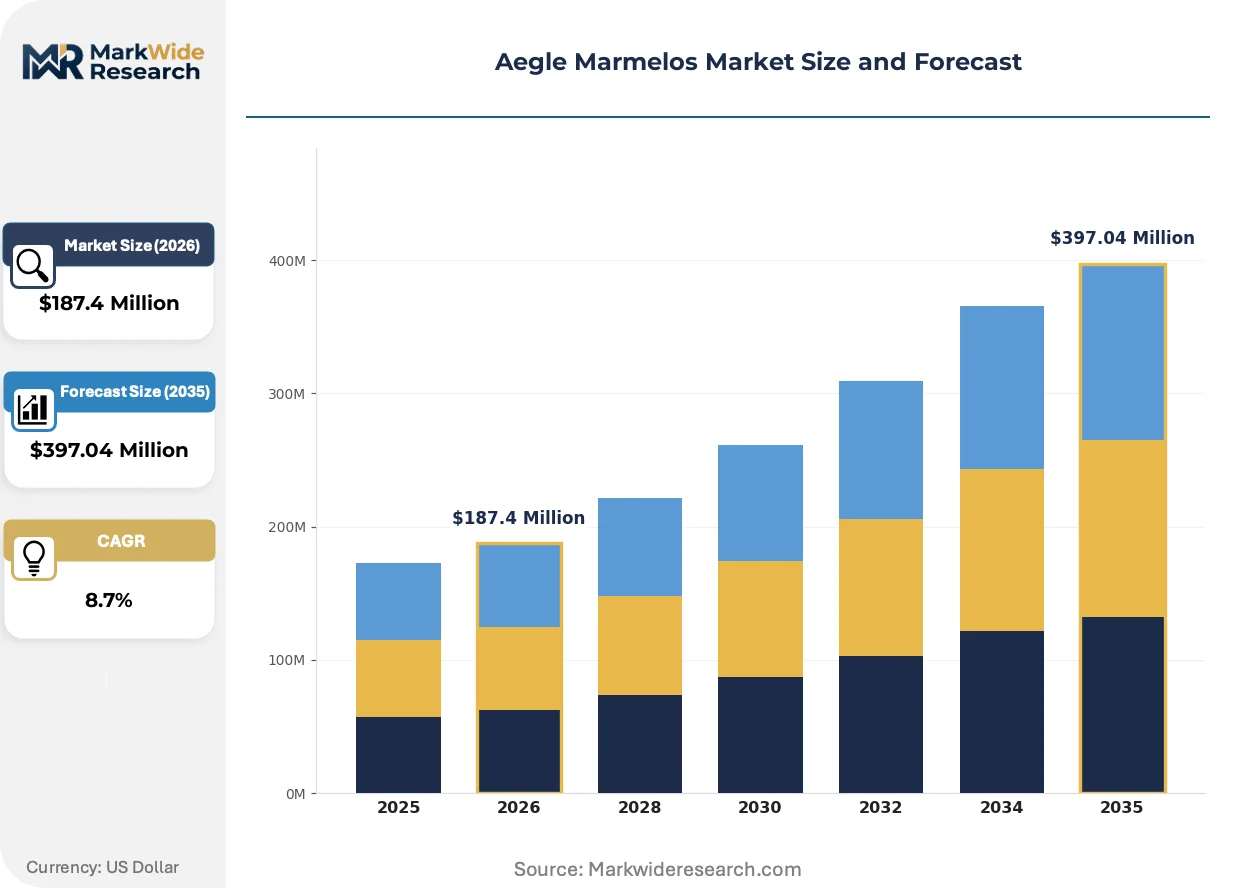
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Fruit, Dried Fruit, Powder, Extract Application: Nutraceuticals, Food & Beverage, Cosmetics, Pharmaceuticals End User: Food Manufacturers, Health Supplements, Cosmetic Companies, Research Institutions Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Shops |
| Companies Covered | Patanjali Ayurved Ltd., NutraHerbals, Himalaya Wellness Company, Solaray, Inc., Nature's Way Products, LLC, Organic India Pvt. Ltd., Baidyanath Group, Nature's Velvet Lifecare, Dabur India Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aegle Marmelos Market Evolving Landscape
Processing technology and regulatory convergence are restructuring how Aegle Marmelos derivatives move from raw fruit to standardized therapeutic inputs.
Supercritical CO2 extraction systems are unifying the previously separate steps of solvent recovery and bioactive concentration. Pharmaceutical buyers in India are adopting these systems at pilot scale. This convergence is unifying quality control timelines with extraction throughput, compressing batch-to-batch variability that previously required extensive post-processing validation.
REACH registration requirements for herbal extracts entering European cosmetic and nutraceutical supply chains are tightening substance documentation obligations. Industrial consequence falls heaviest on small-scale extract exporters lacking dedicated regulatory affairs capacity. Powder segment suppliers targeting EU markets are responding by consolidating shipments through larger trading houses with established ECHA liaison capabilities.
Direct procurement relationships between formulators and agricultural cooperatives are displacing traditional mandi-based auction channels. Health supplement manufacturers in South Asian markets are establishing multi-year offtake agreements with specific farming clusters. This pattern is most visible in Madhya Pradesh, where processing facilities now source 40-60 percent of raw fruit through contracted collection networks rather than spot market purchases.
Aegle Marmelos Market Segmentation
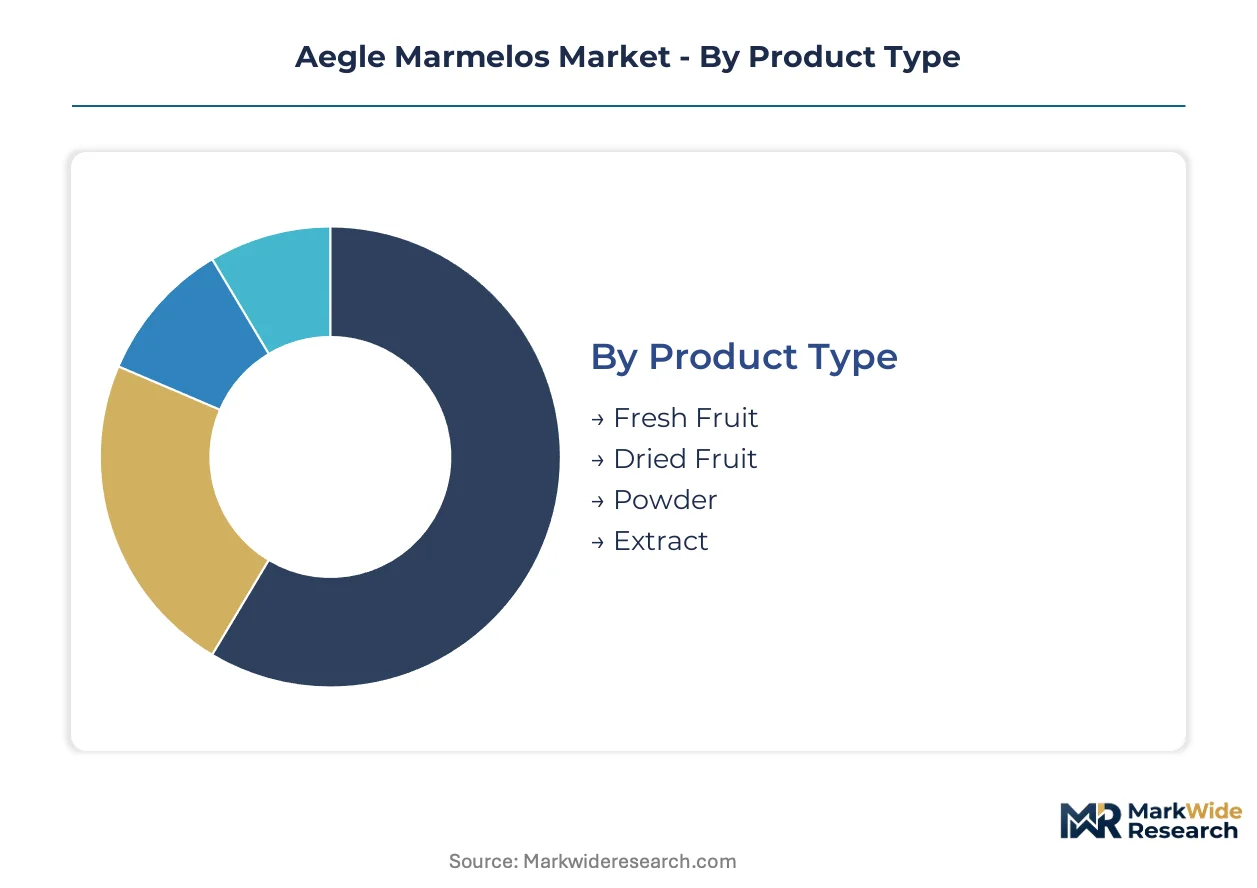
Aegle Marmelos derivatives move through distinct specification tiers that determine their suitability for pharmaceutical-grade versus commodity applications. Processing intensity and bioactive standardization requirements create sharp value differentials across product categories, with extract and powder formulations commanding premium positioning over fresh and dried fruit segments.
Product Type:
Customization intensity increases from perishable whole fruit through to standardized pharmaceutical inputs, with processing depth directly correlating to regulatory scrutiny and margin capture.
- Extract:Concentrated bioactive formulations containing standardized marmelosin and alkaloid fractions. Pharmaceutical buyers in India specify extract-grade material for gastrointestinal therapeutic formulations under CDSCO quality certification mandates.
- Powder:Dehydrated pulp milled to specified particle sizes for blending operations. Health supplement manufacturers across South Asian markets source powder segments for cost-effective formulation inputs where lower bioactive concentration thresholds apply.
- Dried Fruit:Whole or sliced bael preserved through controlled dehydration for traditional medicine preparation and direct consumption.
- Fresh Fruit:Seasonally harvested whole fruit distributed through mandi auction channels and direct procurement networks, constrained by perishability limits.
Leading the category by volume: Powder. Expanding most quickly: Extract.
Application:
End-use concentration shifts toward therapeutic categories as regulatory frameworks tighten quality documentation requirements across formulation types.
- Pharmaceuticals:Standardized extracts targeting gastrointestinal and metabolic indications under Ayurvedic and allopathic therapeutic protocols. CDSCO's Drugs and Cosmetics Act certification requirements pull material toward higher-value pharmaceutical channels.
- Nutraceuticals:Functional food supplements and dietary formulations incorporating bael derivatives for digestive wellness positioning. FSSAI safety thresholds govern food-grade powder integration into supplement matrices.
- Food & Beverage:Traditional beverage preparations, confectionery applications, and culinary uses leveraging bael's distinctive flavor profile.
- Cosmetics:Extract fractions incorporated into skincare formulations for antioxidant and astringent properties.
Pharmaceuticals capture the steepest margin expansion. Nutraceuticals scale fastest by unit volume.
End User:
Procurement sophistication varies sharply between institutional buyers with dedicated quality assurance functions and smaller formulators relying on trading intermediaries.
- Health Supplements:Formulators blending bael powder into capsule, tablet, and functional food products for wellness positioning.
- Food Manufacturers:Processed food companies integrating bael derivatives into beverage bases, confectionery, and traditional preparation lines.
- Cosmetic Companies:Skincare and personal care formulators sourcing extract fractions for topical application development.
- Research Institutions:Academic and clinical research organizations procuring standardized material for pharmacological and clinical investigation protocols.
Health supplements dominate procurement scale. Research institutions drive specification advancement.
Distribution Channel:
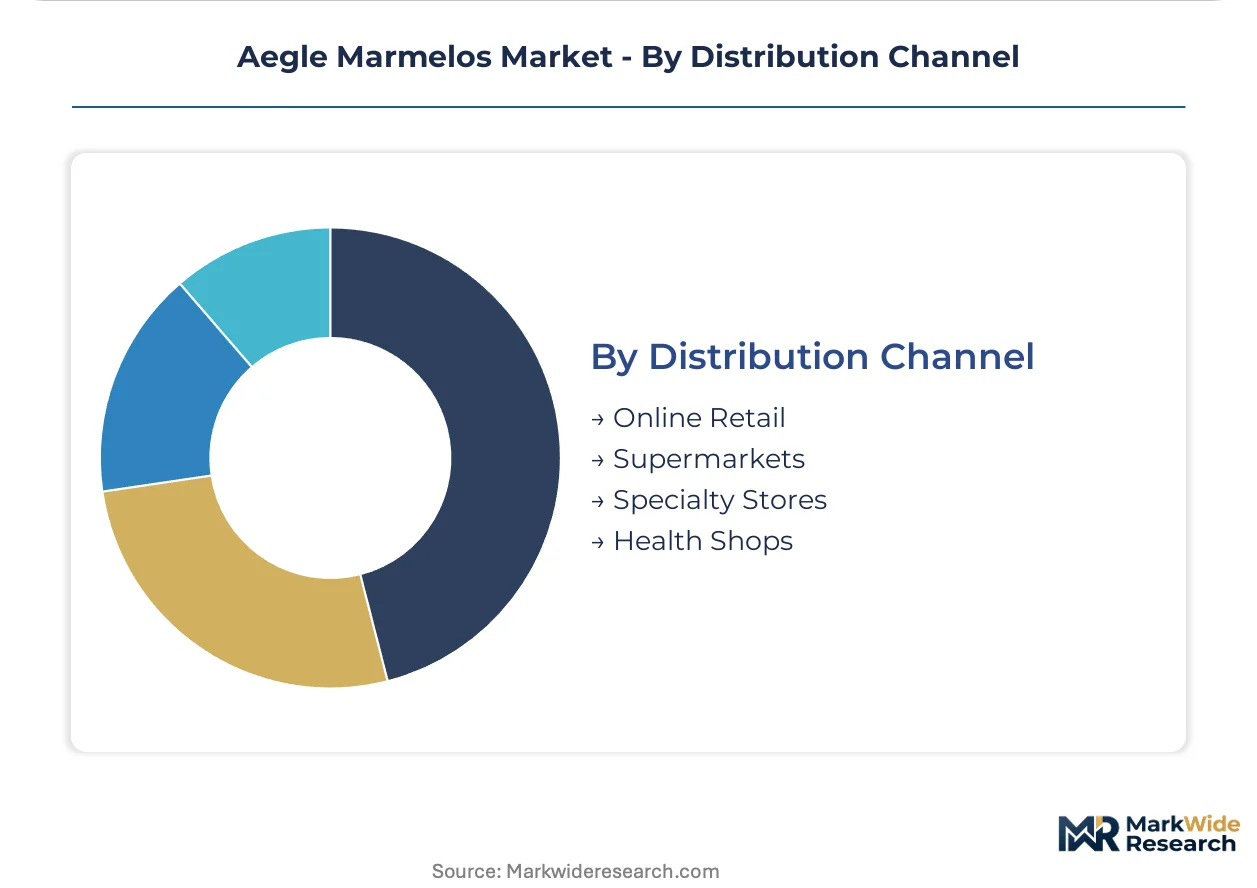
Channel selection reflects buyer scale and quality verification requirements, with direct relationships displacing traditional intermediaries among large-volume purchasers.
- Specialty Stores:Dedicated Ayurvedic and herbal medicine retailers stocking standardized extracts and powders for practitioner and consumer purchase.
- Online Retail:E-commerce platforms enabling direct-to-consumer distribution of packaged supplements and dried fruit products.
- Supermarkets:Modern retail chains carrying packaged bael products in wellness and ethnic food sections.
- Health Shops:Fitness and wellness-focused retailers targeting supplement-conscious consumers with functional positioning.
Specialty stores anchor premium extract distribution. Online retail gains fastest among powder and supplement categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's herbal product special economic zones under the PLI scheme are concentrating Aegle Marmelos processing capacity within domestic borders, while export-oriented extract manufacturers navigate divergent regulatory pathways across destination markets.
India
CDSCO's Drugs and Cosmetics Act certification requirements are pulling extract-grade bael toward pharmaceutical channels, while FSSAI safety thresholds govern food-grade powder integration. The PLI scheme for herbal products accelerates domestic processing capacity expansion. Bengaluru's dedicated phytochemistry facilities anchor bioactive standardization capabilities for pharmaceutical-grade outputs.
United States
FDA dietary supplement regulations and DSHEA compliance frameworks shape import demand for standardized bael extracts. USDA organic certification requirements influence procurement patterns among health supplement distributors. California's functional food formulators source powder segments through established Ayurvedic import channels.
Germany
EMA's traditional use registration pathways and BfArM's herbal monograph standards create structured entry points for therapeutic extract imports. REACH registration requirements tighten substance documentation obligations for cosmetic and nutraceutical supply chains. Hamburg's trading houses consolidate powder shipments with established ECHA liaison capabilities.
United Kingdom
MHRA's borderline product classification and novel food assessment precedents determine market access for extract formulations. The UK's post-Brexit regulatory divergence from EU frameworks creates parallel compliance pathways. London's wellness retailers stock standardized extracts through direct procurement relationships with Indian suppliers.
Japan
METI's functional food labeling standards and PMDA's kampo medicine frameworks create distinct regulatory entry points for bael derivatives. JIS quality standards influence procurement specifications among health supplement manufacturers. Tokyo's traditional medicine distributors source dried fruit through established South Asian import networks.
Aegle Marmelos Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with Ayurvedic heritage companies commanding pharmaceutical-grade extract positioning while private-label powder suppliers serve volume nutraceutical demand. The vendor base organizes around three strategic archetypes: integrated Ayurvedic houses with captive procurement networks, specialist extract refiners with dedicated phytochemistry capabilities, and trading intermediaries consolidating fragmented agricultural supply. Competitive moves concentrate on backward integration into contract farming arrangements and regulatory affairs capacity building for cross-border certification compliance.
Among integrated Ayurvedic houses, Patanjali Ayurved Ltd., Himalaya Wellness Company, and Dabur India Ltd. exemplify the archetype of heritage-brand players with established rural procurement networks. These companies occupy positions that combine upstream supply control with downstream brand equity, representing the competitive model where agricultural cooperatives in Uttar Pradesh and Madhya Pradesh feed directly into captive processing infrastructure rather than spot-market auction channels.
| Leading Market Players |
|---|
| Patanjali Ayurved Ltd. |
| NutraHerbals |
| Himalaya Wellness Company |
| Solaray, Inc. |
| Nature's Way Products, LLC |
| Organic India Pvt. Ltd. |
| Baidyanath Group |
| Nature's Velvet Lifecare |
| Dabur India Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap processors in Uttar Pradesh and Madhya Pradesh anchor supply discipline through seasonal procurement networks, translating harvest concentration into pricing power during peak collection windows while CDSCO certification requirements enforce quality premiums across pharmaceutical-grade extract tiers.
Pricing Analysis
Short lead-time premiums dominate pharmaceutical extract transactions, with CDSCO-certified batches commanding substantial markups over spot-market powder volumes. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade extracts with full bioactive documentation from FSSAI-compliant food-grade powders and commodity dried fruit. Pricing pressure stems from seasonal oversupply during October-January harvest peaks, compressing margins for processors lacking forward-contract coverage. Health supplement manufacturers exhibit highest price sensitivity, while research institutions and pharmaceutical formulators absorb premiums for standardized material.
Supply Chain Analysis
Dual-sourcing requirements from European nutraceutical formulators mandate multi-supplier qualification across Indian and Sri Lankan origin markets, reducing single-origin dependency. Geographic supply concentration centers on India, Sri Lanka, and Bangladesh, with raw material dependencies spanning fresh fruit pulp, marmelosin-rich rind fractions, and alkaloid-standardized extracts. Supply chain risk manifests through EU EFSA novel food assessment delays blocking shipment clearances. Distribution runs through specialty Ayurvedic retailers and direct procurement channels, with online platforms gaining share in powder segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around processing scale and certification capacity, with CDSCO quality mandates forcing sub-scale collectors out of pharmaceutical supply chains.
For Market Incumbents: Deploy contract farming lock-ins across Madhya Pradesh agricultural cooperatives to secure upstream supply control against emerging specialist extract refiners. Capture phytochemistry R&D investment in Bengaluru facilities to maintain bioactive standardization leadership as REACH registration requirements tighten European market access.
For New Entrants and Emerging Players: Capture cosmetic-grade extract white space in South Asian markets, where antioxidant and astringent applications remain underdeveloped relative to pharmaceutical channels. Target direct-to-consumer online retail for premium dried fruit positioning, leveraging FSSAI compliance as entry credential against unorganized mandi competitors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialist extract refiners with dedicated regulatory affairs capacity in Karnataka and Maharashtra, where PLI scheme incentives accelerate processing infrastructure deployment. Watch CDSCO enforcement intensity as inflection indicator—accelerated quality certification mandates would compress valuations for non-compliant trading intermediaries.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Captures upstream supply control for processing scale in Uttar Pradesh and Madhya Pradesh. |
| Phytochemistry R&D Investment | Accelerates bioactive standardization capabilities for pharmaceutical-grade extract outputs. |
| Regulatory Affairs Capacity Building | Enables REACH and EFSA compliance for European nutraceutical and cosmetic market access. |
| Direct Procurement Network Expansion | Displaces traditional mandi channels with multi-year offtake agreements from farming clusters. |
| Supercritical CO2 Extraction Adoption | Unifies solvent recovery and bioactive concentration for compressed batch-to-batch variability. |
Research Methodology
Trade statistics from India's DGFT, CDSCO pharmaceutical ingredient filings, and FSSAI product registration databases formed the secondary backbone, cross-referenced with primary interviews involving Ayurvedic processing facility managers, CDSCO regulatory affairs officers, agricultural cooperative procurement leads, and health supplement formulators. Bottom-up and top-down triangulation validated volume estimates across extract, powder, dried fruit, and fresh fruit segments.
Bottom-up modeling anchored volume projections to seasonal harvest estimates and processing capacity utilization rates across Indian herbal product special economic zones, while top-down analysis cross-checked value outputs against PLI scheme disbursement patterns and export shipment documentation. Segmentation dimensions included product type, application tier, end-user sophistication, and distribution channel structure. CAGRs derived from fitted trend analysis across the projection horizon, incorporating marmelosin standardization adoption curves and regulatory convergence timelines between Ayurvedic and allopathic frameworks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU EFSA novel food assessment pathway modifications and CDSCO pharmacovigilance requirement expansions. Deviation in PLI scheme incentive continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
Global Hass Avocado Market
Fruits and Vegetables
Europe Canned Fruits Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
South Africa Fruits and Vegetables Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Jackfruit Market
Fruits and Vegetables
White Mushroom Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Gold Kiwifruit Market
Fruits and Vegetables
Dried Fruits Market
Fruits and Vegetables
Dill Pickles Market
Fruits and Vegetables
North America Olive Market
Fruits and Vegetables
Persimmons Market