
 Copper Chemicals Market | 2026-2036
Copper Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Chemicals Market Analysis
Agricultural fungicide demand is repositioning copper chemicals consumption as growers shift from legacy sulfur formulations. BHP leverages its integrated mining assets to secure concentrate supply for sulfate producers across the Pacific basin. Aurubis AG anchors European refining capacity, converting complex concentrates into high-purity copper salts for specialized applications. Freeport-McMoRan dominates North American feedstock supply, extending its reach into technical-grade chemical intermediates.
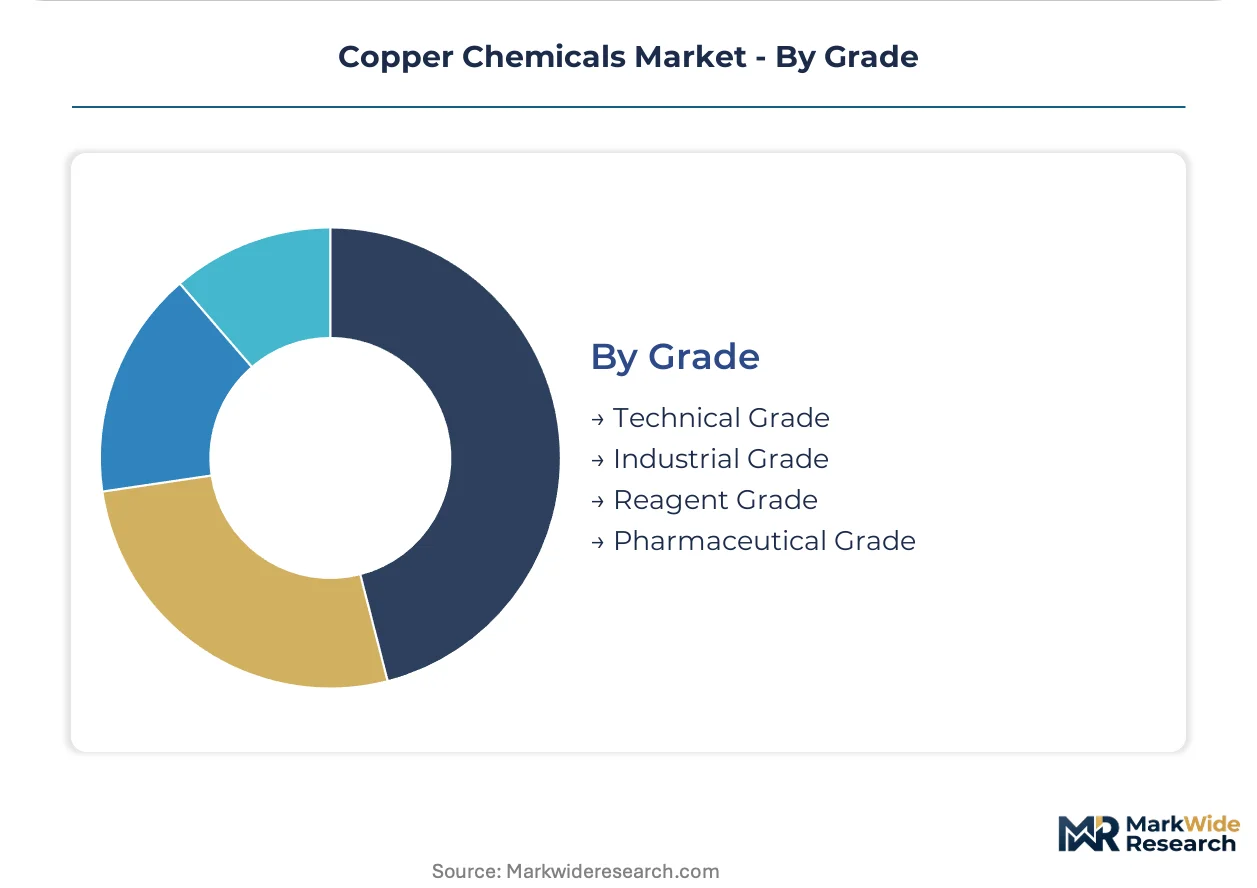
Copper chemicals encompass inorganic and organic compounds derived from copper metal or ore, typically formulated as sulfates, chlorides, nitrates, or acetates with purity grades ranging from technical to reagent levels; these compounds function primarily as biocides, catalyst precursors, and electroplating bath constituents across industrial processes. Copper sulfate leads product-type revenue due to its entrenched role in agriculture and water treatment, while copper chloride exhibits faster trajectory in printed circuit board fabrication. Industrial grade commands the largest volume share among grade tiers, though reagent grade captures disproportionate margin pools from semiconductor and pharmaceutical quality requirements.
EPA registration requirements under FIFRA govern agricultural copper formulations in the United States, while REACH and the EU Green Deal restrict heavy-metal discharge thresholds for European water-treatment applications. China's MEE enforces stricter effluent standards on electroplating facilities, elevating demand for closed-loop copper recovery systems. India's CEA mandates cleaner production protocols for chemical clusters, redirecting capital toward upgraded sulfate crystallization infrastructure. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging purity and environmental compliance thresholds.
Market Dynamics
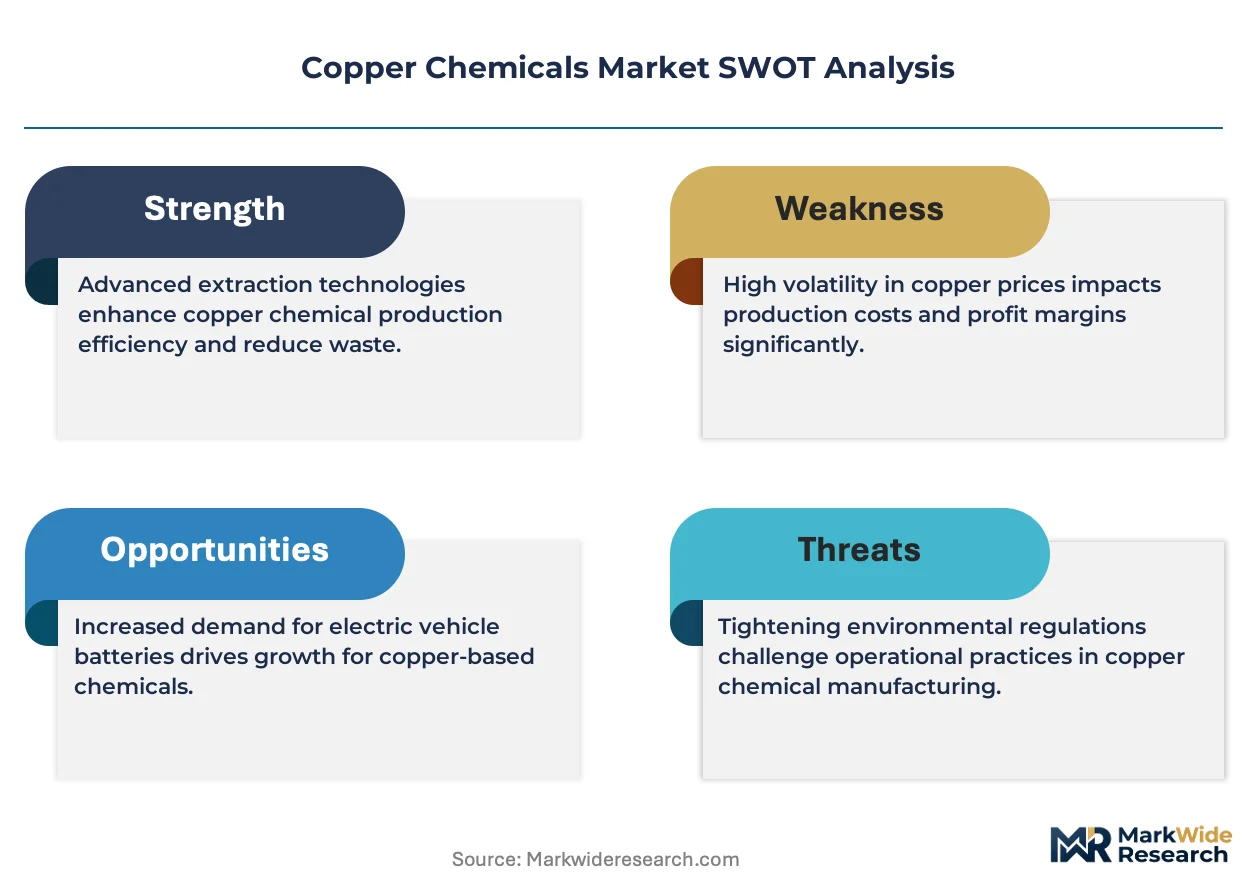
REACH compliance in Europe and China's MEE effluent rules are compressing formulation margins while redirecting capital toward closed-loop recovery systems and higher-purity grades. This regulatory divergence is fragmenting product specifications across jurisdictions.
Growth Catalysts
- Agrochemical corridor expansion:India's CEA cleaner production protocols are accelerating sulfate crystallization upgrades in Gujarat and Maharashtra chemical clusters.
- REACH heavy-metal thresholds:European water-treatment operators are upgrading to reagent-grade copper salts to meet EU Green Deal discharge restrictions.
- Soybean belt fungicide transition:Brazilian growers are displacing legacy sulfur formulations with copper-based biocides across Mato Grosso and Paraná.
Market Restraints
- Concentrate supply concentration:Pacific basin mining consolidation limits feedstock flexibility for sulfate producers dependent on complex ore blends.
- Substitution pressure from synthetic fungicides:Novel SDHI chemistry is capturing share in high-value Brazilian soybean applications.
- Energy cost volatility:Electrolytic refining and crystallization operations face margin compression from natural gas and electricity price swings.
Strategic Opportunities
- Semiconductor plating chemistry:Reagent-grade copper chloride demand is accelerating from advanced packaging substrate fabrication in Taiwan and South Korea.
- Closed-loop recovery mandates:China's MEE electroplating effluent rules are creating service-contract opportunities for on-site copper regeneration systems.
- Pharmaceutical catalyst precursors:Copper acetate specifications for API synthesis remain underpenetrated versus palladium alternatives in Indian manufacturing.
Industry Challenges
- Cross-jurisdiction formulation complexity:Producers must maintain parallel product lines to satisfy diverging EPA FIFRA, REACH, and MEE purity thresholds.
- Crystallization infrastructure capex:Upgrading technical-grade capacity to semiconductor-qualified reagent grades requires multi-year capital commitments.
- Specialized analytical talent scarcity:ICP-MS trace-metal certification and QA protocols demand skill sets concentrated in pharmaceutical and electronics sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Chemicals Market |
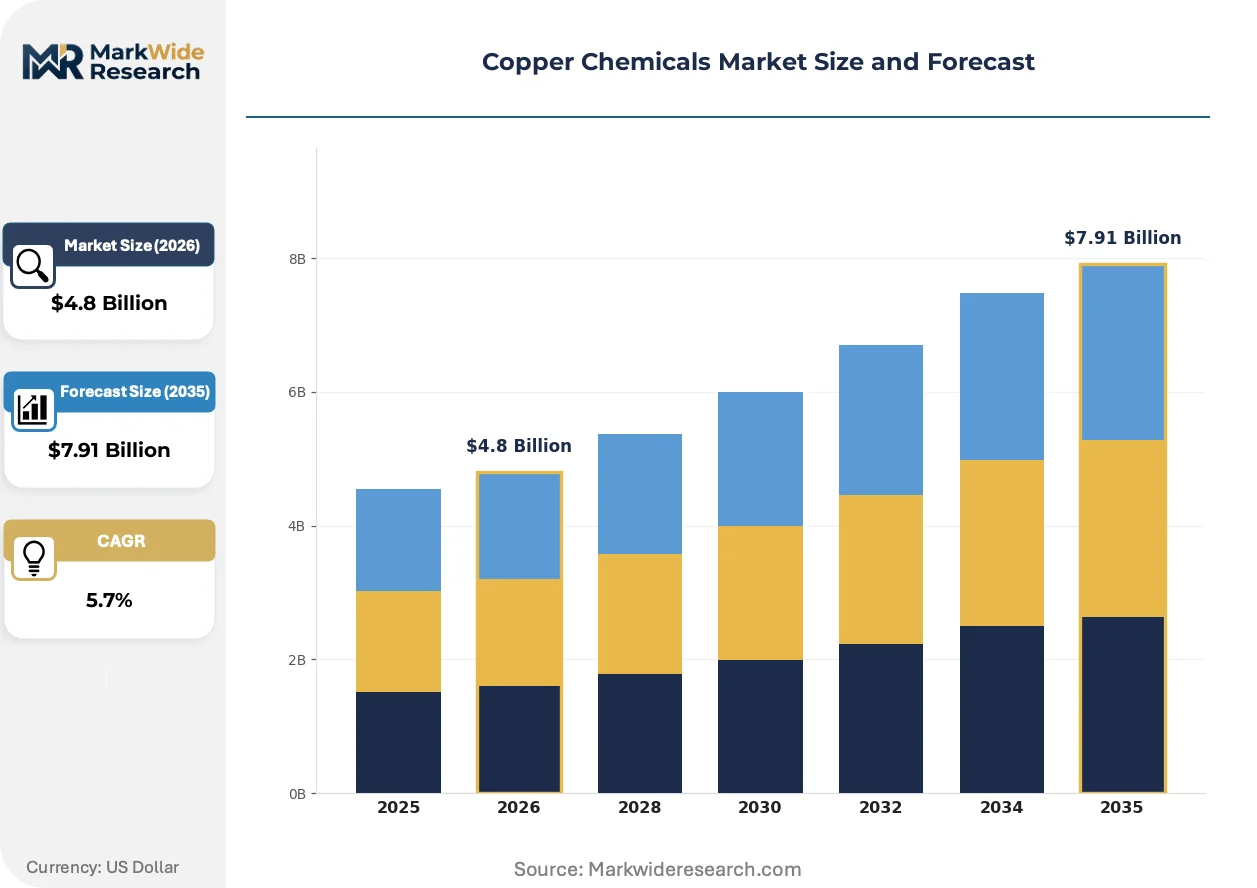
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Sulfate, Copper Chloride, Copper Nitrate, Copper Acetate Application: Agriculture, Water Treatment, Electronics, Construction End User: Pesticide Manufacturers, Chemical Industries, Mining Companies, Electrical Manufacturers Grade: Technical Grade, Industrial Grade, Reagent Grade, Pharmaceutical Grade |
| Companies Covered | Mueller Industries, BHP, Aurubis AG, Freeport-McMoRan, Rio Tinto, Chungco Group, Xiamen Honglu Group, KGHM Polska Miedz, KME, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Chemicals Market Emerging Trajectories
Electrochemical recovery technologies and precision agriculture dosing systems are compressing traditional supply chains while elevating purity requirements across copper chemical applications.
Membrane electrowinning for spent etchant regeneration is decentralizing copper recovery from centralized smelters to printed circuit board fabrication facilities. Taiwan and South Korean substrate manufacturers are adopting modular units to reduce logistics exposure and meet closed-loop mandates. This distributed model is compressing toll-refining margins while locking in captive chemical supply.
REACH authorization清单 additions for heavy-metal compounds are forcing European water-treatment operators toward certified low-impurity sulfate grades. The EU Green Deal's zero-pollution ambition is accelerating substitution timelines for legacy technical-grade formulations. Municipal utilities in Germany and the Netherlands are now requiring third-party ECHA-compliant certification for all copper biocide tenders.
Variable-rate fungicide application via drone-mounted sensors is displacing blanket spraying across Brazil's soybean belt. Mato Grosso cooperatives are contracting precision-agriculture service providers to optimize copper hydroxide dosing by canopy density maps. This consumption-pattern shift is concentrating offtake through integrated agritech platforms rather than traditional distributor networks.
Copper Chemicals Market Segmentation
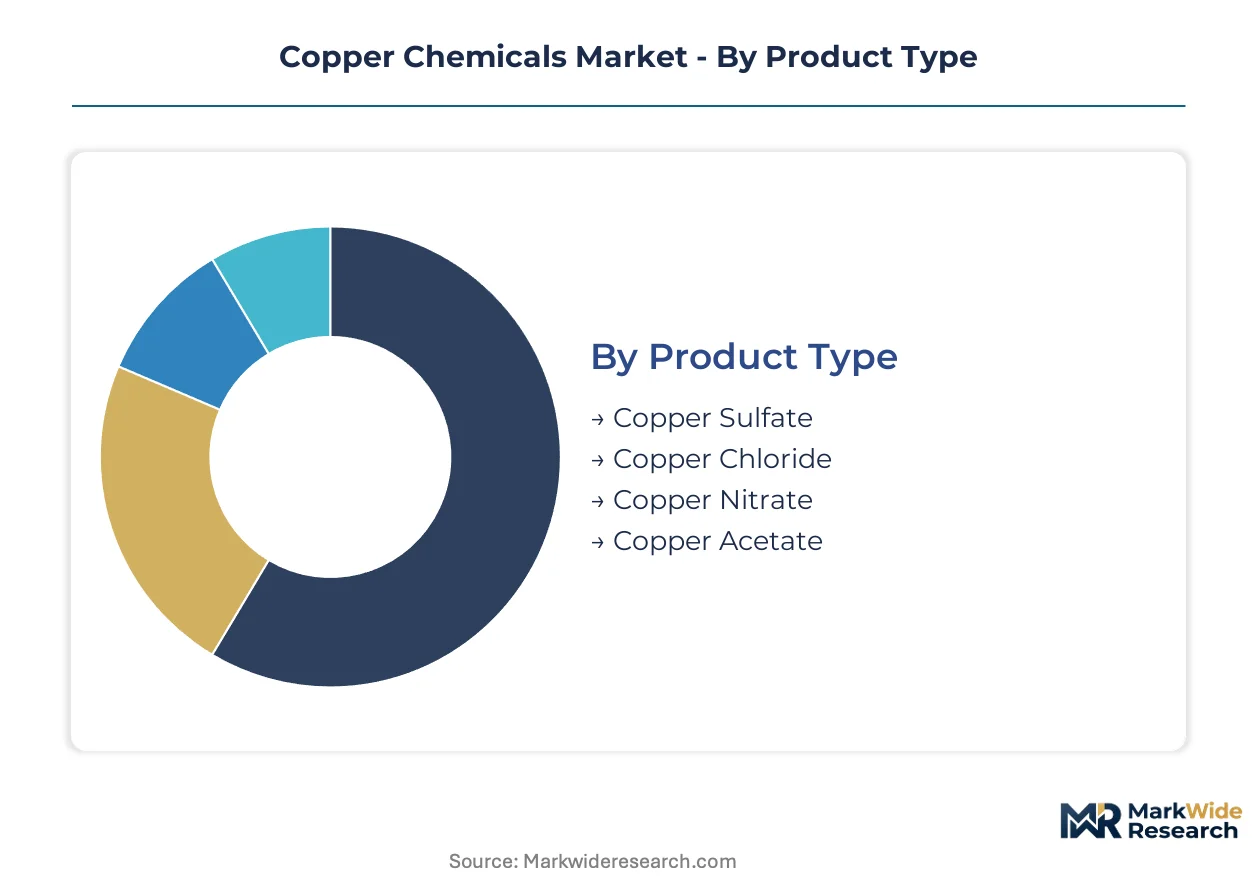
Copper chemicals fragment across purity thresholds and end-use specifications that dictate pricing power and regulatory burden. Buyers in agriculture prioritize cost-efficient technical grades, while semiconductor and pharmaceutical customers demand trace-metal certification that locks in supplier relationships.
Product Type:
Formulation chemistry determines thermal stability, solubility profiles, and compatibility with downstream process conditions.
- Copper Sulfate:Pentahydrate and monohydrate crystalline forms dominate agricultural fungicide and algaecide formulations. Brazilian soybean cooperatives in Mato Grosso anchor agricultural offtake, though water-treatment utilities in Germany and the Netherlands are upgrading to certified low-impurity grades under EU Green Deal procurement rules.
- Copper Chloride:Anhydrous and dihydrate variants serve as electroplating bath constituents and catalyst precursors. Taiwan and South Korean substrate manufacturers are accelerating reagent-grade demand from advanced packaging fabrication, with membrane electrowinning systems enabling closed-loop regeneration at PCB facilities.
- Copper Nitrate:Highly soluble salt used in specialty ceramic pigments and metal surface treatment solutions.
- Copper Acetate:Organic salt employed as catalyst precursor in pharmaceutical API synthesis and wood preservative formulations.
Volume sits with copper sulfate; growth tilts toward copper chloride.
Application:
End-use sectors impose divergent purity, documentation, and supply-security requirements that reshape procurement patterns.
- Agriculture:Fungicide and bactericide formulations for crop protection and livestock footbath applications. India's CEA cleaner production protocols are redirecting capital toward upgraded crystallization infrastructure in Gujarat and Maharashtra chemical clusters.
- Electronics:Printed circuit board fabrication, semiconductor plating chemistry, and battery electrode materials. China's MEE effluent mandates are compressing toll-refining margins while elevating demand for on-site copper recovery systems.
- Water Treatment:Algaecide and molluscicide applications in municipal reservoirs and industrial cooling systems.
- Construction:Wood preservative treatments and antifouling marine coatings.
Revenue concentrates in electronics; agricultural volume expands most quickly from Brazil's fungicide transition.
End User:
Customer scale and integration depth determine whether procurement favors spot-market flexibility or captive supply arrangements.
- Pesticide Manufacturers:Formulators of copper-based biocides for agricultural and consumer markets. EPA FIFRA registration requirements govern US product approvals, while REACH authorization清单 additions redirect European portfolios toward certified grades.
- Chemical Industries:Diversified producers of catalysts, pigments, and specialty intermediates.
- Mining Companies:Operators employing copper chemicals in flotation reagents and metallurgical processes.
- Electrical Manufacturers:Producers of wire, cable, and electronic components requiring electroplating chemistry.
Procurement scale favors chemical industries; specification intensity peaks with electrical manufacturers.
Grade:
Purity certification tiers separate commodity volume from premium-margin specialty positions.
- Technical Grade:Basic purity suitable for agriculture and industrial applications with minimal analytical documentation. REACH heavy-metal thresholds and China's MEE effluent rules are compressing margins while redirecting capital toward closed-loop recovery infrastructure.
- Reagent Grade:High-purity specifications with ICP-MS trace-metal certification for semiconductor and pharmaceutical applications. Taiwan and South Korean substrate manufacturers are locking in supplier relationships through multi-year qualification protocols.
- Industrial Grade:Intermediate purity for electroplating, catalyst production, and general chemical synthesis.
- Pharmaceutical Grade:cGMP-compliant specifications for API synthesis and excipient applications.
Volume concentrates in technical grade; margin expansion follows reagent grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mining concentration in Chile and Australia supplies raw concentrate, while manufacturing demand clusters in East Asian electronics corridors and South American agricultural zones. This geographic split shapes trade flows and regulatory compliance costs.
China
Electronics manufacturing in the Yangtze River Delta and Pearl River Delta consumes copper chloride for printed circuit board fabrication. MEE effluent regulations are forcing electroplating facilities toward closed-loop recovery systems. Shenzhen and Suzhou chemical parks are retrofitting crystallization infrastructure to meet semiconductor-grade purity thresholds.
Brazil
Soybean cooperatives in Mato Grosso and Paraná are displacing sulfur fungicides with copper hydroxide formulations. ANVISA pesticide registration requirements govern biocide approvals for agricultural applications. Precision agriculture platforms in the Cerrado belt are consolidating chemical procurement through drone-based dosing contracts.
Germany
Water-treatment utilities in the Rhine-Ruhr corridor are upgrading to reagent-grade copper sulfate under EU Green Deal procurement rules. ECHA REACH authorizationリスト additions restrict heavy-metal discharge thresholds. Municipal operators in Bavaria and North Rhine-Westphalia now mandate third-party certification for all biocide tenders.
India
Pesticide formulators in Gujarat and Maharashtra are expanding sulfate crystallization capacity for domestic and export markets. CEA cleaner production protocols redirect capital toward upgraded infrastructure. The Mundra and Hazira chemical clusters are capturing agrochemical corridor expansion from soybean belt demand in Latin America.
United States
Electronics plating demand in Texas and Arizona leverages Freeport-McMoRan concentrate supply for technical-grade chemical intermediates. EPA FIFRA registration requirements govern agricultural copper formulations. Phoenix-area semiconductor fabs are qualifying reagent-grade suppliers for advanced packaging substrate fabrication.
Copper Chemicals Market Vendor Landscape
Top-tier vendors anchor mining-integrated supply chains, while mid-tier chemical processors compete on crystallization expertise and regional formulation knowledge. The vendor base stratifies between concentrate owners, toll refiners, and specialty salt producers. Two strategic archetypes dominate: integrated miners extending downstream into chemical intermediates, and independent processors building captive relationships with electronics manufacturers. Competitive moves center on backward integration into concentrate supply and multi-year qualification protocols with semiconductor customers.
Among mining-integrated players, BHP and Freeport-McMoRan exemplify the concentrate-to-chemicals archetype through Pacific basin and North American feedstock control respectively. Aurubis AG occupies a position within European refining capacity, converting complex concentrates into high-purity copper salts. These three entities represent distinct geographic anchors for regional supply security.
| Leading Market Players |
|---|
| Mueller Industries |
| BHP |
| Aurubis AG |
| Freeport-McMoRan |
| Rio Tinto |
| Chungco Group |
| Xiamen Honglu Group |
| KGHM Polska Miedz |
| KME |
| Others |
Supply Flow & Price Mechanics
EU Green Deal zero-pollution mandates gate both qualified supply and premium-tier pricing access, as municipal utilities in Germany and the Netherlands now require ECHA-compliant certification for biocide tenders while electroplating facilities in China face MEE-mandated closed-loop recovery investments that stratify cost structures.
Pricing Analysis
Margin tightening in technical-grade copper sulfate reflects REACH heavy-metal threshold compliance costs and energy price volatility at crystallization facilities. Three-tier pricing structure across reagent, industrial, and technical grades separates semiconductor-qualified suppliers from agricultural formulators. Cost-down pressure on technical grades accelerates because Brazilian soybean cooperatives are optimizing fungicide dosing through precision agriculture platforms. Pesticide manufacturers exhibit highest price sensitivity; semiconductor substrate fabricators in Taiwan and South Korea accept premium reagent-grade premiums for ICP-MS trace-metal certification.
Supply Chain Analysis
Freight cost differentials between Chilean concentrate exports and Asian chemical processing centers are reshoring toll-refining economics toward Pacific basin consolidation. Supply concentrates in Chile, Australia, and Peru for mining feedstock; China, India, and Germany for chemical processing. Raw material dependencies draw from copper concentrate, sulfuric acid, and electrolytic refining capacity. Single-source vulnerability concentrates at Pacific basin mining consolidation points. Distribution runs through integrated agritech platforms in Brazil, toll-refining networks in China, and direct qualification protocols with electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane electrowinning technology is displacing centralized smelter recovery with on-site PCB facility regeneration, compressing traditional toll-refining margins while elevating purity requirements.
For Market Incumbents: Cement multi-year qualification protocols with Taiwan and South Korean substrate manufacturers before novel SDHI synthetic fungicides capture additional Brazilian soybean share. Backward integration into Chilean or Peruvian concentrate supply secures feedstock flexibility against Pacific basin mining consolidation. Investment in semiconductor-grade crystallization infrastructure captures reagent-grade margin expansion as EPA FIFRA and REACH regulatory divergence fragments product lines. For New Entrants and Emerging Players: Direct-to-formulator digital platforms in India's Gujarat and Maharashtra agrochemical corridor bypass established distributor networks. Pharmaceutical-grade copper acetate for API synthesis remains underpenetrated versus palladium alternatives in Indian manufacturing. Target on-site copper regeneration service contracts with Shenzhen and Suzhou electroplating facilities facing MEE effluent mandates. For Investors and Strategic Acquirers: CEA-mandated cleaner production protocol announcements in India are the leading indicator that sulfate crystallization capacity expansion will accelerate. Long-term viability hinges on positioning within reagent-grade qualification pipelines rather than commodity technical-grade exposure. Acquisition targets should exhibit captive relationships with semiconductor packaging substrate fabricators and ECHA certification credentials for EU water-treatment procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Supply | BHP and Freeport-McMoRan feedstock control secures sulfate producer flexibility against Pacific basin consolidation. |
| Semiconductor-Grade Crystallization Investment | Shenzhen and Suzhou chemical parks retrofit infrastructure to meet Taiwan substrate manufacturer purity thresholds. |
| Closed-Loop Recovery Service Contracts | China's MEE electroplating effluent rules create on-site copper regeneration opportunities at PCB fabrication facilities. |
| Precision Agriculture Platform Partnerships | Mato Grosso cooperatives consolidate chemical procurement through drone-based copper hydroxide dosing contracts. |
| ECHA Certification Acquisition | German and Dutch municipal utilities mandate third-party REACH-compliant biocide tenders under EU Green Deal procurement. |
Methodological Framework
Trade statistics from customs databases, SEC 10-K filings from mining-integrated chemical producers, and Cefic sector reports formed the secondary backbone, supplemented by primary interviews with sulfate crystallization plant managers, pesticide formulator procurement leads, and semiconductor substrate fabrication engineers. Bottom-up and top-down triangulation validated volume estimates across grade tiers.
Bottom-up modeling aggregated individual facility capacity and utilization rates while top-down approaches cross-checked against end-use consumption patterns across agriculture, electronics, and water treatment segments. Grade tier, end-use industry, and regional production hub dimensions structured the analytical framework. CAGRs derived from regression analysis against historical price-volume relationships and regulatory implementation timelines. Forecast inputs incorporated MEE effluent rule compliance cost curves and REACH authorization清单 expansion schedules.
Inputs from Chinese electroplating facility operators and Indian CEA compliance officers were available through the study window; gaps in real-time semiconductor substrate manufacturer inventory data introduce uncertainty bands around reagent-grade demand projections. Forecasts reflect documented assumptions regarding regulatory implementation pacing and substitution elasticity between copper-based and synthetic fungicides. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Global Biochemical Reagents Market
Chemical Intermediates
Thioesters Market
Chemical Intermediates
Cytosine Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Penicillin Intermediate Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
Thiochemicals Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
United States Cellulose Acetate Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Palmitoyl Chloride Market