
 Cloud CDN Market | 2026-2036
Cloud CDN Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud CDN Market Analysis
The boundary between premium edge-computing CDN tiers and commodity content delivery is hardening. Akamai Technologies leverages its unmatched edge server footprint to sustain pricing power in latency-sensitive applications. Cloudflare anchors developer-centric workflows with serverless edge logic, while Amazon Web Services competes through tight integration with cloud storage and compute primitives.
Cloud CDN denotes a geographically distributed network of proxy servers and data centers that caches static and dynamic content at edge nodes, typically operating within 10-50 milliseconds of end users to reduce origin server load and improve transfer speeds through TCP/UDP optimization protocols. Video Delivery commands the largest revenue pool among service types due to bit-rate escalation in 4K and live streaming workflows. Multi-Cloud deployment is gaining share fastest as enterprises distribute risk across hyperscaler footprints rather than committing to single-vendor architectures.
FCC net-neutrality rulings in the United States, GDPR data-residency requirements in Europe, and China's MIIT cybersecurity reviews collectively dictate where caching nodes may physically reside and how traffic may traverse national boundaries. ISO 27001 and SOC 2 Type II certifications function as baseline market-access credentials for enterprise procurement committees. Stakeholders must weigh sovereign data requirements against the latency penalties of fragmented infrastructure footprints when selecting provider architectures.
Market Dynamics
Edge computing architectures are compressing the distance between content origin and end-user, forcing CDN providers to densify server footprints within municipal boundaries while navigating divergent data sovereignty regimes.
Growth Catalysts
- 4K and live streaming workflows:Video delivery platforms require sub-50 millisecond latency for real-time interaction, mandating edge node expansion into secondary cities.
- GDPR data-residency requirements:European enterprises must localize caching infrastructure, creating procurement pull for region-bound CDN contracts.
- Multi-cloud deployment patterns:Risk distribution across hyperscaler footprints prevents single-vendor lock-in and sustains infrastructure competition.
Market Restraints
- Energy input cost volatility:Edge data centers face electricity price swings that compress operating margins in markets with carbon-intensive grids.
- Supply concentration in server hardware:Taiwan and South Korea dominate semiconductor fabrication for edge processors, creating geopolitical exposure.
- MIIT cybersecurity review timelines:China's mandatory pre-deployment inspections delay node activation by quarters, fragmenting infrastructure rollout schedules.
Strategic Opportunities
- India data localization mandates:TRAI directives require in-country caching, opening greenfield buildout opportunities for compliant providers.
- Serverless edge logic convergence:WASM runtime integration with CDN edge nodes enables compute-at-edge applications beyond static content delivery.
- ISO 27001 certification arbitrage:Mid-market providers can capture enterprise procurement by accelerating security credential acquisition faster than hyperscalers.
Industry Challenges
- Distributed systems engineering talent scarcity:Edge orchestration requires specialized TCP/UDP optimization expertise that outpaces university pipeline output.
- Legacy origin server integration friction:Enterprises with monolithic application architectures face refactoring costs to exploit edge caching fully.
- SOC 2 Type II audit timelines:Six-to-twelve month certification cycles delay market entry for new entrants targeting regulated verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud CDN Market |
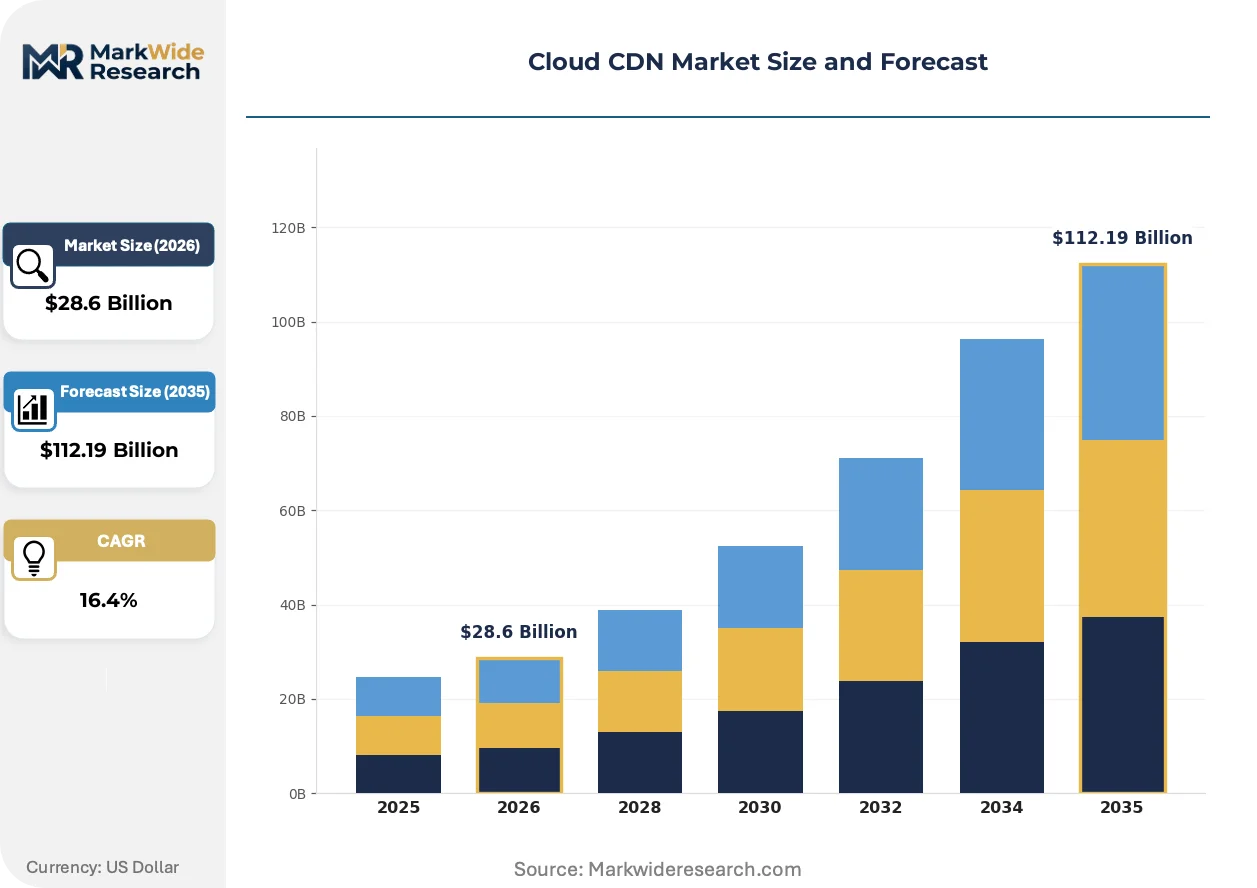
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video Delivery, Web Acceleration, API Acceleration, Image Optimization Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Media Companies, E-Commerce, Gaming Industry, Enterprises Technology: HTTP/2, QUIC, WebSockets, SSL Offloading |
| Companies Covered | Akamai Technologies, Cloudflare, Amazon Web Services, Google Cloud, Microsoft Azure, Fastly, Alibaba Cloud, Edgio, StackPath, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud CDN Market Emerging Trajectories
Latency-sensitive applications are forcing CDN architectures toward compute-enabled edge nodes, blurring the historical boundary between content delivery and cloud processing.
WebAssembly (WASM) runtimes at edge nodes enable lightweight code execution without origin round-trips. Gaming and fintech developers deploy authentication and personalization logic directly to edge POPs. Containerized microservices at the network periphery is overtaking traditional static caching as the primary value proposition for premium CDN tiers.
FCC net-neutrality rulings in the United States restrict paid peering arrangements that previously subsidized infrastructure expansion. Tier-1 ISPs now demand direct settlement for interconnection, raising delivery costs for high-bandwidth video providers. Streaming platforms in North America are responding by building private backbone networks to bypass transit fee inflation.
Enterprise buyers now unbundle CDN procurement from cloud compute contracts, reversing the bundled hyperscaler model of the past decade. Procurement committees evaluate edge performance through synthetic latency benchmarking rather than brand reputation. This behavioral shift is most visible in Germany, where manufacturing firms source CDN independently from AWS or Azure compute commitments.
Cloud CDN Market Segmentation
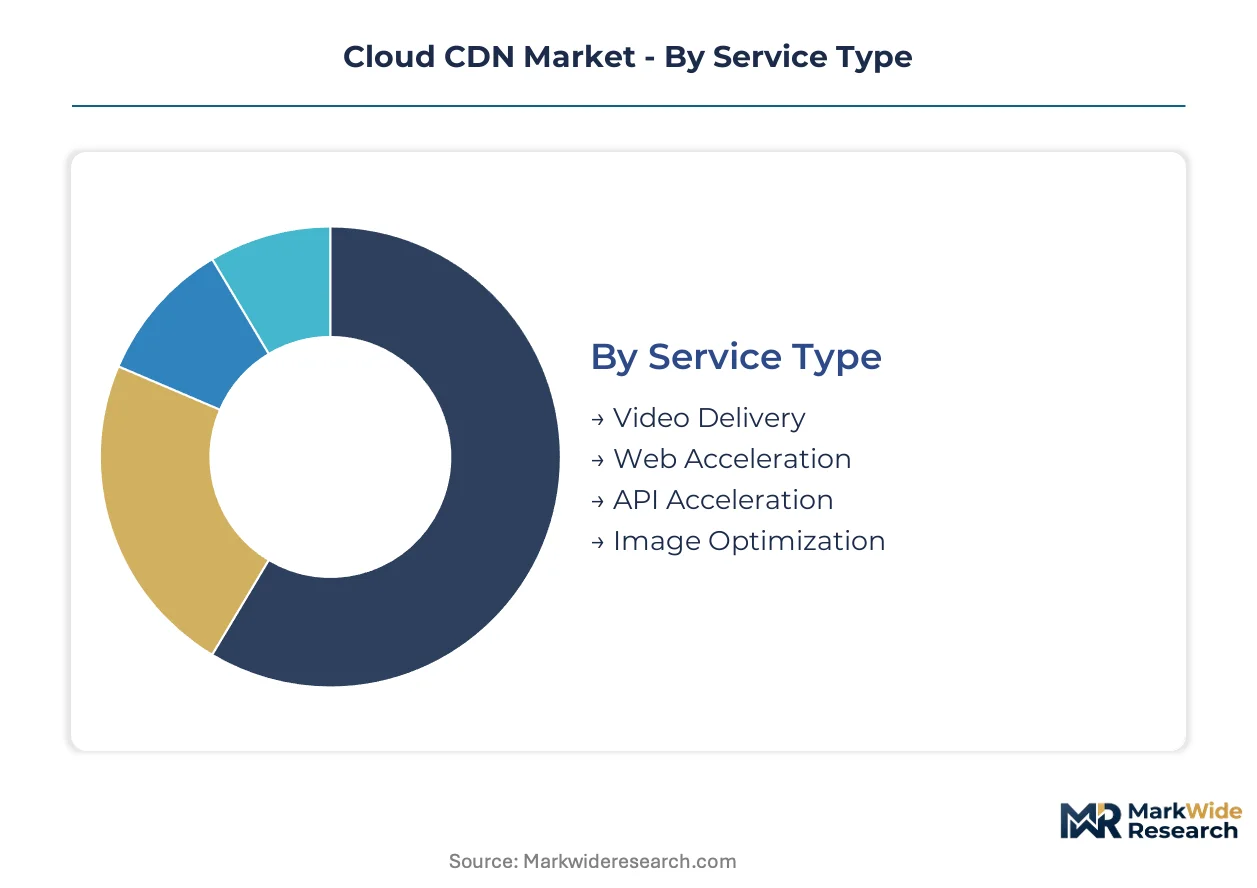
Cloud CDN architectures fragment across multiple technical and commercial dimensions. Procurement committees evaluate segments through latency benchmarks, data sovereignty requirements, and integration complexity with existing cloud footprints.
Service Type:
Protocol optimization and payload characteristics define performance differentiation across service tiers.
- Video Delivery:Bit-rate escalation in 4K and live streaming workflows demands sub-50 millisecond edge proximity. Media platforms in the United States and Germany concentrate procurement here, driven by FCC net-neutrality transit cost pressures and GDPR data-residency mandates.
- Web Acceleration:TCP/UDP optimization protocols compress round-trip times for dynamic HTML and JavaScript payloads. E-commerce checkout flows in China require MIIT-compliant node localization, fragmenting infrastructure deployment schedules across quarters.
- API Acceleration:Fintech and SaaS providers deploy this tier for authentication and transaction validation at edge POPs.
- Image Optimization:Automated compression and format conversion reduce payload weight for mobile-first retail experiences.
Mature deployment sits with Web Acceleration. Newer deployment is concentrated in Video Delivery.
Deployment Model:
Control architecture and data sovereignty posture determine enterprise selection criteria across cloud consumption patterns.
- Public Cloud:Hyperscaler-managed edge nodes offer rapid provisioning without capital deployment. Startups and mid-market enterprises in India leverage TRAI-compliant public infrastructure to satisfy data localization mandates without自建 buildout.
- Multi-Cloud:Risk distribution across AWS, Azure, and Google Cloud footprints prevents single-vendor lock-in. German manufacturing firms unbundle CDN from compute contracts, sourcing independent edge performance through synthetic benchmarking rather than bundled procurement.
- Private Cloud:Captive infrastructure serves defense and financial services with strict data residency requirements.
- Hybrid Cloud:Burst capacity from public nodes supplements private origin infrastructure during traffic spikes.
Volume leadership rests with Public Cloud. Procurement momentum is shifting fastest toward Multi-Cloud.
End User:
Latency tolerance and payload sensitivity vary sharply across vertical application profiles.
- Media Companies:Live sports and broadcast streaming command the largest revenue pool, with bit-rate requirements scaling faster than compression efficiency gains.
- Gaming Industry:Real-time multiplayer synchronization and cloud gaming render pipelines demand edge compute integration beyond static caching. Developers deploy WASM runtimes at edge POPs for authentication and matchmaking logic.
- E-Commerce:Cart abandonment reduction drives investment in checkout flow acceleration and image optimization.
- Enterprises:SaaS application delivery and internal knowledge bases represent steady-state demand with moderate latency requirements.
Revenue concentration aligns with Media Companies. Technology investment intensity peaks within Gaming Industry.
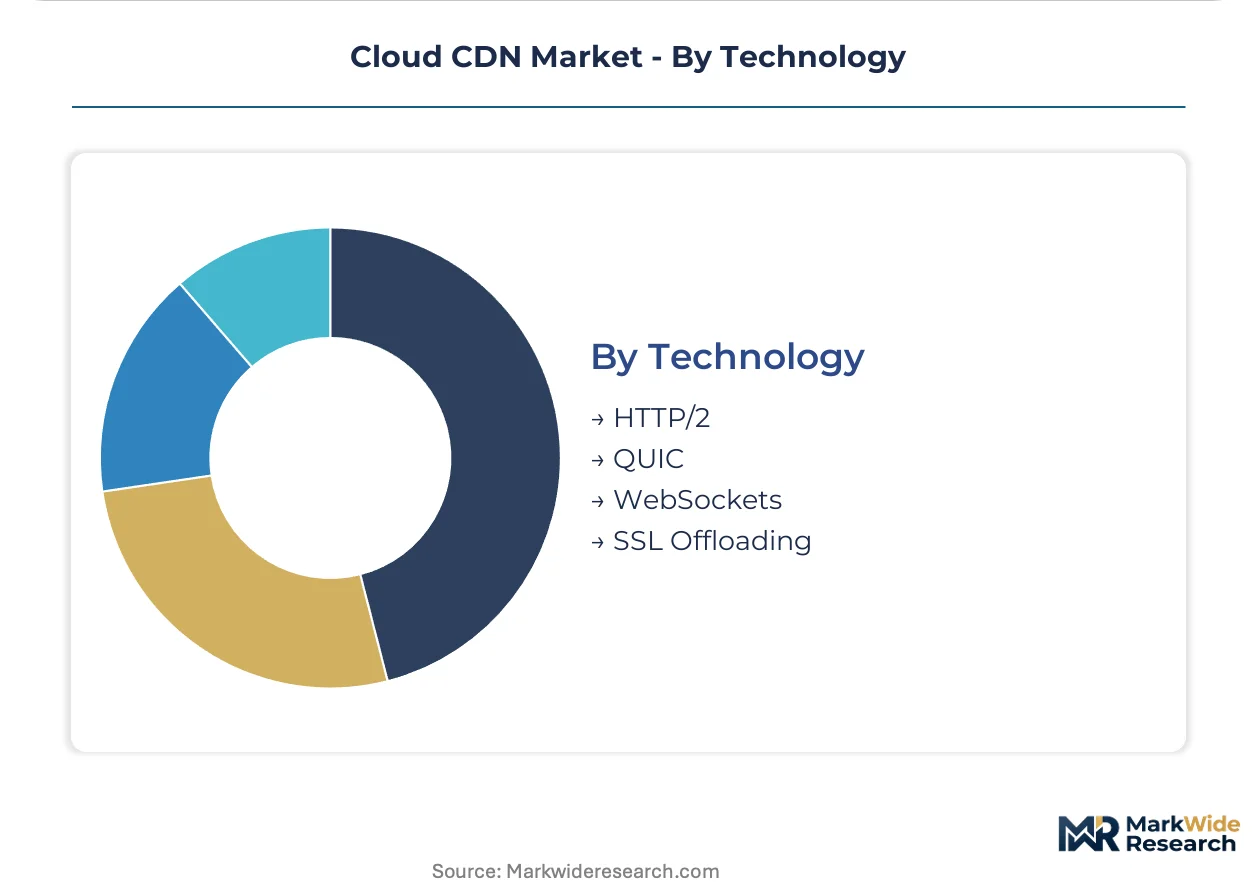
Technology:
Transport layer protocols and security offloading mechanisms determine throughput ceilings and connection reliability.
- QUIC:UDP-based multiplexing eliminates head-of-line blocking inherent in TCP. Google and Cloudflare deployment has normalized this protocol for mobile and lossy network environments.
- HTTP/2:Server push and header compression remain baseline requirements for enterprise procurement committees evaluating CDN vendors.
- WebSockets:Persistent bidirectional connections enable real-time data feeds for trading platforms and collaborative applications.
- SSL Offloading:Edge-terminated encryption reduces origin server computational load and accelerates handshake completion.
Standardized deployment centers on HTTP/2. QUIC is climbing the fastest as mobile traffic share expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors European CDN infrastructure density, hosting hyperscaler edge nodes that serve GDPR-compliant caching for broadcasters across the continent. The United States, China, Germany, India, and Japan concentrate procurement volumes and regulatory complexity.
United States
Media streaming platforms and cloud gaming studios drive node expansion into secondary metros. FCC net-neutrality rulings restrict paid peering arrangements, forcing video providers toward private backbone investments. Dallas-Fort Worth clusters house edge facilities serving central U.S. latency requirements.
China
Domestic cloud providers deploy MIIT-compliant infrastructure for live commerce and short-video platforms. Mandatory cybersecurity reviews delay foreign node activation by quarters, fragmenting rollout schedules. Beijing-Tianjin-Hebei corridor concentrates government-sanctioned edge computing zones.
Germany
Manufacturing firms unbundle CDN procurement from cloud compute contracts, sourcing through synthetic benchmarking. GDPR data-residency mandates require in-country caching for automotive and industrial IoT workloads. Munich hosts edge nodes serving Bavaria's precision engineering clusters.
India
TRAI data localization directives mandate in-country caching for fintech and e-commerce platforms. Public cloud edge nodes satisfy compliance without capital-intensive buildout. Mumbai and Bangalore concentrate startup procurement for video streaming and API acceleration services.
Japan
Cloud gaming and low-latency financial trading drive edge node densification in Tokyo and Osaka. METI guidelines shape infrastructure security standards for critical service providers. Kanto region hosts the highest hyperscaler node density serving real-time multiplayer synchronization.
Cloud CDN Market Vendor Landscape
Premium-margin players sit above commodity-margin players across latency-performance and security-certification dimensions. The vendor base stratifies into three tiers: hyperscalers with bundled cloud integration, pure-play CDNs with edge-compute specialization, and regional providers with sovereign-data compliance. Strategic moves concentrate on serverless edge logic convergence and multi-cloud orchestration tooling.
Within the pure-play tier, Akamai Technologies and Cloudflare exemplify divergent positioning—one leveraging unmatched edge server footprint for latency-sensitive applications, the other anchoring developer-centric workflows with programmable edge logic. Amazon Web Services occupies the hyperscaler-integrated position, competing through tight coupling with cloud storage and compute primitives.
| Leading Market Players |
|---|
| Akamai Technologies |
| Cloudflare |
| Amazon Web Services |
| Google Cloud |
| Microsoft Azure |
| Fastly |
| Alibaba Cloud |
| Edgio |
| StackPath |
| Others |
Supply Flow & Price Mechanics
Edge systems engineering talent concentration in the San Francisco Bay Area and Bangalore widens labor-cost differentials between premium latency-optimized tiers and commodity caching services. Pricing spreads reflect this geographic wage dispersion, with sub-50 millisecond SLAs commanding substantial premiums over standard delivery tiers.
Pricing Analysis
Uptime guarantees anchor value-based pricing for enterprise CDN contracts, with throughput commitments and edge compute availability serving as primary pricing levers. Three-tier pricing structure across premium, standard, and economy levels separates latency-sensitive gaming workloads from bulk video delivery and static asset caching. Cost compression in the economy tier is intensifying because hyperscalers bundle CDN as loss-leader compute attachments. Mid-market SaaS providers exhibit highest price sensitivity, while financial trading platforms demonstrate least elasticity due to regulatory latency requirements.
Supply Chain Analysis
Trans-Pacific fiber routes and interconnection settlement costs constitute significant freight-equivalent logistics burdens for edge node deployment. Taiwan, South Korea, and the United States concentrate semiconductor fabrication for edge processors, while server assembly clusters in Mexico and Vietnam feed regional infrastructure buildouts. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and precision cooling systems. Single-source vulnerability in advanced node fabrication creates geopolitical exposure. Distribution runs through hyperscaler-managed logistics networks and regional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cloud CDN Market sits in a technology-transition phase, with WebAssembly runtimes at edge nodes displacing traditional static caching as the primary value proposition for premium tiers.
For Market Incumbents: Acquire serverless edge compute platforms to defend against developer-workflow migration toward programmable infrastructure. Hyperscaler bundling of CDN as compute attachments threatens standalone pricing power. Certification investment in ISO 27001 and SOC 2 Type II accelerates enterprise procurement velocity. For New Entrants and Emerging Players: Capture India's TRAI-mandated data localization buildout as the most penetrable geography, where mid-market fintech and e-commerce platforms seek compliant alternatives to hyperscaler infrastructure. ISO 27001 certification arbitrage opens procurement access faster than hyperscaler audit cycles permit. For Investors and Strategic Acquirers: Re-rating potential sits with multi-cloud orchestration specialists given enterprise unbundling of CDN from compute contracts. Long-term viability favors vendors with sovereign-data compliance footprints across GDPR, MIIT, and TRAI jurisdictions. Watch synthetic latency benchmarking adoption as inflection signal for procurement committee behavior shift.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Compute Platform Acquisition | WASM runtime integration enables compute-at-edge applications beyond static delivery. |
| Multi-Cloud Orchestration Tooling | Risk distribution across AWS, Azure, and Google Cloud footprints prevents vendor lock-in. |
| Sovereign Data Certification | ISO 27001 and SOC 2 Type II credentials function as baseline enterprise procurement requirements. |
| Secondary Metro Node Densification | Sub-50 millisecond latency mandates edge expansion into municipal boundaries for 4K streaming. |
| Private Backbone Infrastructure | FCC net-neutrality restrictions on paid peering force video providers toward owned transit networks. |
Methodological Framework
Independent corroboration across hyperscaler capex disclosures, TRAI regulatory filings, and enterprise procurement databases underwrites the qualitative findings. Primary interviews with CDN platform engineers, IT procurement officers at manufacturing firms, cloud infrastructure architects, and edge systems specialists combined with secondary validation from SEC filings, MIIT cybersecurity review announcements, and GDPR enforcement actions. Bottom-up node deployment tracking and top-down revenue triangulation anchored market sizing.
Comparable-period anchoring to historical infrastructure rollout cycles calibrated the forecast window across the analysis window. Segmentation dimensions modeled include service type, deployment model, end-user vertical, and regional regulatory cluster. CAGRs derived from edge node densification trajectories, bit-rate escalation in video workflows, and multi-cloud adoption velocity. QUIC protocol penetration and WASM runtime deployment served as technology-specific forecast inputs.
The model holds under stable regulatory enforcement patterns; deviation in MIIT inspection timelines or GDPR fine escalation would shift infrastructure deployment schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Backup Market
Cloud Computing
Europe AI Cloud Computing in Automotive Market
Cloud Computing
Global Marketing Cloud Platform Market
Cloud Computing
Cloud Managed Networking Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Global Distributed Cloud Market
Cloud Computing
North America Cloud Computing Market
Cloud Computing
Cloud Based Information Governance Market
Cloud Computing
Cloud Directory Services Software Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Cloud Computing Services Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
Cloud Infrastructure-As-A-Service Market
Cloud Computing
Application Hosting Market