
 Interleukin 1 Beta (IL-1β) ELISA Kit Market | 2026-2036
Interleukin 1 Beta (IL-1β) ELISA Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Interleukin 1 Beta (IL-1β) ELISA Kit Market Insights
Academic institutions is redrawing procurement priorities across the IL-1β ELISA kit landscape, shifting volume toward high-sensitivity platforms for cytokine profiling research. Thermo Fisher Scientific leverages its distribution density across North American research corridors to sustain kit availability. Abcam differentiates through recombinant antibody specificity, a technical edge that commands premium positioning in autoimmune disorder studies. Wuhan Fine Biotech Co., Ltd. anchors cost-competitive manufacturing, competing aggressively on unit economics for bulk institutional orders.
Interleukin 1 Beta (IL-1β) ELISA kits are immunoassay platforms that quantify picogram-level concentrations of the pro-inflammatory cytokine IL-1β in serum, plasma, or cell culture supernatants through antibody-antigen binding with enzymatic signal amplification, serving primarily as analytical tools for inflammation research and clinical biomarker validation. Sandwich ELISA configurations dominate the product type landscape due to superior specificity and established protocol familiarity among end users. Chemiluminescent detection technology leads the technology segment for low-abundance sample analysis, while colorimetric methods retain volume in routine screening applications where equipment simplicity matters. Cancer research applications represent the fastest-expanding application segment, driven by IL-1β's recognized role in tumor microenvironment modulation and immuno-oncology drug development.
FDA 21 CFR Part 820 quality system regulations and EMA in vitro diagnostic device standards shape kit validation requirements, compelling manufacturers to demonstrate batch-to-batch consistency and analytical sensitivity documentation. ISO 13485 certification has become a baseline market access credential for suppliers targeting clinical diagnostic laboratories. China's NMPA issued updated technical review guidelines for cytokine detection reagents, raising registration barriers for imported kits. Stakeholders must monitor evolving companion diagnostic co-development partnerships between kit vendors and pharmaceutical sponsors, as these alliances increasingly determine long-term contract volumes and technology roadmaps.
Market Dynamics
Precision medicine infrastructure expansion is concentrating kit procurement among pharmaceutical sponsors running immuno-oncology trials, compressing vendor selection cycles toward partners with documented batch-to-batch consistency.
Growth Catalysts
- FDA 21 CFR Part 820:Quality system regulations tighten analytical performance documentation requirements, forcing kit standardization that benefits established suppliers with validation resources.
- Immuno-oncology drug pipelines:Pharmaceutical sponsors accelerate cytokine profiling for tumor microenvironment studies, generating recurring high-volume ELISA kit contracts.
- China's NMPA technical review guidelines:Updated registration barriers for imported cytokine detection reagents create protected market space for domestic manufacturers.
Market Restraints
- Recombinant antibody input costs:Specialized monoclonal antibody production concentrates among limited bioreactor facilities, exposing kit margins to protein purification supply volatility.
- ISO 13485 certification timelines:Clinical diagnostic laboratory access requires 12-18 month quality system audits, delaying new entrant commercialization.
- Multiplex cytokine panels:Luminex and flow cytometry platforms enable simultaneous 10-50 analyte detection, threatening single-analyte ELISA volume in high-throughput screening.
Strategic Opportunities
- Germany's precision medicine networks:BioRN and Berlin-Buch clusters expand autoimmune disorder biomarker programs, creating demand for IL-1β-specific research-grade kits.
- Companion diagnostic co-development:Kit vendors partnering with pharmaceutical sponsors on IL-1β-targeting therapeutics secure long-term supply agreements tied to regulatory submissions.
- Chemiluminescence-colorimetry hybrid platforms:Detection technology convergence enables sensitivity-adjustable workflows, capturing users migrating between research and clinical applications.
Industry Challenges
- Cross-reactivity validation:IL-1β shares structural homology with IL-1α and IL-1 receptor antagonist, demanding extensive antibody specificity testing that extends development cycles.
- Legacy instrument compatibility:Colorimetric kit users face workflow disruption when upgrading to chemiluminescent detection, requiring retraining and capital investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interleukin 1 Beta (IL-1β) ELISA Kit Market |
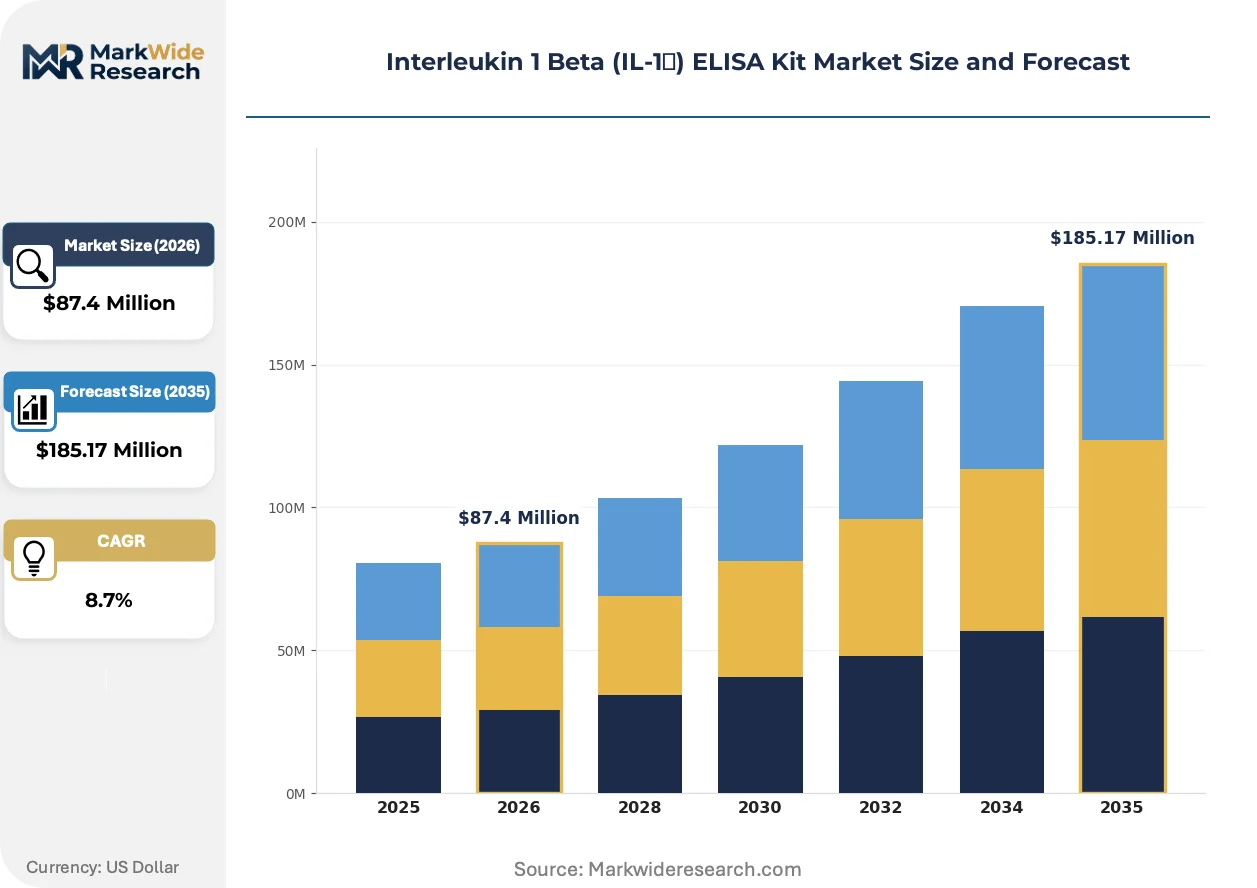
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sandwich ELISA, Competitive ELISA, Quantitative ELISA, Semi-Quantitative ELISA End User: Research Institutions, Diagnostic Laboratories, Pharmaceutical Companies, Academic Institutions Technology: Colorimetric, Chemiluminescent, Fluorescent, Electrochemical Application: Immunology Studies, Cancer Research, Infectious Diseases, Autoimmune Disorders |
| Companies Covered | Elabscience Biotechnology Inc., Wuhan Fine Biotech Co., Ltd., MyBiosource, Inc., Abcam, Thermo Fisher Scientific, CUSABIO, Bio-Techne, RayBiotech, Inc., BioLegend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interleukin 1 Beta (IL-1β) ELISA Kit Market Trends and Innovations
Detection platform evolution and regulatory documentation demands are compressing kit development cycles while fragmenting procurement authority between research procurement offices and clinical quality departments.
Electrochemiluminescence detection is supplanting traditional enzymatic amplification in pharmaceutical discovery settings, offering femtomolar sensitivity for low-abundance tumor microenvironment samples. Large-molecule biologics teams at contract research organizations have adopted this platform for 18-month validation studies. The technology is compressing competitive positioning toward vendors with integrated instrument-reagent ecosystems.
EMA's In Vitro Diagnostic Regulation (IVDR) reclassification of cytokine detection reagents intensifies conformity assessment requirements for CE-marked kits entering European clinical laboratories. Manufacturers must now submit clinical evidence packages that demonstrate diagnostic accuracy across intended use populations. German and French reference laboratories are prioritizing suppliers with notified body partnerships already secured.
Consolidated purchasing agreements now dominate academic medical center procurement, with centralized research cores negotiating multi-year kit supply contracts that displace individual laboratory purchasing autonomy. This behavior concentrates volume among vendors offering flexible lot sizing and just-in-time delivery logistics. The shift is most visible across United States National Cancer Institute-designated cancer centers expanding immuno-oncology programs.
Interleukin 1 Beta (IL-1β) ELISA Kit Market Segmentation
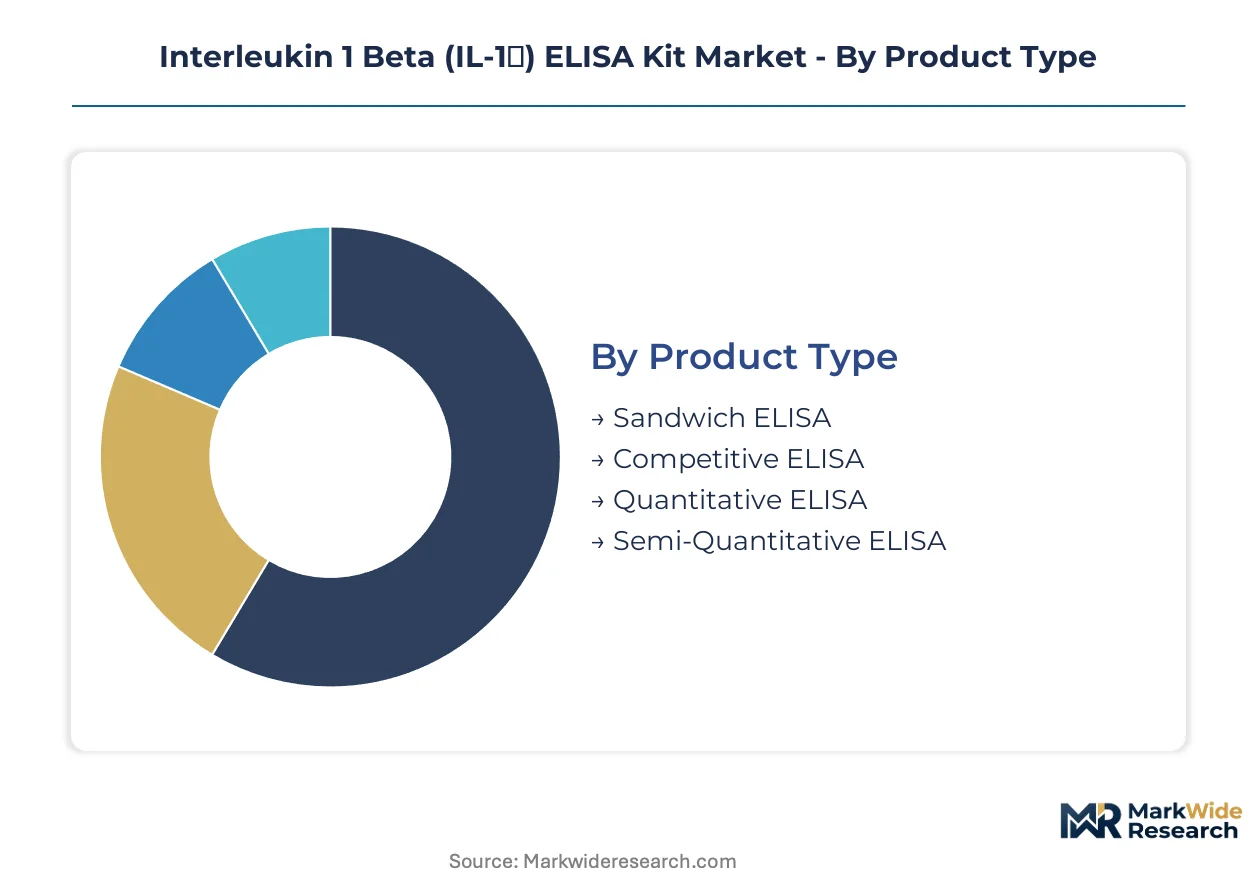
Kit configuration, detection sensitivity, and end-user workflow requirements fragment procurement patterns across the IL-1β ELISA landscape. Vendors must align product architectures with distinct validation standards between research exploration and clinical diagnostic environments.
Product Type:
Margin pools concentrate in high-specificity configurations where antibody engineering investments command premium positioning against routine screening alternatives.
- Sandwich ELISA:Dual-antibody capture architecture achieves picogram-level detection limits through paired monoclonal binding. Pharmaceutical immuno-oncology programs in the United States and Germany drive recurring bulk procurement for tumor microenvironment profiling studies. FDA 21 CFR Part 820 documentation requirements favor established suppliers with validated batch protocols.
- Competitive ELISA:Single-antibody competitive displacement format suits small-molecule detection and hapten quantification where epitope density is limited. Academic laboratories with constrained capital budgets favor this configuration for preliminary screening workflows. China's NMPA registration barriers for imported reagents redirect domestic manufacturers toward this lower-complexity segment.
- Quantitative ELISA:Standard curve-based concentration reporting with defined analytical ranges supports biomarker validation protocols.
- Semi-Quantitative ELISA:Threshold detection format enables rapid positive-negative classification without full calibration infrastructure.
The dominant share belongs to Sandwich ELISA, while Competitive ELISA is closing the gap fastest.
End User:
Procurement authority is fragmenting between centralized research cores and distributed clinical quality departments with divergent compliance requirements.
- Research Institutions:National Cancer Institute-designated centers in the United States negotiate multi-year supply agreements with flexible lot sizing and just-in-time delivery logistics. Electrochemiluminescence platforms are displacing colorimetric workflows for femtomolar sensitivity in low-abundance tumor microenvironment samples.
- Pharmaceutical Companies:Large-molecule biologics teams at contract research organizations drive 18-month validation studies requiring documented batch-to-batch consistency. Companion diagnostic co-development partnerships increasingly determine long-term contract volumes and technology roadmaps.
- Diagnostic Laboratories:ISO 13485 certification and EMA IVDR conformity assessment requirements filter supplier access to European clinical markets.
- Academic Institutions:Consolidated purchasing agreements across centralized research cores displace individual laboratory autonomy with volume concentration effects.
Research Institutions command the largest procurement volume, though Pharmaceutical Companies are expanding their share most steeply.
Technology:
Detection platform evolution is compressing competitive positioning toward vendors with integrated instrument-reagent ecosystems.
- Chemiluminescent:Enzymatic signal amplification with luminol-based substrates delivers femtomolar sensitivity for low-abundance cytokine quantification. German and French reference laboratories prioritize this platform for autoimmune disorder biomarker programs under EMA IVDR frameworks. Capital investment requirements and retraining burdens slow migration from legacy colorimetric infrastructure.
- Colorimetric:Tetramethylbenzidine substrate conversion enables visual or spectrophotometric readout without specialized detection equipment. Routine screening applications in resource-constrained settings retain substantial volume despite sensitivity limitations. Equipment simplicity sustains demand across emerging market diagnostic networks.
- Fluorescent:Fluorophore-conjugated secondary antibodies enable multiplexing capabilities with spectral resolution.
- Electrochemical:Direct electron transfer detection eliminates enzymatic amplification steps for simplified workflow integration.
Chemiluminescent detection holds the leading position, while Electrochemical platforms are gaining adoption most rapidly.
Application:
Disease area funding priorities and therapeutic pipeline activity reshape segment attractiveness across autoimmune, oncologic, and infectious disease domains.
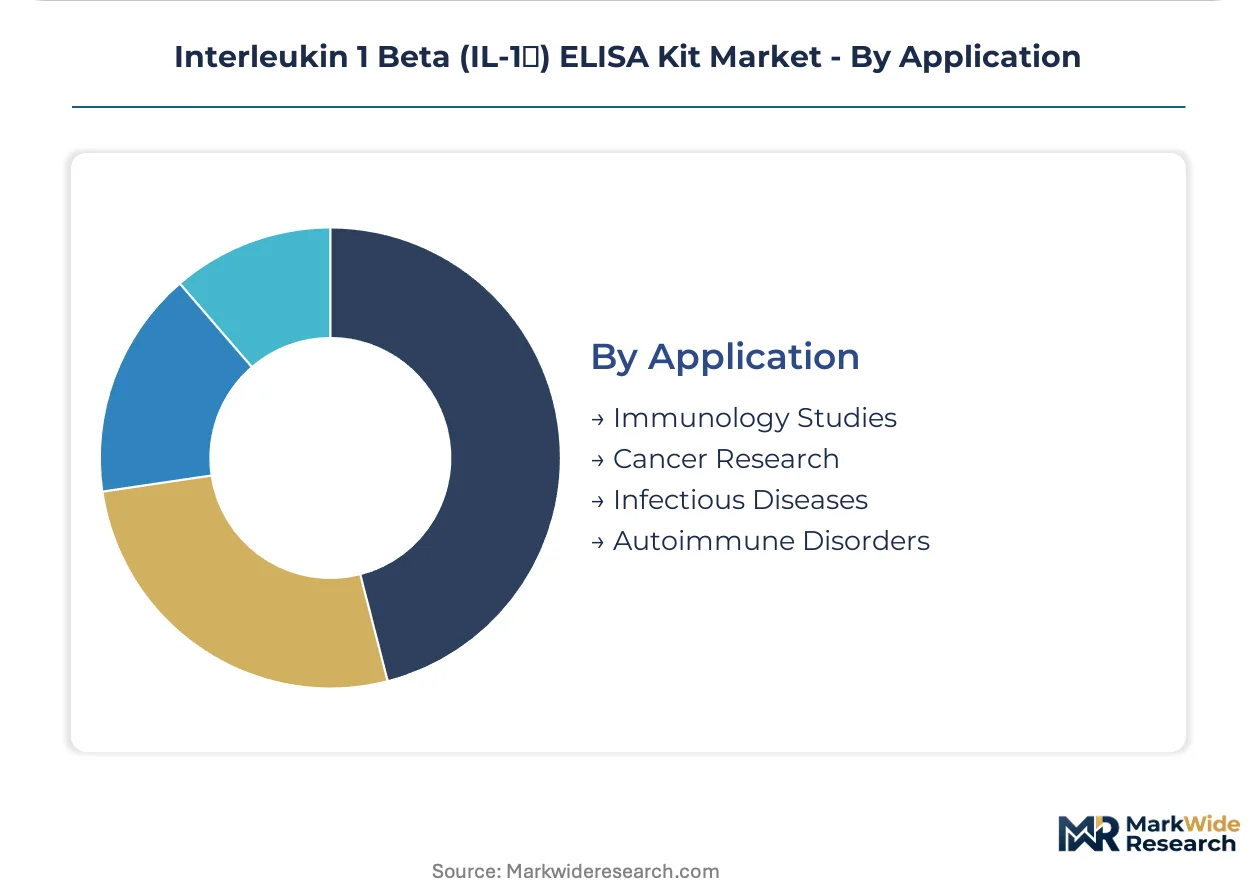
- Cancer Research:IL-1β's recognized role in tumor microenvironment modulation and immuno-oncology drug development concentrates investment in cytokine profiling infrastructure. BioRN and Berlin-Buch clusters in Germany expand autoimmune disorder biomarker programs with IL-1β-specific research-grade kit demand. Cross-reactivity validation with IL-1α and IL-1 receptor antagonist extends development cycles for antibody specificity testing.
- Autoimmune Disorders:Rheumatoid arthritis and inflammatory bowel disease therapeutic development drives biomarker validation requirements. Abcam's recombinant antibody specificity commands premium positioning in this segment through technical differentiation.
- Immunology Studies:Fundamental cytokine network research supports mechanistic understanding across inflammatory pathways.
- Infectious Diseases:Sepsis and acute inflammation monitoring applications require rapid turnaround capabilities for clinical decision support.
Cancer Research dominates application demand, with Autoimmune Disorders expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized bioreactor facilities for monoclonal antibody production cluster in the United States, Germany, and China, concentrating kit manufacturing inputs and shaping regional procurement patterns for IL-1β ELISA platforms.
United States
National Cancer Institute-designated cancer centers drive bulk procurement for immuno-oncology cytokine profiling. FDA 21 CFR Part 820 quality system regulations enforce batch-to-batch consistency documentation. Greater Boston and San Diego biotech corridors anchor pharmaceutical sponsor validation studies requiring 18-month kit supply agreements.
Germany
BioRN and Berlin-Buch precision medicine networks expand autoimmune disorder biomarker programs. EMA In Vitro Diagnostic Regulation reclassification intensifies conformity assessment requirements for CE-marked kits. Heidelberg and Munich research cores prioritize suppliers with secured notified body partnerships for clinical diagnostic access.
China
Domestic manufacturers capture protected market space as NMPA technical review guidelines raise registration barriers for imported cytokine detection reagents. Yangtze River Delta biotech parks scale electrochemiluminescence platform production. Shanghai and Suzhou clusters concentrate cost-competitive manufacturing for bulk institutional orders.
United Kingdom
Academic medical centers consolidate purchasing agreements through centralized research cores. ISO 13485 certification requirements filter supplier access to clinical diagnostic networks. London and Cambridge life science clusters negotiate multi-year supply contracts with flexible lot sizing for cytokine profiling infrastructure.
Japan
PMDA regulatory frameworks shape validation standards for companion diagnostic co-development partnerships. Tokyo and Osaka pharmaceutical sponsors accelerate IL-1β-targeting therapeutic pipelines. Kanto region research institutions adopt femtomolar sensitivity platforms for low-abundance tumor microenvironment studies.
Interleukin 1 Beta (IL-1β) ELISA Kit Market Competitive Landscape
Concentration sits with diversified life science conglomerates and specialized immunoassay developers, creating a tiered structure where validation resources and distribution density determine contract access. Three archetypes dominate: multinational platform vendors with integrated instrument-reagent ecosystems, recombinant antibody specialists commanding premium positioning, and cost-optimized domestic manufacturers competing on unit economics. Competitive moves center on companion diagnostic co-development partnerships and chemiluminescence-colorimetry hybrid platform launches.
Among diversified platform vendors, Thermo Fisher Scientific exemplifies the integrated ecosystem archetype through North American distribution density. Abcam occupies a position within the recombinant antibody specialist tier, leveraging technical differentiation in autoimmune disorder studies. Wuhan Fine Biotech Co., Ltd. anchors the cost-competitive manufacturing archetype, serving bulk institutional orders with aggressive unit economics.
| Leading Market Players |
|---|
| Elabscience Biotechnology Inc. |
| Wuhan Fine Biotech Co., Ltd. |
| MyBiosource, Inc. |
| Abcam |
| Thermo Fisher Scientific |
| CUSABIO |
| Bio-Techne |
| RayBiotech, Inc. |
| BioLegend |
| Others |
Pricing and Supply Chain Analysis
Multi-year kit supply agreements with pharmaceutical sponsors lock in both monoclonal antibody input access and price predictability across volatile bioreactor facility costs. FDA 21 CFR Part 820 compliance documentation and EMA IVDR conformity requirements embed certification premiums into contract structures, while bulk institutional orders in China negotiate unit economics against NMPA-registered domestic alternatives.
Pricing Analysis
FDA 21 CFR Part 820 dictates the pricing tier structure across the IL-1β ELISA kit landscape, separating GMP-validated clinical diagnostic grades from research-use-only alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status, batch-to-batch consistency documentation depth, and antibody specificity validation rigor. Cost compression in the economy tier is intensifying because Wuhan Fine Biotech and domestic Chinese manufacturers exploit NMPA registration barriers to undercut imported reagents. Academic laboratories with constrained capital budgets exhibit highest price sensitivity; pharmaceutical immuno-oncology programs prioritize analytical performance over unit cost.
Supply Chain Analysis
Just-in-time delivery logistics dominate procurement patterns among United States National Cancer Institute-designated centers and German BioRN cluster institutions, though strategic antibody stockpiling persists among vendors exposed to recombinant protein purification volatility. Bioreactor facility concentration in the United States, Germany, and China anchors monoclonal antibody production inputs. Supply chains draw from recombinant antibody production, enzymatic substrate chemicals, and microplate manufacturing. Single-source vulnerability concentrates in specialized bioreactor capacity for high-affinity monoclonal generation. Distribution runs through life science distributors with research corridor density and direct pharmaceutical sponsor contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IL-1β ELISA kit incumbents face substitution pressure from multiplex cytokine panels and electrochemiluminescence platform vendors integrating reagent-instrument ecosystems, demanding defensive positioning around validation documentation and companion diagnostic partnerships.
For Market Incumbents: Secure companion diagnostic co-development partnerships with pharmaceutical sponsors running IL-1β-targeting therapeutic pipelines to lock in multi-year supply agreements and regulatory submission-linked volumes. Deepen backward integration into recombinant antibody production through captive bioreactor capacity or exclusive supply contracts with specialized facilities, insulating margins from protein purification input volatility. Counter Luminex and flow cytometry substitution threats by embedding chemiluminescence-colorimetry hybrid platforms that capture users migrating between research and clinical workflows. For New Entrants and Emerging Players: Anchor in China's NMPA-protected domestic market space where technical review guidelines for cytokine detection reagents disadvantage imported kit competitors. Target competitive ELISA configurations for academic laboratories with constrained capital budgets, exploiting lower regulatory complexity than sandwich ELISA alternatives. Pursue cost-optimized manufacturing scale in Yangtze River Delta biotech parks to serve bulk institutional orders with aggressive unit economics against established multinational pricing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among recombinant antibody specialists with documented batch-to-batch consistency and secured notified body partnerships for EMA IVDR access. Long-term viability hinges on companion diagnostic co-development contract density and electrochemiluminescence platform adoption curves across pharmaceutical discovery settings. Watch for inflection signals in immuno-oncology trial initiation rates at National Cancer Institute-designated centers, as cytokine profiling infrastructure investment precedes kit procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Locks multi-year supply agreements with pharmaceutical sponsors pursuing IL-1β-targeting therapeutics. |
| Recombinant Antibody Production Integration | Captures margin from monoclonal purification through captive bioreactor capacity or exclusive supply contracts. |
| EMA IVDR Notified Body Partnership | Secures CE-marked kit access to German and French reference laboratories under intensified conformity assessment. |
| Chemiluminescence-Colorimetry Hybrid Platform Launch | Captures users migrating between research and clinical applications with sensitivity-adjustable workflows. |
| NMPA Domestic Registration Pathway Investment | Exploits protected market space in China as technical review guidelines raise barriers for imported reagents. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory submission databases, hospital procurement records, and pharmaceutical pipeline disclosures to construct demand-side validation. Interviews with drug development executives, regulatory affairs leads at kit vendors, biomedical engineers at diagnostic laboratories, and GPO contracts managers informed procurement pattern assessment. Secondary sources include FDA 510(k) filings, EMA IVDR technical documentation, ClinicalTrials.gov cytokine profiling protocol specifications, and NMPA registration databases. Bottom-up kit shipment estimates triangulate against top-down precision medicine infrastructure investment flows across the analysis window.
Segmentation dimensions modeled span product type (sandwich versus competitive ELISA), detection technology (chemiluminescent, colorimetric, electrochemical), end-user archetype (research institutions, pharmaceutical companies, diagnostic laboratories), and application domain (cancer research, autoimmune disorders). CAGRs derive from fitted growth curves against documented batch procurement volumes and companion diagnostic partnership announcement timelines. Forecast inputs incorporate immuno-oncology trial initiation rates, NMPA registration pathway completion data, and electrochemiluminescence platform adoption curves at contract research organizations.
Decision-makers should treat outputs as directional under assumptions of sustained precision medicine infrastructure investment and stable regulatory framework evolution; material deviation in multiplex platform substitution rates or bioreactor capacity expansion would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Terbinafine Tablet Market
Biopharmaceuticals
Peptide Drug Conjugates Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Insulin Aspart Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market
Biopharmaceuticals
Vaccine Production Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
Biologic Response Modifiers Market
Biopharmaceuticals
Mammalian Derived Proteins Market