
 Poland ICT Market | 2026-2036
Poland ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Poland ICT Market Insights
EU AI Act compliance is broadening the cost-of-entry calculus for Poland ICT vendors, forcing smaller providers to absorb certification overhead or exit public-sector channels. Asseco Poland leverages its entrenched position in banking software to sustain premium pricing on core-system modernization. Comarch anchors its competitive stance through deep vertical specialization in telecommunications billing and ERP ecosystems. Orange Polska competes by controlling last-mile infrastructure and bundling connectivity with managed cloud services.
Poland ICT encompasses information and communication technology systems spanning software applications, computing hardware, telecommunications infrastructure, and managed services, typically governed by latency thresholds below 50 milliseconds for enterprise workloads and uptime guarantees exceeding 99.9%. Its primary purpose is enabling data processing, enterprise connectivity, and digital workflow automation across commercial and public-sector operations. Services and cloud computing segments command expanding margin pools as Polish enterprises shift capital expenditure to operational expenditure models. Hardware retains structural importance in Warsaw's data center buildouts, though growth velocity lags software-defined infrastructure. Cybersecurity within the technology dimension attracts disproportionate investment as NIS2 transposition hardens baseline requirements for critical infrastructure operators.
BIS certification alignment, EU Cybersecurity Act frameworks, and Poland's national implementation of NIS2 directives collectively elevate product standards and restrict market access for non-compliant vendors. The central bank and financial supervision authority reinforce these thresholds through sector-specific IT governance mandates affecting banking software procurement. Stakeholders must monitor regulatory divergence between EU harmonized standards and Poland's sectoral enforcement intensity to anticipate compliance cost trajectories.
Market Dynamics
Poland ICT operates under tightening EU AI Act compliance thresholds that force vendors to absorb certification overhead or cede public-sector procurement channels entirely. This regulatory compression accelerates vendor consolidation while elevating capital requirements for market participation.
Growth Catalysts
- EU AI Act transposition:Mandatory conformity assessments for high-risk AI systems create certified vendor scarcity that rewards early compliance investments by established ICT providers.
- Financial services cloud migration:Polish banks and insurers are retiring legacy core systems, generating sustained demand for API-native banking platforms and hybrid infrastructure.
- Krakow technology cluster concentration:Deep pools of software engineering talent attract multinational delivery centers, amplifying domestic vendor capabilities through knowledge spillover.
Market Restraints
- Semiconductor supply concentration:Polish hardware integrators remain dependent on East Asian foundry output, exposing procurement cycles to geopolitical disruption and extended lead times.
- NIS2 implementation costs:Critical infrastructure operators face seven-figure compliance investments in SIEM deployment and incident response capabilities, compressing discretionary IT budgets.
- Legacy system technical debt:Cobol and mainframe architectures in Polish banking create integration friction that slows cloud-native replacement timelines.
Strategic Opportunities
- Silesian manufacturing corridor:Industrial IoT penetration remains below Western European baselines, creating whitespace for edge computing and predictive maintenance platforms.
- EU Cybersecurity Act certification:Common Criteria and cloud service scheme approvals unlock cross-border public-sector contracting for Polish vendors.
- 5G private network convergence:Manufacturing and logistics operators in Poznan and Wroclaw are piloting campus networks that bundle connectivity with localized compute.
Industry Challenges
- Cloud architecture skills scarcity:Polish enterprises report persistent gaps in Kubernetes platform engineering and FinOps cost governance, forcing reliance on external systems integrators.
- EU AI Act certification timelines:Notified body capacity constraints extend conformity assessment durations, delaying product launches and freezing R&D roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland ICT Market |
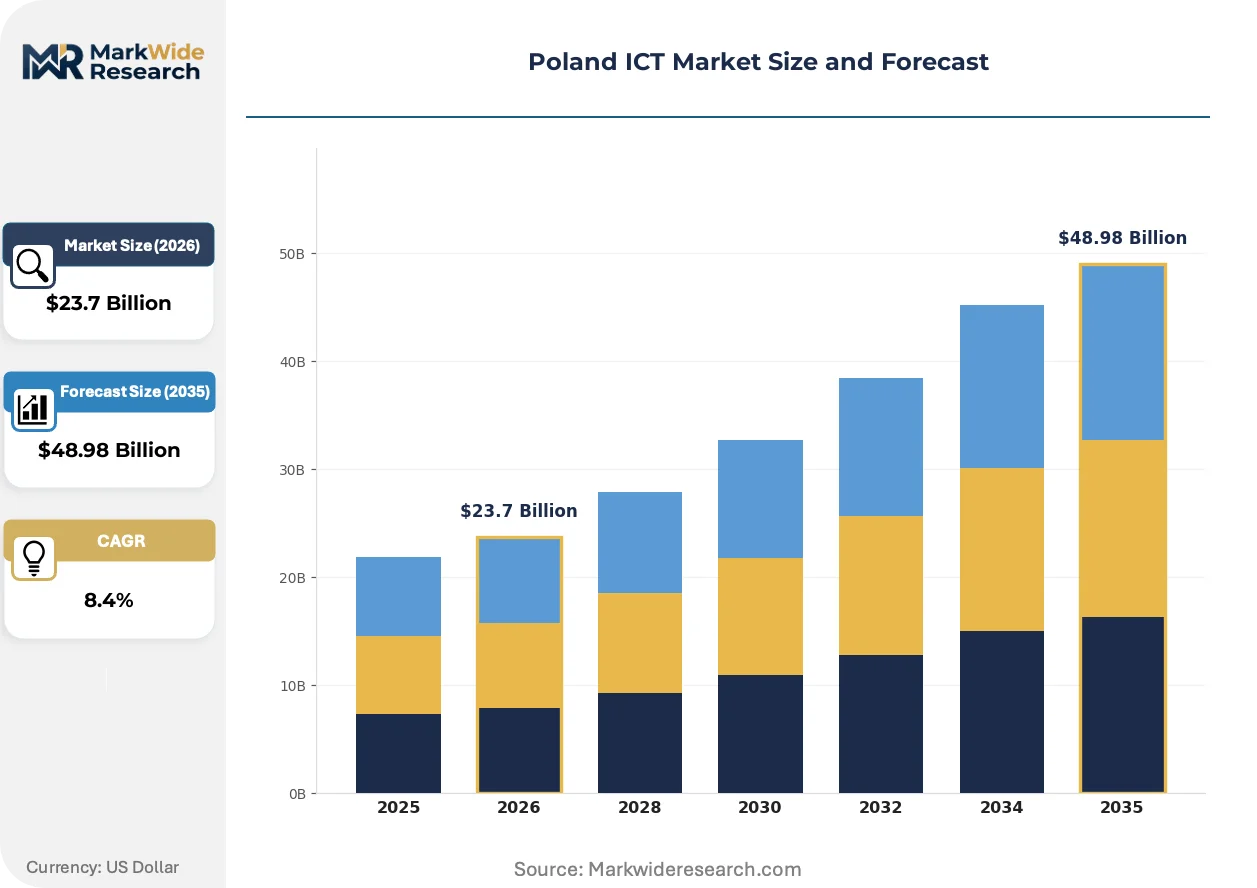
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Infrastructure End User: Telecommunications, Financial Services, Government, Healthcare Technology: Cloud Computing, Big Data, IoT, Cybersecurity Application: Enterprise Resource Planning, Customer Relationship Management, Supply Chain Management, Business Intelligence |
| Companies Covered | Asseco Poland, Comarch, AB, Orange Polska, Microsoft, Google Polska, Dell Technologies Poland, Lenovo Technology, Samsung Electronics Polska, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland ICT Market Trends and Innovations
Software-defined infrastructure is compressing hardware-centric business models across Polish enterprise procurement. Three distinct vectors are reconfiguring competitive positioning and vendor economics.
Containerized microservices architectures are overtaking monolithic application deployments in Warsaw's financial services corridor. Polish banks are replatforming core banking functions onto Kubernetes orchestration layers, collapsing release cycles from quarterly to weekly increments. This velocity compression is overtaking traditional change-management disciplines and elevating platform engineering to strategic priority.
Poland's transposition of NIS2 directives imposes mandatory incident reporting thresholds and supply chain security audits on critical infrastructure operators. Energy and transport sectors face the steepest compliance gradients, with enforcement beginning through sectoral regulators. Vendors are responding by pre-integrating SIEM and SOAR capabilities into managed service offerings.
Subscription consumption models are displacing perpetual license structures across Polish mid-market procurement. Finance directors in manufacturing and retail verticals now prioritize OpEx predictability over capital ownership, compressing vendor cash conversion cycles. This preference shift is most visible in Krakow's SaaS-native startup ecosystem, where annual recurring revenue metrics dominate valuation conversations.
Poland ICT Market Segmentation
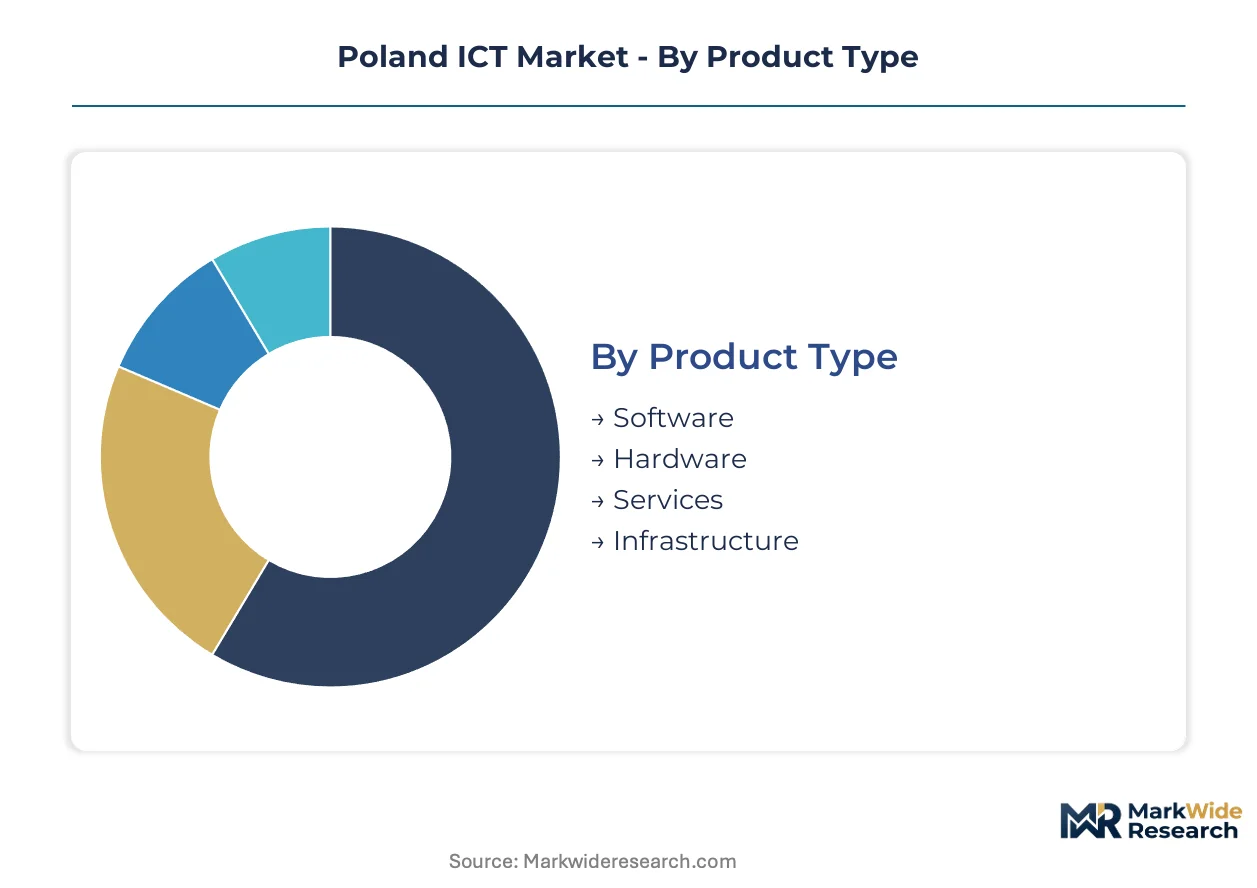
Segmentation in Poland ICT reveals how vendor capabilities align with diverging procurement priorities across regulated industries. Warsaw's financial services corridor and Krakow's technology cluster concentrate demand for distinct technology stacks, while EU AI Act compliance reshapes accessible vendor pools.
Product Type:
Supply concentration in Polish ICT procurement gravitates toward software-defined solutions that minimize hardware dependency and accelerate deployment velocity.
- Software:Enterprise applications span core banking systems, ERP platforms, and vertical-specific solutions. Polish financial services firms in Warsaw drive premium demand for API-native architectures that collapse release cycles from quarterly to weekly increments.
- Hardware:Servers, storage arrays, and networking equipment retain structural importance in data center buildouts. Procurement cycles face extended lead times due to East Asian foundry dependency, compressing margin pools for Polish systems integrators.
- Services:Managed infrastructure, systems integration, and professional services command expanding share as enterprises shift capital expenditure to operational expenditure models.
- Infrastructure:Data center facilities, edge computing nodes, and telecommunications backbone constitute the physical layer underpinning digital service delivery.
Today's leader: Software. Tomorrow's challenger: Services.
End User:
Cost tier stratification separates mission-critical deployments in regulated sectors from discretionary procurement in administrative functions.
- Telecommunications:Network operators require billing systems, subscriber management platforms, and 5G core infrastructure. Orange Polska and Comarch anchor this vertical through deep vertical specialization in OSS/BSS ecosystems.
- Financial Services:Banks and insurers dominate premium ICT spend, retiring legacy Cobol architectures for cloud-native cores. The Polish Financial Supervision Authority enforces sector-specific IT governance mandates that elevate procurement thresholds.
- Government:Public-sector channels demand EU AI Act conformity assessments for high-risk systems, creating certified vendor scarcity.
- Healthcare:Hospital networks and regional health authorities prioritize electronic medical records and telemedicine infrastructure.
Financial Services commands current premium pricing. Telecommunications presents the steepest expansion trajectory as 5G private networks proliferate.
Technology:
Application intensity varies across Polish enterprise maturity levels, with cloud-native architectures displacing on-premise legacy in Warsaw's enterprise corridor.
- Cloud Computing:Hybrid and multi-cloud deployments enable Polish banks to replatform core functions onto Kubernetes orchestration layers. Skills scarcity in platform engineering forces reliance on external systems integrators.
- Big Data:Analytics platforms process transaction streams and customer behavioral data for real-time decisioning. Manufacturing operators in the Silesian corridor apply predictive models to production optimization.
- IoT:Industrial sensors and connected devices penetrate below Western European baselines, creating whitespace for edge computing deployments.
- Cybersecurity:SIEM and SOAR capabilities attract disproportionate investment as NIS2 transposition hardens baseline requirements for critical infrastructure operators.
Cloud Computing anchors current procurement volumes. Cybersecurity gains share fastest as regulatory enforcement intensifies.
Application:
Customer type differentiation separates integrated suite deployments in large enterprises from modular point solutions in mid-market manufacturing and retail.
- Enterprise Resource Planning:Integrated financial, supply chain, and human capital management systems form the operational backbone of Polish manufacturers. Subscription consumption models displace perpetual licenses across mid-market procurement.
- Customer Relationship Management:Sales force automation and marketing orchestration platforms concentrate in financial services and telecommunications verticals seeking subscriber retention optimization.
- Supply Chain Management:Procurement and logistics coordination tools support Poland's role as a Central European distribution hub.
- Business Intelligence:Dashboarding and reporting layers aggregate operational data for executive decision support.
Enterprise Resource Planning retains incumbent dominance. Business Intelligence climbs fastest as self-service analytics democratizes data access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep software engineering talent pools in Krakow and Warsaw anchor Poland's ICT demand concentration. These urban clusters generate knowledge spillover effects that amplify domestic vendor capabilities. EU regulatory frameworks transposed through national legislation shape procurement thresholds across sub-regional markets.
Masovian Voivodeship
Warsaw's financial services corridor drives premium demand for API-native banking platforms and hybrid cloud infrastructure. The Polish Financial Supervision Authority enforces sector-specific IT governance mandates that elevate procurement thresholds for core system modernization. Warsaw enterprise data centers concentrate hardware procurement for latency-sensitive workloads.
Lesser Poland Voivodeship
Krakow's technology cluster attracts multinational delivery centers and SaaS-native startups seeking annual recurring revenue growth. The EU AI Act transposition creates certified vendor scarcity that rewards early compliance investments by established providers. Deep talent pools in platform engineering sustain competitive differentiation for domestic software vendors.
Silesian Voivodeship
Industrial IoT penetration remains below Western European baselines across manufacturing operators in the Katowice-Gliwice corridor. NIS2 implementation imposes mandatory incident reporting thresholds on critical infrastructure operators in energy and transport sectors. Predictive maintenance platforms and edge computing deployments capture whitespace in factory automation.
Greater Poland Voivodeship
Poznan logistics operators pilot 5G private networks that bundle campus connectivity with localized compute infrastructure. EU Cybersecurity Act certification requirements unlock cross-border public-sector contracting opportunities for compliant vendors. Manufacturing and distribution hubs prioritize OpEx predictability over capital ownership in procurement decisions.
Lower Silesian Voivodeship
Wroclaw's shared service centers and R&D facilities generate sustained demand for enterprise collaboration platforms and business intelligence tools. Cloud architecture skills scarcity forces reliance on external systems integrators for Kubernetes platform engineering. Subscription consumption models displace perpetual licenses across mid-market manufacturing procurement.
Poland ICT Market Competitive Landscape
The competitive structure tilts toward vertically integrated domestic specialists with entrenched banking and telecommunications relationships. Vendor consolidation accelerates as EU AI Act compliance costs force smaller providers to absorb certification overhead or exit public-sector channels entirely. Three archetypes dominate: legacy core system modernizers, cloud-native platform builders, and infrastructure-anchored connectivity bundlers. Dominant competitive moves include strategic partnerships for technology licensing and portfolio diversification into adjacent cybersecurity services.
Among Poland-based software specialists, Asseco Poland and Comarch exemplify the vertically integrated domestic archetype, leveraging deep sectoral relationships to sustain premium positioning. Orange Polska occupies a position as the infrastructure-anchored connectivity bundler, controlling last-mile assets that enable managed service packaging. Microsoft and Google Polska represent the global cloud platform tier, competing through hyperscale infrastructure and enterprise productivity ecosystems. These players collectively illustrate how regulatory compliance, vertical specialization, and infrastructure control define competitive differentiation in Polish ICT procurement.
| Leading Market Players |
|---|
| Asseco Poland |
| Comarch |
| AB |
| Orange Polska |
| Microsoft |
| Google Polska |
| Dell Technologies Poland |
| Lenovo Technology |
| Samsung Electronics Polska |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon neutrality mandates gate qualified supply for Polish ICT vendors, restricting premium-tier pricing access to providers with verified sustainable sourcing and energy-efficient data center certifications. Buyers in Warsaw's financial services corridor now require Scope 3 emissions disclosures as standard procurement criteria, compressing margins for non-compliant hardware integrators while rewarding certified cloud-native specialists with pricing power.
Pricing Analysis
Bundled managed services command 40-60% price premiums over unbundled infrastructure procurement across Polish enterprise accounts. Subscription consumption models dominate software and cloud segments, with three-tier pricing structure across premium, standard, and economy levels differentiating by SLA guarantees and support tiers. Pricing pressure stems from hyperscaler competition in Warsaw and Krakow, where Microsoft and Google Polska undercut domestic providers on compute unit economics. Mid-market manufacturing buyers exhibit highest price sensitivity, while financial services prioritize compliance-grade solutions over cost minimization.
Supply Chain Analysis
EU Cybersecurity Act certification gates vendor participation in Polish public-sector procurement, filtering supply pools to Common Criteria-approved providers. Hardware components draw from Taiwan, South Korea, and China, with server-grade semiconductors and networking equipment resting on East Asian foundry output. Single-source vulnerability in advanced node chip fabrication exposes Polish systems integrators to extended lead time volatility. Distribution runs through Warsaw-based national distributors and Krakow technology cluster direct channels, with hyperscale cloud providers bypassing traditional intermediaries entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland ICT functions as a stable compounder, with EU regulatory harmonization driving steady replacement demand across banking and critical infrastructure verticals. Compliance investment cycles create predictable revenue visibility for certified vendors.
For Market Incumbents: Acquire cloud-native engineering talent pools in Krakow and Wroclaw to defend against hyperscaler encroachment in financial services. Consolidate smaller NIS2-compliant competitors before notified body capacity constraints ease. Prioritize backward integration into edge computing hardware to capture 5G private network buildouts in Silesian manufacturing corridors. For New Entrants and Emerging Players: Digital-channel routes through hyperscaler marketplaces offer lowest-friction customer acquisition for SaaS-native entrants. Target Silesian industrial IoT whitespace where predictive maintenance penetration trails Western European baselines. Pursue EU Cybersecurity Act certification early to unlock cross-border public-sector contracting before incumbent lock-in solidifies. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated Polish software specialists because NIS2 compliance costs force sub-scale vendors toward exit. Five-to-ten year viability hinges on banking core modernization cycles and 5G enterprise adoption curves. Monitor notified body capacity expansion as the inflection signal for certification scarcity easing and competitive entry reopening.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Common Criteria approval unlocks public-sector procurement channels excluded to non-compliant rivals. |
| Kubernetes Platform Engineering Buildout | Warsaw banks demand weekly release cycles that collapse traditional change-management disciplines. |
| Edge Computing Infrastructure Deployment | Silesian manufacturing corridors require localized compute for sub-10ms latency industrial control. |
| 5G Private Network Partnership | Poznan logistics operators pilot campus networks bundling connectivity with managed cloud services. |
| Cybersecurity Services Portfolio Extension | NIS2 incident reporting mandates force critical infrastructure operators toward integrated SIEM-SOAR offerings. |
Research Methodology
Coverage spans Masovian, Lesser Poland, Silesian, Greater Poland, and Lower Silesian Voivodeships, with primary inputs from each region combined with secondary validation. Interviews with CTOs at Warsaw financial institutions, IT procurement officers in Krakow technology clusters, platform engineers at multinational delivery centers, and channel partners in Poznan distribution hubs inform demand-side assumptions. Secondary sources include SEC filings from listed ICT vendors, hyperscaler capex disclosures, EU AI Act implementation guidance, and Polish Financial Supervision Authority IT governance circulars. Bottom-up segment sizing triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end-user vertical, technology stack, and application function, with additional granularity on EU AI Act risk classification tiers. CAGRs derive from historical trajectory analysis adjusted for regulatory enforcement intensity and cloud migration velocity. Forecast inputs incorporate Polish banking core replacement pipelines and 5G spectrum auction deployment schedules.
The model assumes a particular technology adoption path; alternative pathways for quantum-resistant cryptography would alter the outlook for cybersecurity investment cycles. Forecasts reflect assumptions on regulatory harmonization timelines and hyperscaler pricing discipline. A model refresh is warranted upon material change in EU AI Act notified body capacity or semiconductor export control expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Structured Data Archiving and Application Retirement Market
Digital Solutions
HIPAA-Compliant Messaging Services Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Communication Intelligence Market
Digital Solutions
Australia Digital Twin Market
Digital Solutions
Product Engineering Services Market
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
North America Data Virtualization Market
Digital Solutions
Data As a Service (Daas) Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Audio Over IP Solutions Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Life Science Multichannel Campaign Management Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Digital Manufacturing Market