
 Crude Heater Market | 2026-2036
Crude Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Crude Heater Market Analysis
US Gulf Coast fabricators is recalibrating production schedules to address backlogs in heavy crude processing units. Amec Foster Wheeler leverages its legacy project portfolio across Middle Eastern refinery complexes. TechnipFMC anchors its position through proprietary heater coil designs for high-sulfur feedstocks. Linde Engineering competes on cryogenic integration packages that bundle crude preheating with downstream gas processing.
Crude heaters are direct-fired or indirect-fired thermal devices that raise the temperature of raw petroleum feedstocks to 300–400°C prior to atmospheric or vacuum distillation, using radiant and convective heat transfer through alloy steel coils housed in refractory-lined chambers. Their primary purpose is to reduce feedstock viscosity, optimize fractional distillation efficiency, and minimize coke formation in downstream processing units. Electric heaters command premium positioning in offshore platforms and remote extraction sites where flaring restrictions limit combustion options, while gas-fired systems dominate large integrated refineries seeking lower per-unit thermal costs. Refining Processes represents the most mature application segment, though Viscosity Reduction is gaining traction as operators blend heavier unconventional crudes requiring more intensive pre-treatment.
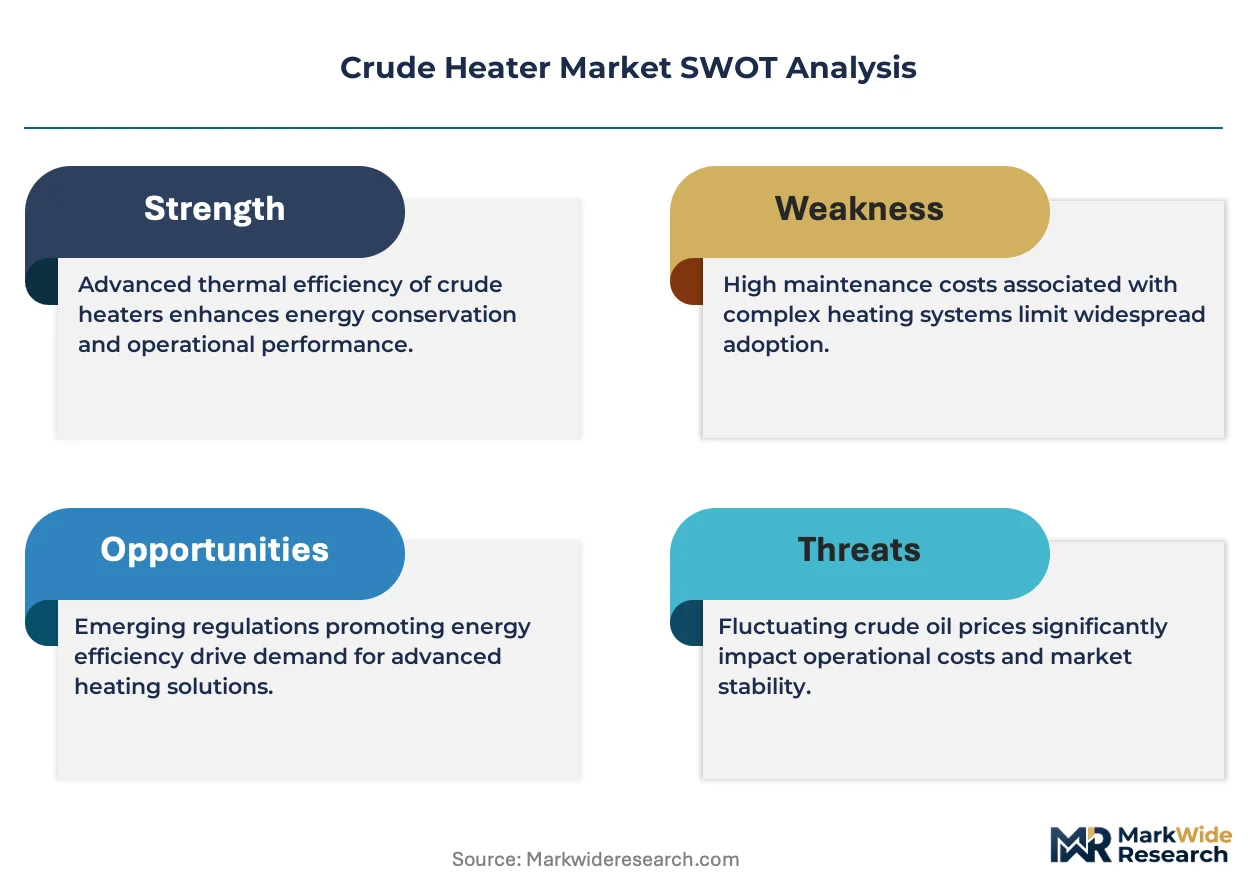
EPA New Source Performance Standards under the Clean Air Act mandate NOx and particulate emissions limits that force retrofit investments or new low-NOx burner adoption. India's BIS specifies minimum thermal efficiency ratings for process heaters above 50 MW capacity, while the EU F-Gas Regulation constrains refrigerant-linked heat recovery configurations in European installations. Stakeholders must weigh capex cycles against evolving carbon border mechanisms that could penalize high-emission thermal assets.
Market Dynamics
The transition toward heavier, higher-sulfur crude slates across North American and Indian refining complexes is forcing wholesale redesigns of radiant coil metallurgy and burner configurations. This feedstock gravity shift compresses thermal efficiency margins and accelerates capital redeployment toward units capable of handling 500°F+ outlet temperatures without accelerated coking.
Growth Catalysts
- EPA New Source Performance Standards:NOx and particulate mandates under the Clean Air Act compel refinery operators to replace legacy fired heaters with low-NOx burner systems, creating sustained replacement demand across the US Gulf Coast corridor.
- Petrochemical integration waves:Crude-to-chemicals complexes in India and the United States require high-duty fired heaters capable of simultaneous distillation feed preheat and ethylene cracker integration.
- Alloy 800HT coil adoption:Advanced nickel-chromium-iron alloys resist sulfidation and carburization in high-sulfur service, extending heater run lengths from 4 to 8 years between decoking cycles.
Market Restraints
- Refractory material cost volatility:High-purity alumina-silica castables and ceramic fiber modules face price pressure from bauxite export restrictions and energy-intensive kiln operations in supplier geographies.
- Fabricator capacity concentration:Heavy-wall alloy coil production concentrates among a limited set of specialized forges in Texas, Louisiana, and Gujarat, creating 18-24 month delivery backlogs for critical radiant section components.
- Electric resistance limitations:Grid infrastructure constraints and MW-scale power requirements limit electric heater deployment to sub-50 MW units, capping addressable share in large integrated refineries.
Strategic Opportunities
- Waste heat recovery convergence:Integration of crude preheating with downstream hydrogen production and amine regeneration units captures 15-20% efficiency gains through process intensification designs.
- India's BIS efficiency mandates:Minimum thermal performance standards for heaters above 50 MW capacity create certified product differentiation and premium positioning for compliant OEMs.
- Remote extraction electrification:Offshore platforms and Arctic production sites facing flaring restrictions present captive demand for explosion-proof electric heater skids with integrated variable frequency drives.
Industry Challenges
- Welding procedure qualification bottlenecks:ASME Section IX certification for exotic alloy joining requires specialized technicians, with qualified radiographic interpreters and orbital weld operators commanding 40% wage premiums.
- Legacy DCS integration friction:Modern burner management systems must interface with 1980s-vintage distributed control architectures, extending commissioning timelines and requiring custom protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crude Heater Market |
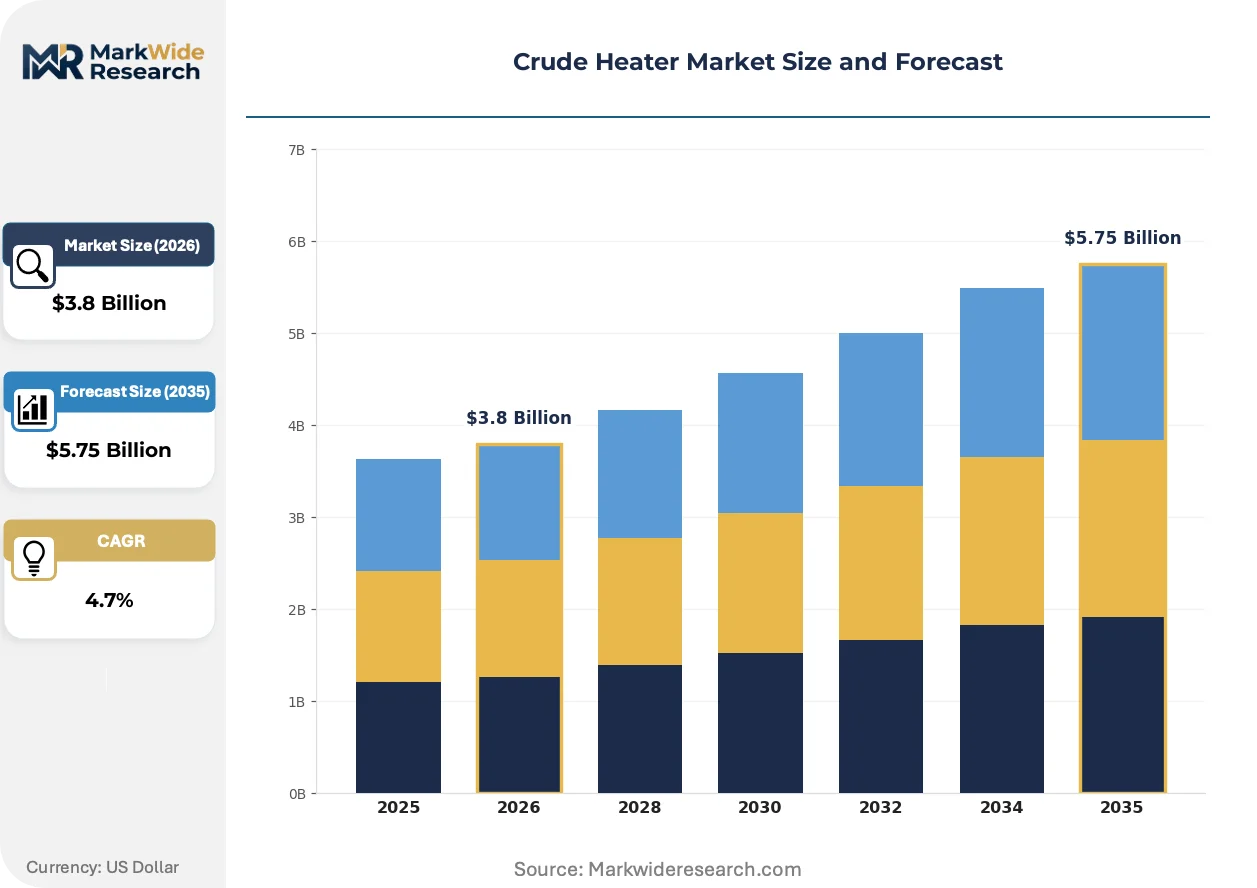
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Heater, Gas Heater, Oil Heater, Infrared Heater Application: Refining Processes, Viscosity Reduction, Heat Exchangers, Preheating End User: Oil & Gas Producers, Petrochemical Companies, Refineries, Chemical Manufacturers Installation Type: Fixed Installation, Portable Installation, Semi-Permanent Installation, Modular Installation |
| Companies Covered | Amec Foster Wheeler, TechnipFMC, Linde Engineering, Alfa Laval, Thermax Limited, Sigma Thermal, Exotherm Corporation, Tulsa Heaters Midstream, Zeeco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crude Heater Market Emerging Trajectories
Digital twin deployment and predictive corrosion modeling are compressing maintenance cycles and enabling condition-based heater operation. These capabilities intersect with evolving emissions accounting frameworks to reshape how operators justify capital allocation across thermal assets.
Electric process heater technology is electrifying marginal applications previously reserved for gas-fired units. Offshore platform operators facing strict NOx caps and helicopter-delivered fuel logistics are adopting 10-25 MW electric radiant heaters with silicon carbide elements. This shift is compressing the total cost gap between combustion and electric systems in remote high-labor-cost environments.
The EU F-Gas Regulation constrains refrigerant selection in heat recovery steam generator configurations, forcing European refiners toward ammonia-based absorption cycles or dry air cooling alternatives. German and Dutch operators report 12-18 month engineering delays as they requalify thermal integration packages. This regulatory friction is diverting investment toward simpler once-through steam generators without organic Rankine bottoming cycles.
Refinery procurement functions are consolidating heater specifications across multiple site locations, displacing historically decentralized engineering authority. Integrated operators like those along the US Gulf Coast now mandate corporate-standard burner management systems and coil metallurgy grades, compressing vendor qualification lists to three approved OEMs per region. This concentration is most visible in Texas and Louisiana, where single-source framework agreements cover 60% of new heater procurements.
Crude Heater Market Segmentation
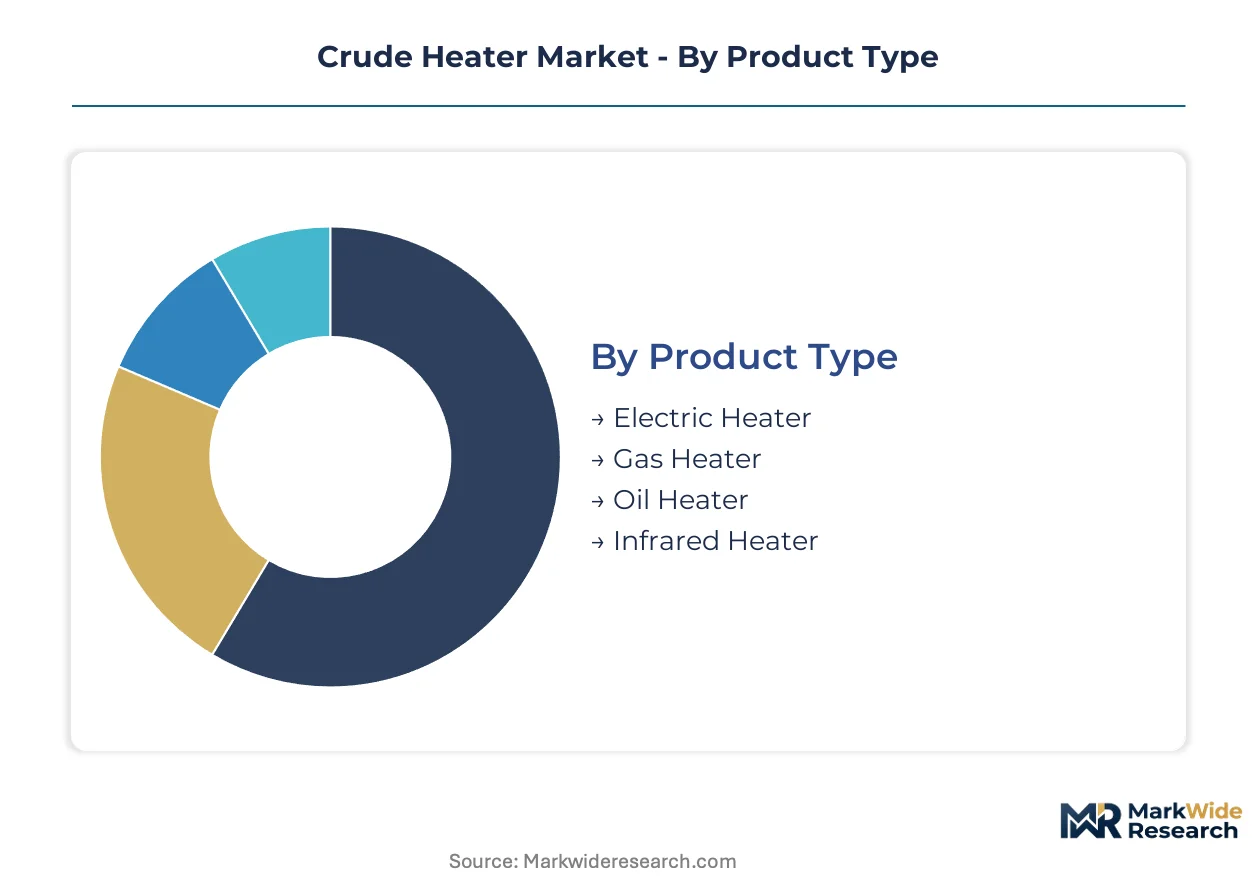
Crude heater procurement patterns diverge sharply across thermal duty requirements, feedstock chemistry, and integration complexity. Segment boundaries determine alloy specification, burner architecture, and aftermarket service intensity.
Product Type:
Volume concentration sits with combustion-based systems, while electric configurations command premium positioning in restricted environments.
- Electric Heater:Silicon carbide or resistance coil elements deliver precise temperature control without combustion emissions. Demand clusters in offshore platforms and Arctic extraction sites where flaring restrictions apply.
- Gas Heater:Fired radiant and convective sections dominate large integrated refineries seeking lower per-unit thermal costs. US Gulf Coast petrochemical corridors favor high-duty gas-fired configurations for crude-to-chemicals integration.
- Oil Heater:Liquid fuel burners serve remote locations lacking pipeline gas infrastructure. Heavy fuel oil firing persists in Middle Eastern and African refining complexes.
- Infrared Heater:Ceramic and catalytic infrared panels address specialized preheating applications with rapid response requirements. Niche deployment in laboratory and pilot-scale distillation units.
Mature deployment sits with Gas Heater configurations across coastal refining belts. Newer deployment is concentrated in Electric Heater systems for electrification mandates and remote extraction.
Application:
Application selection tracks feedstock gravity, sulfur content, and downstream process coupling requirements.
- Refining Processes:Atmospheric and vacuum distillation feed preheating represents the foundational use case. Alloy 800HT coil metallurgy extends run lengths between decoking cycles in high-sulfur service.
- Viscosity Reduction:Pre-treatment of heavy unconventional crudes and bitumen blends demands higher outlet temperatures. Indian refineries expanding heavy crude processing capacity drive specification intensity.
- Heat Exchangers:Integrated fired heater and shell-and-tube bundles optimize thermal efficiency in process intensification designs. Waste heat recovery convergence captures efficiency gains.
- Preheating:Intermediate temperature elevation prior to catalytic cracking or hydrotreating units. Standardized designs predominate in brownfield retrofit projects.
Refining Processes maintains the deepest installed base. Viscosity Reduction is expanding most quickly as heavy crude slate transitions accelerate.
End User:
End user categories separate volume procurement scale from technical specification complexity.
- Oil & Gas Producers:Upstream field operators require compact, modular heaters for wellhead and gathering system applications. Remote extraction electrification trends favor skid-mounted electric units.
- Petrochemical Companies:Crude-to-chemicals complexes demand high-duty fired heaters with simultaneous distillation and ethylene cracker integration. Corporate standardization mandates compress vendor lists to three approved OEMs per region.
- Refineries:Integrated refining operators concentrate procurement authority across multiple site locations. Single-source framework agreements now cover the majority of new heater procurements.
- Chemical Manufacturers:Specialty chemical producers utilize smaller-scale heaters for feedstock preparation and reaction initiation. Sub-50 MW electric resistance units predominate.
Refineries anchor historical procurement volume. Petrochemical Companies are gaining share fastest through greenfield crude-to-chemicals investments.
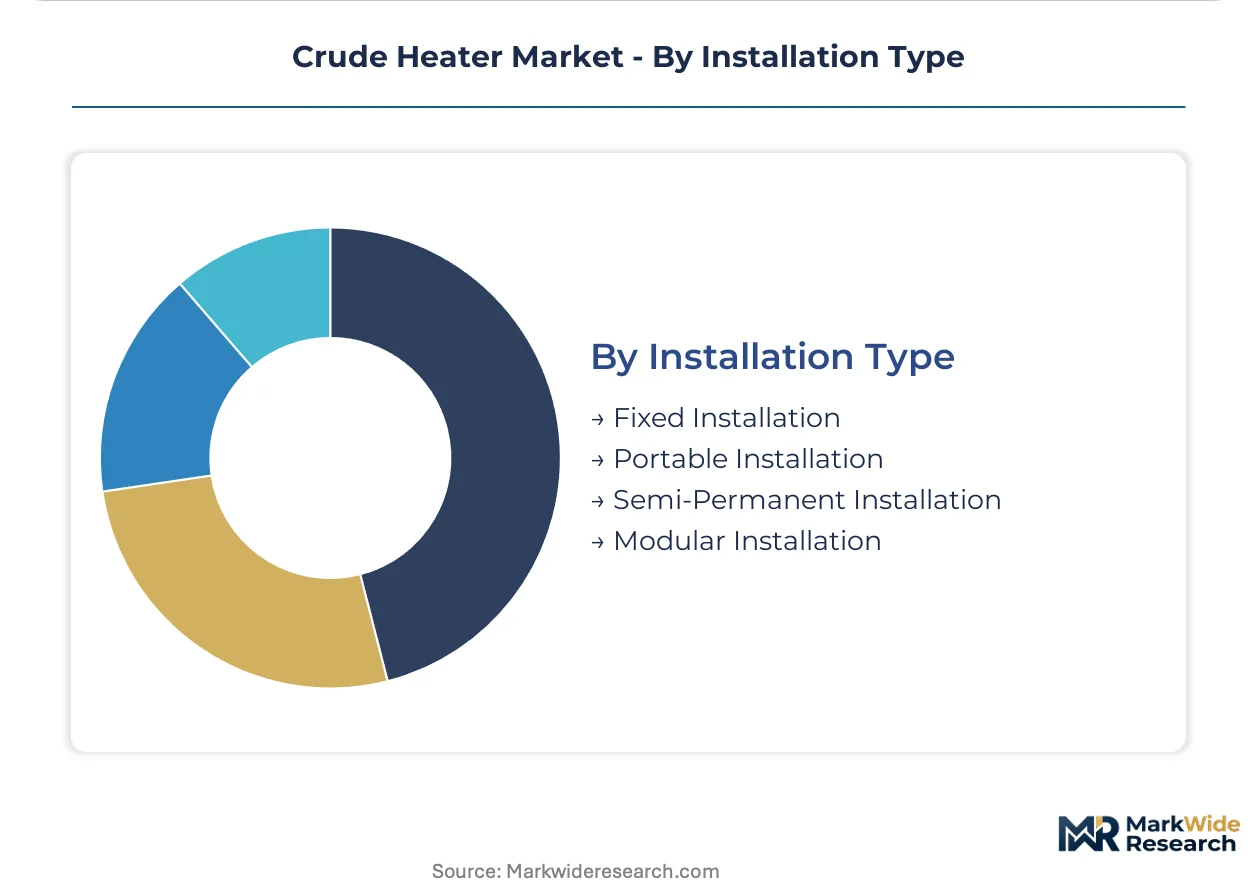
Installation Type:
Installation architecture determines mobility, foundation requirements, and commissioning timeline.
- Fixed Installation:Permanent refractory-lined structures with field-erected radiant sections. Large Gulf Coast refineries favor fixed installations for 50+ MW thermal duty units.
- Portable Installation:Trailer-mounted or skid-based systems for temporary production support. Wellhead heating and emergency turnaround applications.
- Semi-Permanent Installation:Modular components with extended anchor bolt foundations allowing future relocation. Brownfield expansion projects with uncertain long-term configuration.
- Modular Installation:Shop-fabricated radiant and convection sections shipped for field assembly. Compresses construction schedules and improves weld quality control.
Fixed Installation retains dominance in greenfield refining capacity. Modular Installation is climbing the fastest as fabricator capacity constraints extend delivery timelines for field-erected alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin heavy crude output anchors United States procurement intensity, while Middle Eastern sour crude exports drive metallurgical specification shifts across Asian refining corridors. Refinery operators in three distinct geographies are recalibrating thermal asset strategies around sulfur tolerance and emissions compliance.
United States
Gulf Coast petrochemical integration projects demand high-duty fired heaters exceeding 50 MW thermal capacity. EPA New Source Performance Standards under the Clean Air Act mandate NOx emissions limits that force low-NOx burner retrofits across Texas and Louisiana refining clusters. Houston-area fabricators report 18-month backlogs for heavy-wall alloy coil deliveries serving crude-to-chemicals complexes.
India
Reliance Industries and Indian Oil Corporation are expanding heavy crude processing capacity at Jamnagar and Paradip refineries. BIS energy efficiency mandates specify minimum thermal performance ratings for process heaters above 50 MW, creating certified product differentiation for compliant OEMs. Gujarat's specialized forging sector concentrates radiant section component production for domestic and export markets.
Germany
EU F-Gas Regulation constrains refrigerant-linked heat recovery configurations, forcing refiners toward ammonia-based absorption cycles or dry air cooling alternatives. BASF and other Ludwigshafen chemical complex operators report extended engineering timelines for thermal integration requalification. North Rhine-Westphalia's industrial corridor faces 12-18 month delays on organic Rankine bottoming cycle approvals.
Saudi Arabia
Saudi Aramco's crude-to-chemicals investments at Jubail and Yanbu require radiant coil metallurgy rated for 500°F+ outlet temperatures on high-sulfur feedstocks. The country's national petroleum regulator enforces sulfur recovery efficiency standards that cascade into heater burner specification requirements. Eastern Province fabrication yards are expanding capacity for field-erected radiant sections.
China
Sinopec and PetroChina are retrofitting coastal refineries for heavier imported crude slates from Latin America and the Middle East. MIIT industrial efficiency guidelines pressure state-owned operators toward waste heat recovery convergence designs. Shandong Province's independent refining sector concentrates procurement of modular heater packages with accelerated delivery schedules.
Crude Heater Market Vendor Landscape
Global majors compete with regional champions across engineering capabilities and fabrication capacity. The vendor base separates into three tiers: integrated EPC firms with proprietary heater designs, specialized thermal equipment fabricators with alloy forging expertise, and modular skid suppliers serving remote extraction sites. Two dominant competitive moves define current positioning: strategic partnerships between EPC firms and alloy forges to secure coil supply, and geographic expansion of fabrication capacity into high-growth refining corridors.
Within the integrated EPC tier, Amec Foster Wheeler and TechnipFMC occupy positions anchored by legacy project portfolios across Middle Eastern and Gulf Coast refinery complexes. Linde Engineering represents the process intensification archetype, bundling crude preheating with downstream gas processing through cryogenic integration packages. Among specialized thermal fabricators, Thermax Limited exemplifies regional champions scaling beyond domestic Indian demand into Southeast Asian and Middle Eastern markets.
| Leading Market Players |
|---|
| Amec Foster Wheeler |
| TechnipFMC |
| Linde Engineering |
| Alfa Laval |
| Thermax Limited |
| Sigma Thermal |
| Exotherm Corporation |
| Tulsa Heaters Midstream |
| Zeeco |
| Others |
Supply Flow & Price Mechanics
Bauxite price volatility on the London Metal Exchange cascades through refractory supply chains into crude heater procurement tiers, compressing margins for field-erected units while elevating premiums for modular configurations with faster payback profiles.
Pricing Analysis
Warranty bundling separates premium heater OEMs from commodity suppliers, with Alloy 800HT coil guarantees extending to eight-year run lengths commanding substantial uplifts over standard four-year coverage. Three-tier pricing structure across premium, standard, and economy levels reflects metallurgical grade, burner management system sophistication, and aftermarket service intensity. Cost compression in economy-tier electric skids is intensifying because silicon carbide element suppliers face energy-intensive kiln operation penalties. Refinery procurement teams demonstrate highest price sensitivity on sub-50 MW brownfield retrofits, while crude-to-chemicals greenfield developers prioritize thermal integration performance over capital outlay.
Supply Chain Analysis
ASME Section IX welding certification gates entry for radiant section fabricators, concentrating qualified production among specialized forges in Texas, Louisiana, and Gujarat. Heavy-wall alloy coil production draws from nickel-chromium-iron feedstocks, high-purity alumina-silica refractories, and ceramic fiber modules. Single-source vulnerability persists in orbital weld operator availability, with qualified technicians commanding substantial wage premiums. Distribution runs through EPC-led turnkey contracts for integrated refineries and direct OEM sales for modular skid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crude heater supply chains operate under severe fabricator capacity constraints, with 18-24 month delivery backlogs for critical radiant components propping pricing power across all metallurgical tiers.
For Market Incumbents: Anticipate sustained pressure from Indian and Middle Eastern EPC firms expanding their captive forging capabilities. Defensive consolidation should prioritize backward integration into Alloy 800HT coil production through partnerships with Gujarat-based specialized forges. Certification investment in BIS-compliant thermal efficiency ratings creates product differentiation against emerging regional competitors. For New Entrants and Emerging Players: EPA New Source Performance Standards in the United States opens a window for low-NOx burner system specialists to penetrate the retrofit-intensive Gulf Coast corridor. White-space targets include skid-mounted electric heaters for Permian Basin remote extraction sites and ammonia-based heat recovery packages for EU F-Gas-constrained German refineries. Go-to-market execution should anchor on aftermarket service intensity rather than capital equipment margin capture. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular fabrication specialists with established ASME welding qualifications in the US Gulf Coast region. Long-term viability hinges on exposure to crude-to-chemicals capital deployment cycles rather than brownfield replacement demand. The signal to watch is BIS certification backlog lengths as an indicator of Indian market access friction for non-compliant OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Forging | Captive supply of Alloy 800HT coils insulates against 18-24 month delivery backlogs at Texas and Louisiana forges. |
| Low-NOx Burner Technology Licensing | EPA compliance mandates across US Gulf Coast refineries create sustained replacement demand for certified systems. |
| Waste Heat Recovery Convergence | Process intensification designs capturing efficiency gains through hydrogen production integration attract crude-to-chemicals developers. |
| BIS Certification Investment | Minimum thermal efficiency standards for 50+ MW heaters in India create premium positioning for compliant OEMs. |
| Modular Fabrication Capacity Expansion | Shop-fabricated radiant sections compress construction schedules and improve weld quality control for constrained markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with refinery engineering directors, EPC procurement leads, alloy forge operations managers, and aftermarket service heads. EPA New Source Performance Standards documentation, BIS efficiency mandate circulars, EU F-Gas Regulation implementation guidance, and MIIT industrial efficiency guidelines provided regulatory calibration. Bottom-up unit economics across thermal duty segments reconciled with top-down capital expenditure tracking from major refining operators.
Data-stream reconciliation across shipment volumes, installation permits, and alloy consumption patterns informed the analytical framework. Segmentation dimensions modeled include heater type, application intensity, end-user category, and installation architecture across the projection horizon. CAGR derivation incorporated feedstock gravity transition rates, emissions compliance retrofit cycles, and crude-to-chemicals project development pipelines. Industry-specific inputs captured refractory material cost indices and qualified welder availability metrics.
The model assumes a particular technology adoption path; alternative pathways for electric resistance heating penetration would alter the outlook if grid infrastructure investments accelerate meaningfully. Forecasts reflect assumptions around regulatory enforcement consistency and alloy supply chain stability. A model refresh is warranted upon material change in EPA emissions standard stringency or Indian refinery capacity expansion timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Japan AC Motor Market
Industrial Motors
North America Industrial Motors Market
Industrial Motors
Spargers Market
Industrial Motors
Europe Hazardous Location Motors Market
Industrial Motors
Gearless Elevator Traction Motor Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
United States DC Motor Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
Gear Motor Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Latin America Hazardous Location Motors Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Smart Motors Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market