
 United Kingdom Collagen Market | 2026-2036
United Kingdom Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Collagen Market Analytics
Specialist pharmacy and aesthetic clinic distribution channels are reshaping how collagen peptides and native collagen formulations reach end consumers in the United Kingdom. GELITA AG leverages its European manufacturing footprint to sustain bulk gelatin supply contracts with British food manufacturers. Collagen Solutions plc anchors its position through medical-grade collagen matrices for orthopaedic and wound-care applications. Vital Proteins LLC competes via direct-to-consumer subscription models that bypass traditional retail intermediaries.
Collagen comprises a fibrous structural protein rich in glycine, proline, and hydroxyproline amino acids, typically extracted through acid or enzymatic hydrolysis of bovine, porcine, or marine connective tissues for use in biomaterials, food gelling, and nutritional supplementation. Hydrolyzed collagen dominates volume flows due to its cold-water solubility and bioavailability profile favoured by sports nutrition formulators. Medical device applications command the highest margin pools, with aesthetic clinics and pharmaceutical companies driving premium pricing for native collagen with intact triple-helix structures. Gelatin retains mature, price-competitive positioning within British food and beverage manufacturing, though growth rates trail peptide-grade alternatives.
The Food Standards Agency enforces novel food regulations that delay market entry for marine-sourced and recombinant collagen variants, while the Medicines and Healthcare products Regulatory Agency governs collagen-based medical device classifications. MHRA compliance requirements for implantable collagen scaffolds create barriers that favour established suppliers with validated quality management systems. Stakeholders must monitor evolving FSA guidance on cell-cultured collagen and track MHRA post-Brexit divergence from EU Medical Device Regulation harmonisation timelines.
Market Dynamics
MHRA post-Brexit divergence from EU Medical Device Regulation timelines is fragmenting compliance pathways for collagen-based implantable scaffolds, forcing British manufacturers to maintain dual quality management systems while awaiting clarity on UKCA marking permanence.
Growth Catalysts
- Novel food authorisation pathways:The Food Standards Agency's structured safety assessment framework for collagen-derived ingredients provides regulatory certainty that accelerates marine and recombinant variant commercialisation.
- Aesthetic clinic channel expansion:London and South East cosmetic surgery networks are driving premium uptake of native collagen formulations with intact triple-helix structures for dermal filler applications.
- Enzymatic hydrolysis advances:Cold-water solubility improvements in peptide-grade collagen are displacing gelatin in sports nutrition formulations across England and Scotland.
Market Restraints
- Bovine connective tissue supply concentration:Reliance on continental European abattoir sourcing exposes British processors to veterinary health certificate delays and customs friction at Channel ports.
- Marine collagen input cost volatility:North Atlantic fishery quota fluctuations and energy-intensive enzymatic extraction create margin compression for cod-skin and wild-caught alternatives.
- Recombinant collagen technical limitations:Yeast and bacterial expression systems struggle to produce hydroxyproline-rich sequences with native triple-helix stability comparable to mammalian sources.
Strategic Opportunities
- Cell-cultured collagen regulatory tailwind:Evolving FSA guidance on precision-fermentation-derived proteins offers first-mover advantage for laboratory-grown alternatives to animal-extracted matrices.
- Orthopaedic scaffold application expansion:Medical-grade collagen matrices for cartilage regeneration remain underpenetrated in NHS hospital trusts outside London and the South East.
- Direct-to-consumer channel innovation:Subscription models for hydrolyzed peptide powders are bypassing traditional pharmacy distribution and capturing recurring revenue from fitness-focused demographics.
Industry Challenges
- Dual regulatory compliance timelines:Maintaining parallel EU MDR and emerging UKCA technical documentation for implantable devices strains quality assurance staffing and extends certification cycles.
- Bioprocessing skill scarcity:Shortages of GMP-trained fermentation specialists and collagen biochemists constrain scale-up capacity for recombinant production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Collagen Market |
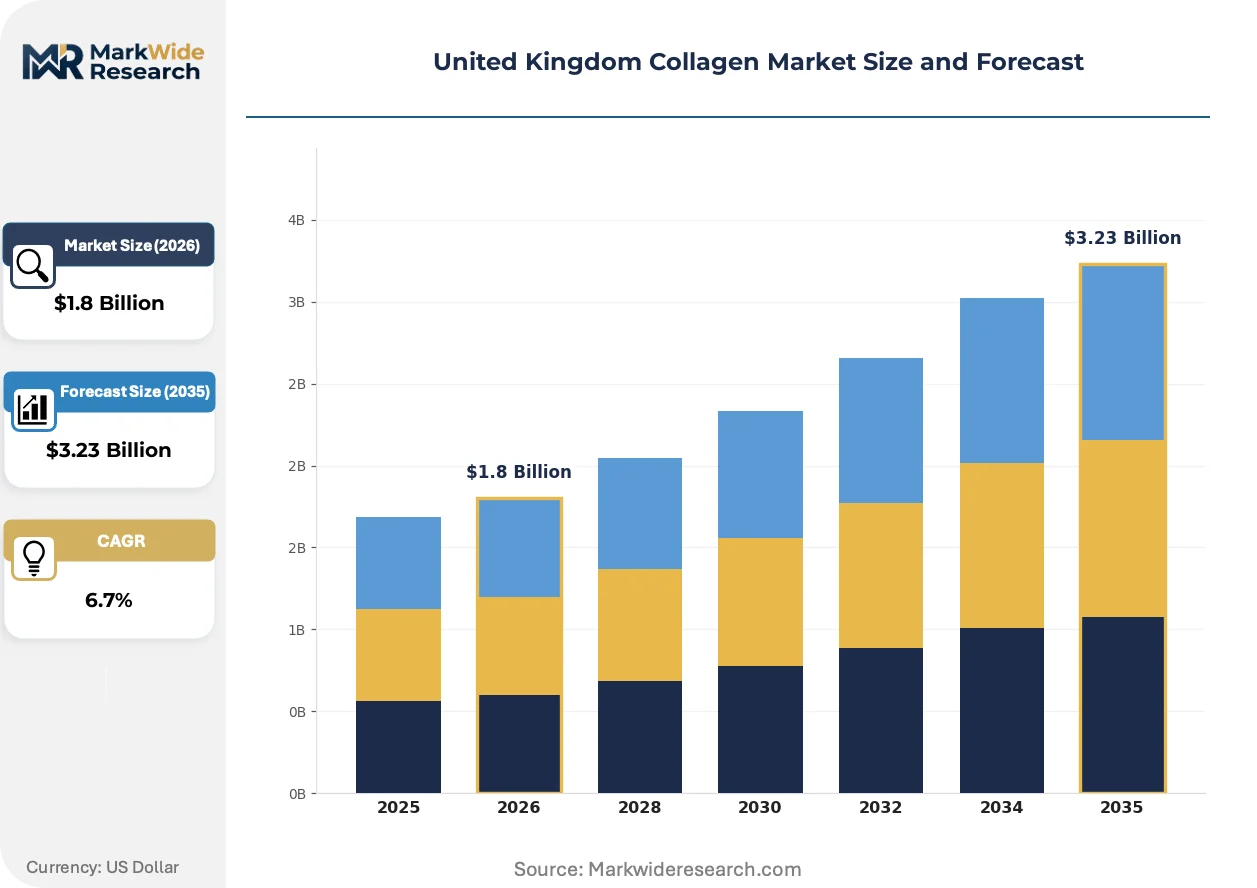
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Native Collagen Application: Cosmetics, Nutrition Supplements, Medical Devices, Food & Beverages End User: Sports Nutrition, Aesthetic Clinics, Pharmaceutical Companies, Food Manufacturers Form: Powder, Liquid, Capsules, Gummies |
| Companies Covered | Nitta Gelatin Inc., Weishardt Holding SA, Collagen Solutions plc, Hunter & Gather Foods Ltd, Vital Proteins LLC, GELITA AG, Tessenderlo Group, Proto-col (On Group Ltd), Darling Ingredients, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Collagen Market Evolving Landscape
Cross-functional convergence between food-grade peptide extraction and medical-device bioprocessing is dissolving traditional segment boundaries, with shared enzymatic platforms now serving both nutraceutical and pharmaceutical purity requirements.
Precision fermentation technology for recombinant collagen production is hybridizing supply chain structures by enabling domestic manufacturing of pharmaceutical-grade proteins without animal agriculture dependencies. Aesthetic clinics and wound-care device manufacturers are piloting these materials for dermal filler and scaffold applications. This shift is compressing reliance on bovine and porcine abattoir networks while creating new upstream partnerships with contract biomanufacturing organisations.
The Medicines and Healthcare products Regulatory Agency's phased implementation of UKCA marking for Class III implantable devices is extending transition timelines and creating compliance uncertainty for collagen scaffold suppliers. British manufacturers are maintaining parallel EU MDR technical documentation while awaiting permanent UK regulatory framework confirmation. Medical-grade collagen producers with validated quality management systems are absorbing these dual-system costs more readily than emerging entrants.
Subscription-based direct-to-consumer distribution for hydrolyzed collagen peptides is displacing traditional retail pharmacy and health food store channels among urban fitness demographics. Vital Proteins and comparable brands are capturing recurring revenue through automated replenishment models that bypass wholesale intermediaries. London and South East metropolitan areas exhibit the highest concentration of these digitally native purchasing patterns.
United Kingdom Collagen Market Segmentation
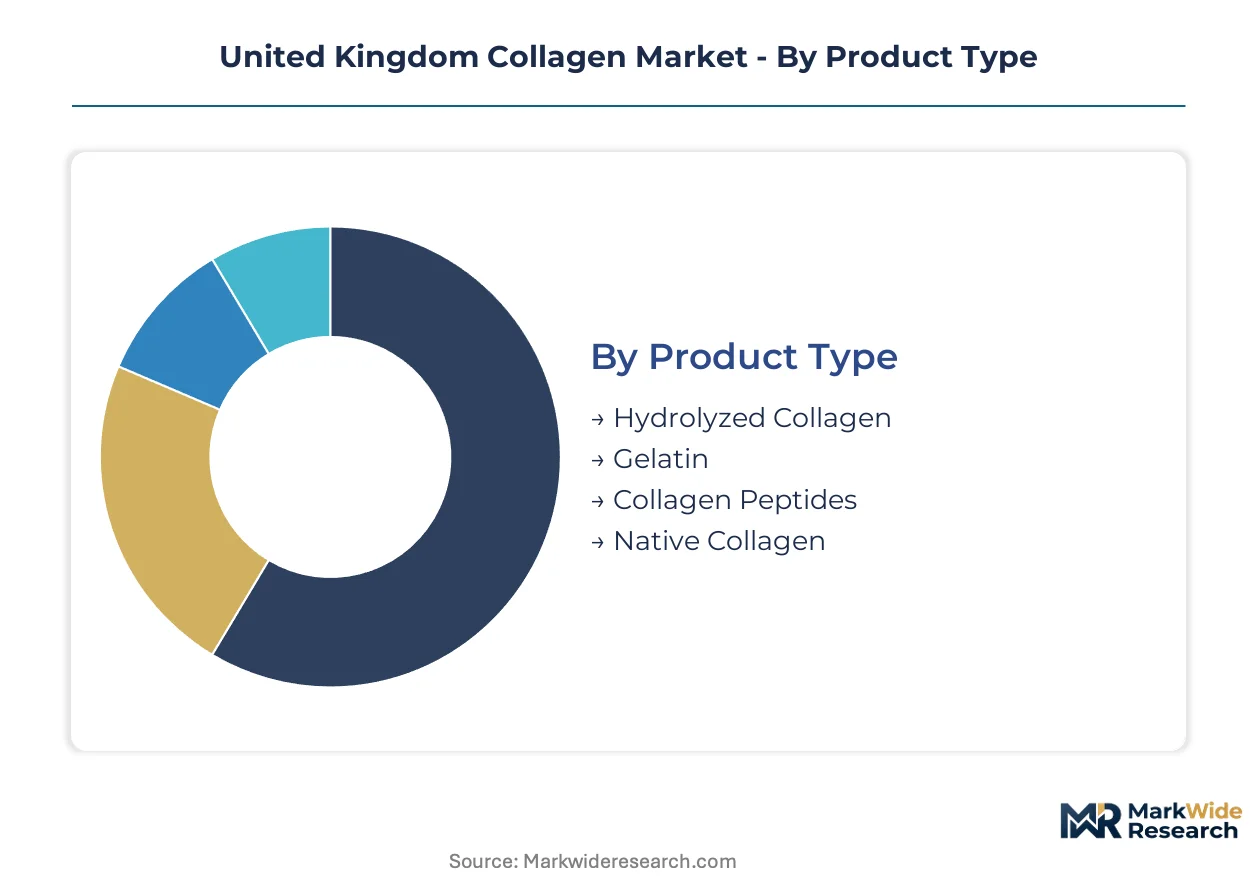
Collagen value chains in the United Kingdom fragment across four distinct dimensions that determine pricing power, regulatory pathway, and channel strategy. Product chemistry dictates whether formulations enter through FSA novel food routes or MHRA medical device classifications. Application context and end-user specification then govern margin capture and volume scalability.
Product Type:
Cost tier separates these four chemistries, with extraction complexity and triple-helix integrity driving the pricing hierarchy from commodity gelatin to premium native structures.
- Hydrolyzed Collagen:Enzymatically cleaved peptides with molecular weights below 10 kDa achieve cold-water solubility prized by sports nutrition formulators. Demand concentrates in England's metropolitan fitness demographics where bioavailability claims command subscription premiums. The Food Standards Agency's novel food framework treats these as established ingredients, accelerating new variant approvals.
- Native Collagen:Intact triple-helix structures preserved through non-denaturing extraction command the highest purity grades for MHRA-regulated implantable scaffolds. Aesthetic clinics in London and the South East absorb limited supply for dermal filler applications where structural integrity determines clinical outcomes.
- Gelatin:Partially hydrolyzed collagen with Bloom strength specifications dominates British food manufacturing gelling applications. Mature pricing and established supply contracts with continental European abattoirs sustain volume flows despite slower growth trajectories.
- Collagen Peptides:Standardized peptide fractions with defined amino acid profiles bridge nutraceutical and cosmetic formulation requirements. Food Standards Agency clearance for oral supplement applications supports broader distribution than medical-grade alternatives.
Hydrolyzed Collagen holds installed capacity. Native Collagen is rotating up the share rankings.
Application:
End-use context determines whether collagen enters through retail, clinical, or industrial procurement channels with radically different margin structures.
- Medical Devices:Class III implantable scaffolds for orthopaedic and wound-care applications require MHRA UKCA marking and validated quality management systems. NHS hospital trusts outside London represent underpenetrated demand as procurement centralization slows adoption.
- Nutrition Supplements:Direct-to-consumer peptide powders and capsules bypass pharmacy intermediaries through subscription models concentrated in urban fitness demographics. The FSA's structured safety assessment provides regulatory certainty that accelerates marine and recombinant variant commercialisation.
- Cosmetics:Topical formulations and ingestible beauty supplements target premium positioning through aesthetic clinic and specialty retail channels. London's cosmetic surgery networks drive native collagen uptake for professional-grade dermal applications.
- Food & Beverages:Gelatin-based gelling and texture modification serves mature British manufacturing demand with price-competitive positioning. Channel consolidation among industrial food processors favors suppliers with continental European bulk supply contracts.
Medical Devices capture the steepest expansion trajectory. Nutrition Supplements is climbing the fastest in absolute volume terms.
End User:
Customer type governs specification stringency, with pharmaceutical and clinical buyers imposing quality standards that commodity food channels do not require.
- Aesthetic Clinics:London and South East cosmetic surgery networks source native collagen with intact triple-helix structures for dermal filler and wound-healing applications. MHRA device classification requirements favor established suppliers with validated sterilization and pyrogen control protocols.
- Sports Nutrition:Fitness-focused consumers in England and Scotland drive peptide-grade hydrolyzed collagen demand through direct-to-consumer subscription channels. Cold-water solubility and rapid absorption claims differentiate formulations in crowded supplement markets.
- Pharmaceutical Companies:Collagen matrices for drug delivery and tissue engineering applications require GMP-certified production and batch-level documentation. MHRA compliance barriers strain quality assurance staffing and extend certification cycles for emerging entrants.
- Food Manufacturers:Bulk gelatin procurement for gelling applications runs through established supply contracts with continental European processors. Veterinary health certificate delays at Channel ports create input volatility for British manufacturers.
Food Manufacturers holds installed capacity. Aesthetic Clinics is gaining share fastest.
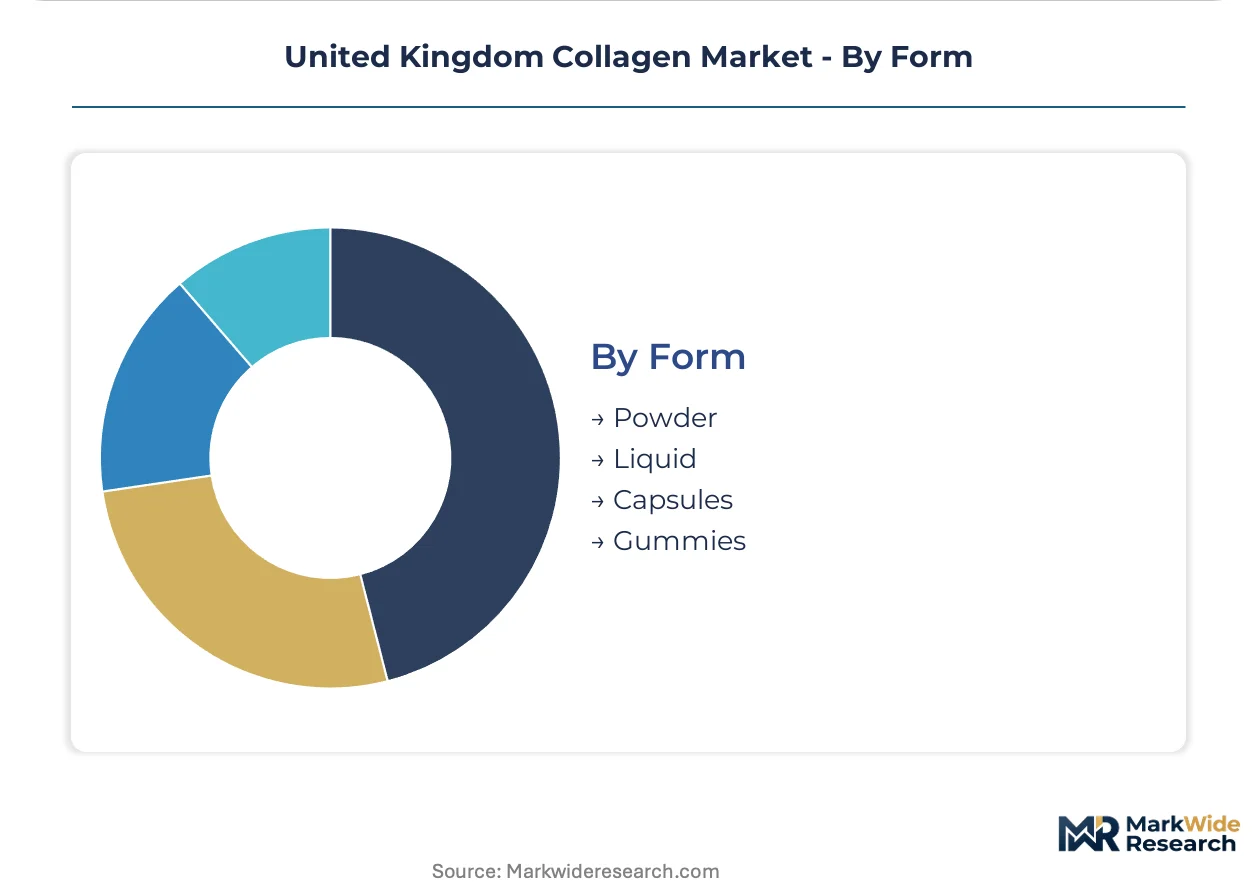
Form:
Delivery format determines manufacturing complexity, stability requirements, and the sophistication of downstream packaging and distribution infrastructure needed.
- Powder:Dried peptide concentrates with low moisture activity support ambient storage and flexible dosing in sports nutrition applications. Automated subscription fulfillment models in London and South East metropolitan areas favor this format's shipping efficiency.
- Liquid:Ready-to-drink collagen shots require aseptic processing and cold chain or preservative systems that elevate production costs. Convenience positioning targets time-constrained urban consumers willing to pay form premiums.
- Capsules:Precise unit dosing and taste masking suit pharmaceutical and premium nutraceutical positioning. Hard-shell and soft-gel encapsulation capacity constraints limit supplier options for scaled production.
- Gummies:Confectionery-format delivery appeals to younger demographics and beauty-positioned ingestible cosmetics. Sugar content and stability challenges complicate clean-label formulation strategies.
Powder holds installed capacity. Liquid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing for native collagen concentrates in London and the South East diverges sharply from commodity gelatin flows through Midlands food manufacturing corridors. This pricing-power asymmetry reflects divergent regulatory pathways and end-user specification stringency across English regions and the Celtic nations.
London and South East
Aesthetic clinic networks and pharmaceutical company headquarters drive demand for medical-grade collagen matrices with intact triple-helix structures. The Medicines and Healthcare products Regulatory Agency's UKCA marking requirements for Class III implantable devices create compliance barriers that favor established suppliers with validated quality management systems. Harley Street cosmetic surgery clusters and Cambridge biotech corridors anchor premium consumption.
Midlands
Industrial food manufacturing concentrates gelatin procurement for gelling and texture modification applications. Veterinary health certificate delays at Channel ports disrupt continental European abattoir sourcing for Birmingham and Leicester processors. The Food Standards Agency's novel food framework provides regulatory certainty for established bovine-derived ingredients.
North England
Sports nutrition formulators in Manchester and Leeds metropolitan areas drive peptide-grade hydrolyzed collagen uptake through direct-to-consumer subscription channels. Cold-water solubility specifications differentiate formulations targeting fitness-focused urban demographics. Regional distribution hubs face margin compression from energy-intensive enzymatic extraction costs.
Scotland
North Atlantic fishery networks supply marine collagen feedstock for cod-skin extraction facilities. Quota fluctuations and seasonal availability create input cost volatility for Aberdeen and Glasgow processors. The Food Standards Agency's structured safety assessment accelerates commercialisation of wild-caught alternatives.
Wales and Northern Ireland
Agricultural processing infrastructure supports bovine connective tissue collection for gelatin and peptide extraction. Cross-border veterinary certification requirements with the Republic of Ireland complicate supply chain logistics for Northern Irish manufacturers. Welsh bioprocessing clusters explore precision fermentation partnerships for recombinant collagen production.
United Kingdom Collagen Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower specification scope. The United Kingdom collagen market structures around three distinct capability layers: bulk gelatin suppliers with continental European manufacturing footprints, medical-grade matrix producers with MHRA-validated quality systems, and direct-to-consumer peptide brands with subscription-based distribution infrastructure. Consolidation pressures concentrate among food-grade processors facing veterinary certification friction, while fragmentation persists in nutraceutical channels where digital-native entrants bypass traditional pharmacy intermediaries. Dominant competitive moves include backward integration into animal agriculture supply networks and strategic partnerships with contract biomanufacturing organisations for recombinant production scale-up.
Among German-headquartered bulk suppliers, GELITA AG occupies a position exemplifying scale-driven gelatin production for British food manufacturing contracts. Collagen Solutions plc, a UK-registered public limited company, anchors the medical-grade tier through orthopaedic and wound-care matrix specialisation. Vital Proteins LLC represents the direct-to-consumer archetype with subscription models that bypass traditional retail channels in London and South East metropolitan areas.
| Leading Market Players |
|---|
| Nitta Gelatin Inc. |
| Weishardt Holding SA |
| Collagen Solutions plc |
| Hunter & Gather Foods Ltd |
| Vital Proteins LLC |
| GELITA AG |
| Tessenderlo Group |
| Proto-col (On Group Ltd) |
| Darling Ingredients |
| Others |
Value Network & Pricing Analysis
Continental European abattoir networks for bovine connective tissue feed margin concentration toward medical-grade native collagen producers, while commodity gelatin processors absorb veterinary certification friction at Channel ports. Price stratification across the United Kingdom collagen market reflects this upstream geography more than downstream demand dispersion.
Pricing Analysis
The customization-premium spread separates configured-to-order medical-grade matrices from standard hydrolyzed peptide powders. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and triple-helix integrity, with MHRA-validated implantable scaffolds commanding the widest spreads. Cost compression in commodity gelatin runs through energy-intensive extraction and continental sourcing delays. Food manufacturers exhibit the highest price sensitivity, while aesthetic clinics absorb premiums for native structural integrity.
Supply Chain Analysis
Extended payment terms from British food manufacturers to continental suppliers strain working capital for Midlands processors facing veterinary health certificate delays. Supply draws from Germany, France, and the Netherlands for bovine raw material, with North Atlantic fisheries feeding Scottish marine extraction. Single-source vulnerability concentrates in Channel port logistics for abattoir-sourced inputs. Distribution runs through direct-to-consumer subscription infrastructure for peptide-grade products, bypassing traditional pharmacy wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived collagen presents a credible substitution threat that incumbent animal-extraction specialists must navigate through capability investment or partnership structures.
For Market Incumbents: Pre-empt recombinant displacement by securing contract biomanufacturing organisation partnerships for precision fermentation scale-up. Backward integration into North Atlantic fishery networks reduces marine input volatility for cod-skin processors. MHRA dual-compliance cost absorption favors established quality management systems over emerging entrants.
For New Entrants and Emerging Players: NHS hospital trusts outside London and the South East present the most penetrable geography for medical-grade collagen matrices. Orthopaedic scaffold applications remain underpenetrated in regional procurement centralization structures. Direct-to-consumer subscription infrastructure offers the lowest barrier go-to-market angle for peptide-grade entrants.
For Investors and Strategic Acquirers: Capital is best deployed toward platform integrators with validated MHRA quality systems and enzymatic hydrolysis capabilities spanning nutraceutical and pharmaceutical purity requirements. Long-term viability hinges on cell-cultured collagen regulatory tailwinds and FSA guidance evolution. The signal to monitor is FSA novel food authorization acceleration for precision-fermentation-derived proteins.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Enables domestic pharmaceutical-grade production without continental abattoir dependencies. |
| MHRA UKCA Marking Investment | Secures permanent regulatory positioning for Class III implantable device classifications. |
| Direct-to-Consumer Channel Buildout | Bypasses pharmacy intermediaries to capture recurring revenue from urban fitness demographics. |
| North Atlantic Fishery Integration | Reduces input cost volatility for cod-skin and wild-caught marine collagen alternatives. |
| Orthopaedic Scaffold Portfolio Expansion | Targets underpenetrated NHS hospital trusts outside London procurement corridors. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with collagen biochemists, GMP fermentation specialists, aesthetic clinic procurement managers, and Food Standards Agency regulatory leads; and secondary validation through MHRA device registration databases, FSA novel food authorization records, and customs/trade flow documentation. Bottom-up volume modeling triangulated against top-down market sizing across product chemistry and application segments.
Forecast inputs considered enzymatic hydrolysis capacity expansion, MHRA post-Brexit regulatory divergence timelines, and precision fermentation commercialization trajectories across the analysis window. Segmentation dimensions included product type, application context, end-user specification, and delivery format. CAGRs derived from installed capacity utilization rates and substitution elasticity parameters for recombinant alternatives.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cell-cultured collagen specialists or accelerated FSA authorization pathways would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Absorbable Tissue Spacer Market
Biomaterials
Bone Distractors Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Bone Substitutes Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Flowable Hemostats Market
Biomaterials
Chitosan Market
Biomaterials
Hydrogel Face Mask Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Europe Collagen Market
Biomaterials
Mushroom Materials Market
Biomaterials
Hemostatic Gels Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Bone and Joints Ingredients Market